
Market Overview:
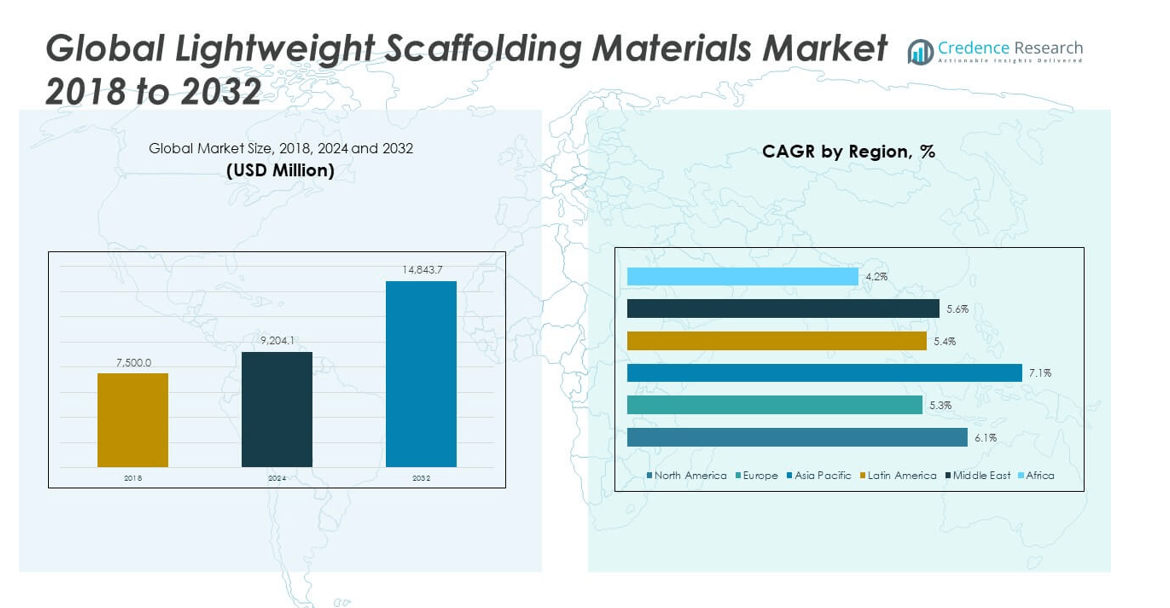
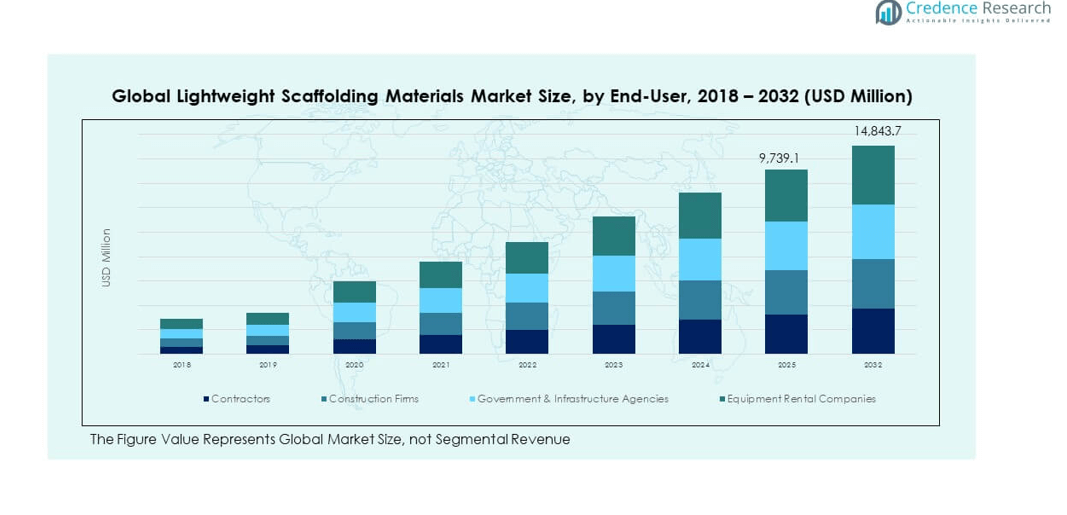
The Global Lightweight Scaffolding Materials Market size was valued at USD 7,500.0 million in 2018 to USD 9,204.1 million in 2024 and is anticipated to reach USD 14,843.7 million by 2032, at a CAGR of 6.21% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Lightweight Scaffolding Materials Market Size 2024 | USD 9,204.1 million |
| Lightweight Scaffolding Materials Market, CAGR | 6.21% |
| Lightweight Scaffolding Materials Market Size 2032 | USD 14,843.7 million |
Market growth is driven by the rising demand for efficient and safe construction solutions, coupled with the increasing emphasis on reducing structural weight without compromising strength. Advancements in material science, including the development of high-strength aluminum alloys and composite materials, are enhancing durability and load-bearing capacity. Expanding urban infrastructure projects, renovation activities, and industrial construction across developing economies are further boosting adoption, while the push for faster installation and dismantling processes strengthens market penetration.
Asia-Pacific leads the market due to rapid urbanization, infrastructure expansion, and large-scale construction activities in China, India, and Southeast Asia. North America and Europe maintain strong shares, driven by stringent safety regulations and the adoption of advanced scaffolding systems in commercial and industrial projects. Emerging markets in the Middle East, Africa, and Latin America are witnessing growth as governments invest in new urban developments, transport infrastructure, and high-rise building projects, creating a favorable environment for lightweight scaffolding material adoption.
Market Insights:
- The Global Lightweight Scaffolding Materials Market was valued at USD 9,204.1 million in 2024 and is projected to reach USD 14,843.7 million by 2032, growing at a CAGR of 6.21% from USD 7,500.0 million in 2018.
- Increasing global construction activities across residential, commercial, and industrial sectors is driving strong demand for lightweight, durable, and safe scaffolding solutions.
- Advancements in material technology, including high-strength aluminum alloys and composites, enhance load-bearing capacity, corrosion resistance, and ease of assembly.
- Price volatility of raw materials such as aluminum impacts manufacturing costs, profit margins, and long-term pricing strategies.
- Shortage of skilled labor for safe assembly and operation poses operational risks and slows project execution, especially in emerging markets.
- Asia-Pacific leads the market due to rapid urbanization and large-scale infrastructure projects in China, India, and Southeast Asia, while North America and Europe maintain significant shares through advanced safety regulations.
- Emerging markets in the Middle East, Africa, and Latin America present growth opportunities driven by urban development, transport infrastructure investments, and industrial expansion.
Market Drivers:
Rising Global Construction Activities Fueling Material Demand:
The Global Lightweight Scaffolding Materials Market benefits significantly from the steady growth of global construction projects across residential, commercial, and industrial sectors. Rapid urbanization in developing economies is driving large-scale infrastructure projects, including high-rise buildings, bridges, and public facilities. Governments are prioritizing investments in transport networks, urban renewal, and affordable housing schemes. Construction firms seek materials that offer strength, durability, and reduced weight for safer and faster assembly. The demand for flexible and modular scaffolding systems is increasing, enabling customization to diverse project needs. Industries are also recognizing the operational efficiency achieved through reduced labor and installation time. Lightweight scaffolding offers a competitive edge in meeting strict project timelines. This adoption trend is reinforced by contractors’ focus on lowering operational costs while enhancing workplace safety.
- For instance, Layher Holding GmbH & Co. KG improved its Allround Scaffolding system by leveraging higher-tensile steel and advanced production techniques, which reduced component weight but maintained high load capacities-the result being up to 10% faster assembly and a 12% increase in transport efficiency.
Advancements in Material Technology Enhancing Performance:
Continuous innovations in material science are creating high-strength, corrosion-resistant scaffolding materials, such as advanced aluminum alloys and fiber-reinforced composites. These materials maintain structural integrity while significantly reducing weight, making them easier to transport and assemble. Enhanced load-bearing capacity allows for safer operation in complex construction environments. The market is witnessing increased adoption in both new construction and renovation projects. Manufacturers are integrating safety features such as anti-slip platforms and quick-lock mechanisms to improve usability. The demand for high-performance scaffolding solutions is particularly strong in regions with stringent construction safety regulations. Improved resistance to environmental degradation extends product life cycles, delivering better return on investment for buyers. This technological progress positions lightweight scaffolding as a preferred choice for modern construction needs.
- For instance, Altrex B.V. recently introduced Fiber-Deck® platforms for its MiTOWER system, making platforms 30% lighter than traditional wooden counterparts, yet retaining comparable strength and durability. This enables safer and quicker assembly, directly supporting operational efficiency and reduced labor fatigue in both new builds and renovation projects.
Stringent Safety Regulations Driving Quality Standards:
The implementation of strict safety regulations worldwide is pushing contractors to invest in high-quality scaffolding systems. Regulatory bodies mandate compliance with structural stability, load-bearing limits, and worker safety guidelines. This has led to rising demand for certified lightweight scaffolding that meets or exceeds international standards. The market is benefiting from increased inspections and safety audits across construction sites. Employers are focusing on minimizing accidents and liability risks by using proven, tested materials. Manufacturers are responding by developing scaffolding with enhanced stability and ease of assembly. The ability to quickly set up and dismantle scaffolding without compromising safety is becoming a key purchasing factor. The growing emphasis on occupational health and safety in construction directly supports market expansion.
Cost Efficiency and Productivity Gains Boosting Adoption:
Lightweight scaffolding reduces transportation and labor costs due to its ease of handling and faster assembly. Construction companies are under constant pressure to deliver projects on time and within budget. Using lighter yet durable scaffolding minimizes downtime during setup and dismantling phases. This efficiency translates into reduced project overhead and improved profitability. In high-rise and complex structures, ease of mobility and repositioning significantly accelerates workflow. The reduced physical strain on workers also supports higher productivity and safety. Industries are increasingly aligning procurement strategies with long-term operational savings. These cost advantages, combined with performance reliability, are driving strong uptake across global construction sectors.
Market Trends:
Growing Adoption of Modular and Customizable Scaffolding Designs:
The Global Lightweight Scaffolding Materials Market is witnessing a shift toward modular scaffolding systems that can be easily customized to specific project requirements. Construction firms are seeking adaptable solutions that can be configured for diverse building shapes and heights. Modular designs allow efficient space utilization and better maneuverability in restricted work zones. Demand is rising for systems that can integrate with advanced construction equipment for enhanced workflow. The flexibility of modular scaffolding supports both short-term projects and long-term infrastructure developments. Rental companies are expanding their offerings to include modular solutions, catering to varied client needs. This trend reflects a broader industry shift toward versatility, efficiency, and adaptability in scaffolding applications.
- For instance, Coronet Scaffold Group has delivered over 3,500 scaffolding projects worldwide using modular systems designed for high-strength and stability, supported by strict welding and manufacturing processes with over 24 international certifications. This ensures rapid system configuration for diverse project requirements and compliance with safety protocols across construction sectors.
Integration of Digital Tools for Safety and Efficiency:
Digital technology is transforming the scaffolding industry through innovations like 3D modelling, augmented reality (AR), and digital load monitoring. The Global Lightweight Scaffolding Materials Market is benefiting from these tools, which enhance project planning and safety management. AR applications allow virtual assembly previews, helping crews understand configurations before on-site installation. Digital load sensors monitor weight distribution in real-time, reducing the risk of overloading. Remote monitoring systems improve compliance with safety regulations by providing instant alerts. The adoption of digital platforms also streamlines inventory management and scaffolding lifecycle tracking. This integration aligns with the broader construction industry’s shift toward digital transformation.
- For instance, PERI SE’s PERIcap and Genio robotics suite incorporates digital load monitoring and 3D modeling in scaffolding management, resulting in measurable reductions in labor hours and improvements in safety compliance during deployment at large infrastructure sites. These tools integrate with existing platforms, supporting instant alerts and real-time project analytics.
Sustainability and Eco-Friendly Material Development:
There is a growing demand for scaffolding materials with lower environmental impact, driving interest in recyclable and sustainable solutions. Manufacturers in the Global Lightweight Scaffolding Materials Market are investing in eco-friendly production processes and materials such as recycled aluminum. The emphasis on reducing carbon footprints aligns with corporate sustainability commitments and government environmental targets. Eco-friendly scaffolding solutions appeal to green-certified projects and companies pursuing LEED accreditation. These materials maintain high structural performance while supporting environmental stewardship. Increasing regulations on waste reduction and sustainable sourcing are accelerating adoption. This trend strengthens the long-term market potential for sustainable scaffolding innovations.
Rising Popularity of Rental and Leasing Models:
The market is seeing a surge in scaffolding rental services, particularly for lightweight systems, driven by cost-effectiveness and flexibility. Contractors prefer renting to reduce upfront capital investment and maintenance costs. The rental model allows access to the latest scaffolding technologies without long-term ownership commitments. In the Global Lightweight Scaffolding Materials Market, rental providers are expanding fleets to include high-performance and modular systems. Short-term projects, seasonal demand fluctuations, and event setups further boost rental adoption. The rental sector also benefits from professional assembly and dismantling services, enhancing safety and efficiency. This trend supports continuous market engagement across diverse construction and industrial projects.
Market Challenges Analysis:
Price Volatility of Raw Materials Impacting Profit Margins:
The Global Lightweight Scaffolding Materials Market faces challenges from fluctuations in raw material prices, particularly aluminum and composite inputs. These materials are subject to global supply chain disruptions, trade policies, and energy cost changes. Price instability directly affects manufacturing costs and profit margins for producers. Sudden increases in raw material prices can lead to higher product costs, reducing competitiveness. Smaller manufacturers often struggle to absorb cost hikes without passing them on to customers. Volatility also complicates long-term contract pricing, creating uncertainty in procurement planning. Companies are seeking alternative sourcing strategies to manage this risk. Effective supply chain management and cost optimization remain critical to maintaining profitability.
Shortage of Skilled Labor for Safe Assembly and Operation:
A lack of adequately trained workers in scaffolding assembly and safety management poses operational risks. The Global Lightweight Scaffolding Materials Market requires skilled labor to ensure correct installation and secure usage. Incorrect assembly can compromise structural stability, increasing the risk of accidents. Labor shortages in many regions slow down project execution and reduce overall productivity. Training programs and certifications are often limited, especially in emerging markets. This gap in workforce competence forces companies to invest in extensive on-site training. Manufacturers are responding by designing systems that are simpler to assemble without specialized skills. However, addressing the skilled labor deficit remains a long-term industry challenge.
Market Opportunities:
Expansion in Emerging Economies with Large Infrastructure Pipelines:
Rapid urbanization and industrialization in emerging markets are creating strong demand for lightweight scaffolding solutions. The Global Lightweight Scaffolding Materials Market can capitalize on infrastructure investments in Asia-Pacific, the Middle East, and Africa. Large-scale construction of commercial complexes, transport networks, and residential developments drives significant material needs. Governments are prioritizing urban expansion, requiring safe and efficient scaffolding systems. The potential for high-volume contracts in these regions offers attractive growth prospects. Partnerships with local distributors and construction firms can accelerate market penetration. This expansion aligns with the global trend of shifting economic activity toward developing economies.
Technological Innovation Driving Product Differentiation:
Advancements in material engineering, safety features, and digital integration create opportunities for differentiation in the market. The Global Lightweight Scaffolding Materials Market benefits from innovations like quick-lock systems, enhanced corrosion resistance, and smart monitoring tools. These features improve user safety, extend product lifespan, and streamline operations. Manufacturers that invest in R&D can position themselves as leaders in performance-driven scaffolding solutions. The demand for specialized systems tailored to niche applications, such as offshore platforms or heritage building restorations, is also growing. Leveraging technology to create premium offerings strengthens competitiveness and profitability in the global market.
Market Segmentation Analysis:
By Product
Frame scaffolding holds a dominant share due to its simplicity, structural stability, and suitability for a wide range of building projects. Tube & clamp scaffolding remains popular for projects with irregular structures requiring flexibility in configuration. Mobile or rolling scaffolding sees rising adoption for indoor works and frequent relocation needs. Suspended or hanging scaffolding is preferred for high-rise façade work and bridge maintenance. Cantilever and specialty lightweight frames address niche requirements in industrial, architectural, and confined-space applications.
- For example, Euro Towers Ltd. produces 3T Ladder Frame Towers and AGR (Advanced Guardrail) systems compliant with TUV ISO 9001:2015 and BS.EN.1004 European standards, offering platform heights from 0.25m to 2m and ensuring safe access for multiple workers. ZARGES GmbH’s mobile scaffold towers, made of lightweight high-grade aluminum profiles, enable setup by one to two persons and provide safe workspaces for several users at heights up to multiple meters.
By Application
Commercial construction generates the highest demand, driven by infrastructure expansion, urban high-rises, and commercial complexes. Residential building maintenance supports consistent market activity through renovation and repair projects. Industrial access applications require robust scaffolding for chemical plants, energy utilities, and manufacturing facilities. Aerospace and shipyard maintenance rely on lightweight yet strong systems for large and intricate structures. Event structures and temporary installations form a fast-moving segment demanding quick setup and mobility.
- For instance, Instant UpRight supplies mobile tower systems compliant with EN1004, ANSI, and OSHA standards, offering world-class aluminum towers used in over 40 countries and accompanied by a 10-year structural warranty on key components. SafeSmart Access’s MiniMobile system, constructed from T6 aircraft-grade aluminum, fits through standard 27.5" doorways and is certified to ANSI/ASSE A10.8-2011, providing safe and fast interior access for renovation and maintenance projects.
By End-use Industry
Construction remains the largest contributor, supported by global urbanization and infrastructure investments. Oil & gas and energy & utilities demand high-strength, safety-compliant scaffolding for operational sites. Telecommunication and infrastructure sectors deploy lightweight scaffolding for tower, bridge, and transit system maintenance. Maritime and aerospace industries emphasize corrosion resistance, durability, and customized designs for complex projects.
By Load Capacity
Light-duty scaffolding serves maintenance, painting, and light construction needs. Medium-duty systems are favored in general construction and industrial works. Heavy-duty lightweight systems deliver high load capacity for large infrastructure, energy, and industrial projects, c ombining structural integrity with mobility advantages.
Segmentation:
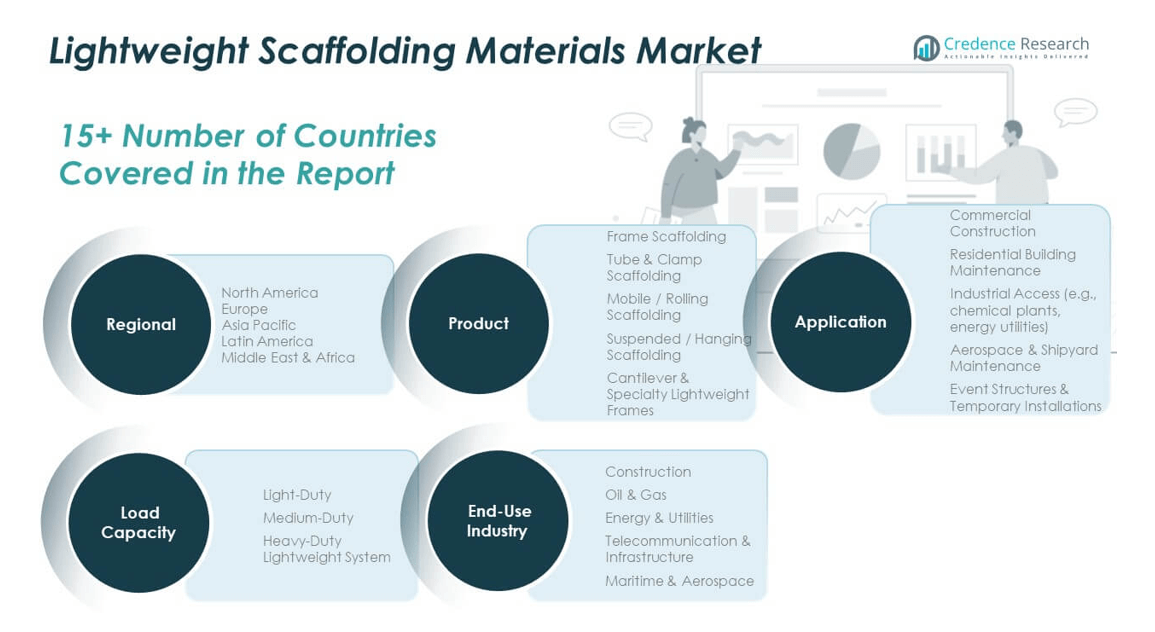
By Product
- Frame Scaffolding
- Tube & Clamp Scaffolding
- Mobile / Rolling Scaffolding
- Suspended / Hanging Scaffolding
- Cantilever & Specialty Lightweight Frames
By Application
- Commercial Construction
- Residential Building Maintenance
- Industrial Access (e.g., chemical plants, energy utilities)
- Aerospace & Shipyard Maintenance
- Event Structures & Temporary Installations
By End-use Industry
- Construction
- Oil & Gas
- Energy & Utilities
- Telecommunication & Infrastructure
- Maritime & Aerospace
By Load Capacity
- Light-Duty
- Medium-Duty
- Heavy-Duty Lightweight System
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Lightweight Scaffolding Materials Market size was valued at USD 2,008.5 million in 2018 to USD 2,424.3 million in 2024 and is anticipated to reach USD 3,884.9 million by 2032, at a CAGR of 6.1% during the forecast period. It holds approximately 26.3% of the global market share. The Global Lightweight Scaffolding Materials Market in this region benefits from robust construction activity in both residential and commercial sectors, driven by urban redevelopment and infrastructure upgrades. Strict safety regulations promote the adoption of certified, high-performance scaffolding systems. The U.S. leads the region with substantial investments in high-rise buildings, industrial facilities, and transportation projects. Canada supports steady growth through urban housing and energy sector maintenance. Demand for advanced modular scaffolding systems is rising to meet tight project timelines. High labor costs encourage the use of lightweight, quick-assembly materials to improve efficiency. The market is supported by the presence of leading global manufacturers and a strong rental services network.
Europe
The Europe Lightweight Scaffolding Materials Market size was valued at USD 1,672.5 million in 2018 to USD 1,958.4 million in 2024 and is anticipated to reach USD 2,950.8 million by 2032, at a CAGR of 5.3% during the forecast period. It accounts for roughly 21.3% of the global share. The Global Lightweight Scaffolding Materials Market in Europe is shaped by stringent safety standards, environmental regulations, and heritage building restoration projects. Germany, the UK, and France lead demand with strong infrastructure investment and modernization initiatives. The region sees growing use of corrosion-resistant, sustainable scaffolding solutions in maritime and industrial projects. Refurbishment of aging transport networks fuels consistent adoption. Demand from event structures and temporary installations remains high in markets with strong tourism and cultural sectors. The rental market is mature, offering advanced systems for varied project needs. Manufacturers in Europe focus on integrating eco-friendly materials and precision engineering to enhance product appeal.
Asia Pacific
The Asia Pacific Lightweight Scaffolding Materials Market size was valued at USD 2,685.0 million in 2018 to USD 3,394.9 million in 2024 and is anticipated to reach USD 5,865.2 million by 2032, at a CAGR of 7.1% during the forecast period. It commands about 37% of the global market share. The Global Lightweight Scaffolding Materials Market in Asia Pacific is propelled by rapid urbanization, massive infrastructure investments, and industrial expansion in China, India, and Southeast Asia. Mega projects, including high-speed rail, metro systems, and commercial complexes, create strong demand for modular and mobile scaffolding systems. The construction boom in emerging economies fuels high-volume procurement of lightweight solutions to meet fast-track deadlines. Governments are emphasizing worker safety, increasing the use of standardized scaffolding systems. Industrial maintenance in sectors like shipbuilding, oil & gas, and manufacturing further supports market expansion. The rental market is expanding, offering cost-effective solutions for small and medium contractors. Local manufacturing capacity and competitive pricing strengthen regional supply chains.
Latin America
The Latin America Lightweight Scaffolding Materials Market size was valued at USD 562.5 million in 2018 to USD 684.7 million in 2024 and is anticipated to reach USD 1,037.1 million by 2032, at a CAGR of 5.4% during the forecast period. It represents about 7.4% of the global market share. The Global Lightweight Scaffolding Materials Market in Latin America is supported by ongoing urban development, public infrastructure investments, and housing projects in Brazil, Mexico, and Argentina. Governments are prioritizing affordable housing schemes and urban renewal programs, driving consistent demand. Large-scale industrial facilities, including oil refineries and energy plants, contribute to market growth. Lightweight scaffolding is preferred for maintenance and expansion work in constrained spaces. The event and entertainment industry also contributes seasonal demand for temporary structures. Price-sensitive markets favor durable, reusable systems with lower lifecycle costs. The region is gradually adopting higher safety standards, improving product quality requirements.
Middle East
The Middle East Lightweight Scaffolding Materials Market size was valued at USD 382.5 million in 2018 to USD 447.3 million in 2024 and is anticipated to reach USD 687.2 million by 2032, at a CAGR of 5.6% during the forecast period. It accounts for nearly 4.9% of the global market share. The Global Lightweight Scaffolding Materials Market in the Middle East is driven by large-scale infrastructure projects, including commercial hubs, stadiums, and transport networks, particularly in GCC countries. Ongoing construction for mega events and tourism infrastructure stimulates strong demand. Oil & gas sector maintenance projects require heavy-duty lightweight systems for operational efficiency. High temperatures and harsh environments increase demand for corrosion-resistant materials. UAE and Saudi Arabia dominate the regional market with high investment in mixed-use developments. The rental sector is expanding to support project-based demand. Strategic partnerships between local suppliers and international manufacturers improve availability of advanced systems.
Africa
The Africa Lightweight Scaffolding Materials Market size was valued at USD 189.0 million in 2018 to USD 294.6 million in 2024 and is anticipated to reach USD 418.5 million by 2032, at a CAGR of 4.2% during the forecast period. It holds around 3.1% of the global market share. The Global Lightweight Scaffolding Materials Market in Africa is shaped by gradual urbanization, infrastructure development, and industrial expansion in South Africa, Egypt, and Nigeria. Governments are investing in road networks, public housing, and energy projects. Lightweight scaffolding is gaining adoption in urban construction for its ease of handling and reduced labor requirements. Maintenance projects in mining and industrial facilities contribute steady demand. Limited access to advanced systems in some regions slows adoption, but imports and rental services are bridging the gap. The market shows potential in coastal and maritime projects requiring corrosion-resistant solutions. Local manufacturing remains limited, with reliance on imports from Asia and Europe.
Key Player Analysis:
- Layher Holding GmbH & Co. KG
- PERI SE
- Altrex B.V.
- Instant UpRight
- ZARGES GmbH
- Alufase
- Youngman (WernerCo)
- Coronet Scaffold Group
- SafeSmart Access
- Euro Towers Ltd.
- Sunset Ladder & Scaffold Co.
- Kuwatec Inc.
- Jinmao Group
Competitive Analysis:
The Global Lightweight Scaffolding Materials Market is moderately fragmented, with a mix of global leaders and regional manufacturers competing on product quality, safety standards, and cost efficiency. Leading players such as Layher Holding GmbH & Co. KG, PERI SE, and Altrex B.V. dominate through advanced engineering, extensive product portfolios, and strong distribution networks. Smaller firms focus on price competitiveness and niche applications to secure market share. Innovation in lightweight alloys, modular designs, and corrosion-resistant materials strengthens competitive positioning. Rental services form a critical part of the value chain, with established providers offering comprehensive solutions from supply to assembly. Strategic mergers, partnerships, and capacity expansions are common to enhance market reach. Companies prioritize meeting stringent regulatory standards to gain client trust, particularly in developed markets. The competitive environment is shaped by technological advancements, project-based demand cycles, and the ability to deliver customized scaffolding systems efficiently.
Recent Developments:
- In April 2025, Layher Holding GmbH & Co. KG commenced operations at its new high-tech production facility, “Plant 3,” in Güglingen-Eibensbach, Germany. This state-of-the-art, energy-efficient plant is dedicated to manufacturing Allround Scaffolding and employs cutting-edge automation, energy recovery, and digitalization throughout its processes. The investment aims to boost production capacity, quality, and sustainability, addressing growing demand in the lightweight scaffolding segment.
- In May 2024, PERI SE announced the acquisition of UK-based Mabey Hire Ltd., a leader in ground shoring, propping, temporary bridges, and smart construction sensors. This strategic deal strengthens PERI’s position in the infrastructure and refurbishment market in the UK and internationally, allowing for expanded cross-selling and enhanced service for customers. Additionally, PERI SE acquired promaintain GmbH & Co. KG, effective July 2023, further enhancing its project management and industrial scaffolding capabilities.
- In April 2024, Altrex B.V. extended its longstanding partnership agreement with Pop Up Products Limited for another 10 years, taking their collaboration for mobile access towers, ladders, and stepladders in the UK and Ireland to 2034 and beyond. The partnership, which has resulted in over 1.1 million tower components delivered, focuses on developing innovative, sustainable, and ergonomic access solutions.
- On March 4, 2025, Instant UpRight announced the upcoming launch of its new Roof Edge Protection System. This advanced safety solution, designed for quick installation without roof penetration, offers enhanced durability and compliance with rigorous international safety standards. The product targets both temporary and permanent applications in construction, emphasizing versatility across different roof types.
Market Concentration & Characteristics:
The Global Lightweight Scaffolding Materials Market demonstrates moderate concentration, with top-tier players holding significant shares due to brand reputation, compliance with international safety standards, and global distribution capabilities. It is characterized by a strong demand for modular, portable, and corrosion-resistant systems that meet diverse industry needs. The market exhibits steady growth in both new construction and maintenance segments, supported by the expansion of rental services. Technological innovation, customization, and integration of digital tools are emerging as key differentiators. Regional players maintain competitiveness by serving local markets with cost-effective solutions and flexible supply options.
Report Coverage:
The research report offers an in-depth analysis based on product type, application, end-use industry, and load capacity. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising infrastructure investments will expand demand in urban and industrial construction projects worldwide.
- Adoption of modular and quick-assembly systems will increase to meet tight project deadlines.
- Material innovations in aluminum alloys and composites will enhance durability and load performance.
- Sustainability initiatives will push for recyclable and eco-friendly scaffolding solutions.
- Digital integration with load monitoring and safety tracking tools will gain market traction.
- The rental and leasing segment will grow as contractors seek cost-efficient procurement models.
- Asia-Pacific will strengthen its dominance with large-scale public and private sector projects.
- Stricter safety regulations will boost certified product adoption across developed markets.
- Specialized scaffolding for aerospace, maritime, and event structures will create niche growth avenues.
- Strategic collaborations between global leaders and regional suppliers will expand market penetration.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Global Construction Activities
Rapid urbanization and infrastructure investments in both developed and emerging economies are driving demand for lightweight scaffolding materials, as construction firms seek efficient, safe, and cost-effective solutions for high-rise buildings, bridges, and public facilities.
Advancements in Material Technology
Innovations in high-strength aluminum alloys and composite materials are enhancing the durability, corrosion resistance, and load-bearing capacity of scaffolding, making them more attractive for modern construction and renovation projects.
Stringent Safety Regulations
Increasingly strict safety standards and regulatory requirements worldwide are compelling contractors to adopt certified, high-quality lightweight scaffolding systems that ensure worker safety and compliance, boosting market growth.
Cost Efficiency and Productivity Gains
Lightweight scaffolding reduces transportation and labor costs due to easier handling and faster assembly, enabling construction companies to meet tight project deadlines and improve profitability, which accelerates market adoption.
Growth of Rental and Leasing Models
The rising popularity of scaffolding rental and leasing services allows contractors to access advanced lightweight systems without significant upfront investment, supporting flexible project execution and driving continuous market engagement.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Lightweight Scaffolding Materials Market, and what is its projected size in 2032?
Which Global Lightweight Scaffolding Materials Market market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Lightweight Scaffolding Materials Market?
Who are the leading companies in the Global Lightweight Scaffolding Materials Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Frame Scaffolding
- 1.2.2 Tube & Clamp Scaffolding
- 1.2.3 Mobile / Rolling Scaffolding
- 1.2.4 Suspended / Hanging Scaffolding
- 1.2.5 Cantilever & Specialty Lightweight Frames
- 1.3 By Application
- 1.3.1 Commercial Construction
- 1.3.2 Residential Building Maintenance
- 1.3.3 Industrial Access
- 1.3.4 Aerospace & Shipyard Maintenance
- 1.3.5 Event Structures & Temporary Installations
- 1.4 By Load Capacity
- 1.4.1 Light-Duty
- 1.4.2 Medium-Duty
- 1.4.3 Heavy-Duty Lightweight System
- 1.5 By End-use Industry
- 1.5.1 Construction
- 1.5.2 Oil & Gas
- 1.5.3 Energy & Utilities
- 1.5.4 Telecommunication & Infrastructure
- 1.5.5 Maritime & Aerospace
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 7,500.0 million → 2032: USD 14,843.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Lightweight Scaffolding Materials Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Lightweight Scaffolding Materials Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Lightweight Scaffolding Materials Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Lightweight Scaffolding Materials Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Lightweight Scaffolding Materials Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Lightweight Scaffolding Materials Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Lightweight Scaffolding Materials Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Lightweight Scaffolding Materials Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 7,500.0 million → 2032: USD 14,843.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Lightweight Scaffolding Materials Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Frame Scaffolding
- 12.3.7.2 Tube & Clamp Scaffolding
- 12.3.7.3 Mobile / Rolling Scaffolding
- 12.3.7.4 Suspended / Hanging Scaffolding
- 12.3.7.5 Cantilever & Specialty Lightweight Frames
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Commercial Construction
- 12.4.7.2 Residential Building Maintenance
- 12.4.7.3 Industrial Access
- 12.4.7.4 Aerospace & Shipyard Maintenance
- 12.4.7.5 Event Structures & Temporary Installations
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Load Capacity - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Light-Duty
- 12.5.7.2 Medium-Duty
- 12.5.7.3 Heavy-Duty Lightweight System
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-use Industry - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Volume Forecast, 2018-2032
- 12.6.5 Base-Year Market Share, 2018
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Construction
- 12.6.7.2 Oil & Gas
- 12.6.7.3 Energy & Utilities
- 12.6.7.4 Telecommunication & Infrastructure
- 12.6.7.5 Maritime & Aerospace
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Lightweight Scaffolding Materials End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Lightweight Scaffolding Materials Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Lightweight Scaffolding Materials Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Lightweight Scaffolding Materials Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Layher Holding GmbH & Co. KG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 PERI SE
- 18.4 Altrex B.V.
- 18.5 Instant UpRight
- 18.6 ZARGES GmbH
- 18.7 Coronet Scaffold Group
- 18.8 SafeSmart Access
- 18.9 Euro Towers Ltd.
- 18.10 Youngman (WernerCo)
- 18.11 Alufase
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

