
Market Overview
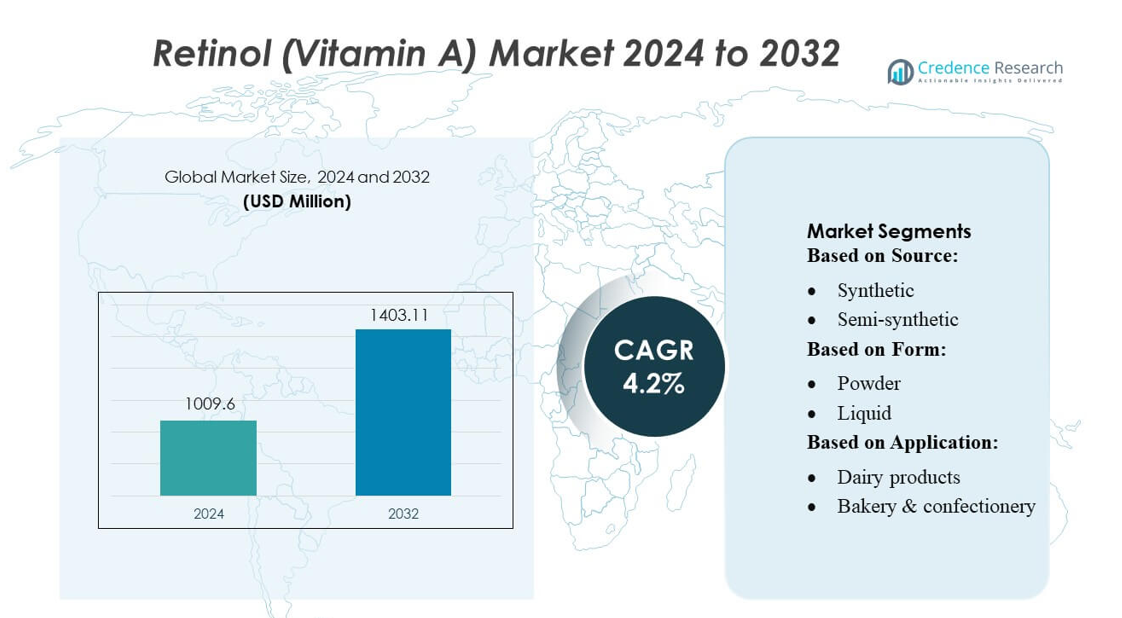
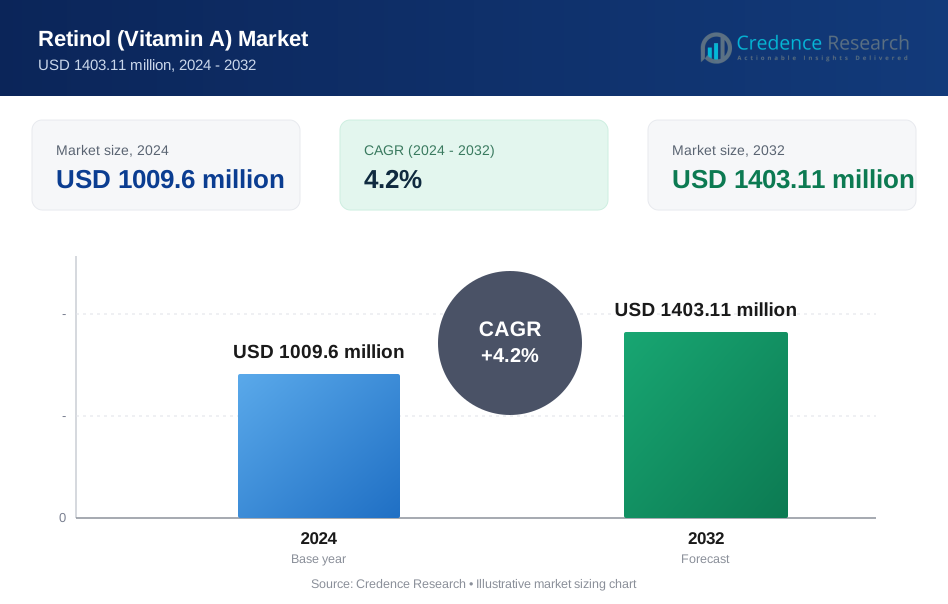
Retinol (Vitamin A) Market size was valued USD 1009.6 million in 2024 and is anticipated to reach USD 1403.11 million by 2032, at a CAGR of 4.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Retinol (Vitamin A) Market Size 2024 | USD 1009.6 million |
| Retinol (Vitamin A) Market, CAGR | 4.2% |
| Retinol (Vitamin A) Market Size 2032 | USD 1403.11 million |
The Retinol (Vitamin A) market is led by prominent companies including Botanic Healthcare, Fengchen Group Co., Ltd, CSPC Pharmaceutical Group Limited, Global Calcium PVT LTD, Northeast Pharmaceutical Group Co., Ltd (NEPG), Sinofi Ingredients, Foodchem International Corporation, DSM Jiangshan Pharmaceutical (Jiangsu) Co., Ltd, Fooding, and Spectrum Chemical. These players focus on technological innovations such as microencapsulation, beadlets, and stabilized powders to enhance bioavailability, stability, and shelf life, while expanding product portfolios across fortified foods, functional beverages, and infant nutrition. North America emerges as the leading region, accounting for 28% of the global market, driven by high consumer awareness, regulatory support for vitamin A fortification, and strong adoption of functional and fortified products. Strategic partnerships, R&D investments, and growing demand for clean-label and plant-based retinol are further strengthening competitive positioning and market growth in this region.
Market Insights
- The Retinol (Vitamin A) market size was valued at USD 1009.6 million in 2024 and is projected to reach USD 1403.11 million by 2032, growing at a CAGR of 4.2% during the forecast period.
- North America leads the market with a 28% share, driven by high consumer awareness, regulatory support for vitamin A fortification, and strong adoption of fortified foods, functional beverages, and infant nutrition products.
- Synthetic and plant-based sources dominate the market, while powder and beadlet forms are the most widely used due to stability, bioavailability, and versatility in fortified and functional food applications.
- Key drivers include rising health-conscious consumers, government fortification initiatives, and demand for immunity-boosting and clean-label products, while challenges include stability issues and stringent regulatory compliance across regions.
- The market is highly competitive, with leading players focusing on technological innovations, strategic partnerships, R&D investments, and expansion into emerging markets to strengthen presence and meet growing demand.
Market Segmentation Analysis:
By Source:
The Retinol market is predominantly driven by synthetic sources, accounting for approximately 55% of the global market share. Synthetic retinol is favored due to its consistent potency, cost-effectiveness, and scalability compared to natural sources. Among natural sources, plant-based retinol is increasingly adopted in response to rising consumer preference for clean-label and vegan-friendly products. Key growth drivers in this segment include regulatory support for fortification, growing awareness of vitamin A deficiency, and the food and supplement industry’s demand for stable, high-purity retinol ingredients. Animal-based and microbial sources remain niche, often used in specialty applications.
- For instance, synthetic‑retinol segment represented around 82.8% of total retinol revenues. Research and Markets. Among natural sources, plant‑based retinol is increasingly adopted in response to rising consumer preference for clean‑label and vegan‑friendly products.
By Form:
Powder forms dominate the retinol market, holding around 60% share due to their stability, ease of handling, and incorporation across multiple applications, including fortified foods and dietary supplements. Liquid and beadlet forms are also significant, valued for controlled release, bioavailability, and versatility in beverage and functional food products. Encapsulated retinol is gaining traction in premium applications, protecting against degradation and enhancing shelf life. Market growth is driven by manufacturers’ focus on stability enhancement, innovations in microencapsulation technology, and increasing demand for forms compatible with heat-processed and long-shelf-life products.
- For instance, vitamin A palmitate offering, they specify potency levels like 500,000 IU/g, 1,000,000 IU/g, and up to 1.7 Million IU/g (for oil form) as per their product data.
By Application:
Functional foods lead the retinol application segment, capturing roughly 45% of the market share, driven by rising health-conscious consumer behavior and fortified product innovations. Dairy products, bakery, and confectionery follow, benefiting from fortification mandates and convenience-focused consumption trends. Infant formula is a high-value sub-segment, experiencing robust growth due to stringent nutritional standards and growing awareness of vitamin A’s role in child development. Key drivers include increasing fortification programs, rising disposable incomes, and manufacturers leveraging retinol for immunity-boosting and eye-health claims in everyday food products.
Key Growth Drivers
Rising Health Awareness and Nutritional Deficiency Concerns
Increasing global awareness of vitamin A deficiency, particularly in developing regions, is driving demand for retinol-fortified foods and supplements. Consumers are actively seeking products supporting eye health, immunity, and overall wellness. Government initiatives promoting mandatory fortification in staple foods and beverages further accelerate adoption. The combination of rising disposable incomes and growing health-conscious populations in Asia-Pacific, Latin America, and parts of Europe creates a favorable environment for market expansion, positioning retinol as a vital nutrient across functional foods, dairy, and infant nutrition segments.
- For instance, CSPC maintains multiple first‑class R&D centers (in China and the U.S.), and possesses a broad regulatory/quality infrastructure: as of recent disclosures, they hold 16 CEP certificates, 33 DMF registrations, and have passed numerous on‑site inspections including by the U.S. FDA.
Growth of Functional and Fortified Food Applications
The surge in functional foods, fortified beverages, and infant nutrition products is a major driver of the retinol market. Manufacturers increasingly incorporate retinol into bakery, dairy, cereals, and ready-to-drink formulations to enhance nutritional value. Technological advancements in encapsulation and stabilization ensure product efficacy even during heat processing and extended storage. As consumers seek convenience without compromising health benefits, fortified and functional products gain traction, expanding the retinol market and prompting innovation in product forms such as powders, beadlets, and encapsulated formulations.
- For instance, Global Calcium operates 14 manufacturing plants, spans over 40+ acres, and is certified under multiple global standards (cGMP, EU‑GMP, COFEPRIS, WHO‑cGMP, HACCP, ISO 9001:2015, ISO 14001:2015, FSSC, kosher & halal) - giving them regulatory and quality credentials for supplying raw materials or premixes for global food, nutraceutical, or fortification uses.
Technological Advancements in Retinol Formulation and Delivery
Innovations in microencapsulation, beadlet, and encapsulated liquid technologies have significantly improved the stability, bioavailability, and shelf life of retinol in food and supplement products. Such advancements allow manufacturers to integrate vitamin A into diverse applications without compromising efficacy, taste, or appearance. Enhanced delivery systems also support controlled release, targeted absorption, and compatibility with heat-processed or long-shelf-life products. These technological developments drive broader adoption, enabling companies to cater to both mass-market and premium segments while addressing regulatory and quality compliance globally.
Key Trends & Opportunities
Plant-Based and Clean-Label Retinol Demand
Consumer preference for plant-based, vegan-friendly, and clean-label ingredients is driving opportunities for natural retinol sources. Plant-derived vitamin A is gaining traction in functional foods, beverages, and dietary supplements as health-conscious and environmentally aware populations prioritize sustainable nutrition. Manufacturers are responding with innovations in extraction, fortification, and stability solutions that align with clean-label trends, creating premium positioning opportunities. This shift allows companies to diversify offerings while meeting regulatory and consumer-driven demand for transparency, ethical sourcing, and traceable ingredient supply chains.
- For instance, Sinofi reportedly handles more than 10,000 metric tons of food additives and industrial products per year in its supply network.
Expansion in Emerging Markets
Emerging regions such as Asia-Pacific, Latin America, and Africa present significant growth opportunities due to rising urbanization, increasing disposable incomes, and growing awareness of vitamin A benefits. Governments in these regions are increasingly enforcing fortification programs for staple foods like flour, cereals, and dairy. Additionally, the expanding retail network, e-commerce penetration, and rising demand for convenience and fortified products support market growth. Companies investing in localized formulations, cost-effective production, and distribution strategies can capture substantial market share in these high-potential geographies.
- For instance, Foodchem provides specification data: for its “500/1000 Feed Grade” vitamin A powder the content is specified as ≥ 500,000 IU/g or ≥ 1,000,000 IU/g depending on grade.
Innovation in Infant Nutrition and Specialty Applications
Infant formula and specialty nutrition products present a high-value growth avenue for retinol due to strict nutritional guidelines and growing parental awareness. Innovations in microencapsulation and beadlet technology enable safe, stable incorporation into infant formulas and ready-to-eat products. Opportunities also exist in sports nutrition, clinical supplements, and premium functional foods where retinol is marketed for immunity, skin health, and eye health benefits. Continuous product development and targeted marketing in these niche but high-margin applications can strengthen brand positioning and drive incremental revenue growth globally.
Key Challenges
Stability and Shelf-Life Concerns
Retinol is highly sensitive to heat, light, oxygen, and moisture, making formulation and storage challenging. Degradation during processing or extended storage reduces efficacy, limiting its incorporation in certain applications. Manufacturers must invest in advanced encapsulation, beadlet, or microemulsion technologies, which can increase production costs. Maintaining bioavailability while ensuring product stability in diverse food matrices remains a critical challenge, especially in heat-processed or long-shelf-life products. Failure to address stability issues may impact consumer trust and regulatory compliance, restricting market expansion.
Regulatory and Compliance Barriers
Stringent regulations on fortification levels, labeling, and safety testing vary across countries, posing challenges for global distribution of retinol products. Companies must navigate complex regulatory frameworks to ensure compliance with maximum permissible levels in foods, supplements, and infant nutrition. Frequent changes in legislation, combined with differing regional standards, increase the cost and time for product approvals. Non-compliance can result in product recalls, reputational damage, or legal penalties, creating a significant barrier for both established and new entrants in the competitive retinol market.
Regional Analysis
North America:
North America leads the retinol market with an estimated 28% share, driven by high consumer awareness of health and wellness, widespread fortification programs, and strong demand for functional foods and dietary supplements. The U.S. dominates due to established regulations supporting vitamin A enrichment in dairy, cereals, and infant nutrition products. Technological advancements in encapsulation and beadlet forms support product stability, while premiumization trends boost adoption in skincare and specialty nutrition. Rising investment in R&D, coupled with a growing preference for clean-label and plant-based retinol sources, continues to fuel steady regional growth.
Europe:
Europe holds approximately 25% of the global retinol market, with significant adoption in fortified foods, functional beverages, and infant formula. Stringent regulatory standards, such as EU directives on micronutrient fortification, ensure high-quality and safe product offerings. Germany, France, and the U.K. are key contributors due to strong consumer demand for nutritional and wellness products. Increasing popularity of plant-based and vegan-friendly retinol sources presents growth opportunities. Additionally, the region’s emphasis on preventive healthcare, immunity-boosting foods, and technological innovations in retinol encapsulation drives steady expansion across both mainstream and premium segments.
Asia-Pacific:
Asia-Pacific represents a rapidly growing market, capturing around 30% share due to increasing urbanization, rising disposable incomes, and government-led vitamin A fortification programs. India, China, and Southeast Asia are primary growth drivers, with high demand in fortified staples, dairy products, and infant nutrition. The region’s expanding middle class and rising health-conscious population support functional food and supplement adoption. Manufacturers are leveraging localized formulations, cost-effective production, and advanced encapsulation technologies to enhance stability and bioavailability. The combination of regulatory support, awareness campaigns, and expanding retail and e-commerce networks positions Asia-Pacific as the fastest-growing region globally.
Latin America:
Latin America accounts for roughly 10% of the retinol market, driven by rising awareness of vitamin A deficiency and increasing consumption of fortified foods and dietary supplements. Brazil and Mexico are major contributors, supported by government-led fortification initiatives and public health programs. The growing retail sector and expanding urban populations enable broader distribution of functional and fortified products. Additionally, technological improvements in retinol stabilization and encapsulation support product longevity in tropical climates. Challenges include price sensitivity and regulatory variations across countries, yet opportunities exist in premium fortified foods and infant nutrition segments, offering potential for incremental market growth.
Middle East & Africa:
The Middle East & Africa holds around 7% market share, influenced by increasing awareness of micronutrient deficiencies and gradual adoption of fortified foods and beverages. Gulf Cooperation Council countries, South Africa, and Egypt are key markets, where urbanization and rising disposable income drive demand for functional nutrition products. Infant nutrition and dairy fortification present significant opportunities. However, market growth is constrained by regulatory inconsistencies, limited distribution networks, and cost-sensitive consumers. Investment in stable retinol formulations, localized fortification strategies, and awareness campaigns could enhance adoption, creating potential for steady growth across both urban and emerging rural markets in the region.
Market Segmentations:
By Source:
- Synthetic
- Semi-synthetic
By Form:
- Powder
- Liquid
By Application:
- Dairy products
- Bakery & confectionery
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Retinol (Vitamin A) market is highly competitive, with key players such as Botanic Healthcare, Fengchen Group Co., Ltd, CSPC Pharmaceutical Group Limited, Global Calcium PVT LTD, Northeast Pharmaceutical Group Co., Ltd (NEPG), Sinofi Ingredients, Foodchem International Corporation, DSM Jiangshan Pharmaceutical (Jiangsu) Co., Ltd, Fooding, and Spectrum Chemical. The Retinol (Vitamin A) market is highly competitive, driven by continuous innovation in formulation and delivery technologies such as microencapsulation, beadlets, and stabilized powders to enhance bioavailability, stability, and shelf life. Companies are increasingly investing in research and development to introduce fortified foods, functional beverages, and infant nutrition products that meet rising consumer demand for health, immunity, and wellness benefits. Strategic initiatives, including mergers, partnerships, and regional expansion, are common to strengthen market position. Additionally, adherence to stringent regulatory standards, focus on clean-label and sustainable sourcing, and adaptation to emerging market trends enable companies to differentiate their offerings and capture growth opportunities in both mature and high-growth regions globally.
Key Player Analysis
- Botanic Healthcare
- Fengchen Group Co., Ltd
- CSPC Pharmaceutical Group Limited
- Global Calcium PVT LTD
- Northeast Pharmaceutical Group Co., Ltd (NEPG)
- Sinofi Ingredients
- Foodchem International Corporation
- DSM Jiangshan Pharmaceutical (Jiangsu) Co., Ltd
- Fooding
- Spectrum Chemical
Recent Developments
- In April 2024, P&G Health's Evion launched a new Vitamin E enriched cream, co-branded with Aloe Vera, to be used as a daily moisturizer or with sunscreen for enhanced nourishment. The new formulation aims to provide deep hydration, protect the skin from environmental damage, and reduce dullness and dark spots, resulting in more radiant and healthy-looking skin.
- In March 2024, Lonza announced an agreement with Roche to acquire Genentech's biologics manufacturing site in California. This is expected to significantly enhance Lonza's biologics manufacturing capability and make it one of the largest sites globally.
- In February 2024, Performance Lab, a UK-based company, launched new supplements including vitamin C, vitamin B complex, and magnesium, stating they are 100% plant-based and free from artificial binders and fillers.
Report Coverage
The research report offers an in-depth analysis based on Source, Form, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for fortified and functional foods will continue to drive market growth globally.
- Innovative delivery technologies like microencapsulation and beadlets will expand product applications.
- Increasing consumer awareness of eye health, immunity, and overall wellness will boost retinol adoption.
- Clean-label and plant-based retinol sources will gain popularity among health-conscious consumers.
- Infant nutrition and specialized dietary products will remain high-growth segments.
- Emerging markets will see accelerated growth due to urbanization and rising disposable incomes.
- Regulatory support for vitamin A fortification will encourage wider product incorporation.
- Manufacturers will invest in R&D to enhance stability, bioavailability, and shelf life of retinol.
- E-commerce and modern retail channels will facilitate greater accessibility of fortified products.
- Collaboration and partnerships within the industry will drive innovation and market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Retinol (Vitamin A) Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Retinol (Vitamin A) Market projected to grow between 2025 and 2032?
What are the key drivers for the growth of the Retinol (Vitamin A) market?
Which is the major segment in Retinol (Vitamin A) Market by End-user?
Who are the leading companies in the Retinol (Vitamin A) Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1009.6 million → 2032: USD 1403.11 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Retinol (Vitamin A) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Retinol (Vitamin A) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Retinol (Vitamin A) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Retinol (Vitamin A) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Retinol (Vitamin A) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Retinol (Vitamin A) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Retinol (Vitamin A) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Retinol (Vitamin A) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1009.6 million → 2032: USD 1403.11 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Retinol (Vitamin A) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Retinol (Vitamin A) Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Retinol (Vitamin A) Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Retinol (Vitamin A) Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
