
Market Overview
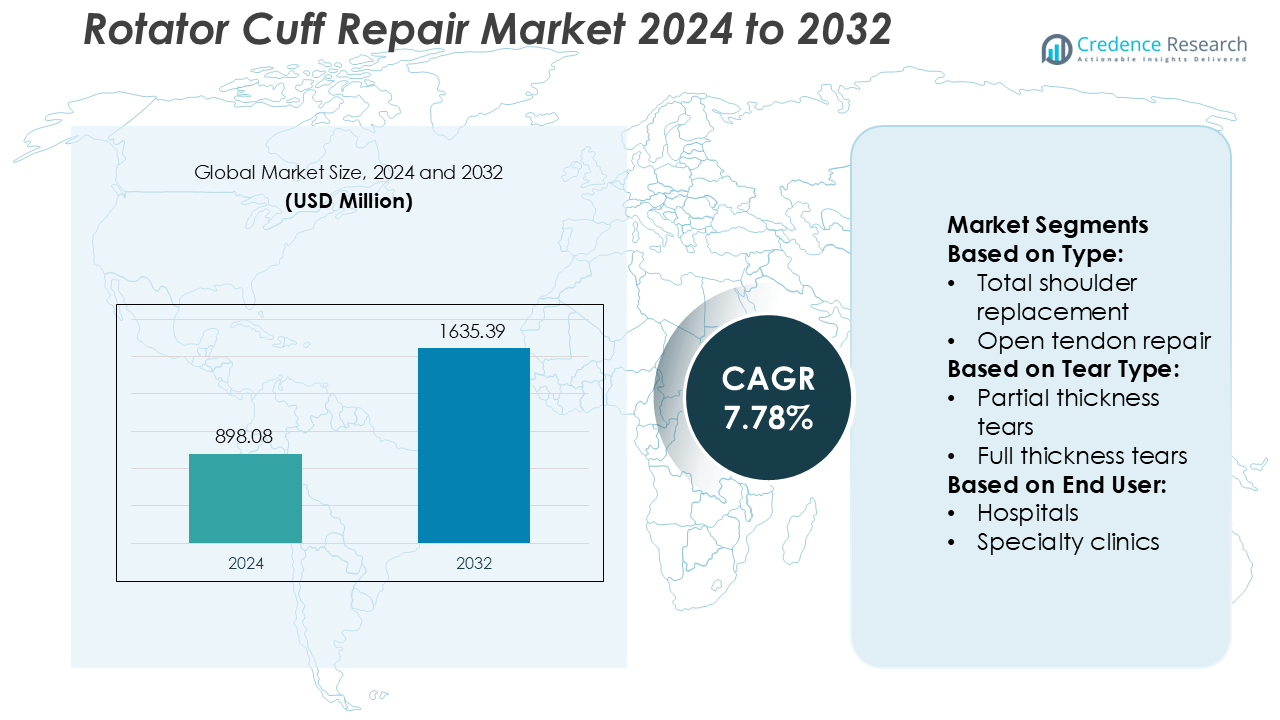
Rotator Cuff Repair Market size was valued USD 898.08 million in 2024 and is anticipated to reach USD 1635.39 million by 2032, at a CAGR of 7.78% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Rotator Cuff Repair Market Size 2024 | USD 898.08 Million |
| Rotator Cuff Repair Market, CAGR | 7.78% |
| Rotator Cuff Repair Market Size 2032 | USD 1635.39 Million |
The rotator cuff repair market features strong competition among major players such as Smith & Nephew plc, DePuy Synthes, KARL STORZ, Orthocell Limited, Atreon Orthopedics, Regenexx, Novartis AG, Physiomobility Health Group, OrthoNY, and SironixMedtech. These companies focus on developing advanced arthroscopic systems, biologic grafts, and regenerative therapies to improve patient recovery and surgical precision. North America leads the global market with a 42% share in 2024, driven by high healthcare expenditure, a well-established orthopedic infrastructure, and the rapid adoption of minimally invasive repair procedures. Continuous innovation, favorable reimbursement policies, and the presence of leading device manufacturers sustain the region’s dominance.
Market Insights
- The Rotator Cuff Repair Market was valued at USD 898.08 million in 2024 and is projected to reach USD 1635.39 million by 2032, growing at a CAGR of 7.78%.
- Rising prevalence of shoulder injuries, expanding geriatric population, and adoption of arthroscopic surgeries are key growth drivers enhancing treatment demand.
- The market trend shows increasing use of orthobiologics and regenerative therapies, alongside technological advancements in robotic-assisted and minimally invasive repair systems.
- Competitive dynamics are shaped by innovation-focused players investing in biologic implants, imaging technologies, and global partnerships to improve procedural outcomes.
- North America dominates with a 42% market share, supported by advanced healthcare infrastructure and strong manufacturer presence, while the surgery segment, led by arthroscopy, holds a 54% share, reflecting patient preference for faster recovery and precision-based procedures.
Market Segmentation Analysis:
By Type
The surgery segment leads the rotator cuff repair market with a 54% share in 2024. Arthroscopy dominates within this category due to its minimally invasive approach, shorter recovery time, and lower postoperative complications. Surgeons increasingly prefer arthroscopic procedures for enhanced visualization and precision in tendon reattachment. The rising incidence of sports-related shoulder injuries and degenerative tears in the elderly further boosts demand. Advancements in arthroscopic instruments, suture anchors, and imaging guidance technologies are driving adoption in both developed and emerging healthcare markets.
- For instance, Smith & Nephew plc introduced its LYNX 4K arthroscopic imaging system, featuring advanced 4K ultra-high-definition resolution and an integrated digital platform supporting real-time visualization during shoulder repairs.
By Tear Type
Full-thickness tears hold the dominant share of 63% in 2024, driven by their higher clinical severity and the necessity for surgical intervention. These tears often result from trauma or chronic degeneration and significantly impair shoulder function. The growing aging population and increasing participation in physically demanding activities contribute to their prevalence. Healthcare providers are prioritizing early diagnosis through MRI and ultrasound imaging to optimize surgical outcomes. The availability of advanced biologic repair materials and minimally invasive options enhances treatment success for full-thickness tear management.
- For instance, Sironix Medtech reports that its portfolio of shoulder implants has surpassed 125,000 + units implanted globally. Its STATIV® all-suture anchor (available in 1.5 mm and 1.8 mm diameters) features a patented design that removes minimal bone and provides secure fixation for shoulder instability repairs.
By End User
Hospitals represent the largest end-user segment, accounting for 48% of the market in 2024. They lead due to their comprehensive surgical infrastructure, advanced imaging equipment, and presence of skilled orthopedic surgeons. Hospitals also serve as primary centers for complex rotator cuff repair procedures, including arthroscopy and total shoulder replacement. The rising patient inflow for sports injuries and post-traumatic shoulder disorders supports this dominance. In addition, expanding reimbursement coverage and the integration of specialized rehabilitation units within hospitals improve patient recovery and procedural efficiency.
Key Growth Drivers
Increasing Prevalence of Shoulder Injuries
The growing incidence of shoulder injuries due to sports activities, occupational strain, and aging populations is a primary growth driver. Rotator cuff tears are increasingly diagnosed in individuals over 40, often resulting from repetitive motion and tissue degeneration. This rise in cases fuels demand for both surgical and non-surgical repair options. Improved awareness, better diagnostic imaging, and access to specialized orthopedic care contribute to early detection and treatment, supporting steady market expansion across both developed and emerging healthcare systems.
- For instance, Orthocell’s product Striate+™ is now cleared for use in the U.S., Australia, Europe, Canada, Brazil and Singapore, and achieved a post-market study success rate of 98.6%.
Technological Advancements in Surgical Techniques
The adoption of minimally invasive and arthroscopic procedures is transforming rotator cuff repair outcomes. Advanced suture anchors, biologic grafts, and 3D imaging systems have enhanced surgical precision and recovery speed. Hospitals and surgical centers increasingly use robotic-assisted tools to minimize complications and improve postoperative rehabilitation. These innovations reduce hospital stays and improve patient satisfaction, encouraging more patients to opt for surgery. Ongoing R&D investments by medical device companies continue to refine these technologies, strengthening market penetration globally.
- For instance, ROTIUM® Bioresorbable Wick integrate electrospun nanofiber scaffolds that absorb up to 469% of their weight in whole blood, enhancing the healing micro-environment at the tendon-bone interface.
Rising Adoption of Orthobiologics in Repair Procedures
The growing use of orthobiologics such as platelet-rich plasma (PRP) and stem cell therapies is accelerating treatment adoption. These materials improve healing, reduce inflammation, and enhance tendon-to-bone integration. Surgeons are increasingly using biologic augmentation to improve outcomes for chronic or complex tears. Regulatory approvals and expanding clinical studies supporting the efficacy of orthobiologics are also boosting confidence among healthcare providers. The combination of biologic and mechanical repair techniques is becoming a preferred approach, supporting the long-term success of rotator cuff treatments.
Key Trends & Opportunities
Shift Toward Outpatient and Ambulatory Surgeries
The market is witnessing a significant shift toward outpatient and ambulatory settings for rotator cuff repairs. Advancements in anesthesia and minimally invasive techniques allow same-day discharge, reducing treatment costs. Ambulatory surgery centers are increasingly preferred due to faster turnaround times and reduced infection risks. This trend benefits both patients and healthcare systems by improving accessibility and cost efficiency. Growing reimbursement support for outpatient orthopedic procedures presents a strong opportunity for market players to expand service offerings.
- For instance, Regenexx’s outpatient procedures use the patient’s own blood or bone marrow concentrate, processed to 20-times (20×) baseline stem-cell concentration via a patented protocol.
Integration of Digital and Robotic Surgery Systems
The integration of robotics and digital visualization systems in shoulder surgeries is a key trend. Robotic-assisted devices improve suture placement accuracy, minimize tissue damage, and shorten rehabilitation periods. Artificial intelligence-driven preoperative planning tools further enhance precision in tendon repair. These innovations are increasingly adopted in specialized orthopedic centers and teaching hospitals. Companies focusing on advanced navigation systems and surgical robotics are likely to gain a competitive edge by offering improved safety, consistency, and clinical outcomes.
- For instance, Novartis uses automation in drug-discovery: its screening robots test from a 1.6 million-compound library using 1,536-well microplates.
Key Challenges
High Cost of Surgical and Biologic Treatments
The high cost of arthroscopic surgeries and orthobiologic materials remains a significant barrier to widespread adoption. Many healthcare systems, especially in developing countries, face affordability challenges due to limited reimbursement. Patients often bear out-of-pocket expenses for advanced grafts or biologics, restricting accessibility. Price sensitivity among hospitals and insurance limitations further constrain market growth. Manufacturers are under pressure to provide cost-effective solutions without compromising quality, prompting a shift toward locally manufactured and reusable surgical components.
Postoperative Complications and Re-Tear Risks
Re-tear rates and postoperative complications continue to challenge long-term treatment success. Despite advances in surgical techniques, tendon re-rupture occurs in a notable percentage of patients, particularly older adults with poor tissue quality. These issues increase the need for revision surgeries and extended rehabilitation, raising overall healthcare costs. Limited patient adherence to physiotherapy and inconsistent recovery monitoring further contribute to suboptimal outcomes. This challenge emphasizes the importance of enhanced biologic repair methods and patient-specific treatment strategies in future developments.
Regional Analysis
North America
North America leads the rotator cuff repair market with a 42% share in 2024. The region’s dominance stems from high healthcare spending, widespread adoption of arthroscopic procedures, and advanced orthopedic infrastructure. The U.S. drives the majority of revenue due to a strong presence of key medical device manufacturers and favorable reimbursement policies. Increasing sports participation and a rising elderly population further contribute to market expansion. Continuous innovation in surgical tools and biologic therapies strengthens regional growth, while strong collaborations between hospitals and research institutions support clinical advancements in rotator cuff repair techniques.
Europe
Europe holds a 27% share of the rotator cuff repair market in 2024, driven by advanced healthcare systems and growing awareness of early orthopedic intervention. Germany, the U.K., and France remain key contributors due to the increasing use of minimally invasive procedures and orthobiologic implants. Supportive government healthcare funding and well-established rehabilitation services promote patient recovery and procedural success. The market also benefits from the rising prevalence of degenerative joint diseases in the aging population. Ongoing technological improvements and the expansion of outpatient orthopedic centers continue to strengthen Europe’s position in the global market.
Asia-Pacific
Asia-Pacific accounts for 20% of the global market share in 2024 and represents the fastest-growing regional segment. Rising healthcare investments, increasing sports-related injuries, and expanding access to orthopedic specialists are key growth drivers. China, Japan, and India are major contributors due to improving hospital infrastructure and rising adoption of arthroscopic repair systems. The growing middle-class population and higher health awareness are encouraging elective surgical procedures. Favorable government initiatives promoting medical tourism and the establishment of specialized orthopedic centers further enhance regional growth prospects in rotator cuff repair treatments.
Latin America
Latin America captures an 7% share of the rotator cuff repair market in 2024. The region is witnessing increasing demand for affordable shoulder repair procedures, particularly in Brazil, Mexico, and Argentina. Expanding healthcare infrastructure and the gradual adoption of arthroscopic techniques support market growth. However, limited access to advanced biologic materials and high treatment costs remain challenges. Government health programs focused on musculoskeletal disorders are improving diagnosis and surgical intervention rates. Rising medical tourism and the establishment of specialized orthopedic clinics in major cities further enhance regional market opportunities.
Middle East & Africa
The Middle East & Africa hold a 4% share of the global market in 2024. Growth is supported by expanding private healthcare facilities and a rising focus on orthopedic care modernization. The United Arab Emirates and Saudi Arabia lead regional adoption due to investments in advanced surgical technology and skilled orthopedic professionals. Increasing sports-related shoulder injuries among younger populations also contribute to demand. However, high treatment costs and limited reimbursement coverage restrict broader access. Ongoing government initiatives to enhance healthcare infrastructure are expected to support gradual market growth in the coming years.
Market Segmentations:
By Type:
- Total shoulder replacement
- Open tendon repair
By Tear Type:
- Partial thickness tears
- Full thickness tears
By End User:
- Hospitals
- Specialty clinics
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Rotator Cuff Repair Market is characterized by the presence of key players such as Smith & Nephew plc, SironixMedtech, Physiomobility Health Group, Orthocell Limited, Atreon Orthopedics, Regenexx, KARL STORZ, OrthoNY, DePuy Synthes, and Novartis AG. The rotator cuff repair market is driven by continuous innovation in surgical techniques, biologics, and rehabilitation solutions. Companies are investing heavily in research and development to enhance the precision, safety, and recovery outcomes of repair procedures. The market is seeing a growing shift toward minimally invasive arthroscopic technologies, supported by advancements in imaging systems and suture materials. Collaboration between medical device manufacturers, hospitals, and research institutions is strengthening clinical efficacy and accelerating product approvals. Strategic mergers, acquisitions, and global distribution expansions remain key approaches for sustaining competitiveness and addressing the rising global demand for advanced shoulder repair treatments.
Key Player Analysis
- Smith & Nephew plc
- SironixMedtech
- Physiomobility Health Group
- Orthocell Limited
- Atreon Orthopedics
- Regenexx
- KARL STORZ
- OrthoNY
- DePuy Synthes
- Novartis AG
Recent Developments
- In February 2025, Atreon Orthopedics received FDA 510(k) clearance and launched the BioCharge Autobiologic Matrix, a fully resorbable synthetic scaffold for rotator cuff repair. The implant enhances tendon healing, reinforces the suture-tendon interface, and reduces re-tear risk. It is designed for simplified arthroscopic implantation, improving surgical efficiency and patient outcomes.
- In July 2024, Inter Cars extended its strategic collaboration with TotalEnergies Lubrifiants for a further five years. The long-term deal prioritizes delivering high-quality lubricants to the automotive repair and maintenance sector. The partnership, extending the term of the agreement, further enhances Inter Cars service, especially for independent workshops and service centers throughout Europe, with the provision of its original equipment quality lubricants for vehicle maintenance.
- In July 2023, Smith+Nephew introduced its REGENETEN Bioinductive Implant in India, following over 100,000 procedures worldwide. Delivered arthroscopically, the implant has revolutionized rotator cuff procedures. The launch aimed to elevate patient care standards for those affected by rotator cuff disease.
Report Coverage
The research report offers an in-depth analysis based on Type, Tear Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience steady growth due to increasing shoulder injury cases worldwide.
- Demand for minimally invasive arthroscopic procedures will continue to rise among surgeons.
- Orthobiologics and regenerative therapies will gain wider acceptance in tendon healing.
- Technological advancements in imaging and robotics will enhance surgical precision.
- Outpatient and ambulatory surgical centers will play a larger role in treatment delivery.
- Growing awareness of early diagnosis will drive patient preference for timely intervention.
- Expansion of reimbursement coverage will improve access to advanced surgical options.
- Collaborations between device manufacturers and healthcare providers will strengthen innovation.
- Personalized treatment plans using AI-driven diagnostics will improve clinical outcomes.
- Emerging economies will witness faster adoption due to improved healthcare infrastructure and training.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Rotator Cuff Repair Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Rotator Cuff Repair Market projected to grow between 2025 and 2032?
Which Rotator Cuff Repair Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Rotator Cuff Repair Market?
Who are the leading companies in the Rotator Cuff Repair Market?
Which region commanded the largest share of the Rotator Cuff Repair Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 898.08 million → 2032: USD 1635.39 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Rotator Cuff Repair Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Rotator Cuff Repair Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Rotator Cuff Repair Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Rotator Cuff Repair Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Rotator Cuff Repair Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Rotator Cuff Repair Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Rotator Cuff Repair Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Rotator Cuff Repair Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 898.08 million → 2032: USD 1635.39 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Rotator Cuff Repair Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Rotator Cuff Repair Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Rotator Cuff Repair Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Rotator Cuff Repair Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

