
Market Overview:
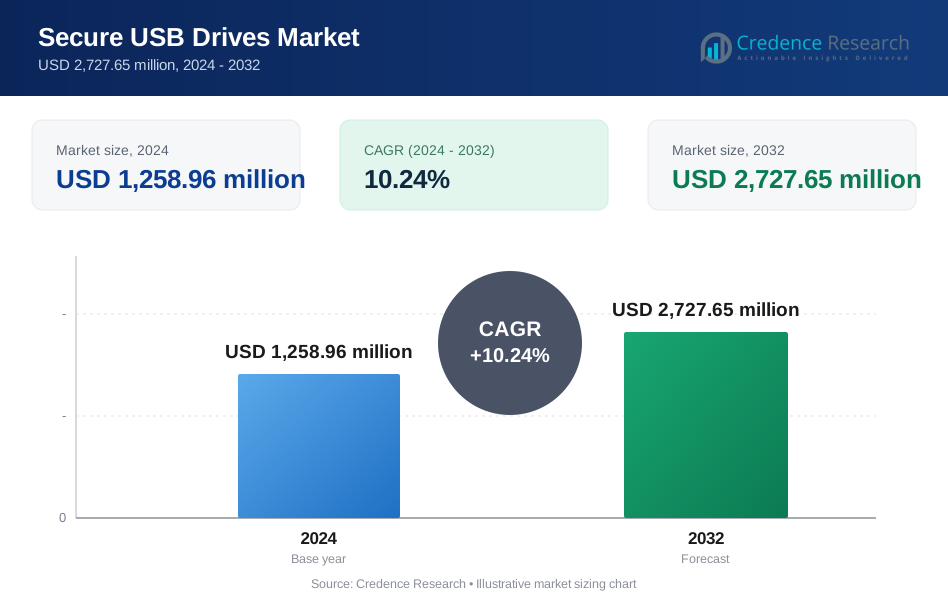
The Secure USB Drives Market size was valued at USD 890.00 million in 2018 to USD 1,258.96 million in 2024 and is anticipated to reach USD 2,727.65 million by 2032, at a CAGR of 10.24% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Secure USB Drives Market Size 2024 | USD 1,258.96 Million |
| Secure USB Drives Market, CAGR | 10.24% |
| Secure USB Drives Market Size 2032 | USD 2,727.65 Million |
Rising cybersecurity threats, stricter compliance requirements, and remote work adoption are driving secure USB drive usage across enterprises and government institutions. These drives offer hardware encryption, biometric or keypad access, and tamper-proof features to protect sensitive files. Organizations in finance, defense, and healthcare are increasingly deploying them to prevent data leaks and maintain regulatory compliance. Remote users rely on secure USBs to transfer data safely across unsecured networks or offline devices. High-profile data breach incidents have reinforced the need for portable encrypted storage.
North America leads the market due to strong regulatory enforcement and enterprise cybersecurity maturity. Europe follows, supported by GDPR and national data security mandates. Asia Pacific is emerging rapidly with increased IT modernization and awareness in countries like China, Japan, and India. Latin America is gaining traction through public sector digitization, while the Middle East shows consistent demand from government and defense sectors. Africa remains at an early stage, with gradual adoption in education and public administration sectors.

Market Insights:
- The Secure USB Drives Market reached USD 890.00 million in 2018, USD 1,258.96 million in 2024, and USD 2,727.65 million by 2032, growing at a CAGR of 10.24%.
- North America leads with 35.36% share, followed by Europe at 27.38% and Asia Pacific at 26.95%, driven by regulation and enterprise security demand.
- Asia Pacific is the fastest-growing region with about 26.95% share, supported by rapid digitalization, government IT programs, and rising cyber risks.
- By type, hardware-based secure USB drives hold nearly 65% share, while software-based secure USB drives account for around 35%.
- By application, government and military contribute about 38% share, while finance and enterprises together represent nearly 44% of demand.
Market Drivers
Rising Demand for Endpoint Data Protection Across Distributed and Mobile Workforces
The rise in remote work and BYOD policies increases the need for secure endpoint devices. Organizations are prioritizing encrypted USB drives to prevent accidental data loss or unauthorized access. Secure USB drives offer hardware-based encryption, physical protection, and password or biometric access controls. These features are essential when employees work outside the corporate network. Cyberattacks targeting removable media highlight the importance of secure drives. Enterprises are implementing strict policies for handling sensitive information. Sectors like finance, healthcare, and defense rely on secure drives for compliance. The Secure USB Drives Market responds with certified, tamper-proof solutions. It continues to evolve to support both operational flexibility and data integrity.
- For example, Apricorn Aegis Secure Key 3NX, featuring FIPS 140-2 Level 3 certification and a rugged aluminum body tested to MIL-STD-810G for drops. This aligns with hardware encryption and physical protection needs.
Stringent Regulatory Mandates for Data Security Across Key Industry Verticals
Data protection regulations in North America and Europe drive secure hardware adoption. Laws like GDPR, HIPAA, and FISMA require strong data encryption and control. Non-compliance risks include heavy fines, litigation, and reputational damage. Secure USB drives help enterprises maintain control over portable data transfer. Devices with FIPS 140-2 and Common Criteria certifications are preferred in regulated sectors. The BFSI sector uses secure USBs for customer data handling and internal audits. Healthcare relies on them for patient information and clinical records. Governments enforce secure data access for sensitive files. These factors ensure sustained growth of the Secure USB Drives Market.
Growing Adoption of Encrypted USBs in Military, Defense, and Government Agencies
Military and defense users require portable drives with robust encryption, authentication, and tamper-resistance. Secure USBs used in these sectors must operate under harsh physical and cyber conditions. They protect mission-critical files and national security information. Government agencies deploy secure USBs for identity management and secure offline access. Drive approvals for classified data handling push demand for certified models. Solutions with remote wipe, write-protection, and zero-footprint software are gaining traction. OEMs are integrating dual-factor authentication and onboard malware protection. Secure USBs are also used for secure OS booting and controlled distribution of files. These requirements significantly expand adoption across public sector institutions.
- For example, Kingston IronKey D300, which is waterproof to IEC 60529 IPX8 (up to 1.2 meters submersion) and operates from 0°C to 60°C, with tamper-evident epoxy filling for harsh conditions.
Integration of Hardware-Level Encryption with Advanced Access Controls
Secure USB drives now include biometric fingerprint readers and keypad access. These features reduce reliance on software-based encryption alone. Hardware-level security ensures that sensitive data stays protected even when the device is stolen. Drives can block brute-force attempts and self-destruct after failed access trials. Advanced models store credentials on secure chips and enable read-only modes. Enterprises choose multi-layered access to align with internal IT policies. Integration with digital rights management further improves control. These innovations help the Secure USB Drives Market maintain a high level of adoption. It serves both high-risk industries and corporate users seeking strong data safeguards.
Market Trends
Wider Availability of Biometric and Fingerprint Authentication in USB Drive Designs
Vendors are adding biometric features to mainstream secure USB devices. Fingerprint sensors provide single-user or multi-user authentication options. These eliminate password dependency while improving security and convenience. Drives with biometric locking are widely used in legal, finance, and consulting firms. They restrict access even if the USB is lost or stolen. Small and medium businesses are adopting biometric USBs due to ease of use. Models with onboard fingerprint templates avoid the need for drivers or software. The Secure USB Drives Market benefits from rising interest in password-free security. It also aligns with identity-driven access policies adopted by enterprises.
Rising Focus on Zero-Footprint Operation and Platform Independence
Secure USB drives are moving toward cross-platform compatibility and minimal system dependency. Zero-footprint drives operate without leaving logs on host systems. This is critical for confidential tasks in legal and intelligence domains. Drives supporting Windows, Linux, and macOS gain traction in mixed environments. Portable execution of encrypted applications further increases utility. Enterprises prefer drives that work on locked-down systems without admin rights. These trends align with increased mobility and privacy needs. Developers offer plug-and-play functionality with embedded secure browsers or readers. The Secure USB Drives Market evolves with demand for clean, portable, and discreet operation.
- For example, Kanguru Defender Elite300 lacks verifiable fingerprint support; it's password-based with AES 256-bit encryption and FIPS 140-2 certification, but no biometric features per official specs.
Cloud-Integrated Secure USBs for Backup, Sync, and Remote Management
Vendors are launching secure USB drives with hybrid local–cloud functionality. These models allow encrypted data backup to approved cloud accounts. Administrators can remotely lock, wipe, or revoke access in case of loss. Centralized key management becomes possible through cloud dashboards. Integration with Microsoft Azure or AWS enhances enterprise usability. Drives with automatic backup features address disaster recovery needs. Syncing across authorized endpoints ensures file continuity without compromising security. The Secure USB Drives Market sees growth in IT-managed environments. It serves distributed teams needing secure file transport with remote policy enforcement.
- For instance, the iStorage datAshur PRO2 features AES-XTS 256-bit hardware encryption, FIPS 140-2 Level 3 certification, and an IP68-rated waterproof and dustproof keypad design, offering robust physical and data protection for secure USB storage.
Growing Customization Demand in Industrial and Institutional Procurement
Enterprises request customized secure USB solutions with specific capacities, firmware, and access modes. Industrial use cases include offline diagnostics, software patching, and SCADA system updates. Educational institutions use secure drives for examination data handling. Public sector tenders specify hardware certifications and branding. Healthcare organizations demand drives with antivirus scanning and patient record protection. Pre-loaded policies, audit trails, and access logs are often required. Devices designed for rugged environments and extended lifespans gain traction. These trends push vendors to offer bulk-customizable secure USBs. The Secure USB Drives Market responds with sector-specific designs and modular features.
Market Challenges Analysis
Cost Constraints Limit Secure USB Adoption Among Budget-Sensitive Users and Institutions
Secure USB drives cost significantly more than standard flash drives, especially with biometric or military-grade features. This limits adoption in schools, small businesses, and cost-conscious public sector units. The price gap discourages volume purchases, particularly in emerging economies. Software-based encryption alternatives appear more affordable despite being less secure. Free cloud storage options with basic encryption also reduce interest in hardware drives. High-end models include advanced chips, onboard processors, and protective casings, increasing costs. OEMs struggle to lower prices while maintaining robust certifications. The Secure USB Drives Market faces adoption barriers in segments that prioritize cost over security. It must address pricing flexibility to penetrate underserved sectors.
Limited Awareness of Encrypted USB Benefits in Developing Economies
Many small businesses in developing countries are unaware of risks tied to unencrypted data transfers. This slows market expansion in regions with low cybersecurity maturity. Users may not understand the distinction between basic password protection and hardware encryption. Regulatory enforcement also lags in several APAC and African countries. Limited IT budgets and infrastructure further reduce secure hardware procurement. Training gaps in cybersecurity awareness contribute to reliance on traditional USBs. In such regions, the Secure USB Drives Market must rely on partnerships, pilot programs, and government incentives. Expanding education and awareness remains a key challenge for broader adoption.

Market Opportunities
Expansion into Education, Legal, and Consulting Sectors with Mid-Range Certified Models
Vendors can tap institutional buyers in education, law, and consulting with mid-priced, FIPS-compliant drives. These sectors need to transfer confidential documents securely, often in offline conditions. Secure USBs offer simple and compliant solutions without full infrastructure upgrades. The Secure USB Drives Market can benefit by offering entry-level certified drives at scale. This opens new avenues beyond defense and finance segments.
Growth Potential in Asia Pacific Through Local Manufacturing and Compliance Support
APAC countries show rising demand due to digitalization and cyber risk concerns. Governments promote local secure hardware sourcing through public procurement policies. Vendors entering through localization, language support, and region-specific features can win long-term contracts. The Secure USB Drives Market can grow by building supply chain presence and certification partnerships across Asia.
Market Segmentation Analysis:
By type, hardware-based secure USB drives lead the Secure USB Drives Market due to their robust, tamper-resistant encryption. These drives offer onboard security features such as biometric access, PIN authentication, and self-destruct mechanisms. Enterprises and government agencies prefer them for their ability to operate independently of software. Software-based secure USB drives hold a smaller share, appealing to users seeking flexibility and lower cost. They are more suitable for individuals and small businesses with basic security needs.
- For instance, Kingston's IronKey D300 provides AES 256-bit hardware encryption in XTS mode with FIPS 140-2 Level 3 certification, reformatting after 10 invalid password attempts and featuring a zinc casing sealed with tamper-evident epoxy.
By application, the government/military segment dominates the market due to stringent data protection requirements and classified information handling. These institutions deploy secure USBs across defense operations, intelligence, and public infrastructure. The finance sector ranks second, using encrypted drives to safeguard sensitive client data and comply with regulatory audits. Enterprise users adopt secure USBs for internal file transfer, employee mobility, and endpoint control. The individual segment is growing steadily, driven by increasing awareness of personal data protection. It supports adoption of entry-level and biometric USB solutions. The Secure USB Drives Market continues to diversify across sectors with rising focus on compliance and data privacy.
- For instance, Apricorn's Aegis Secure Key 3z delivers XTS-AES 256-bit hardware encryption with FIPS 140-2 Level 3 certification and a hardened aluminum keypad rated for over 1 million presses.
Segmentation:
By Type
- Software-Based Secure USB Drives
- Hardware-Based Secure USB Drives
By Application
- Government / Military
- Finance
- Enterprises
- Individual
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Secure USB Drives Market size was valued at USD 318.62 million in 2018 to USD 445.16 million in 2024 and is anticipated to reach USD 963.14 million by 2032, at a CAGR of 10.2% during the forecast period. North America holds the highest market share of approximately 35.36% in 2024. Strong cybersecurity regulations and enforcement across the U.S. and Canada drive adoption. Government and defense agencies deploy secure USBs for handling classified and mission-critical data. Enterprises prioritize encrypted storage to comply with HIPAA, FISMA, and other data privacy mandates. High spending on endpoint security and digital transformation fuels hardware-based USB drive purchases. Leading vendors operate from the region, supporting fast product delivery and certifications. Remote work and mobile workforce trends sustain consistent demand. The Secure USB Drives Market benefits from a mature cybersecurity landscape in North America.
Europe
The Europe Secure USB Drives Market size was valued at USD 252.76 million in 2018 to USD 344.67 million in 2024 and is anticipated to reach USD 708.51 million by 2032, at a CAGR of 9.5% during the forecast period. Europe accounts for a market share of 27.38% in 2024. GDPR compliance requirements continue to push enterprises toward secure data transfer solutions. Government institutions and financial service providers invest in hardware-encrypted drives. Western European countries lead in adoption, particularly Germany, the UK, and France. Organizations prefer FIPS 140-2 and Common Criteria-certified devices to meet internal audit standards. Cloud restrictions in some sectors further raise demand for portable secure storage. Vendors target procurement contracts through localization and customization. The Secure USB Drives Market gains traction in Europe through regulatory alignment and security-conscious buyers.
Asia Pacific
The Asia Pacific Secure USB Drives Market size was valued at USD 230.24 million in 2018 to USD 339.35 million in 2024 and is anticipated to reach USD 807.39 million by 2032, at a CAGR of 11.5% during the forecast period. Asia Pacific represents a market share of 26.95% in 2024. Rapid digitalization and rising data protection awareness fuel regional growth. China, Japan, South Korea, and India lead secure USB demand across government and enterprise sectors. Businesses adopt encrypted storage to prevent breaches and meet emerging compliance norms. Regional data protection laws and IT modernization programs support investments. Local production and customization options improve affordability and adoption. Educational and defense institutions adopt secure USBs for controlled data handling. The Secure USB Drives Market expands in Asia Pacific through cybersecurity initiatives and rising industrial digitization.
Latin America
The Latin America Secure USB Drives Market size was valued at USD 55.18 million in 2018 to USD 77.29 million in 2024 and is anticipated to reach USD 155.12 million by 2032, at a CAGR of 9.2% during the forecast period. Latin America holds a market share of 6.14% in 2024. Growth is driven by banking, government, and law enforcement sectors in Brazil, Mexico, and Chile. These users seek affordable, certified USB drives for internal communication and field operations. Rising cyberattacks encourage organizations to secure portable storage. Regulatory frameworks are evolving but still limited compared to North America or Europe. SMBs are gradually investing in encrypted USBs for client data security. Market penetration remains low in rural areas but gains traction in urban business zones. Vendors focus on cost-effective solutions to tap mid-tier buyers. The Secure USB Drives Market in Latin America is in its early growth phase with room for expansion.
Middle East
The Middle East Secure USB Drives Market size was valued at USD 23.14 million in 2018 to USD 29.70 million in 2024 and is anticipated to reach USD 54.84 million by 2032, at a CAGR of 8.1% during the forecast period. The region contributes around 2.36% of the market in 2024. Governments drive adoption through defense modernization and national cybersecurity initiatives. UAE and Saudi Arabia invest in secure digital infrastructure, including encrypted data storage. Secure USBs support remote access to controlled government and military networks. Enterprises in oil and gas use them for field data and system patching. Market adoption is rising, though procurement cycles can be long. Regional vendors often partner with international OEMs to meet demand. The Secure USB Drives Market in the Middle East grows steadily with state-backed security programs.
Africa
The Africa Secure USB Drives Market size was valued at USD 10.06 million in 2018 to USD 22.79 million in 2024 and is anticipated to reach USD 38.65 million by 2032, at a CAGR of 6.2% during the forecast period. Africa accounts for about 1.81% of the global market in 2024. Government agencies and NGOs are key early adopters of encrypted USBs. South Africa leads regional demand, followed by Kenya and Nigeria. Market development is slow due to limited awareness and budget constraints. Cloud and software-based security solutions still dominate many institutions. Regulatory standards for data protection are emerging across the continent. Vendors target the region with affordable models and pilot programs. The Secure USB Drives Market in Africa grows gradually with donor-backed digitization and national ICT policies.
Key Player Analysis:
- Kingston Technology
- SanDisk
- LaCie
- Kanguru Solutions
- Transcend Information
- DataLocker
- Apricorn
- Integral Memory
- iStorage
- Verbatim
- Axiom Memory Solutions

Competitive Analysis:
The Secure USB Drives Market features strong competition among global and regional players focused on high-security storage solutions. Key companies include Kingston Technology, Apricorn, Kanguru Solutions, DataLocker, and Verbatim. These vendors offer FIPS-certified and hardware-encrypted USB drives with advanced features like biometric access, onboard keypad entry, and remote wipe capabilities. Firms invest in R&D to improve compatibility, durability, and device management options. Government tenders and enterprise bulk orders drive vendor differentiation through certifications, device customization, and support services. Competitive pricing and compliance with data security regulations influence buyer preferences across sectors. Players actively expand product portfolios to serve military, healthcare, financial, and enterprise clients. The Secure USB Drives Market sees growing focus on portable secure storage with centralized control tools and policy enforcement. Strategic partnerships and regional distribution networks help companies strengthen presence in high-growth markets such as Asia Pacific and Latin America.
Recent Developments:
- In November 2025, Kingston Technology launched the Dual Portable SSD, a cable-free drive for secure data backup and transfers. The product supports USB‑A and USB‑C devices with USB 3.2 Gen 2 performance. It delivers fast read and write speeds suited for high‑resolution photos and 4K video storage.
- In September 2024, iStorage Group acquired Kanguru Solutions, a U.S.-based provider of secure data storage and duplication systems. The acquisition expanded iStorage’s hardware-encrypted product line with Kanguru’s three decades of expertise. The combined portfolio targets government, healthcare, and finance sectors in the Secure USB Drives Market.
Report Coverage:
The research report offers an in-depth analysis based on Type and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will continue rising due to stricter data privacy regulations across global enterprise and public sectors.
- Integration of biometric security and onboard authentication will drive innovation in product offerings.
- Remote work adoption will sustain long-term usage of portable encrypted storage for endpoint security.
- Cloud-managed secure USBs with remote control features will gain preference in enterprise environments.
- Emerging economies will witness growing adoption as awareness and compliance enforcement improve.
- Manufacturers will offer more sector-specific customizations, especially for defense, healthcare, and finance.
- Price-sensitive segments will see broader entry-level options with essential encryption features.
- Regional production hubs in Asia Pacific will support lower costs and higher availability.
- Strategic partnerships with IT integrators and compliance consultants will expand vendor reach.
- The Secure USB Drives Market will diversify beyond government and BFSI, capturing education and legal sectors.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for Endpoint Data Protection Across Distributed and Mobile Workforces
The shift to remote work and BYOD policies has increased the need for secure endpoint devices, with organizations prioritizing encrypted USB drives to prevent data loss or unauthorized access. Secure USB drives with hardware-based encryption and advanced access controls are essential for employees working outside corporate networks, driving market growth.
Stringent Regulatory Mandates for Data Security Across Key Industry Verticals
Data protection regulations such as GDPR, HIPAA, and FISMA require strong encryption and control over portable data, pushing enterprises and government agencies to adopt secure USB drives. Compliance needs and the risk of heavy fines for non-compliance are major factors fueling demand for certified, tamper-proof USB solutions.
Growing Adoption in Military, Defense, and Government Agencies
Military, defense, and government sectors require robust, tamper-resistant USB drives for handling classified and mission-critical data. The need for certified devices with advanced encryption, authentication, and physical protection is driving significant adoption in these high-security environments.
Integration of Hardware-Level Encryption with Advanced Access Controls
Vendors are increasingly offering secure USB drives with biometric fingerprint readers, keypad access, and self-destruct features, enhancing security beyond software-based solutions. These innovations appeal to enterprises and regulated sectors seeking multi-layered protection for sensitive data.
Rapid Digitalization and Cybersecurity Awareness in Emerging Markets
Asia Pacific and other emerging regions are experiencing rapid IT modernization and rising awareness of cyber risks, leading to increased adoption of secure USB drives. Local manufacturing, compliance support, and government IT programs further accelerate market growth in these regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Secure USB Drives Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Secure USB Drives Market projected to grow between 2024 and 2032?
Which Secure USB Drives Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Secure USB Drives Market?
Who are the leading companies in the Secure USB Drives Market?
Which region commanded the largest share of the Secure USB Drives Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Hardware-Based Secure USB Drives
- 1.2.2 Software-Based Secure USB Drives
- 1.3 By Application
- 1.3.1 Government / Military
- 1.3.2 Finance
- 1.3.3 Enterprises
- 1.3.4 Individual
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,258.96 million → 2032: USD 2,727.65 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Secure USB Drives Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Secure USB Drives Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Secure USB Drives Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Secure USB Drives Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Secure USB Drives Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Secure USB Drives Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Secure USB Drives Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Secure USB Drives Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,258.96 million → 2032: USD 2,727.65 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Secure USB Drives Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hardware-Based Secure USB Drives
- 12.3.7.2 Software-Based Secure USB Drives
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Government / Military
- 12.4.7.2 Finance
- 12.4.7.3 Enterprises
- 12.4.7.4 Individual
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Secure USB Drives End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Secure USB Drives Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Secure USB Drives Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Secure USB Drives Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Kingston Technology
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 SanDisk
- 18.4 LaCie
- 18.5 Kanguru Solutions
- 18.6 Transcend Information
- 18.7 DataLocker
- 18.8 Apricorn
- 18.9 Integral Memory
- 18.10 iStorage
- 18.11 Verbatim
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

