
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Silicon Anode Lithium-Ion Battery Market Size 2024 | USD 1,048.00 Million |
| Silicon Anode Lithium-Ion Battery Market, CAGR | 49.10% |
| Silicon Anode Lithium-Ion Battery Market Size 2032 | USD 25,596.6 Million |
Market Overview
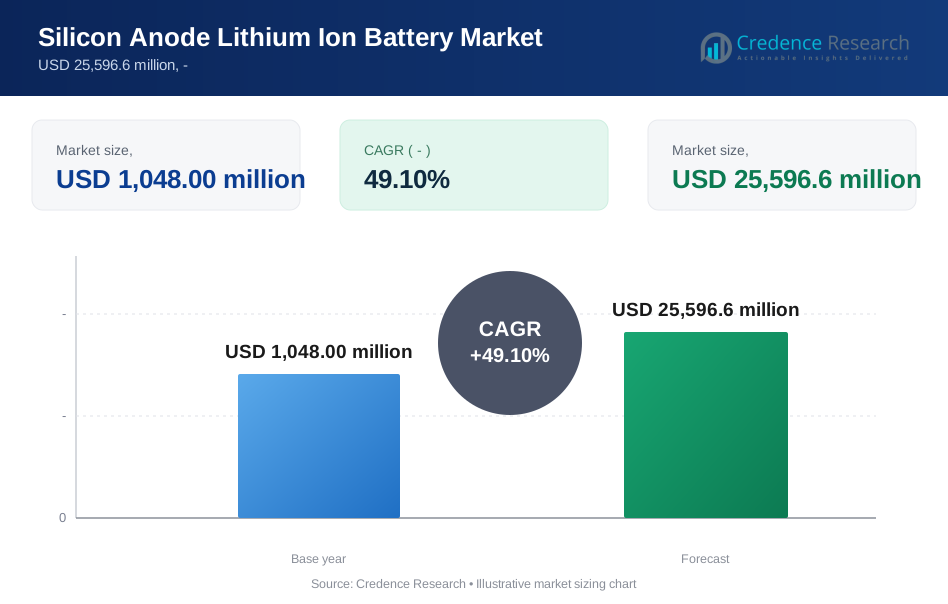
The Silicon Anode Lithium-Ion Battery Market is projected to surge from USD 1,048.00 million in 2024 to USD 25,596.6 million by 2032, reflecting an impressive compound annual growth rate (CAGR) of 49.10%.
The Silicon Anode Lithium-Ion Battery Market is propelled by advancements in battery technology and rising demand for higher energy density and longer-lasting batteries. Innovations in silicon anode materials are enhancing performance, leading to increased adoption in electric vehicles and consumer electronics. Growing environmental concerns and the shift towards renewable energy sources are driving the demand for more efficient and sustainable battery solutions. Additionally, significant investments in research and development are accelerating the commercialization of silicon anode technology, contributing to the market's robust growth trajectory.
The Silicon anode lithium-ion battery market is experiencing significant growth across North America, Europe, and Asia-Pacific. North America leads with advancements driven by key players such as Enovix Corporation and Amprius Inc., focusing on high-energy-density solutions. In Europe, companies like Sila Nanotechnologies Inc. and Boston Power Inc. are making strides in innovative technologies. Asia-Pacific, with its burgeoning industrial base, sees significant contributions from Nanograf Corp and XG Sciences Inc. These regions are at the forefront of technological advancements and market expansion, shaping the future of silicon anode battery technologies.
Market Drivers
Increased Energy Density Demands
The escalating demand for higher energy density is a primary driver for the Silicon Anode Lithium-Ion Battery Market. The burgeoning electric vehicle (EV) industry, seeking to extend driving ranges, requires batteries that surpass the performance of traditional graphite anodes. For instance, silicon anodes can hold 10 times as many lithium ions by weight as graphite, and experimental reports have observed a 20-40% increase in energy density of silicon anode-based LiBs. Silicon anodes significantly enhance energy storage capacity, making them a compelling choice for EV applications. Similarly, the consumer electronics sector, encompassing smartphones and laptops, demands longer battery life to meet the needs of users who rely on these devices throughout the day. The superior energy density provided by silicon anodes addresses these requirements effectively, driving market growth.
Government Support and Policies
Government policies and incentives are significantly shaping the Silicon Anode Lithium-Ion Battery Market. For instance, the U.S. Department of Energy announced $43 million in funding for projects that will advance research, development, demonstration, and deployment in several areas critical to the future of advanced batteries. This funding is aligned with strategies detailed in the U.S. National Blueprint for Transportation Decarbonization, which is a landmark interagency framework of strategies and actions to remove all emissions from the transportation sector by 2050. Furthermore, stringent environmental regulations are pushing for cleaner energy solutions, including advanced battery technologies. This regulatory support fosters innovation and investment in silicon anode batteries, facilitating their integration into the market and contributing to their growth.
Sustainability and Environmental Concerns
Sustainability and environmental impact are increasingly influencing battery technology advancements. Silicon-based batteries hold the potential to enhance energy storage efficiency within renewable energy systems, contributing to a greener energy landscape. This improvement is crucial as the world shifts towards sustainable energy solutions. Moreover, the development of silicon anodes aligns with global priorities to reduce the environmental footprint of battery production and disposal. By offering a more sustainable alternative to conventional battery technologies, silicon anodes support efforts to minimize ecological impact and promote a cleaner environment.
Technological Advancements
Technological advancements play a pivotal role in the growth of the silicon anode battery market. Breakthroughs in material science are addressing challenges such as volume expansion and limited cycle life associated with silicon anodes. Ongoing research and development efforts are enhancing performance and reliability, making silicon anodes more viable for widespread use. Additionally, improvements in manufacturing processes are boosting production efficiency and reducing costs. These advancements contribute to making silicon anode batteries more accessible and affordable, further driving their adoption in various applications.
Market Trends
Cost Reduction, Safety Improvements, and Supply Chain Optimization
Cost reduction remains a key trend in the silicon anode battery sector. Industry players are focused on optimizing production processes and achieving economies of scale to make silicon anodes more cost-effective. Alongside cost considerations, safety improvements are essential for the widespread adoption of silicon anode batteries. Addressing issues related to thermal runaway and ensuring battery safety are critical to gaining consumer trust and regulatory approval. Furthermore, supply chain optimization is becoming increasingly important. Establishing robust and secure supply chains for silicon and other critical materials is crucial to meet the growing demand and ensure a steady supply of high-quality components.
Collaboration, Recycling, and Technological Integration
Collaboration and partnerships within the industry are on the rise as stakeholders work together to accelerate technology development and mitigate risks associated with silicon anode batteries. For example, General Motors and OneD Battery Sciences in Palo Alto, Calif., are putting OneD’s silicon nanotechnology into GM’s Ultium battery cells. In terms of recycling, researchers at Rice University have developed a method to recycle lithium-ion batteries, using flash Joule heating, allows for rapid heating of battery waste, magnetic separation, and a remarkable 98% recovery of battery metals. The development of sustainable recycling processes for silicon-based batteries is being actively pursued to address environmental concerns and reduce the ecological footprint. Finally, there is a growing interest in integrating silicon anodes with other advanced battery technologies, such as solid-state electrolytes, to create next-generation batteries with enhanced performance and safety features.
Market Challenges Analysis
Technical Challenges: Volume Expansion, Lithium Plating, and Efficiency Issues
Silicon anode batteries face significant technical challenges that impact their performance and longevity. One major issue is volume expansion. For instance, most of the silicon-based anodes have the drawbacks of huge volume expansion (≈400%), poor electronic conductivity (≈10 −3 S cm −1), and a low Li + diffusion rate (≈10 −13 cm 2 s −1). Silicon anodes undergo substantial volume changes during charging cycles, which can lead to structural instability and a reduced cycle life. This phenomenon causes mechanical stress and degradation, making it difficult for silicon anodes to maintain consistent performance over time. Another challenge is lithium plating. The formation of lithium dendrites on the silicon anode can pose serious safety hazards, such as short circuits and thermal runaway, while also diminishing battery efficiency. Additionally, silicon anodes often suffer from low Coulombic efficiency, particularly in their initial stages. This lower efficiency impacts overall battery performance, resulting in less energy being stored and released effectively compared to traditional graphite anodes.
Economic and Market Challenges: Cost, Supply, and Competition
The silicon anode market also grapples with several economic and market-related challenges. High production costs are a significant concern, as the manufacturing of high-quality silicon anode materials involves complex processes and advanced technologies, leading to elevated costs compared to conventional graphite anodes. Additionally, the availability of raw materials poses a challenge; securing a stable supply of high-purity silicon is critical but often subject to price fluctuations and supply chain disruptions. The market maturity for silicon anode batteries remains relatively low compared to graphite-based technologies, resulting in supply chain inefficiencies and higher costs. Safety concerns further complicate market dynamics, as extensive testing and stringent safety measures are necessary to address potential risks such as thermal runaway. Furthermore, intense competition from alternative battery technologies, including solid-state and lithium-sulfur batteries, poses a threat to market share and can impact the adoption and growth of silicon anode batteries.
Market Segmentation Analysis:
By Material:
The Silicon anode lithium-ion battery market is diversified by material types, each offering unique benefits and addressing specific challenges. Micronized silicon-carbon powder combines silicon with carbon to improve conductivity and mitigate expansion issues. SILA Silicon Anode material represents a newer approach with enhanced performance metrics. Porous silicon anodes are designed to accommodate volume changes during charge and discharge cycles, enhancing cycle life. Nano-Porous Silicon provides a highly porous structure at the nanoscale, which supports better lithium-ion accommodation. SiFAB incorporates advanced fabrication techniques to improve battery efficiency and longevity. Each material segment is evolving to overcome the limitations of silicon anodes, such as volume expansion and poor cycle life, thereby driving advancements in battery performance.
By Technology:
In terms of technology, the market showcases several innovative approaches. 3D Cell Architecture introduces a three-dimensional structure to optimize space utilization and battery performance. 100% Silicon Nanowire Anode Technology utilizes silicon nanowires to enhance capacity and performance significantly. Nanocarbon scaffold technology integrates a nanocarbon framework to support silicon, improving mechanical stability and conductivity. Silgrain and Sinanode technologies focus on refining the silicon's structural properties to enhance battery life and efficiency. XFC-Energy Technology emphasizes ultra-fast charge capabilities, addressing the need for rapid energy replenishment. These technological advancements are critical in enhancing the overall performance and safety of silicon anode batteries, positioning them as competitive options in the evolving energy storage market.
Segments:
Based on Material:
- Micronized silicon-carbon powder
- SILA Silicon Anode material
- Porous silicon anodes
- Nano-Porous Silicon
- SiFAB
Based on Technology:
- 3D Cell Architecture
- 100% Silicon Nanowire Anode Technology
- Nanocarbon scaffold
- Silgrain
- Sinanode
- XFC-Energy Technology
Based on Capacity:
- < 3,000 mAh
- 3,000 to 10,000 mAh
- > 10,000 mAh
- By Application:
- Consumer Eelectronics
- Automotive
- Aerospace & Defense
- Medical Devices
- Energy
Based on the Geography:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis
Asia-Pacific
Asia-Pacific dominates the market with a substantial 45% share, primarily due to the region's stronghold in battery manufacturing and robust electric vehicle (EV) industry. China leads this segment, benefiting from its vast EV market, supportive government policies, and significant investments in battery technology. Japan and South Korea follow closely, leveraging their advanced electronics industries and research capabilities to drive innovation in silicon anode technology. The Asia-Pacific market is characterized by intense competition among battery manufacturers, leading to rapid advancements in energy density and charging capabilities. The region's market is further bolstered by the presence of major consumer electronics manufacturers, who are increasingly adopting silicon anode batteries for their products. Additionally, countries like India are emerging as potential growth markets, driven by ambitious EV adoption targets and increasing focus on renewable energy storage solutions.
North America
North America holds the second-largest market share at 30%, with the United States at the forefront of silicon anode battery development. The region's market is characterized by a strong emphasis on research and development, with numerous startups and established companies pushing the boundaries of silicon anode technology. For instance, leading silicon anode battery manufacturers like Amprius and Enevate are boosting growth by offering cost-efficient, advanced batteries for various industries like automotive and consumer electronics. The North American market benefits from significant venture capital investments and collaborations between academia and industry.
Key Player Analysis
- Nanograf Corp
- Zenlab Energy Inc.
- Enovix Corporation
- Eocell Inc.
- Sila Nanotechnologies Inc.
- Enevate Corporation
- Boston Power Inc.
- XG Sciences Inc.
- Amprius Inc.
- Nexion Ltd
- Nanotech Instruments Inc.
Competitive Analysis
In the Silicon anode lithium-ion battery market, leading players like Enovix Corporation and Amprius Inc. are distinguishing themselves with advanced technologies and substantial R&D investments. Enovix focuses on its 3D cell architecture to enhance energy density, while Amprius is renowned for its high-performance silicon nanowire anodes. Sila Nanotechnologies Inc. and Enevate Corporation are notable for their innovative silicon anode materials, with Sila leveraging silicon-carbon composites and Enevate advancing silicon-dominant anodes with high power density. Nanograf Corp and XG Sciences Inc. are driving innovation through their unique nano-porous silicon materials and proprietary technologies. The competitive landscape is marked by intense R&D activities and strategic partnerships, as companies strive to address challenges such as volume expansion and cost, aiming to gain a competitive edge in this rapidly evolving market.
Recent Developments
- In March 2022, Enovix Corporation launched an advanced technology for silicon lithium batteries to increase the tolerance level of batteries without compromising energy density. The technology provides safer batteries with better lithium plating protection, high thermal conductivity, and better mechanical strength.
- In May 2022, Sila, a next-generation battery materials company, today announced the purchase of a facility with more than 600,000 square feet of space located in Moses Lake, WA to be used to manufacture Sila’s breakthrough lithium-ion anode materials at automotive volumes and quality. Powered with hydropower, the facility is located on 160 acres of land close to rail lines for convenient and efficient shipping.
- In February 2023, Nanograf raised $65 million in an oversubscribed Series B funding round to scale North American production of Silicon Anode products.
- In April 2022, Zenlab announced that Energy Assurance, an independent third-party test laboratory, validated the high specific energy and high power of Zenlab’s new large-format pouch cells for the electric aviation market.
- In March 2022, Eocell entered into a Master Development Agreement with Morrow Batteries AS to commercialize a best-in-class prismatic battery for the automotive industry.
Market Concentration & Characteristics
The Silicon anode lithium-ion battery market exhibits moderate concentration with a few key players dominating the landscape. Leading companies such as Enovix Corporation, Amprius Inc., and Sila Nanotechnologies Inc. hold significant market shares due to their advanced technologies and substantial investments in R&D. This concentration is driven by the high barriers to entry, including the need for sophisticated manufacturing capabilities and significant capital expenditure. The market is characterized by rapid technological advancements and ongoing innovation, with players focusing on improving energy density, cycle life, and cost-efficiency. Competitive dynamics are shaped by strategic partnerships, technology licensing, and aggressive R&D efforts aimed at overcoming challenges like volume expansion and manufacturing costs. As a result, the market remains dynamic, with players continuously striving to differentiate their offerings and capture a larger share of the growing demand for high-performance battery solutions.
Report Coverage
The research report offers an in-depth analysis based on Material, Technology, Capacity and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to see widespread adoption as technology advances.
- Innovations will improve energy density, cycle life, and efficiency.
- Production costs will decrease with better manufacturing processes.
- Enhanced safety measures will address thermal runaway and other risks.
- Growth in electric vehicles, consumer electronics, and renewable energy will drive market expansion.
- Increased collaboration will accelerate technological development.
- Focus on sustainability will lead to better recycling practices and reduced environmental impact.
- Supportive government policies and incentives will boost market growth.
- The market will remain competitive with players striving for leadership.
- Expansion into emerging markets will contribute to global growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increased Energy Density Demands
Silicon anode lithium-ion batteries offer significantly higher energy density compared to traditional graphite anodes, making them highly attractive for electric vehicles and consumer electronics that require longer battery life and greater storage capacity.
Government Support and Policies
Substantial government funding and supportive policies, such as those from the U.S. Department of Energy and European initiatives, are accelerating research, development, and commercialization of silicon anode technologies, fostering market growth.
Sustainability and Environmental Concerns
The shift toward renewable energy and the need for more sustainable battery solutions are driving adoption of silicon anode batteries, which can improve energy storage efficiency and reduce the environmental impact of battery production and disposal.
Technological Advancements
Breakthroughs in material science and manufacturing processes are overcoming challenges like volume expansion and cycle life, making silicon anode batteries more reliable, cost-effective, and suitable for mass-market applications.
Cost Reduction and Supply Chain Optimization
Industry efforts to optimize production processes and secure robust supply chains for silicon and related materials are reducing costs and ensuring a steady supply of high-quality components, supporting broader market adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Silicon anode lithium-ion battery market?
What factors are driving the growth of the Silicon anode lithium-ion battery market?
What are the key segments within the Silicon anode lithium-ion battery market?
What are some challenges faced by the Silicon anode lithium-ion battery market?
Who are the major players in the Silicon anode lithium-ion battery market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Capacity
- 1.2.1 < 3,000 mAh
- 1.2.2 3,000 to 10,000 mAh
- 1.2.3 > 10,000 mAh
- 1.3 By Material
- 1.3.1 Micronized silicon-carbon powder
- 1.3.2 SILA Silicon Anode material
- 1.3.3 Porous silicon anodes
- 1.3.4 Nano-Porous Silicon
- 1.3.5 SiFAB
- 1.4 By Technology
- 1.4.1 3D Cell Architecture
- 1.4.2 100% Silicon Nanowire Anode Technology
- 1.4.3 Nanocarbon scaffold
- 1.4.4 Silgrain
- 1.4.5 Sinanode
- 1.4.6 XFC-Energy Technology
- 1.5 By Application
- 1.5.1 Consumer Electronics
- 1.5.2 Automotive
- 1.5.3 Aerospace & Defense
- 1.5.4 Medical Devices
- 1.5.5 Energy
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,048.00 million → 2032: USD 25,596.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Silicon Anode Lithium Ion Battery Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Silicon Anode Lithium Ion Battery Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Silicon Anode Lithium Ion Battery Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Silicon Anode Lithium Ion Battery Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Silicon Anode Lithium Ion Battery Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Silicon Anode Lithium Ion Battery Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Silicon Anode Lithium Ion Battery Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Silicon Anode Lithium Ion Battery Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,048.00 million → 2032: USD 25,596.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Silicon Anode Lithium Ion Battery Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Capacity - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 < 3,000 mAh
- 12.3.7.2 3,000 to 10,000 mAh
- 12.3.7.3 > 10,000 mAh
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Micronized silicon-carbon powder
- 12.4.7.2 SILA Silicon Anode material
- 12.4.7.3 Porous silicon anodes
- 12.4.7.4 Nano-Porous Silicon
- 12.4.7.5 SiFAB
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 3D Cell Architecture
- 12.5.7.2 100% Silicon Nanowire Anode Technology
- 12.5.7.3 Nanocarbon scaffold
- 12.5.7.4 Silgrain
- 12.5.7.5 Sinanode
- 12.5.7.6 XFC-Energy Technology
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Consumer Electronics
- 12.6.7.2 Automotive
- 12.6.7.3 Aerospace & Defense
- 12.6.7.4 Medical Devices
- 12.6.7.5 Energy
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Silicon Anode Lithium Ion Battery End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Silicon Anode Lithium Ion Battery Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Silicon Anode Lithium Ion Battery Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Silicon Anode Lithium Ion Battery Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Nanograf Corp
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Zenlab Energy Inc.
- 18.4 Enovix Corporation
- 18.5 Eocell Inc.
- 18.6 Sila Nanotechnologies Inc.
- 18.7 Enevate Corporation
- 18.8 Boston Power Inc.
- 18.9 XG Sciences Inc.
- 18.10 Amprius Inc.
- 18.11 Nexion Ltd
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

