
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smart Home Appliances Market Size 2024 | USD 61.73 Million |
| Smart Home Appliances Market, CAGR | 9.01% |
| Smart Home Appliances Market Size 2032 | USD 129.24 Million |
Market Overview
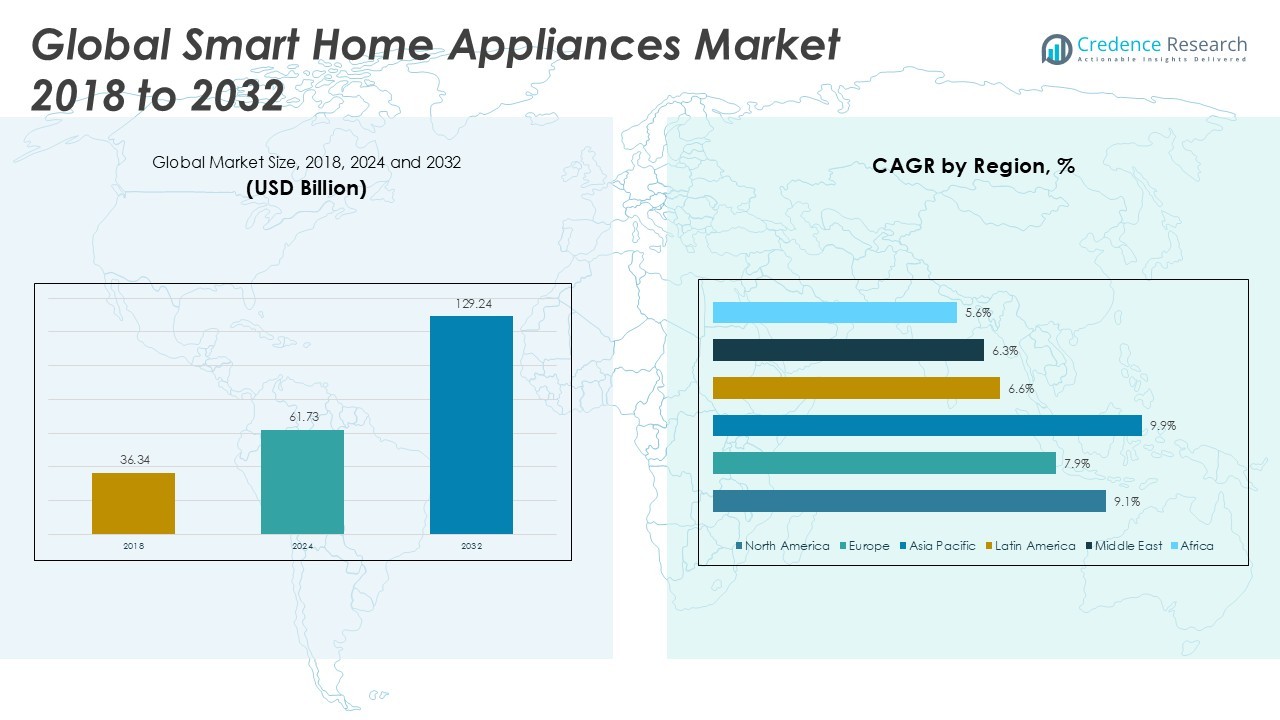
Smart Home Appliances Market size was valued at USD 36.34 billion in 2018 to USD 61.73 billion in 2024 and is anticipated to reach USD 129.24 billion by 2032, at a CAGR of 9.01% during the forecast period.
The Smart Home Appliances market is experiencing robust growth driven by rising consumer demand for convenience, energy efficiency, and connectivity. Increasing adoption of Internet of Things (IoT) technology and smart assistants has made home automation more accessible, encouraging consumers to upgrade traditional appliances. Urbanization, improving living standards, and growing awareness of energy conservation are further fueling market expansion. Key manufacturers are investing in product innovation, integrating AI and machine learning to deliver personalized experiences and predictive maintenance. The trend toward seamless interoperability among devices and the proliferation of smartphone-controlled applications are enhancing user engagement. In addition, the market benefits from supportive government policies promoting energy-efficient solutions and the rapid expansion of smart infrastructure in emerging economies. However, concerns about data privacy and high initial costs may present challenges, though declining prices and enhanced cybersecurity measures are expected to mitigate these barriers and sustain market momentum.
The geographical analysis of the Smart Home Appliances Market highlights significant growth across North America, Europe, and Asia Pacific, with these regions serving as the primary hubs for technological innovation and product adoption. North America and Europe benefit from established infrastructure and a strong consumer appetite for connected home solutions, while Asia Pacific shows rapid expansion driven by urbanization and rising disposable incomes, especially in countries like China, Japan, and South Korea. Leading players such as Whirlpool Corporation, LG Electronics, and Samsung Electronics Co. Ltd focus on product innovation, smart integration, and strategic partnerships to strengthen their positions in these competitive regions. Haier Group also plays a pivotal role, leveraging its strong presence in Asia and expanding global footprint to cater to diverse consumer needs. Together, these companies shape the market landscape by offering a broad portfolio of advanced, connected appliances and driving technological advancements.Top of Form
Market Insights
- The Smart Home Appliances Market reached USD 61.73 billion in 2024 and is expected to grow to USD 129.24 billion by 2032, at a CAGR of 9.01%.
- Rising consumer demand for convenience, connectivity, and energy-efficient living is driving rapid adoption of smart home appliances.
- Integration of artificial intelligence, IoT, and voice assistant technologies is shaping product innovation and creating seamless user experiences.
- Leading companies such as Whirlpool Corporation, LG Electronics, Samsung Electronics Co. Ltd, and Haier Group are focusing on expanding product portfolios and investing in research and development to strengthen their competitive edge.
- High initial costs, concerns over data privacy, and cybersecurity risks are key restraints that could slow the pace of market growth in certain segments.
- Asia Pacific, North America, and Europe represent the most dynamic regions, with Asia Pacific experiencing the fastest expansion due to urbanization, growing middle-class populations, and government-backed smart city initiatives.
- The market shows a trend toward interoperability, premiumization, and sustainability, with brands prioritizing eco-friendly materials, energy management features, and personalized user experiences to meet evolving consumer preferences.
Market Drivers
Growing Consumer Demand for Convenience and Connected Living Consumers are showing an increasing preference for convenience and seamless connectivity in their homes, which drives significant demand for smart home appliances. The market benefits from evolving lifestyles, where individuals seek solutions that simplify daily routines and improve efficiency. With the integration of voice assistants and remote control features, consumers enjoy easier management of household tasks. The Smart Home Appliances Market leverages this shift by offering advanced appliances that align with modern expectations for comfort and automation. Features such as scheduled operations, real-time monitoring, and personalized settings make these products attractive. Brands focusing on intuitive design and user-friendly interfaces are gaining wider acceptance among tech-savvy homeowners. The growing popularity of home automation platforms continues to reinforce market expansion.
- For instance, according to the Consumer Technology Association, over 69 million U.S. households use at least one smart home device.
Advancements in IoT and Artificial Intelligence Integration
Innovations in IoT and artificial intelligence are playing a pivotal role in shaping the Smart Home Appliances Market. Manufacturers have adopted smart sensors and connectivity features that allow appliances to adapt to user habits and optimize energy consumption. AI-driven predictive maintenance and personalized recommendations enhance product value and customer loyalty. Smart appliances can analyze data, adjust performance based on real-time feedback, and even anticipate user needs. Integration with home ecosystems such as smart speakers and mobile applications supports interoperability among devices, improving the overall user experience. Investments in R&D for smarter algorithms and adaptive technologies contribute to the sector’s growth. The rapid development of AI-enabled features is transforming expectations for home convenience.
- For instance, AI-driven predictive maintenance in smart appliances has reduced breakdown rates by up to 30%, according to industry reports.
Supportive Government Policies and Sustainability Initiatives
Government initiatives aimed at promoting energy efficiency and sustainable living are encouraging adoption of smart home appliances. Regulatory standards for energy conservation push manufacturers to design eco-friendly products. Incentives such as rebates and tax credits make it more appealing for consumers to invest in advanced appliances. The Smart Home Appliances Market benefits from growing awareness around sustainability, as buyers consider long-term cost savings and environmental impact. Manufacturers highlight energy-efficient ratings and sustainable materials in their product lines. Public and private partnerships focusing on smart city development and green infrastructure further stimulate market demand. Policies prioritizing reduced energy consumption drive innovation within the sector.
Expanding Urbanization and Growth in Emerging Economies
Rapid urbanization and rising disposable incomes in emerging markets contribute significantly to the Smart Home Appliances Market. Urban centers often adopt new technologies faster, creating a fertile environment for the deployment of smart solutions. New residential projects and smart city initiatives accelerate the penetration of advanced appliances. It caters to an expanding base of middle-class consumers seeking convenience, status, and efficiency. Availability of high-speed internet and mobile connectivity facilitates the integration of smart technologies in daily life. Retailers and manufacturers focus on tailoring product offerings for different income segments to increase accessibility. Growth in construction and modernization projects further supports market expansion.
Market Trends
Rising Integration of AI and Voice Assistants Across Devices
Artificial intelligence and voice assistants are increasingly present in smart home appliances, shaping a major trend within the industry. The Smart Home Appliances Market now features products with advanced voice control and adaptive learning capabilities, enabling users to operate appliances with simple commands. Manufacturers incorporate AI to enhance personalization, automate routines, and support energy savings. Consumers now expect refrigerators, washing machines, and other devices to learn their habits and provide proactive service alerts. Seamless interaction between appliances and digital assistants creates a more cohesive smart home environment. It positions AI-driven solutions at the center of innovation and product differentiation. The growing reliance on these intelligent systems reflects shifting consumer expectations for convenience and connectivity.
- For instance, voice-controlled smart appliances now account for over 40% of connected home devices, according to industry surveys.
Proliferation of Interoperable and Connected Home Ecosystems
Homeowners are seeking unified control over their household devices, leading to a strong trend toward interoperable and connected smart home ecosystems. The Smart Home Appliances Market responds with solutions that support multiple communication protocols and centralized control platforms. Appliances from different brands are now more likely to integrate within a single ecosystem, reducing fragmentation and enhancing user experience. Companies focus on compatibility with leading smart home hubs and applications to increase product appeal. It reduces barriers to entry for new users and simplifies device management for existing customers. Efforts to standardize connectivity drive higher adoption rates across diverse markets. This movement toward ecosystem integration is redefining the home appliance landscape.
For instance, over 75% of smart home users prefer devices that integrate seamlessly with existing home automation systems, according to market research.Focus on Energy Efficiency and Sustainable Features
Manufacturers are prioritizing sustainability by incorporating energy-efficient technologies and eco-friendly materials into new product designs. The Smart Home Appliances Market places emphasis on appliances that monitor and optimize energy use, helping households lower their utility costs. Smart sensors and real-time consumption tracking allow users to make informed decisions about appliance usage. Energy ratings and green certifications influence purchasing decisions for environmentally conscious consumers. It supports broader global initiatives aimed at reducing carbon footprints and promoting responsible consumption. Brands that position their products as sustainable solutions gain a competitive edge. Heightened focus on sustainability is becoming a core element of product development and marketing.
Growth of Premiumization and Personalized Experiences
Consumers are increasingly willing to invest in high-end smart home appliances that offer tailored experiences and advanced features. The Smart Home Appliances Market sees rising demand for customizable options, premium materials, and unique design aesthetics. Manufacturers respond with products that enable individualized settings, multi-user profiles, and integration with lifestyle applications. Technology-driven personalization, such as automatic recipe suggestions or predictive maintenance alerts, elevates the overall value proposition. It aligns with a broader trend of consumers seeking differentiated experiences within their homes. Premiumization drives brand loyalty and positions companies to capture higher margins. The shift toward personalized, high-value offerings continues to shape industry growth.
Market Challenges Analysis
Concerns Over Data Privacy and Cybersecurity Risks
Data privacy and cybersecurity remain critical challenges for the Smart Home Appliances Market, with consumers expressing concern about the safety of personal information. Connected devices can become targets for cyberattacks, exposing sensitive user data and compromising household security. The integration of IoT and cloud-based platforms increases the risk of unauthorized access and potential data breaches. It forces manufacturers to invest heavily in robust encryption, regular software updates, and advanced authentication protocols. Many consumers hesitate to adopt new technologies due to perceived vulnerabilities. Regulatory scrutiny over data protection continues to intensify, requiring compliance with evolving international standards. Building trust through transparency and strong security features is essential for sustainable market growth.
- For instance, cybersecurity reports indicate that smart home devices experience an average of 12,000 hacking attempts per household annually.
High Initial Costs and Compatibility Issues with Legacy Systems
The Smart Home Appliances Market faces obstacles related to high initial investment costs and compatibility with existing home infrastructure. Many consumers consider smart appliances to be premium products, placing them out of reach for cost-sensitive segments. Upgrading or replacing older devices and integrating them with new technologies often involves additional expenses and technical complexities. It may discourage widespread adoption, especially in emerging markets or regions with lower disposable incomes. Compatibility challenges also arise when connecting devices from different manufacturers or integrating with outdated wiring and networks. Standardization efforts are still ongoing, and the lack of seamless interoperability slows market expansion. Addressing these challenges will require ongoing industry collaboration and innovation.
Market Opportunities
Expanding Adoption in Emerging Markets and Urban Centers
Emerging markets and rapidly urbanizing regions offer significant growth opportunities for the Smart Home Appliances Market. Rising disposable incomes, increasing internet penetration, and infrastructure improvements create favorable conditions for smart appliance adoption. Urban centers tend to embrace new technologies more quickly, driving higher demand for automated and connected solutions. The market can target first-time buyers in these regions by developing affordable, entry-level product lines. It benefits from government support for smart city initiatives and investments in digital infrastructure. Companies that localize features and design products for diverse cultural preferences stand to gain market share. Accelerated urban development and modernization projects will continue to support long-term market expansion.
Innovations in Energy Efficiency and Sustainable Product Design
Growing consumer awareness of sustainability and energy conservation presents valuable opportunities for manufacturers to differentiate their offerings. The Smart Home Appliances Market stands to benefit by introducing products with advanced energy-saving features, real-time consumption monitoring, and eco-friendly materials. Governments and regulatory agencies increasingly promote green standards, creating incentives for both consumers and producers. It allows companies to align with global sustainability goals and strengthen their brand reputation. Product lines with smart energy management, water-saving technologies, and recyclable components attract environmentally conscious buyers. Manufacturers who lead in sustainable innovation will be well positioned to capture new customer segments. Ongoing R&D investment in this area can unlock further competitive advantages.
Market Segmentation Analysis:
By Product:
The Smart Home Appliances Market demonstrates a diverse product landscape, with distinct segments driving overall growth and innovation. Among product segments, smart washing machines account for a substantial share due to rising consumer demand for convenience and automation in laundry care. It enables users to control cycles remotely, optimize energy and water use, and receive maintenance alerts. The market for smart air purifiers is expanding rapidly as urbanization and pollution concerns prompt households to prioritize indoor air quality. Consumers value features such as real-time air monitoring, app connectivity, and advanced filtration technologies. Smart TVs represent another high-revenue segment, supported by increased content streaming, integration with voice assistants, and seamless connectivity to other smart devices within the home. The “Others” category encompasses a range of connected products such as smart refrigerators, ovens, and lighting, each contributing to the overall ecosystem of automated living.
By Distribution Channel:
The Smart Home Appliances Market reflects evolving consumer preferences for purchasing methods. Online channels capture a growing revenue share as consumers seek convenience, wider product selection, and access to detailed product reviews. E-commerce platforms and direct-to-consumer brand websites facilitate easy comparison and often provide promotional offers, making online purchasing attractive for tech-savvy buyers. Offline channels, including specialty stores and large-format retail outlets, maintain relevance by offering hands-on experience, personal consultations, and immediate product availability. It appeals to customers who prefer in-person interactions and want to evaluate product quality before purchase. Hybrid retail strategies, such as integrating online platforms with in-store experiences, are becoming more prominent, meeting the needs of diverse consumer groups.
Segments:
Based on Product:
- Smart Washing Machines
- Smart Air Purifiers
- Smart TV
- Others
Based on Distribution Channel:
- Online
- Offline
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Smart Home Appliances Market
North America Smart Home Appliances Market grew from USD 11.56 billion in 2018 to USD 19.35 billion in 2024 and is projected to reach USD 40.67 billion by 2032, reflecting a compound annual growth rate (CAGR) of 9.1%. North America is holding a 31% market share. The United States and Canada drive regional demand, supported by high technology adoption, established smart home infrastructure, and a strong presence of leading global brands. The region sees rising consumer preference for connected living, IoT integration, and premium product offerings. Regulatory support for energy-efficient appliances further stimulates market expansion. E-commerce platforms and large retail chains play a significant role in product accessibility. Key players invest in R&D to maintain competitiveness in this mature market.
Europe Smart Home Appliances Market
Europe Smart Home Appliances Market grew from USD 7.82 billion in 2018 to USD 12.65 billion in 2024 and is projected to reach USD 24.42 billion by 2032, with a CAGR of 7.9%. Europe accounts for a 19% market share. Countries such as Germany, the United Kingdom, and France are leading in adoption, driven by consumer interest in energy conservation, government incentives, and a strong regulatory focus on sustainability. The region features a robust ecosystem of manufacturers and distributors, with consumers valuing both product design and eco-friendly features. Smart home appliance penetration in Western Europe remains high, while Central and Eastern Europe show steady growth. Demand for integrated solutions continues to rise. Partnerships between technology companies and utility providers support further adoption.
Asia Pacific Smart Home Appliances Market
Asia Pacific Smart Home Appliances Market grew from USD 14.33 billion in 2018 to USD 25.35 billion in 2024 and is projected to reach USD 56.64 billion by 2032, achieving the highest CAGR of 9.9%. Asia Pacific is holding a 44% market share. China, Japan, and South Korea represent the largest country markets, benefiting from rapid urbanization, growing middle-class populations, and government-backed smart city initiatives. It attracts global manufacturers and local startups focused on affordable and innovative products. Rising internet penetration and mobile connectivity drive online sales. India is emerging as a high-growth market with increasing disposable income and modernization of housing. The region remains a hub for product innovation and manufacturing.
Latin America Smart Home Appliances Market
Latin America Smart Home Appliances Market grew from USD 1.23 billion in 2018 to USD 2.06 billion in 2024 and is projected to reach USD 3.61 billion by 2032, at a CAGR of 6.6%. Latin America accounts for a 3% market share. Brazil and Mexico are the key markets, supported by expanding urban centers and rising consumer awareness of smart technology benefits. Economic growth and investments in smart infrastructure support gradual adoption. Retail partnerships and online channels increase market accessibility. Local brands are gaining ground, responding to the demand for cost-effective solutions. Distribution challenges and economic volatility may impact market momentum.
Middle East Smart Home Appliances Market
Middle East Smart Home Appliances Market grew from USD 0.88 billion in 2018 to USD 1.35 billion in 2024 and is projected to reach USD 2.30 billion by 2032, recording a CAGR of 6.3%. The Middle East is holding a 2% market share. The United Arab Emirates and Saudi Arabia lead regional adoption, supported by luxury real estate development and a focus on smart city projects. High internet penetration and demand for premium appliances drive market growth. Regional consumers favor technologically advanced products with strong design appeal. International brands dominate, but local innovation is increasing. Challenges include fragmented distribution and variable consumer awareness.
Africa Smart Home Appliances Market
Africa Smart Home Appliances Market grew from USD 0.52 billion in 2018 to USD 0.98 billion in 2024 and is projected to reach USD 1.60 billion by 2032, reflecting a CAGR of 5.6%. Africa accounts for a 1% market share. South Africa, Nigeria, and Kenya serve as leading country markets, benefitting from urbanization and improving digital infrastructure. It presents opportunities for affordable and entry-level smart appliances tailored to local needs. Growth remains gradual due to price sensitivity and limited access to advanced technology in some regions. The market relies on mobile connectivity and emerging e-commerce platforms. Strategic partnerships with local distributors can help accelerate adoption.
Key Player Analysis
- Whirlpool Corporation
- LG Electronics
- Haier Group
- Samsung Electronics Co. Ltd
- Panasonic Corporation
- BSH Hausgeräte GmbH
- Electrolux AB
- Koninklijke Philips N.V
- GE Appliances
- Xiaomi Corporation
Competitive Analysis
The competitive landscape of the Smart Home Appliances Market features prominent global players including Whirlpool Corporation, LG Electronics, Samsung Electronics Co. Ltd, Haier Group, Panasonic Corporation, BSH Hausgeräte GmbH, Electrolux AB, Koninklijke Philips N.V, GE Appliances, and Xiaomi Corporation. These companies maintain their leadership through extensive investment in research and development, continuously introducing innovative products with advanced connectivity, artificial intelligence, and IoT integration. They focus on expanding their product portfolios to cover a wide range of smart appliances, from washing machines and refrigerators to air purifiers and televisions, meeting diverse consumer needs. Firms prioritize user-friendly interfaces, personalized experiences, and enhanced security features to differentiate their offerings and build customer loyalty. Strategic alliances, partnerships, and mergers help companies expand their reach into emerging markets and adapt quickly to changing technological trends. Brands compete not only on product innovation but also on after-sales service, distribution networks, and brand reputation. This dynamic environment encourages agility and responsiveness, driving the continuous evolution of smart home solutions and reinforcing market competitiveness.
Recent Developments
- In June 2023, GE Profile™ launched the UltraFast Combo, an all-in-one laundry solution that utilizes ventless heat pump technology. The new combination of washer and dryer eliminates the laborious task of transferring the load from the washer to the dryer.
- In June 2023, SmartThings announced new features for SmartThings Energy. The upgrades encourage individuals to take action on their energy consumption, save money, and gain incentives while contributing to a more sustainable future.
- In April 2023, Samsung Electronics Co., Ltd. announced SmartThings Station, an affordable smart home hub and fast charging pad. It offers users to automate different aspects of their home environment with quick setup and compatibility with a wide range of smart home products.
- In January 2023, the Home Connectivity Alliance (HCA) announced the HCA 1.0 interface specification at the Consumer Electronics Show in Las Vegas. Through this specification, consumers will be able to connect any device with any app and pave the path for more energy-efficient solutions.
Market Concentration & Characteristics
The Smart Home Appliances Market displays a moderate to high level of concentration, with a few established global manufacturers holding significant market share. It features intense competition driven by technological innovation, rapid product launches, and strong brand loyalty. The market’s characteristics include a high rate of adoption of connected and energy-efficient products, growing integration with IoT platforms, and a continuous focus on user convenience and personalization. Companies differentiate themselves through advanced features, robust after-sales service, and the ability to offer seamless interoperability across multiple devices. The presence of a tech-savvy consumer base and supportive regulatory frameworks further accelerates innovation cycles. The market evolves rapidly, influenced by shifts in consumer preferences, urbanization trends, and the ongoing push for sustainable and eco-friendly solutions.
Report Coverage
The research report offers an in-depth analysis based on Product, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Smart Home Appliances Market is projected to grow significantly between 2025 and 2032, driven by increasing consumer demand for connected and energy-efficient devices.
- Integration of artificial intelligence and Internet of Things technologies is enhancing appliance functionality, enabling features like predictive maintenance and personalized user experiences.
- Smart appliances are increasingly being designed to optimize energy consumption, contributing to sustainability goals and reducing household energy costs.
- The adoption of universal standards like Matter is improving interoperability among devices from different manufacturers, simplifying user experience.
- The Asia Pacific region is expected to lead market growth due to rapid urbanization, rising disposable incomes, and increasing adoption of smart technologies.
- Consumer preferences are shifting towards appliances that offer remote control capabilities, voice assistant integration, and seamless connectivity with other smart home devices.
- Security and privacy concerns remain a challenge, prompting manufacturers to invest in robust cybersecurity measures and transparent data handling practices.
- The market is witnessing a trend towards multifunctional appliances that combine various features, such as refrigerators with built-in touchscreens and recipe suggestions.
- Offline retail channels continue to play a significant role in consumer purchases, offering hands-on experience and personalized customer service.
- Continuous innovation and strategic partnerships among technology companies are expected to drive the development of more advanced and user-friendly smart home appliances.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Integration of IoT and Artificial Intelligence
The adoption of IoT and AI technologies enables smart home appliances to offer predictive maintenance, adaptive learning, and seamless connectivity, enhancing user convenience and driving market growth.
Urbanization and Rising Disposable Incomes
Rapid urbanization and increasing middle-class populations, especially in Asia Pacific, are boosting demand for smart appliances as consumers seek modern, efficient, and connected home solutions.
Government Policies and Sustainability Initiatives
Supportive regulations and incentives for energy-efficient appliances, along with growing consumer awareness of sustainability, are encouraging both manufacturers and consumers to adopt smart, eco-friendly products.
Proliferation of Interoperable Ecosystems
The trend toward device interoperability and universal standards like Matter is making it easier for consumers to integrate multiple smart appliances, reducing barriers to adoption and expanding the market.
Growth of Online Retail and E-commerce
The increasing preference for online channels provides consumers with greater access to product information, reviews, and competitive pricing, accelerating the adoption of smart home appliances globally.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Smart Home Appliances Market?
What factors are driving the growth of the Smart Home Appliances Market?
What are the key segments within the Smart Home Appliances Market?
What are some challenges faced by the Smart Home Appliances Market?
Who are the major players in the Smart Home Appliances Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Smart Washing Machines
- 1.2.2 Smart Air Purifiers
- 1.2.3 Smart TV
- 1.2.4 Smart Refrigerators
- 1.2.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 61.73 billion → 2032: USD 129.24 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Smart Home Appliances Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Smart Home Appliances Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Smart Home Appliances Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Smart Home Appliances Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Smart Home Appliances Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Smart Home Appliances Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Smart Home Appliances Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Smart Home Appliances Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 61.73 billion → 2032: USD 129.24 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Smart Home Appliances Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Smart Washing Machines
- 12.3.7.2 Smart Air Purifiers
- 12.3.7.3 Smart TV
- 12.3.7.4 Smart Refrigerators
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 Segment Growth Comparison
- 12.5 Segment Attractiveness and Priority Matrix
Chapter 13 Global Smart Home Appliances Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Smart Home Appliances Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Smart Home Appliances Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Whirlpool Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 LG Electronics
- 17.4 Haier Group
- 17.5 Samsung Electronics Co. Ltd
- 17.6 Panasonic Corporation
- 17.7 BSH Hausgeräte GmbH
- 17.8 Electrolux AB
- 17.9 Koninklijke Philips N.V
- 17.10 GE Appliances
- 17.11 Xiaomi Corporation
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

