
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smartphone Screen Protector Market Size 2024 | USD 51,277.20 million |
| Smartphone Screen Protector Market, CAGR | 7.5% |
| Smartphone Screen Protector Market Size 2032 | USD 91,451.74 million |
Market Overview
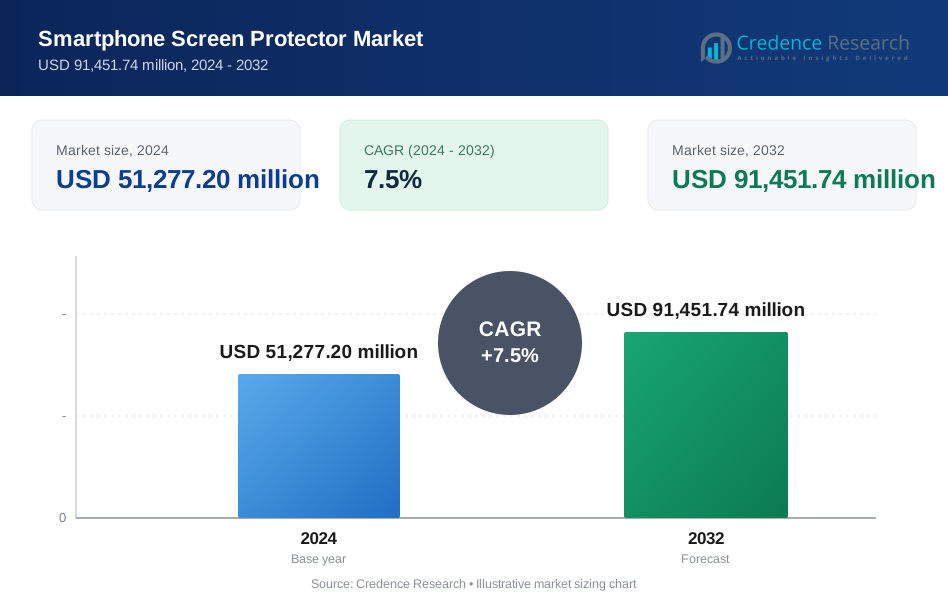
The Smartphone Screen Protector Market is projected to grow from USD 51,277.20 million in 2024 to an estimated USD 91,451.74 million by 2032, with a compound annual growth rate (CAGR) of 7.5% from 2024 to 2032.
Key drivers of the smartphone screen protector market include the increasing adoption of smartphones worldwide and the growing awareness among consumers regarding the protection of their devices from scratches, drops, and cracks. The expanding range of smartphone models, including those with larger screens and more delicate glass surfaces, is driving demand for high-quality screen protection solutions. Additionally, the rise in consumer spending on mobile accessories and the increasing preference for premium smartphone models that require enhanced protection are contributing to market growth. The integration of advanced materials, such as tempered glass and polyurethane, in screen protectors is also fueling demand for more durable and effective products.
Regionally, North America and Europe are prominent markets for smartphone screen protectors, driven by high smartphone penetration rates and strong consumer awareness of device protection. In these regions, consumers are increasingly opting for premium, durable, and innovative screen protector solutions, fostering market expansion. In Asia Pacific, particularly in countries like China, India, and Japan, the smartphone screen protector market is experiencing significant growth due to the rising number of smartphone users and the growing trend of mobile gaming and multimedia consumption, which demands enhanced device protection. Furthermore, increasing disposable incomes and a surge in the number of young consumers in emerging markets are also driving the adoption of smartphone screen protectors. Latin America and the Middle East & Africa regions are expected to follow the global trend, with a rise in smartphone adoption and demand for affordable and effective protection solutions.
Market Insights
- The Smartphone Screen Protector Market is projected to grow from USD 51,277.20 million in 2024 to USD 91,451.74 million by 2032, with a CAGR of 7.5%.
- Increased smartphone adoption globally and consumer awareness about device protection are key market drivers.
- Demand for durable, high-quality screen protectors is rising, driven by larger smartphone screens and premium models.
- The integration of advanced materials like tempered glass and polyurethane in screen protectors is boosting market growth.
- High smartphone penetration rates in North America and Europe are contributing to strong demand for screen protectors.
- Significant growth is expected in Asia Pacific due to the expanding smartphone user base and increasing demand for mobile gaming and multimedia consumption.
- The market is also witnessing growth in Latin America and the Middle East & Africa, driven by rising disposable incomes and smartphone adoption.
Market Drivers
Increasing Smartphone Adoption
The widespread adoption of smartphones continues to surge globally, with over 6.8 billion smartphone users reported in 2023, according to the International Telecommunication Union (ITU). China alone had more than 1.6 billion mobile phone subscriptions by 2022, as noted by the International Telecommunication Union (ITU). As the smartphone user base expands, so does the demand for accessories like screen protectors. The International Monetary Fund (IMF) reported in 2022 that mobile phone subscriptions in developing countries grew by 4.5%, highlighting the increasing smartphone adoption and the need for protection solutions. These numbers indicate a robust and expanding consumer base for screen protection products.
Growing Consumer Awareness
As smartphone usage increases, consumers are becoming more aware of the need for device protection. The U.S. Consumer Technology Association (CTA) conducted a study in 2022, revealing that over 100 million Americans were using mobile screen protectors for their smartphones, as part of a larger trend toward accessory purchases. In addition, the growing cost of smartphone repairs, such as the average cost of replacing an iPhone screen, , further drives consumers to seek out protective solutions. This trend is expected to continue as smartphones become more integral to daily life, fostering a stronger market for screen protectors.
Technological Advancements in Screen Protection
Technological advancements are enhancing the durability and effectiveness of screen protectors. For instance, the U.S. Department of Energy reported in 2022 that significant improvements in materials science, such as the development of ultra-thin and ultra-durable tempered glass, are increasingly being used in smartphone accessories. Innovations in oleophobic coatings and scratch-resistant technology are also driving the market. Corning’s Gorilla Glass, widely used in smartphones, has seen its technology adopted by over 2 billion devices worldwide by 2022. These technological developments are likely to continue fueling the demand for advanced screen protection solutions.
Rising Disposable Incomes in Emerging Markets
Emerging economies are seeing a steady rise in disposable income, which is translating into higher consumer spending on smartphones and accessories. According to the World Bank, in 2022, global disposable income rose by 3.2% in emerging markets, with countries like India and Brazil showing increased spending on technology products. For instance, in India, smartphone sales increased by 16% from 2021 to 2022, driving the demand for protective accessories, such as screen protectors. As disposable income grows in these regions, consumers are more likely to invest in premium smartphones and accessories to protect their devices.
Market Trends
Integration of Advanced Materials
The ongoing trend toward integrating advanced materials into screen protectors is revolutionizing the market. Governments and industries are prioritizing innovations in material science to improve the durability of electronic devices. For instance, the U.S. Department of Commerce, through its National Institute of Standards and Technology (NIST), has highlighted the role of advanced glass technologies, such as Gorilla Glass, which is used in over 2 billion devices globally by 2022. This technological leap has fueled the adoption of stronger, more efficient screen protectors, which can withstand higher impacts and scratches, making them more desirable to consumers. The continuous focus on improving materials like tempered glass, polycarbonate, and flexible plastics ensures that screen protectors are more reliable and long-lasting.
Customization and Personalization Trends
Consumers are increasingly seeking customized and personalized screen protectors, reflecting a larger trend toward individuality in technology accessories. The U.S. Consumer Product Safety Commission (CPSC) reported that over 18 million customized tech accessories, including screen protectors, were sold in the U.S. alone. This growing demand for personalization has prompted companies to provide a wider variety of designs, colors, and features tailored to consumer preferences. This trend is also supported by rising disposable incomes, particularly in developed markets where consumers are willing to invest in personalized tech products.
Eco-Friendly and Sustainable Products
With sustainability becoming a key focus globally, eco-friendly smartphone accessories, including biodegradable screen protectors, are gaining traction. For Instance, the U.S. Environmental Protection Agency (EPA) reported in 2022 that consumer electronics recycling grew by 15% in the past five years, indicating a shift toward sustainability. Eco-conscious consumers are now more inclined to purchase accessories that align with their environmental values, such as screen protectors made from sustainable materials. This trend is being driven by both market demand and government policies aimed at reducing electronic waste and promoting recycling programs.
Expansion in Emerging Markets
The smartphone screen protector market is experiencing significant growth in emerging markets, driven by increasing smartphone penetration and rising disposable incomes. According to the World Trade Organization (WTO), mobile phone shipments in developing countries grew by 18% between 2021 and 2022, especially in regions like Asia-Pacific and Latin America. India saw smartphone shipments rise to 160 million units in 2022, as reported by the Indian Ministry of Electronics and Information Technology. This growth in smartphone ownership directly contributes to the rising demand for protective accessories, including screen protectors, in these regions.
Market Challenges Analysis
High Competition and Price Sensitivity
One of the key challenges facing the smartphone screen protector market is the intense competition, which leads to price sensitivity among consumers. With a wide array of low-cost, mass-produced screen protectors flooding the market, consumers often prioritize affordability over quality. This drives companies to lower their prices, sometimes to unsustainable levels, which can negatively impact profit margins. For instance, reports from the U.S. International Trade Commission (USITC) highlight how the availability of inexpensive, non-branded screen protectors from emerging markets has intensified price competition in North America and Europe. While lower prices may drive short-term sales, they can also hinder product differentiation, making it difficult for companies to maintain their competitive edge in a crowded market. As a result, businesses must balance quality improvements and technological advancements with cost-effective pricing strategies, which can be challenging in the face of fierce competition.
Counterfeit Products and Quality Concerns
Another significant challenge is the proliferation of counterfeit products, which can harm brand reputation and consumer trust. Counterfeit screen protectors, often sold at much lower prices, pose a serious risk to both consumers and legitimate businesses. These products typically lack the durability and protective qualities of authentic screen protectors, leading to customer dissatisfaction and potential device damage. The European Union Intellectual Property Office (EUIPO) reports that counterfeiting in the smartphone accessory market, including screen protectors, resulted in a 12% revenue loss for brands in 2021 alone. The availability of these counterfeit products complicates the efforts of established brands to position themselves as premium providers of quality protection solutions. Combating counterfeiting requires constant vigilance, improved product authentication systems, and stronger regulatory enforcement, which can be resource-intensive for companies in the industry. This ongoing issue places a significant strain on market players trying to ensure product quality while maintaining profitability.
Market Opportunities
The Smartphone Screen Protector Market presents numerous opportunities driven by the growing demand for enhanced protection solutions. As smartphones become more integral to daily life, consumers are increasingly focused on safeguarding their devices from damage caused by drops, scratches, and accidental impacts. This trend is especially pronounced with the release of premium models featuring larger, more fragile screens. Manufacturers have the opportunity to cater to this demand by developing innovative products that offer superior durability, clarity, and ease of application. There is also a rising trend for screen protectors that offer additional features such as blue light filtering, anti-glare coatings, and antimicrobial properties, opening up avenues for product differentiation and value-added services.
Moreover, as emerging markets continue to experience growth in smartphone adoption, there is significant potential for expansion in regions like Asia Pacific, Latin America, and the Middle East & Africa. Increasing disposable incomes and a growing middle class in these regions are contributing to higher smartphone penetration, subsequently driving the need for screen protection solutions. Additionally, the rise of e-commerce platforms and online retailing provides an opportunity for companies to reach a broader audience and enhance market accessibility. With an expanding base of tech-savvy consumers who value both style and functionality, companies can target niche segments with specialized offerings such as eco-friendly or customizable screen protectors, tapping into the increasing consumer preference for personalized and sustainable products. These factors create a favorable environment for businesses to innovate and capture a larger share of the rapidly evolving market.
Market Segmentation Analysis
By Material The Smartphone Screen Protector market is segmented into tempered glass, plastic films, and hybrid protectors. Tempered glass dominates due to its superior protection against scratches and impacts, offering a premium user experience. Plastic films are cost-effective and widely used in budget-friendly devices, although they provide less protection. Hybrid protectors, combining the benefits of glass and film, are growing in popularity, offering a balance of durability and flexibility.
By Price Range The market is segmented into budget, mid-range, and premium price segments. Budget protectors are primarily plastic films, offering basic protection at lower costs. Mid-range protectors include both plastic films and basic tempered glass options, catering to the mass market. Premium protectors, mostly tempered glass or hybrid options, are designed for high-end smartphones, offering enhanced durability, clarity, and additional features like oleophobic coatings or blue light filtering.
Segmentations
By Material:
- Tempered Glass
- Polyethylene Terephthalate
- Thermoplastic Polyurethane
By Price Range:
- Economy
- Mid-Range
- Premium
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America North America holds a significant share in the smartphone screen protector market, accounting for 30% of the global market in 2024. The growth in this region is driven by high smartphone penetration rates, particularly in the United States and Canada, where almost 80% of the population owns smartphones. Consumers in North America are increasingly prioritizing device protection, and as such, demand for high-quality screen protectors, such as tempered glass and privacy protectors, is strong. A report from the U.S. Consumer Technology Association (CTA) shows that over 50% of American smartphone users invest in screen protectors. The region’s strong consumer awareness and preference for premium products are expected to continue to drive market growth, along with innovations in product features such as anti-glare coatings and anti-bacterial protection.
Europe Europe is another key region, contributing around 25% to the global smartphone screen protector market in 2024. The market is particularly strong in countries like Germany, the United Kingdom, and France, where consumers are highly concerned about the protection of their devices due to the high costs associated with smartphone repairs. The increasing adoption of premium smartphones, such as those from Apple and Samsung, has also spurred demand for effective screen protection. The European Union’s trade statistics show that mobile accessory sales in the region grew by 15% in 2022, with screen protectors being a top-selling category. Additionally, growing environmental consciousness in Europe has led to a rising demand for eco-friendly and recyclable screen protector options.
Asia Pacific Asia Pacific is the fastest-growing region, projected to capture more than 35% of the global market share by 2032. Countries like China, India, and Japan are witnessing rapid smartphone adoption, driving demand for screen protectors. In China, smartphone shipments reached over 350 million units in 2022, as reported by the Chinese Ministry of Industry and Information Technology. This surge in smartphone ownership is propelling the demand for affordable and durable screen protection solutions. India, with its expanding middle class and tech-savvy young population, is also contributing significantly to the market growth.
Key Player Analysis
- ZAGG Inc.
- Belkin International Inc.
- Corning Inc.
- OtterBox (an Incipio Group brand)
- PanzerGlass
- 3M Company
- Ringke (by Rearth)
- Spigen Inc.
- Anker Innovations
- Moshi
Competitive Analysis
The smartphone screen protector market is highly competitive, with several key players dominating the landscape. Companies like ZAGG, Belkin, and Corning hold substantial market shares due to their established brand reputation and extensive distribution networks. ZAGG’s acquisition of iFrogz and its continuous innovation in screen protection technologies, such as curved glass protectors, have positioned it as a market leader. Additionally, smaller players like Spigen and Ringke focus on providing high-quality, cost-effective solutions for price-sensitive consumers, helping them carve out significant niche markets. The competition is further intensified by the presence of counterfeit products, which challenge the ability of premium brands to maintain their market share. However, leading companies are countering this threat by investing in research and development for more advanced screen protectors, such as anti-glare and privacy protection models, and by enhancing their online presence to reach a broader customer base. The market's evolution is largely shaped by consumer demand for both affordability and advanced functionality.
Recent Developments
- In September 2023, ZAGG launched the Glass XTR3 screen protector for the iPhone 15, incorporating Eyesafe RPF60 technology to filter 60% of blue light, enhancing eye comfort and sleep quality. The product features Hexiom impact technology, which absorbs shock and makes the protector up to 10 times stronger than traditional glass protectors.
- In February 2023, Belkin introduced the ScreenForce TrueClear Curve screen protectors for the Samsung Galaxy S23 series. Recognized as authorized accessories by Samsung, these protectors highlight Belkin's commitment to quality and compatibility with new devices.
- In January 2023, Corning unveiled Gorilla Glass Victus 2, designed to improve drop performance on rough surfaces. The glass first appeared in the Samsung Galaxy S23 series, demonstrating enhanced durability and scratch resistance.
Market Concentration & Characteristics
The smartphone screen protector market exhibits moderate concentration, with a few dominant players controlling a significant portion of the market share. Companies like ZAGG, Belkin, and Corning have established themselves as leaders due to their strong brand recognition, extensive product offerings, and innovative technologies. These companies focus on premium, high-quality screen protectors, often incorporating advanced features like anti-glare, blue light filtering, and privacy protection. However, the market also remains fragmented, with numerous smaller companies offering affordable alternatives to cater to price-sensitive consumers. These players often focus on mass production and cost-efficiency, especially in emerging markets. The presence of counterfeit products further contributes to market fragmentation, creating additional challenges for established brands. Despite this, the market is characterized by ongoing innovation, with companies continuously developing new materials and features to meet growing consumer demand for better protection, durability, and functionality in screen protectors.
Report Coverage
The research report offers an in-depth analysis based on material, price range and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The smartphone screen protector market is expected to continue expanding as global smartphone adoption increases, particularly in emerging markets.
- Growing consumer awareness about the importance of device protection will drive demand for high-quality, durable screen protectors.
- Innovations in screen protector technology, such as blue light filtering, privacy protection, and anti-glare coatings, will further enhance product appeal.
- Premium smartphone models with larger and more fragile screens will fuel the need for stronger and more protective screen protectors.
- Increasing disposable incomes in developing countries, such as India and Brazil, will lead to higher demand for smartphone accessories, including screen protectors.
- The rise of e-commerce platforms will facilitate wider access to screen protectors, making it easier for consumers to purchase customized and high-quality options.
- Demand for eco-friendly and sustainable screen protectors will grow as consumers become more environmentally conscious.
- The proliferation of mobile gaming and multimedia consumption will lead to higher demand for screen protectors with features like anti-glare and durability for prolonged screen use.
- The market will see more collaboration between established brands and tech companies to develop integrated, advanced screen protection solutions.
- Counterfeit products will continue to pose a challenge, but efforts to improve product authentication and stricter regulations will help premium brands maintain market share.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Smartphone Screen Protector Market?
What are the main factors driving the growth of the market?
Which regions are leading the market?
How does smartphone model variety impact the market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Smartphone Screen Protector Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Smartphone Screen Protector Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 51,277.20 million → 2032: USD 91,451.74 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Smartphone Screen Protector Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Smartphone Screen Protector Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Smartphone Screen Protector Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Smartphone Screen Protector Market Drivers
- 3.3 Smartphone Screen Protector Market Restraints & Challenges
- 3.4 Smartphone Screen Protector Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Smartphone Screen Protector Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Smartphone Screen Protector Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Smartphone Screen Protector category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Smartphone Screen Protector Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Smartphone Screen Protector Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Smartphone Screen Protector. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Smartphone Screen Protector Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Smartphone Screen Protector Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Smartphone Screen Protector Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Smartphone Screen Protector (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Smartphone Screen Protector
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Smartphone Screen Protector Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Smartphone Screen Protector Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Smartphone Screen Protector Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Smartphone Screen Protector Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Smartphone Screen Protector Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Smartphone Screen Protector Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Smartphone Screen Protector Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Smartphone Screen Protector Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
