
Market Overview:
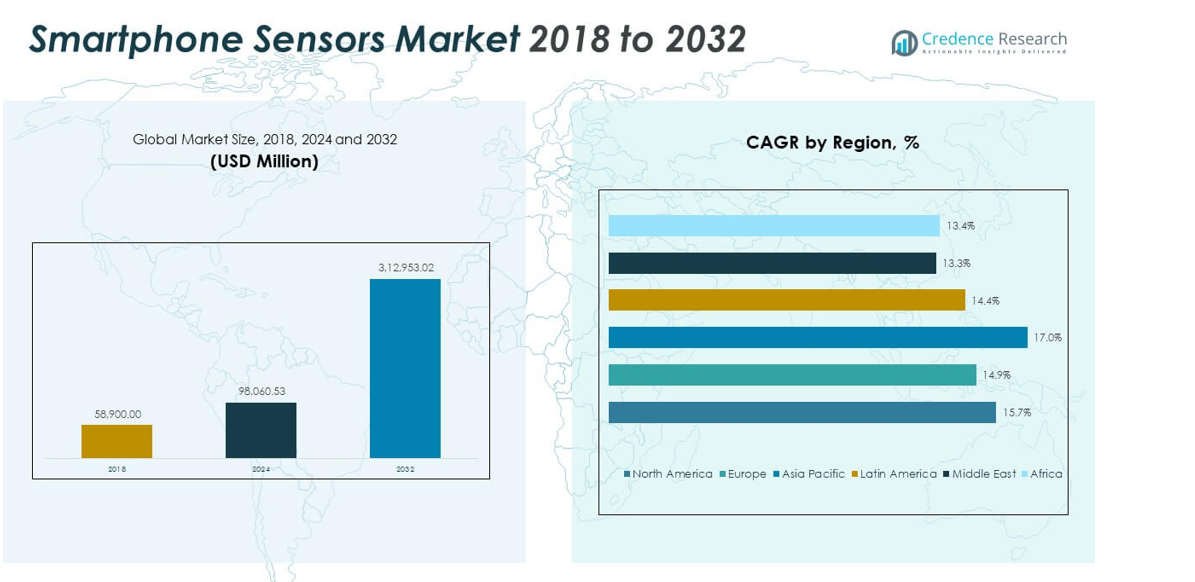
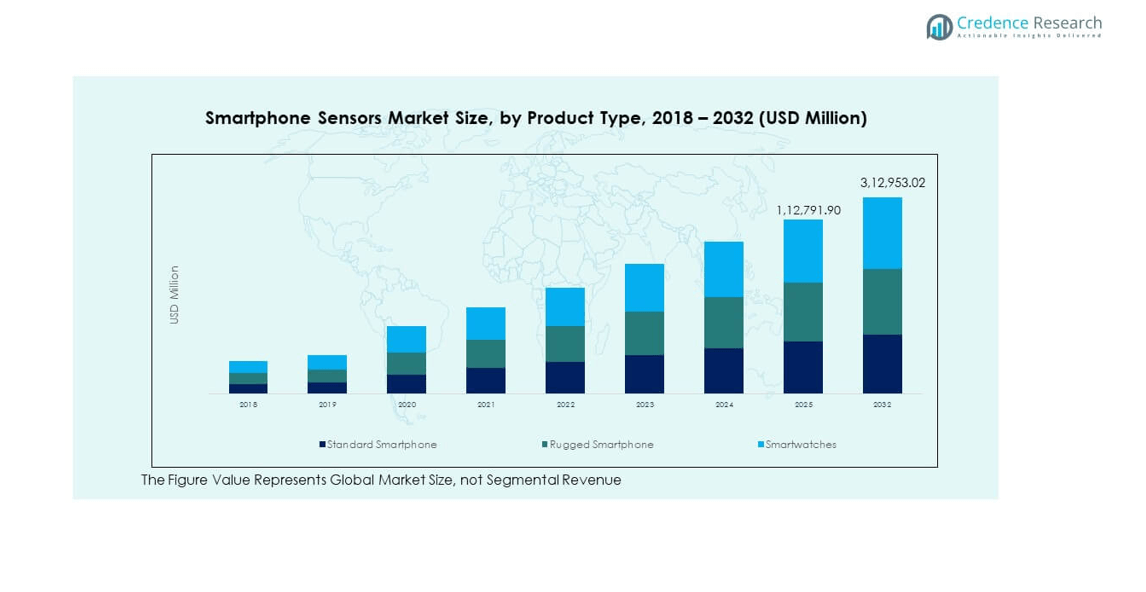
The Global Smartphone Sensors Market size was valued at USD 58,900.00 million in 2018 to USD 98,060.53 million in 2024 and is anticipated to reach USD 312,953.02 million by 2032, at a CAGR of 15.69% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smartphone Sensors Market Size 2024 | USD 98,060.53 million |
| Smartphone Sensors Market, CAGR | 15.69% |
| Smartphone Sensors Market Size 2032 | USD 312,953.02 million |
Growth stays strong due to rising interest in enhanced user experience features. Phone makers add better camera sensors, faster fingerprint modules, and precise motion units to support gaming and AR functions. AI-driven image processing needs high-quality sensors that deliver sharp input for faster computation. Battery-efficient components attract brands that want longer device life. Demand rises further as OEMs push new form factors like foldables that rely on advanced sensing units to manage display movement and device safety.
Regional expansion reflects wider smartphone adoption across major economies. Asia Pacific leads due to large-scale production hubs and strong consumer demand in China, India, and South Korea. North America holds a strong position with high premium device sales and early use of advanced features. Europe shows steady progress through strong replacement cycles and rising interest in secure sensors. Latin America and the Middle East & Africa emerge as growing markets driven by expanding 4G and 5G access and rising mid-range smartphone shipments.
Market Insights:
- The Global Smartphone Sensors Market was valued at USD 58,900.00 million in 2018, reached USD 98,060.53 million in 2024, and is projected to hit USD 312,953.02 million by 2032, growing at a CAGR of 15.69%, driven by rapid advances in imaging, biometrics, and motion-sensing technologies.
- Asia Pacific (28.38%), North America (35.36%), and Europe (25.48%) held the top three regional shares in 2024. North America leads through early adoption of premium devices, Europe benefits from strong replacement cycles, and Asia Pacific remains dominant due to massive production hubs and high consumer demand.
- Asia Pacific is the fastest-growing region, supported by its 0% CAGR and strong growth in China, India, and South Korea. Expanding 5G coverage, rising mid-range smartphone shipments, and large-scale OEM manufacturing reinforce its lead.
- Smartwatches accounted for the largest share in product segmentation, reflecting rising demand for health, fitness, and continuous monitoring capabilities across global consumer groups.
- Standard smartphones contributed the second-largest share, followed by rugged smartphones, supported by broader consumer adoption and wider integration of advanced imaging, security, and motion sensors across mainstream models.
Market Drivers:
Rising Demand for High-Performance Imaging Sensors
The Global Smartphone Sensors Market grows due to strong demand for advanced camera performance. Brands use larger sensors that capture more light during daily photography. AI tools improve output and require precise data from imaging modules. Multi-camera setups lift the need for wide, macro, and depth sensors. Premium phones include stronger optical features to support sharp videos. Mid-range phones adopt similar modules to attract value-focused buyers. Sensor makers improve low-light capability through better pixel design. Strong user interest in visual content keeps imaging demand steady.
- For instance, Sony’s IMX989 one-inch sensor captures 72% more light than a 1/1.3-inch unit, delivering higher clarity in low-light scenes.
Expansion of Biometric and Security Capabilities
Biometric sensors improve device safety and build user trust. Face unlock modules respond faster and work under varied lighting. Fingerprint units track small patterns on skin with high accuracy. Brands adopt under-display sensors that support sleek phone designs. Secure payment use cases push firms toward better authentication hardware. New identity rules in some regions increase the demand for strong biometrics. It drives steady upgrades across entry-level and flagship models. Growth stays firm as users expect secure access on every device.
- For instance, Apple Face ID uses a dot projector that maps over 30,000 infrared dots for precise 3D recognition. Fingerprint units track small patterns on skin with high accuracy.
Growth of Motion, Orientation, and Interaction Features
Motion sensors shape gaming, AR, and gesture-based functions in many phones. Gyroscopes guide smooth screen movement during video and game use. Accelerometers support activity tracking and daily movement capture. Proximity modules help manage screen behavior during calls. Ambient light sensors support smooth display adjustment in bright areas. Brands refine algorithms to use sensor data with greater precision. New interaction modes push firms to blend multiple sensors for faster response. Wider use cases lift overall demand for compact yet strong modules.
AI Integration and Efficient Power Management
AI functions depend on clean sensor inputs for fast processing. Phone makers adopt smarter components that lower energy demand. Better thermal design supports longer sensor life across heavy tasks. Efficient modules help users manage battery during camera and gaming use. It supports smoother performance during multi-app activity. Firms develop sensors that adjust power draw based on active features. New chipsets guide better coordination across sensor hardware. Demand increases as brands push AI-led improvements across device platforms.
Market Trends:
Rapid Shift Toward Multi-Sensor Fusion Systems
The Global Smartphone Sensors Market moves toward fusion systems that blend data from many units. Brands combine camera, gyro, and accelerometer inputs to improve accuracy. This setup guides better AR use and smoother mapping functions. Multi-sensor links support premium camera modes during daily content creation. Software tools merge signals to cut noise from motion-heavy scenes. Sensor fusion improves user safety during navigation. Firms upgrade modules that supply higher data rates. Growth stays firm as phones move toward smarter connected features.
- For instance, Google’s Pixel uses fused gyro-camera data for its Super Res Zoom system, enabling stable long-range images without optical zoom hardware.
Rising Adoption of Under-Display and Invisible Sensors
Under-display designs remove visible cutouts on modern phones. Fingerprint units hide below AMOLED layers while keeping response speed strong. Light and proximity modules shift under screens with compact builds. Firms explore ultrasonic units that work with wet or dusty fingers. Invisible layouts support edge-to-edge screens across new models. Better materials help sensors track signals through dense display glass. Camera makers test under-panel imaging for future flagship release. Clean design trends keep demand for hidden sensors high.
- For instance, Samsung’s ultrasonic in-display sensor captures 3D ridge patterns through glass using high-frequency sound waves. Light and proximity modules shift under screens with compact builds.
Growth of Environmental and Health Monitoring Sensors
Brands integrate sensors that track air quality and environmental change. Temperature units help flag abnormal device heat during high-load tasks. Some models test basic breath or air indicators for wellness apps. Advanced sensors monitor humidity inside sealed phone frames. Health platforms use motion and light modules for heart-related measures. Strong interest in wellness apps pushes early tests of compact biosensors. Integration of these tools expands feature sets in many phones. Long-term growth depends on accuracy and regulatory clarity.
Rising Use of 3D Sensing and Depth-Mapping Technologies
Depth sensors support secure face unlock and improved portrait imaging. Structured light modules guide precise mapping for AR tools. Time-of-flight units lift accuracy across short-range depth tasks. Gaming functions use 3D sensing for better spatial response. App developers rely on depth data to build new visual tools. Strong use in premium models drives wider adoption. It shapes future design across mid-range phones. The Global Smartphone Sensors Market benefits from steady demand for advanced depth tools.
Market Challenges Analysis:
High Cost Pressure and Complex Integration Needs
The Global Smartphone Sensors Market faces strong cost pressure across major segments. High-end sensors raise manufacturing budgets for many brands. Compact footprints complicate placement inside slim phone bodies. Engineers handle thermal limits during long camera or gaming tasks. Strong integration requires tight tuning across hardware and software. Suppliers adjust pricing to stay competitive during large-volume orders. Quality variation raises rework time for some modules. Firms invest in long testing cycles to avoid product failure.
Supply Chain Constraints and Rapid Technology Shifts
Supply chains struggle with fluctuating chip availability. Some materials remain limited during peak production seasons. Rapid sensor upgrades challenge firms that manage long design cycles. Vendors handle shifting safety rules around biometric and data-based units. Production delays affect mid-range phone launches during busy months. High reliance on a few sensor makers increases risk for global brands. Fast technology cycles trigger bigger R&D spending. Firms balance innovation with stable supply to support market growth.
Market Opportunities:
Expansion of AI-Driven Photography and AR Experiences
The Global Smartphone Sensors Market gains new openings through AI-led imaging. Better sensors help algorithms create lifelike photos across many scenes. AR games and filters push demand for accurate motion data. Firms invest in sensors that support low-noise output for night modes. Strong social media use boosts interest in creative imaging tools. Foldable devices unlock fresh camera layouts that need refined modules. Energy-efficient builds attract brands that target longer user sessions. Growth stays steady across premium and mid-range tiers.
Rising Need for Advanced Security and Ambient Intelligence
Secure apps lift demand for modern biometric systems across new phone lines. Under-display sensors unlock wider design freedom for brands. Privacy-focused regions push adoption of safer authentication tools. Smart home links need phones that sense motion and location with accuracy. New identity use cases lift the value of robust sensing platforms. Brands add ambient intelligence features that guide personalized response. Energy-smart components support safe use during long tasks. Wider digital adoption strengthens long-term opportunity across global markets.
Market Segmentation Analysis:
By Smartphone Type
The Global Smartphone Sensors Market expands through rising use across standard smartphones, rugged models, smartwatches, and other wearables. Standard smartphones hold the largest need for camera, biometric, and motion units due to high user demand. Rugged smartphones use stronger sensors that tolerate shock, heat, and pressure. Smartwatches depend on motion and biometric modules for fitness and wellness tracking. Other wearables adopt compact sensors for gesture control and continuous monitoring. It benefits from steady integration across lifestyle, industrial, and enterprise devices. Growth follows wider digital adoption across global markets.
- For instance, Apple’s iPhone uses a LiDAR scanner capable of measuring depth up to 5 meters for AR functions. Rugged smartphones use stronger sensors that tolerate shock, heat, and pressure.
By Price
Sensors vary across phones priced under USD 100, USD 100 to USD 300, USD 300 to USD 500, and above USD 500. High-end price segments adopt stronger camera, depth, and biometric sensors to support advanced features. Mid-range phones use improved modules that balance cost and performance. Entry-level phones integrate essential components to support basic imaging and safety needs. Models above USD 500 lead sensor innovation with better accuracy and power control. Brands upgrade modules to match user demand for smooth performance. It helps sensor makers gain wider placement across pricing tiers.
- For instance, Samsung’s ISOCELL GM2 powers many mid-range models with 48-megapixel output and Tetracell pixel-binning. Entry-level phones integrate essential components to support basic imaging and safety needs.
By Application
High-end applications rely on advanced camera units, precise biometrics, and strong motion sensors to support premium features. Mid-level devices adopt versatile modules that balance speed and accuracy. Low-end phones use essential components that maintain stable daily function. Rising interest in mobile imaging pushes strong demand across high-end and mid-level phones. Entry-level segments sustain volume growth in developing markets. It strengthens sensor adoption across varied performance groups.
Segmentation:
- By Smartphone Type
- Standard Smartphone
- Rugged Smartphone
- Smartwatches
- Other Wearables
- By Price
- USD 300 to USD 500
- USD 100 to USD 300
- Above USD 500
- Under USD 100
- By Application
- High-End
- Mid-Level
- Low-End
- By Country (Regional Sub-Segments)
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis:
North America
The North America Global Smartphone Sensors Market size was valued at USD 21,086.20 million in 2018 to USD 34,673.62 million in 2024 and is anticipated to reach USD 110,504.27 million by 2032, at a CAGR of 15.7% during the forecast period. Market share 2024: 35.36%. North America holds a strong position in the Global Smartphone Sensors Market due to high demand for premium smartphones. Users adopt devices with advanced imaging, biometric, and motion-sensing features. Brands release early upgrades that push stronger sensor performance. AI-led photography and gaming tools lift the need for accurate data capture. It benefits from strong innovation cycles driven by leading tech firms. Carrier-driven 5G expansion raises the need for advanced sensor integration. Enterprise mobility programs expand adoption across business users. Replacement cycles remain steady across the U.S. and Canada.
Europe
The Europe Global Smartphone Sensors Market size was valued at USD 15,608.50 million in 2018 to USD 24,983.14 million in 2024 and is anticipated to reach USD 75,344.27 million by 2032, at a CAGR of 14.9% during the forecast period. Market share 2024: 25.48%. Europe shows stable growth supported by strong consumer demand for reliable smartphone performance. Users prefer devices with secure biometric systems and advanced imaging modules. AI adoption improves camera quality across mid-range and premium phones. Strict data norms push brands to refine sensor reliability and safety. It gains traction through rising interest in AR-based applications. Growth remains firm across Germany, France, and the UK. Southern Europe shows steady recovery in smartphone shipments. Strong replacement demand supports long-term sensor adoption.
Asia Pacific
The Asia Pacific Global Smartphone Sensors Market size was valued at USD 16,079.70 million in 2018 to USD 27,834.07 million in 2024 and is anticipated to reach USD 97,109.57 million by 2032, at a CAGR of 17.0% during the forecast period. Market share 2024: 28.38%. Asia Pacific leads due to strong production hubs and massive smartphone consumption. China drives high-volume sensor demand across varied price segments. India shows fast growth supported by wider 4G and 5G adoption. South Korea and Japan push innovation through strong OEM ecosystems. It benefits from rapid upgrades in imaging, gaming, and AI features. Local brands use multi-sensor platforms to enhance user experience. Wearables expand faster across health-focused users. Rising mid-range segments support lasting regional momentum.
Latin America
The Latin America Global Smartphone Sensors Market size was valued at USD 3,180.60 million in 2018 to USD 5,235.45 million in 2024 and is anticipated to reach USD 15,294.01 million by 2032, at a CAGR of 14.4% during the forecast period. Market share 2024: 5.34%. Latin America grows through rising smartphone upgrades across major economies. Countries shift toward mid-range models that use improved imaging and security sensors. Brazil drives strong sales with wide digital adoption. Mexico and Argentina expand through young consumer groups using camera-heavy applications. It gains demand from gaming and social media activities that need better sensor output. Carriers expand 4G and 5G, lifting smart device use. Wearables also gain traction in urban areas. Growth remains steady despite price-sensitive segments.
Middle East
The Middle East Global Smartphone Sensors Market size was valued at USD 1,443.05 million in 2018 to USD 2,166.50 million in 2024 and is anticipated to reach USD 5,822.65 million by 2032, at a CAGR of 13.3% during the forecast period. Market share 2024: 2.21%. The Middle East grows through rising adoption of premium devices in GCC markets. Users prefer high-quality imaging and secure biometric features. Smart city projects push demand for strong mobile capabilities. It benefits from early adoption of advanced display formats and AI tools. Mid-range phones gain traction across broader population groups. E-commerce expansion strengthens smartphone replacement cycles. Regional brands focus on robust camera setups to attract younger users. Growth improves with wider digital services in urban zones.
Africa
The Africa Global Smartphone Sensors Market size was valued at USD 1,501.95 million in 2018 to USD 3,167.75 million in 2024 and is anticipated to reach USD 8,878.24 million by 2032, at a CAGR of 13.4% during the forecast period. Market share 2024: 3.23%. Africa expands through rising penetration of affordable smartphones. Low-end and mid-level phones drive strong sensor demand. Users adopt better camera features across social messaging and content creation. It grows through wider mobile banking and digital services. East and West Africa lead adoption with young tech-driven populations. Brands focus on durable sensors suited for hot and dusty environments. Wearables gain slow but steady traction. Urban areas shape demand for improved biometric and imaging modules.
Key Player Analysis:
- STMicroelectronics
- Murata Manufacturing Co., Ltd.
- Panasonic Corporation
- Qualcomm Incorporated
- Silicon Laboratories, Inc.
- Bosch Sensortec
- Senodia Technologies
- Fujitsu Limited
- Alps Electric
Competitive Analysis:
The Global Smartphone Sensors Market features strong competition among sensor manufacturers that focus on accuracy, power control, and compact design. Leading companies invest in advanced imaging, biometric, and motion units to secure placement in premium and mid-range devices. It gains support from rapid sensor innovation driven by AI, AR, and secure authentication needs. Firms compete through faster upgrades, deeper partnerships with OEMs, and broader product portfolios. Supplier strength depends on production scale, patent ownership, and alignment with chipset roadmaps. New entrants face high R&D needs and tight integration demands. Established players refine material science and calibration tools to maintain an edge. Market rivalry stays intense across Asia Pacific, North America, and Europe.
Recent Developments:
- STMicroelectronics accelerated its market dominance through a major strategic acquisition. In July 2025, STMicroelectronics announced the acquisition of NXP Semiconductors' MEMS sensors business for a total purchase price of $950 million in cash, comprising $900 million as an upfront payment and $50 million linked to technical milestones. The NXP MEMS business generated approximately $300 million in revenues during 2024, focusing on automotive safety sensors and industrial applications. This transaction represents a significant strategic fit for STMicroelectronics, as it strengthens the company's position across automotive, industrial, and consumer sectors by combining highly complementary technologies and customer relationships. The acquisition is expected to close in the first half of 2026, pending regulatory approvals, and will enhance ST's capability in automotive safety applications, motion sensors for airbags, vehicle dynamics monitoring, tire pressure management, and engine systems while leveraging the company's Integrated Device Manufacturer model for accelerated innovation cycles.
- Silicon Laboratories, Inc. reported strong financial performance driven by sensor and IoT device market expansion. In the first quarter of 2025, ending April 5, 2025, Silicon Labs achieved revenue of $178 million, representing a 67% to 68% year-over-year increase. Industrial & Commercial revenue was $96 million, marking a 47% year-over-year growth, while Home & Life revenue totaled $82 million, with a 99% year-over-year growth. The company announced its next-generation Series 3 platform on 22-nanometer process technology, which is now ramping into production. The platform features advancements in performance, AI inference capabilities, scalable memory architectures, and backward code compatibility with Series 2 devices. Additionally, Silicon Labs introduced the new Series 2 BG29 family of Bluetooth Low Energy devices, which complements its portfolio for applications like medical wearables, asset trackers, and sensors.
- Fujitsu Limited advanced its sensor and mobile technology initiatives through multiple strategic developments. In October 2024, Fujitsu announced the development of an AI application preventing quality degradation in 5G wireless networks, incorporating three key technologies including AI-powered real-time quality of experience estimation, early traffic detection preventing network degradation, and intelligent base station coverage optimization. The company began global rollout of this technology to mobile network operators starting November 2024, enhancing smartphone user connectivity during high-traffic periods while reducing operating costs and power consumption. In March 2025, Rakuten Mobile partnered with Fujitsu to accelerate 5G network expansion using Fujitsu's compact, energy-efficient radio units (model 44R21) based on O-RAN specifications, with the equipment showcased at MWC Barcelona 2025. These developments support improved smartphone sensor performance through optimized network infrastructure.
Report Coverage:
The research report offers an in-depth analysis based on Smartphone Type, Application and Price. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for advanced imaging sensors will increase with AI-driven photography.
- Biometric upgrades will expand across under-display and 3D sensing modules.
- Low-power sensor designs will support longer battery life in compact devices.
- Wearables will push demand for precise motion and biometric components.
- AR and VR features will require higher depth accuracy and faster response.
- Rugged sensors will gain traction in industrial and field-use smartphones.
- Multi-sensor fusion will evolve to support smarter interaction features.
- Supply chains will shift toward localized production for stable output.
- Sensor software optimization will become a key competitive factor.
- Premium smartphone growth will guide long-term innovation cycles.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Advances in Imaging and Camera Sensor Technology
Smartphone manufacturers are integrating larger, more sensitive camera sensors and multi-lens setups to deliver superior photography and video capabilities. This trend is driven by consumer demand for high-quality imaging and the proliferation of AI-powered computational photography, which requires precise and high-resolution sensor input.
Expansion of Biometric and Security Features
The adoption of advanced biometric sensors, such as under-display fingerprint readers and 3D facial recognition modules, is accelerating as users and regulators demand stronger device security and seamless authentication. These sensors are increasingly standard across both premium and mid-range devices, fueling market growth.
Growth in Motion, Orientation, and Environmental Sensing
Motion sensors like accelerometers, gyroscopes, and proximity sensors are essential for gaming, AR, gesture control, and battery management. The integration of environmental and health monitoring sensors in smartphones and wearables further expands the market by enabling new applications in wellness and safety.
AI Integration and Power-Efficient Sensor Design
The need for real-time AI processing in smartphones is driving demand for sensors that deliver clean, accurate data while consuming minimal power. Efficient sensor designs extend battery life and support advanced features such as AI-driven photography, AR, and multi-app multitasking, making them attractive to both OEMs and consumers.
Emergence of New Form Factors and Multi-Sensor Fusion
Innovations like foldable smartphones and edge-to-edge displays require advanced, compact, and often invisible sensors to manage device safety, display movement, and user interaction. Multi-sensor fusion systems that combine data from multiple sensor types are enabling smarter, more responsive user experiences, further propelling market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the global smartphone sensors market in 2023 and 2032, and its CAGR?
At what Compound Annual Growth Rate is the Global Smartphone Sensors Market projected to grow between 2025 and 2032?
What are the primary drivers of growth in the smartphone sensors market?
How do advancements in sensor technology impact the market?
Which region holds the largest market share in the smartphone sensors market?
Who are some of the key players in the global smartphone sensors market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Price
- 1.2.1 Under USD 100
- 1.2.2 USD 100 to USD 300
- 1.2.3 USD 300 to USD 500
- 1.2.4 Above USD 500
- 1.3 By Application
- 1.3.1 High-End
- 1.3.2 Mid-Level
- 1.3.3 Low-End
- 1.4 By Smartphone Type
- 1.4.1 Standard Smartphone
- 1.4.2 Rugged Smartphone
- 1.4.3 Smartwatches
- 1.4.4 Other Wearables
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 98,060.53 million → 2032: USD 312,953.02 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Smartphone Sensors Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Smartphone Sensors Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Smartphone Sensors Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Smartphone Sensors Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Smartphone Sensors Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Smartphone Sensors Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Smartphone Sensors Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Smartphone Sensors Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 98,060.53 million → 2032: USD 312,953.02 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Smartphone Sensors Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Price - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Under USD 100
- 12.3.7.2 USD 100 to USD 300
- 12.3.7.3 USD 300 to USD 500
- 12.3.7.4 Above USD 500
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 High-End
- 12.4.7.2 Mid-Level
- 12.4.7.3 Low-End
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Smartphone Type - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Standard Smartphone
- 12.5.7.2 Rugged Smartphone
- 12.5.7.3 Smartwatches
- 12.5.7.4 Other Wearables
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Smartphone Sensors End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Smartphone Sensors Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Smartphone Sensors Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Smartphone Sensors Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 STMicroelectronics
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Murata Manufacturing Co., Ltd.
- 18.4 Panasonic Corporation
- 18.5 Qualcomm Incorporated
- 18.6 Silicon Laboratories, Inc.
- 18.7 Bosch Sensortec
- 18.8 Senodia Technologies
- 18.9 Fujitsu Limited
- 18.10 Alps Electric
- 18.11 NXP Semiconductors
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

