
Market Overview
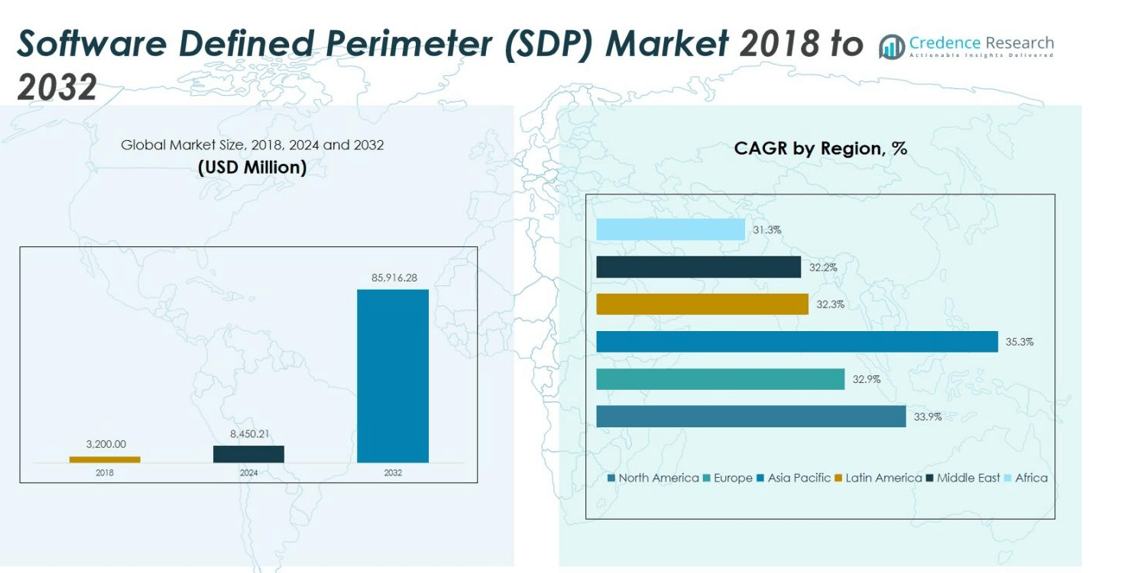
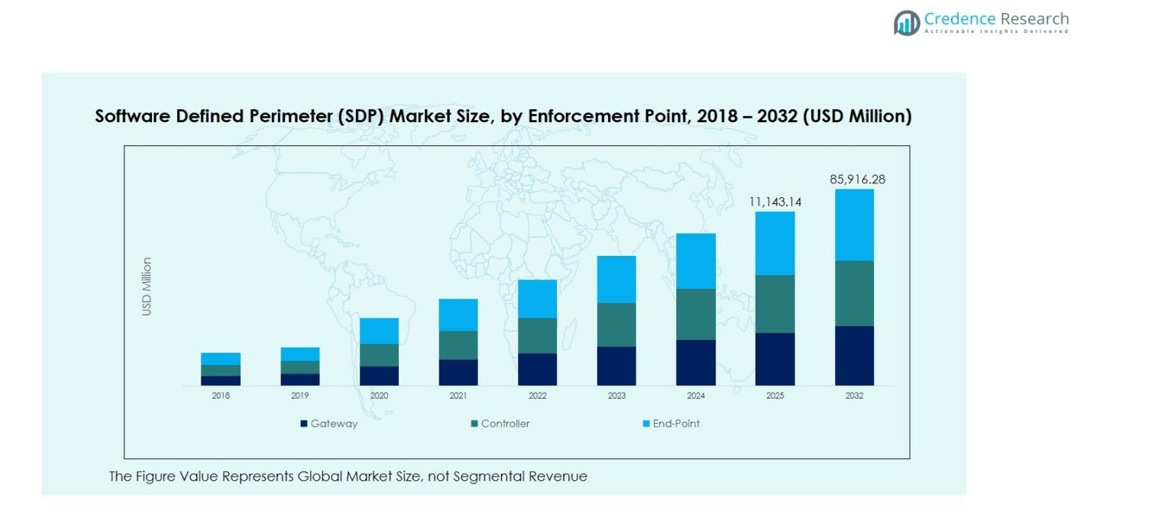
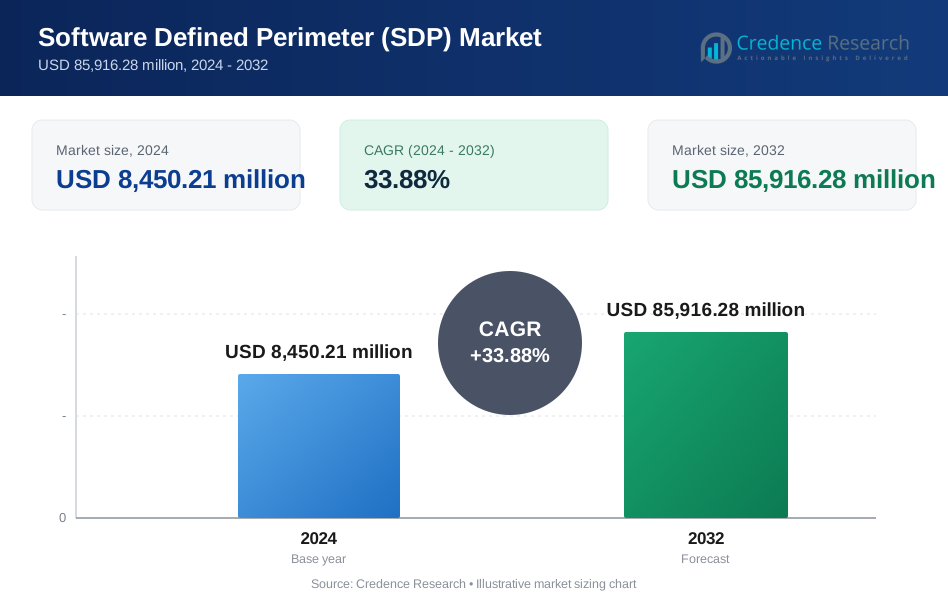
The Global Software Defined Perimeter (SDP) Market size was valued at USD 3,200.00 million in 2018, increased to USD 8,450.21 million in 2024, and is anticipated to reach USD 85,916.28 million by 2032, expanding at a CAGR of 33.88% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Software Defined Perimeter (SDP) Market Size 2024 | USD 8,450.21 million |
| Software Defined Perimeter (SDP) Market, CAGR | 33.88% |
| Software Defined Perimeter (SDP) Market Size 2032 | USD 85,916.28 million |
The Software Defined Perimeter (SDP) Market is dominated by major players such as Akamai Technologies, Broadcom, Cisco Systems, Dell Inc., Zscaler, Fortinet, Intel Corporation, Palo Alto Networks, Proofpoint, Verizon, Unisys Corporation, and Check Point Software Technologies Ltd. These companies focus on enhancing zero-trust network access (ZTNA) solutions, integrating AI for advanced threat detection, and expanding cloud security capabilities. North America leads the global market with a 36% share, driven by strong technological infrastructure and early adoption of SDP frameworks. Asia Pacific follows with 28%, supported by rapid digitalization, cloud investments, and growing cybersecurity awareness across major economies like China, Japan, and India.
Market Insights
- The Global Software Defined Perimeter (SDP) Market was valued at USD 8,450.21 million in 2024 and is projected to reach USD 85,916.28 million by 2032, growing at a CAGR of 33.88% during the forecast period.
- Growing demand for zero-trust security frameworks and cloud-based access control is driving market expansion across industries such as IT, BFSI, and defense.
- Integration of AI and machine learning into SDP solutions enhances real-time threat detection and automated risk mitigation, shaping future market trends.
- The market is moderately fragmented, with key players like Cisco Systems, Zscaler, Palo Alto Networks, and Akamai Technologies focusing on product innovation and partnerships to expand global reach.
- North America leads with a 36% share, followed by Asia Pacific at 28% and Europe at 26%, while Latin America, the Middle East, and Africa collectively contribute the remaining 10%, showing rising adoption in developing economies.
Market Segmentation Analysis:
By Enforcement Point
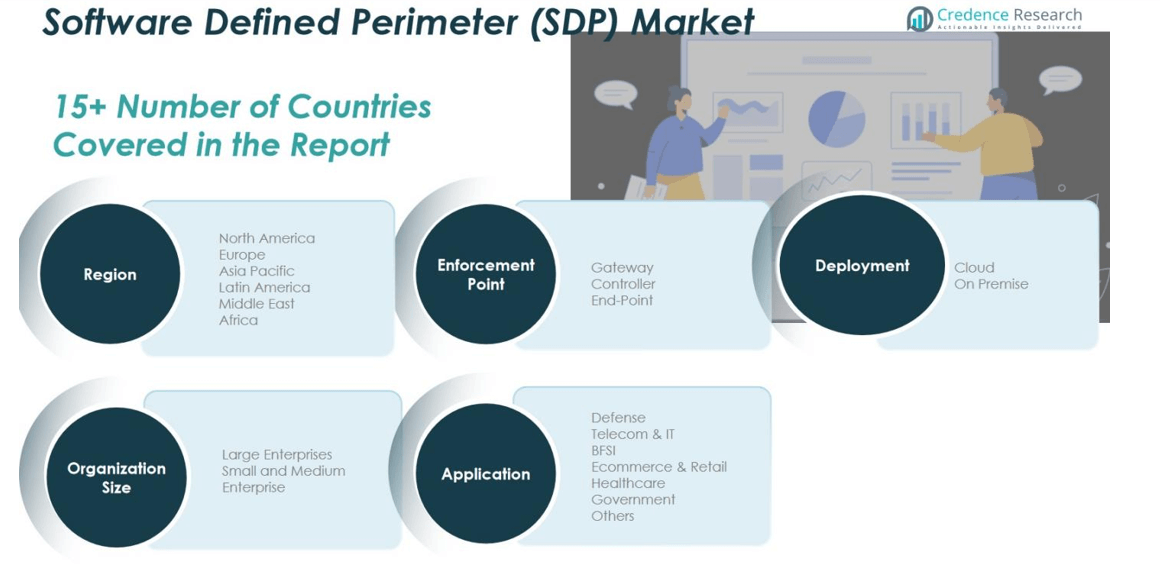
The gateway segment dominates the Software Defined Perimeter (SDP) Market, accounting for 48% of total revenue in 2024. Gateways act as the first line of defense, managing access control and user authentication between networks and cloud resources. Their adoption is driven by rising demand for secure hybrid network environments and zero-trust architectures. Controllers hold a moderate share of 32%, ensuring centralized policy enforcement, while end-points represent 20%, supported by growing endpoint security integration in remote work solutions. The gateway’s scalability and compatibility with cloud-based applications keep it the preferred choice among enterprises.
- For instance, Fortinet integrates gateways as critical enforcement points in its FortiGate SDP solution. Its gateways provide secure, identity-based access control to cloud and on-premises resources, widely adopted in industries needing strong compliance assurance.
By Application
The telecom and IT segment leads the SDP Market with 35% market share in 2024, driven by rapid digitalization, 5G deployment, and growing cloud service adoption. These industries rely heavily on SDP solutions to secure distributed workloads and virtualized environments. The BFSI sector follows with 22%, emphasizing secure remote transactions and data protection. Defense and government collectively contribute 25%, fueled by cybersecurity modernization programs. Healthcare and ecommerce segments are growing steadily, driven by data privacy compliance and increasing online activity. Expanding enterprise connectivity continues to boost SDP adoption across industries.
- For instance, hSenid SDP has enabled telecom companies to reduce time-to-market for new digital services through its low-code application development environment.
By Deployment
The cloud-based segment holds the dominant position in the SDP Market, capturing 68% market share in 2024. This dominance stems from the widespread transition toward cloud-native architectures and remote workforce enablement. Organizations prefer cloud deployment for its scalability, reduced maintenance, and cost efficiency. On-premise deployment retains 32% share, appealing to sectors with strict regulatory and data sovereignty requirements such as defense and BFSI. The cloud segment’s momentum is strengthened by integration with identity and access management tools and the growing shift toward software-as-a-service (SaaS) delivery models across global enterprises.
Key Growth Drivers
Rising Demand for Zero-Trust Security Architectures
The growing focus on zero-trust network access (ZTNA) is a primary driver of the Software Defined Perimeter (SDP) Market. Enterprises are shifting away from traditional perimeter-based security to identity-centric models that authenticate every user and device before granting access. This transition helps minimize data breaches and insider threats. Large organizations, particularly in BFSI and IT sectors, are adopting SDP solutions to secure remote connections and hybrid infrastructures. The rising complexity of cyberattacks further accelerates SDP implementation across global enterprises seeking adaptive protection.
- For instance, Zscaler strengthened its zero-trust capabilities by acquiring Airgap Networks to integrate agentless segmentation with its Zero Trust SD-WAN platform, providing comprehensive secure access across hybrid infrastructures.
Expansion of Cloud-Based Workloads and Remote Operations
Rapid cloud adoption and the expansion of remote work ecosystems are fueling SDP market growth. Organizations increasingly deploy multi-cloud and hybrid environments that require unified access management and encryption. SDP solutions enable seamless, policy-driven connectivity between users and distributed cloud resources. The pandemic-driven remote work culture has strengthened this trend, with companies prioritizing cloud security and device-agnostic access. Enterprises prefer SDP due to its scalability, flexibility, and reduced dependency on traditional VPNs, making it essential for modern, distributed network architectures.
- For instance, Appgate deployed its SDP solution to secure a global financial services client’s cloud and remote access environments, resulting in a significant reduction in attack surface by cloaking infrastructure and controlling access via single-packet authorization.
Growing Regulatory and Compliance Requirements
Tightening global regulations on data protection and privacy are boosting SDP demand. Frameworks such as GDPR, HIPAA, and CCPA push organizations to adopt advanced network security models that provide visibility and control. SDP architectures help meet compliance standards by isolating network resources and enforcing least-privilege access. Industries handling sensitive information, such as finance, healthcare, and government, are leading adopters. As compliance audits become stricter, SDP offers a proactive approach to safeguard data and ensure adherence to security mandates while improving operational transparency.
Key Trends & Opportunities
Integration with AI and Machine Learning for Threat Detection
Artificial intelligence (AI) and machine learning (ML) are transforming SDP capabilities through predictive analytics and real-time anomaly detection. Vendors are integrating AI-driven behavioral insights to automate risk assessment and strengthen access control mechanisms. This integration enhances visibility into user activity and network traffic, enabling faster threat response. The growing adoption of AI-enabled SDP solutions presents strong opportunities for vendors focusing on intelligent network monitoring, adaptive authentication, and continuous security posture improvement across diverse enterprise environments.
- For instance, SentinelOne’s Singularity™ Endpoint Security leverages AI algorithms to analyze network traffic and user interactions, detecting threats with high accuracy and automatically initiating mitigation actions to prevent breaches.
Rising Opportunities in SMEs and Developing Economies
Small and medium enterprises (SMEs) and developing regions are emerging as new growth frontiers for SDP providers. The increasing digitization of operations, coupled with limited internal IT resources, drives SMEs to adopt cloud-based SDP solutions. Affordable subscription models and managed security services make SDP accessible to mid-tier organizations. Meanwhile, Asia-Pacific, Latin America, and Africa offer untapped potential due to expanding internet infrastructure and growing cybersecurity awareness. This shift enables vendors to capture long-term opportunities in fast-evolving regional markets.
- For instance, in Asia-Pacific, Sumitomo Mitsui Financial Group has integrated platform-as-a-service cloud solutions into its supply chain workflows, demonstrating how hybrid cloud architectures support SME digital transformation.
Key Challenges
High Implementation Complexity and Integration Barriers
Despite its benefits, SDP deployment involves complex integration with legacy systems and existing security frameworks. Many enterprises face challenges aligning SDP with their current identity management, network monitoring, and cloud configurations. This complexity increases deployment time and cost, discouraging adoption among smaller organizations. The lack of skilled cybersecurity professionals further complicates integration efforts. Vendors must focus on simplifying implementation processes and enhancing interoperability to overcome these barriers and ensure broader market penetration.
Limited Awareness and Misconceptions about SDP Technology
Awareness gaps regarding the distinct advantages of SDP over traditional VPNs or firewalls remain a significant challenge. Many enterprises still view SDP as a niche or experimental technology rather than a mainstream solution. Misunderstandings about scalability, cost-effectiveness, and performance can slow adoption. Continuous education, demonstrations, and pilot projects are crucial to address these misconceptions. Industry partnerships and awareness campaigns can help bridge this gap, driving confidence and accelerating global adoption of software-defined perimeter solutions.
Regional Analysis
North America
North America dominates the Software Defined Perimeter (SDP) Market, holding the largest share of 36% in 2024. The market was valued at USD 1,113.60 million in 2018, increased to USD 2,903.44 million in 2024, and is projected to reach USD 29,478.03 million by 2032, expanding at a CAGR of 33.9%. Growth is driven by early adoption of zero-trust architectures, strong cybersecurity infrastructure, and presence of leading players such as Cisco, Zscaler, and Palo Alto Networks. High cloud adoption across BFSI, IT, and defense sectors further strengthens regional dominance in the global SDP market.
Europe
Europe holds a significant 26% market share in the global Software Defined Perimeter (SDP) Market. The regional market stood at USD 820.80 million in 2018, reached USD 2,081.06 million in 2024, and is anticipated to hit USD 19,954.29 million by 2032, recording a CAGR of 32.9%. Growth is supported by stringent data protection regulations such as GDPR and increasing investments in network security modernization. Countries including the UK, Germany, and France lead adoption due to rising cloud migration and demand for zero-trust frameworks across financial, healthcare, and government sectors.
Asia Pacific
Asia Pacific is the fastest-growing region in the Software Defined Perimeter (SDP) Market, capturing 28% market share in 2024. The market was valued at USD 892.48 million in 2018, rose to USD 2,448.41 million in 2024, and is projected to reach USD 27,166.80 million by 2032, growing at a CAGR of 35.3%. Rapid digital transformation, increasing cloud investments, and expansion of SMEs across China, India, Japan, and South Korea drive market acceleration. Growing awareness of cybersecurity and government-backed digital infrastructure programs continue to propel adoption of SDP solutions in the region.
Latin America
Latin America accounts for 5% of the global SDP market share, reflecting steady adoption across enterprises modernizing their IT infrastructure. The market stood at USD 163.20 million in 2018, expanded to USD 425.81 million in 2024, and is estimated to reach USD 3,940.98 million by 2032, growing at a CAGR of 32.3%. Brazil and Mexico lead regional deployment, driven by expanding digital ecosystems and rising cloud-based service adoption. Increasing investments in cybersecurity resilience and managed service offerings also strengthen the region’s growth potential in the global SDP landscape.
Middle East
The Middle East holds a 3% market share in the global Software Defined Perimeter (SDP) Market. The market was valued at USD 124.48 million in 2018, increased to USD 308.38 million in 2024, and is expected to reach USD 2,835.71 million by 2032, with a CAGR of 32.2%. Rapid digital transformation initiatives in GCC countries, rising adoption of cloud security in BFSI and government sectors, and expansion of smart city projects drive regional growth. Increasing partnerships between global cybersecurity vendors and regional telecom providers further accelerate SDP market expansion.
Africa
Africa represents an emerging market with a 2% share in the global Software Defined Perimeter (SDP) Market. The regional market grew from USD 85.44 million in 2018 to USD 283.12 million in 2024, and is projected to reach USD 2,540.48 million by 2032, advancing at a CAGR of 31.3%. Growth is fueled by improving digital connectivity, increasing adoption of cloud computing, and government initiatives to strengthen cybersecurity frameworks. South Africa, Egypt, and Kenya are leading adopters, with rising awareness about zero-trust security models and demand for cost-efficient, scalable SDP solutions.
Market Segmentations:
By Enforcement Point:
- Gateway
- Controller
- End-Point
By Application:
- Defense
- Telecom & IT
- BFSI
- Ecommerce & Retail
- Healthcare
- Government
- Others
By Deployment:
- Cloud
- On-Premise
By Organization Size:
- Large Enterprises
- Small and Medium Enterprises
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Software Defined Perimeter (SDP) Market features prominent players such as Akamai Technologies, Broadcom, Cisco Systems, Dell Inc., Zscaler, Fortinet, Intel Corporation, Palo Alto Networks, Proofpoint, Verizon, Unisys Corporation, and Check Point Software Technologies Ltd. The market is highly dynamic and innovation-driven, with companies focusing on expanding zero-trust network access (ZTNA) capabilities, integrating AI for threat detection, and enhancing interoperability across hybrid cloud environments. Strategic initiatives such as mergers, acquisitions, and partnerships are common as vendors aim to strengthen their security portfolios and global reach. Continuous R&D investment supports advancements in automation, scalability, and analytics-based security models. Startups are also entering the space with niche solutions, intensifying competition. Established players leverage their broad product ecosystems and enterprise client base to maintain leadership positions, while emerging providers compete through agility, cost efficiency, and managed service offerings tailored to small and mid-sized organizations.
Key Player Analysis
- Akamai Technologies
- Broadcom
- Cisco Systems, Inc.
- Dell Inc.
- Zscaler, Inc.
- Fortinet, Inc.
- Intel Corporation
- Palo Alto Networks, Inc.
- Proofpoint, Inc.
- Verizon, Inc.
- Unisys Corporation
- Check Point Software Technologies Ltd.
Recent Developments
- In 2025, Check Point Software Technologies Ltd. announced a strategic partnership with Microsoft Corporation to integrate its SDP solutions with Microsoft Azure’s cloud infrastructure.
- In January 2023, InstaSafe entered into a partnership with iValue InfoSolutions to broaden its SDP-based zero-trust security solutions across multi-cloud and on-premise environments in India.
- On September 17, 2024, Zscaler and CrowdStrike announced a strategic integration pairing Zscaler’s Zero Trust Exchange™ with the CrowdStrike Falcon® platform to unify AI-powered endpoint and network access protections
Report Coverage
The research report offers an in-depth analysis based on Enforcement Point, Application, Deployment, Organization Size and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Software Defined Perimeter (SDP) Market will witness rapid adoption due to the growing zero-trust security trend.
- Cloud-native SDP solutions will become standard as enterprises expand hybrid and multi-cloud environments.
- Integration of AI and machine learning will enhance real-time threat detection and automated policy enforcement.
- SMEs will increasingly adopt SDP through affordable SaaS-based and managed service models.
- Government and defense sectors will prioritize SDP for securing critical infrastructure and sensitive data.
- Partnerships between cybersecurity vendors and telecom providers will drive large-scale deployment.
- Demand for SDP in remote workforce management will continue to rise post-digital transformation.
- Vendors will focus on interoperability to integrate SDP with identity management and network access control systems.
- Regulatory compliance and data privacy mandates will further accelerate market growth.
- The market will see consolidation as leading players acquire niche security firms to expand technological capabilities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Software Defined Perimeter Market?
At what Compound Annual Growth Rate is the Software Defined Perimeter (SDP) Market projected to grow between 2025 and 2032?
What factors are driving the growth of the Software Defined Perimeter market?
What are some challenges faced by the Software Defined Perimeter market?
Who are the major players in the Software Defined Perimeter Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Software Defined Perimeter (SDP) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Software Defined Perimeter (SDP) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8,450.21 million → 2032: USD 85,916.28 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Software Defined Perimeter (SDP) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Software Defined Perimeter (SDP) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Software Defined Perimeter (SDP) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Software Defined Perimeter (SDP) Market Drivers
- 3.3 Software Defined Perimeter (SDP) Market Restraints & Challenges
- 3.4 Software Defined Perimeter (SDP) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Software Defined Perimeter (SDP) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Software Defined Perimeter (SDP) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Software Defined Perimeter (SDP) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Software Defined Perimeter (SDP) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Software Defined Perimeter (SDP) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Software Defined Perimeter (SDP) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Software Defined Perimeter (SDP) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Software Defined Perimeter (SDP) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Software Defined Perimeter (SDP) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Software Defined Perimeter (SDP) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Software Defined Perimeter (SDP) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Software Defined Perimeter (SDP) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Software Defined Perimeter (SDP) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Software Defined Perimeter (SDP) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Software Defined Perimeter (SDP) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Software Defined Perimeter (SDP) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Software Defined Perimeter (SDP) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Software Defined Perimeter (SDP) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Software Defined Perimeter (SDP) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
