
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| South Korea Cyber Physical Systems Market Size 2024 | USD 5335.1 million |
| South Korea Cyber Physical Systems Market, CAGR | 10.75% |
| South Korea Cyber Physical Systems Market Size 2032 | USD 12072.65 million |
Market Overview:
The South Korea Cyber Physical Systems is projected to grow from USD 5335.1 million in 2024 to an estimated USD 12072.65 million by 2032, with a compound annual growth rate (CAGR) of 10.75% from 2024 to 2032.
Several factors are driving the expansion of CPS in South Korea. The nation's robust push towards Industry 4.0 and digital transformation across manufacturing, automotive, and energy sectors necessitates the integration of CPS technologies. These technologies enable automation, enhanced data analysis, and real-time decision-making, leading to improved efficiency and productivity. Government initiatives, such as the "Digital New Deal," prioritize investments in data centers and cloud infrastructure, fostering the adoption of CPS solutions. These investments are crucial in advancing connectivity and data management, which are central to CPS applications. Additionally, the increasing demand for automation, real-time monitoring, and smart infrastructure in sectors like manufacturing, healthcare, and transportation further accelerates CPS adoption. As industries continue to embrace digitalization, CPS technologies are becoming integral to the seamless integration of physical and digital systems.
Regionally, South Korea's CPS market is influenced by its strategic position within the Asia Pacific region. The country's commitment to integrating CPS technologies, including the Industrial Internet of Things (IIoT), smart grids, and digital twins, into various industries positions it as a key player in the regional market. South Korea is leveraging its advanced technology infrastructure to lead in the development of CPS solutions, which are critical to enhancing operational efficiencies and reducing costs. This alignment with broader regional trends contributes to South Korea's significant share in the CPS market, driven by technological advancements and supportive government policies. Moreover, the collaboration between private and public sectors is accelerating innovation and the deployment of CPS solutions across industries, positioning South Korea as a technological hub for CPS in the Asia Pacific.
Market Insights:
- The South Korea Cyber Physical Systems is projected to grow from USD 5335.1 million in 2024 to an estimated USD 12072.65 million by 2032, with a compound annual growth rate (CAGR) of 10.75% from 2024 to 2032.
- The Global Cyber Physical Systems is projected to grow from USD 1,25,271.30 million in 2024 to an estimated USD 2,71,668.59 million by 2032, with a compound annual growth rate (CAGR) of 10.16% from 2024 to 2032.
- Government initiatives, such as the "Digital New Deal," are crucial in promoting the widespread adoption of CPS technologies across key industries.
- Industry 4.0 adoption is accelerating in sectors like manufacturing, automotive, and energy, driving demand for advanced automation and smart infrastructure.
- The increasing integration of IoT devices and high-speed connectivity is enhancing the effectiveness of CPS solutions, supporting real-time data analysis and decision-making.
- The demand for smart city solutions is pushing the growth of CPS, particularly in areas like energy management, transportation, and urban infrastructure.
- The market faces challenges, including high implementation costs, cybersecurity concerns, and interoperability issues, which may slow adoption rates.
- Despite these challenges, South Korea’s advanced technological infrastructure and focus on digital transformation position it as a leader in the regional CPS market.
Report Scope
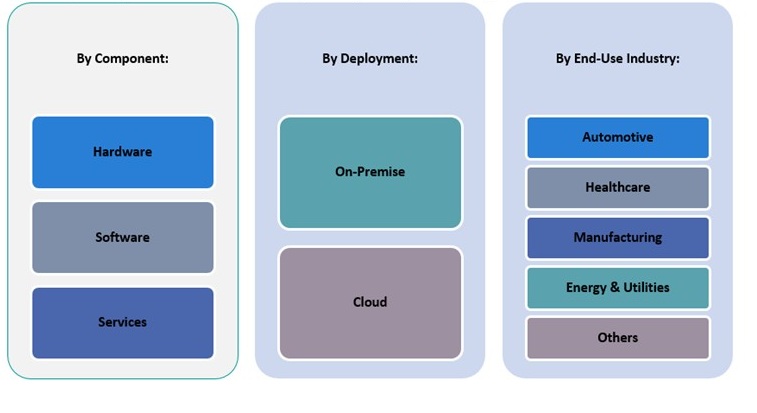
This report segments the South Korea Cyber Physical Systems Market as follows
Market Drivers:
Government Initiatives and Policies
One of the primary drivers of the Cyber-Physical Systems (CPS) market in South Korea is the government's strong support for digital transformation and Industry 4.0 initiatives. The South Korean government has introduced various policies aimed at advancing smart manufacturing, automation, and data-driven technologies. For instance, the "Digital New Deal" program, which focuses on building a robust digital infrastructure, emphasizes the integration of CPS technologies into various industries such as manufacturing, healthcare, and transportation. These policies encourage private and public sector investments, fostering an environment conducive to the widespread adoption of CPS solutions. Furthermore, government support is pivotal in developing smart cities and enhancing national security through advanced CPS applications, driving overall market growth.
Increasing Demand for Automation and Efficiency
South Korea’s increasing demand for automation and efficiency across industries is another major driver for the growth of the CPS market. As industries such as automotive, manufacturing, and energy seek to enhance operational efficiency and reduce costs, CPS technologies provide critical solutions. By integrating physical systems with digital components, businesses can achieve real-time monitoring, predictive maintenance, and enhanced control systems, which directly translate to cost savings and improved productivity. This push toward automation is particularly evident in the manufacturing sector, where CPS enables smart factories that can monitor and control production lines autonomously. As a result, South Korea’s industrial sector is rapidly adopting CPS to remain competitive on the global stage.
Technological Advancements in IoT and Connectivity
The rapid development of the Internet of Things (IoT) and advancements in connectivity technologies are significantly contributing to the expansion of the CPS market in South Korea. IoT devices are essential for connecting physical systems to digital networks, which allows real-time data collection, analysis, and feedback. South Korea’s high-speed internet infrastructure and advanced telecommunications network support the seamless integration of IoT solutions in various CPS applications, from smart homes to industrial automation. This synergy between IoT and CPS enhances the effectiveness of automation, real-time monitoring, and data-driven decision-making, which fuels market demand. As IoT adoption increases, South Korea continues to lead in implementing these technologies across various sectors.
Growth of Smart Infrastructure and Industry 4.0 Adoption
The growing emphasis on smart infrastructure and the adoption of Industry 4.0 principles are key drivers of CPS market growth in South Korea. Industry 4.0 integrates cyber-physical systems, IoT, artificial intelligence, and big data analytics to transform manufacturing processes, create smarter supply chains, and optimize energy consumption. In South Korea, both the public and private sectors are heavily investing in smart grids, autonomous vehicles, and digital twins, all of which rely on CPS technologies. This move towards smart infrastructure enhances the efficiency, safety, and sustainability of urban and industrial environments. For example, energy losses in smart grids utilizing CPS have decreased by 30%, showcasing their impact on improving resource utilization. As South Korea continues to advance its technological capabilities, CPS solutions are becoming integral to its national strategy for economic growth and global competitiveness.
Market Trends:
Rising Adoption of Digital Twins
A key market trend in South Korea's Cyber-Physical Systems (CPS) landscape is the growing adoption of digital twins across industries. Digital twins, which create virtual replicas of physical systems to simulate and analyze real-time data, are gaining traction in sectors like manufacturing, energy, and healthcare. For instance, manufacturers are leveraging digital twin technology to simulate production processes, enabling predictive maintenance and reducing downtime, which aligns with the goals of Industry 4.0. Digital twins provide virtual replicas of physical assets. By utilizing digital twins, companies can improve their predictive maintenance capabilities, reduce downtime, and optimize system performance. In South Korea, manufacturers are increasingly incorporating digital twin technology to enhance product design, manufacturing processes, and overall operational efficiency. This trend reflects the country's broader push towards digital innovation, where the integration of virtual and physical environments leads to smarter, more adaptable industries.
Shift Towards Autonomous Systems
Another notable trend in the South Korean CPS market is the shift towards the development and deployment of autonomous systems. These systems, which leverage advanced artificial intelligence (AI), machine learning, and robotics, are transforming various sectors such as automotive, logistics, and healthcare. Autonomous vehicles, drones, and robots are becoming integral parts of industries seeking greater efficiency, safety, and reduced operational costs. For instance, Hyundai Motor Group has been actively developing autonomous vehicles with features like highway driving assistance. South Korea is positioning itself at the forefront of autonomous technology, with government-backed initiatives and corporate investments aimed at accelerating the commercialization of self-driving vehicles and robotic automation in industries. As automation technology advances, CPS solutions are being increasingly used to monitor, control, and optimize autonomous systems in real-time.
Integration of AI and Machine Learning in CPS
Artificial Intelligence (AI) and machine learning are increasingly being integrated with CPS technologies in South Korea. These advanced technologies enable the real-time processing of massive datasets generated by CPS systems, leading to more intelligent decision-making, predictive analytics, and autonomous operations. South Korea is embracing AI-driven CPS solutions in sectors such as manufacturing, where AI is being used to optimize production lines, improve quality control, and predict equipment failures. The integration of AI and machine learning allows CPS to become more adaptive and efficient, making it a key trend in the market. As AI capabilities continue to evolve, the synergies between AI and CPS are expected to drive more innovative applications and broaden their adoption across industries.
Focus on Smart Cities and Infrastructure Development
The focus on smart cities and the development of intelligent infrastructure is also shaping the CPS market in South Korea. The government is investing heavily in building connected, data-driven urban environments that leverage CPS technologies for improved resource management, transportation, and public services. Smart cities rely on a network of sensors, IoT devices, and CPS solutions to monitor everything from traffic patterns to energy usage, enhancing the quality of life for residents while promoting sustainability. South Korea’s commitment to developing smart cities is driving demand for CPS solutions that facilitate real-time monitoring, data-driven insights, and integrated services. As urbanization continues, the trend of smart city development will likely become one of the most significant drivers of CPS adoption in South Korea.
Market Challenges Analysis:
High Implementation Costs
One of the key restraints in the South Korean Cyber-Physical Systems (CPS) market is the high implementation costs associated with deploying CPS solutions. For instance, advanced CPS systems often require significant investment in cutting-edge technologies, such as IoT devices, AI platforms, and robotics. The complexity of integrating these technologies into existing infrastructures further increases installation expenses. Small and medium-sized enterprises (SMEs) are particularly affected, as they often lack the financial resources to invest in these systems. According to market analyses, SMEs face additional burdens due to the need for skilled personnel to manage and maintain CPS solutions, which adds to operational costs and delays return on investment
Cybersecurity Concerns
Cybersecurity is another major challenge for the CPS market in South Korea. As CPS technologies rely heavily on interconnected devices and networks, they are vulnerable to cyberattacks that could compromise data integrity, privacy, and system functionality. South Korea, being a highly connected nation with a strong emphasis on digital transformation, faces increased risks of cyber threats targeting critical infrastructure. Ensuring the security of CPS systems is a complex task, requiring robust security protocols and constant updates to defend against evolving threats. The lack of standardized cybersecurity frameworks for CPS could lead to potential vulnerabilities, limiting trust and slowing down market adoption.
Interoperability Issues
The challenge of interoperability remains a significant barrier to the growth of the CPS market in South Korea. CPS solutions often involve the integration of diverse systems, devices, and platforms, which may not always be compatible with each other. This lack of seamless integration can hinder the effective deployment and scaling of CPS technologies across different industries. Without standardized protocols and frameworks for interoperability, businesses face difficulties in ensuring that various CPS components communicate and work together efficiently. This issue can delay implementation, increase costs, and limit the potential benefits of CPS systems.
Skill Shortages
The shortage of skilled professionals in the fields of CPS, AI, IoT, and data analytics poses a challenge to the successful adoption and scaling of CPS technologies in South Korea. The demand for highly specialized talent in these areas often exceeds the supply, creating a talent gap that affects the development, deployment, and maintenance of CPS solutions. Companies may face difficulties in recruiting and retaining the necessary expertise, leading to delays in CPS adoption and increased reliance on external vendors. Addressing this skill gap is critical for fostering a sustainable and growing CPS market.
Market Opportunities:
South Korea's Cyber-Physical Systems (CPS) market presents significant opportunities for growth, particularly as industries continue to embrace digital transformation. One of the key opportunities lies in the manufacturing sector, where the adoption of Industry 4.0 technologies, such as automation, smart factories, and predictive maintenance, is rapidly accelerating. With South Korea's strong industrial base, particularly in electronics, automotive, and machinery, CPS solutions can provide manufacturers with enhanced operational efficiencies, reduced costs, and improved product quality. As companies seek to stay competitive globally, the integration of CPS technologies will be essential in driving innovation, optimizing production processes, and increasing productivity. This trend is further supported by the government’s initiatives, such as the "Digital New Deal," which encourages the adoption of CPS solutions across various industries.
Additionally, the development of smart cities and infrastructure offers a substantial market opportunity for CPS providers in South Korea. The government’s commitment to creating connected, sustainable urban environments presents a growing demand for CPS technologies in sectors like transportation, energy management, and urban planning. Smart grids, intelligent traffic systems, and real-time monitoring of public services are just a few examples of how CPS can enhance urban living. The need for integrated, data-driven systems to manage resources efficiently is driving the growth of smart cities, positioning CPS as a key enabler of this transformation. As South Korea continues to focus on its urbanization and sustainability goals, the CPS market is poised for long-term growth, providing ample opportunities for businesses to innovate and expand.
Market Segmentation Analysis:
The South Korea Cyber-Physical Systems (CPS) market can be segmented by component, deployment, and end-use industry, each of which plays a critical role in the market's dynamics.
By Component:
The CPS market in South Korea is categorized into hardware, software, and services. Hardware holds a significant share due to the demand for sensors, controllers, and robotics, which are essential for real-time monitoring and automation. The software segment is also experiencing growth, driven by the increasing need for advanced analytics, machine learning algorithms, and control systems to process and interpret data. Services, including system integration, consulting, and maintenance, play an essential role in supporting the deployment and ongoing optimization of CPS technologies.
By Deployment:
CPS solutions are deployed through two primary models: on-premise and cloud. On-premise deployment continues to dominate in industries like manufacturing and automotive, where security and control over systems are critical. However, the cloud deployment model is gaining traction, especially in industries that require scalability, flexibility, and real-time data access. Cloud-based CPS solutions are being increasingly adopted in sectors like healthcare and energy, where remote monitoring and data sharing are pivotal.
By End-Use Industry:
The automotive, healthcare, and manufacturing sectors are the primary drivers of CPS adoption in South Korea. The automotive industry is utilizing CPS for autonomous vehicles and advanced driver-assistance systems (ADAS). Healthcare is leveraging CPS for patient monitoring, diagnostics, and personalized care. The manufacturing sector, driven by Industry 4.0 initiatives, is embracing CPS for smart factories and predictive maintenance. Other sectors, including energy and utilities, are increasingly adopting CPS for smart grids, energy management, and sustainable resource optimization. Each of these industries presents unique opportunities for CPS deployment, fueling market growth across various segments.
Segmentation:
By Component:
- Hardware
- Software
- Services
By Deployment:
- On-Premise
- Cloud
By End-Use Industry:
- Automotive
- Healthcare
- Manufacturing
- Energy & Utilities
- Others
Regional Analysis:
South Korea's Cyber-Physical Systems (CPS) market exhibits a dynamic landscape, with significant developments across various regions. The market's growth is influenced by factors such as industrialization, technological advancements, and strategic government initiatives aimed at promoting digital transformation.
Seoul Metropolitan Area
The Seoul Metropolitan Area, encompassing Seoul and its surrounding provinces, stands as the epicenter of CPS development in South Korea. This region houses a majority of the nation's technology firms, research institutions, and industrial complexes. The concentration of resources and infrastructure has fostered rapid adoption of CPS technologies, particularly in manufacturing and smart city projects. While precise market share figures are not publicly disclosed, it is estimated that the Seoul Metropolitan Area accounts for over 50% of the national CPS market, reflecting its pivotal role in driving innovation and implementation.
Gyeonggi Province
Adjacent to Seoul, Gyeonggi Province plays a crucial role in the CPS ecosystem. The province's proximity to the capital has facilitated collaboration between local governments and private enterprises. Gyeonggi's focus on integrating CPS in sectors such as automotive manufacturing and healthcare has positioned it as a key player in the regional market. It is estimated that Gyeonggi Province contributes approximately 20% to the national CPS market share, underscoring its importance in the country's technological landscape.
Other Provinces
Regions such as Busan, Daegu, and Incheon are also embracing CPS technologies, albeit to a lesser extent. These areas are focusing on specific applications, including port automation in Busan and smart grid initiatives in Daegu. Collectively, these provinces account for the remaining 30% of the CPS market share, with each contributing uniquely to the diversification and expansion of CPS applications across South Korea.
Key Player Analysis:
- Toshiba Corporation
- Hitachi, Ltd.
- Fujitsu Limited
- Panasonic Corporation
- NEC Corporation
- Huawei Technologies Co., Ltd.
- Samsung Electronics Co., Ltd.
- Infosys Limited
- Wipro Limited
Competitive Analysis:
The competitive landscape of the South Korean Cyber-Physical Systems (CPS) market is characterized by the presence of both global and local players, each striving to leverage emerging technologies such as IoT, AI, and robotics. Key players in the market include large multinational corporations such as Siemens AG, Honeywell, and ABB, which provide advanced CPS solutions across various industries, including manufacturing, energy, and automotive. These companies are capitalizing on their technological expertise, extensive product portfolios, and global presence to dominate the CPS market in South Korea. Local players, including companies like Samsung Electronics and LG Electronics, are also significant competitors, focusing on innovations tailored to South Korea’s unique market needs. These companies often combine their capabilities in hardware and software to offer integrated CPS solutions, particularly in smart manufacturing and smart city initiatives. The competitive environment remains dynamic, with ongoing investments in research and development driving continuous innovation and expansion of CPS applications across industries.
Recent Developments:
- On March 31, 2025, Siemens AG announced the formation of the Accenture Siemens Business Group at Hannover Messe 2025. This partnership aims to transform engineering and manufacturing by combining Siemens' industrial AI and automation technologies with Accenture's data and AI expertise. The group will employ 7,000 professionals globally to develop software-defined products and factories, leveraging Siemens Xcelerator portfolio and Accenture’s AI capabilities.
- In Oct 2024, Phosphorus Cybersecurity Inc., a leader in unified security management for xIoT devices, announced its strategic expansion into the Asia Pacific and Japan (APJ) region. This move is driven by the region’s rapid growth in cyber-physical systems and increasing cybersecurity challenges.
- On March 6, 2025, Armis, a prominent cyber exposure management company, acquired OTORIO, a leading provider of operational technology (OT) and cyber-physical system (CPS) security. OTORIO's Titan platform will now be integrated into Armis' Centrix™ cloud-based platform, expanding its capabilities to include on-premises CPS solutions for air-gapped environments.
- In February 2025, Nozomi Networks was recognized as a Leader in the 2025 Gartner Magic Quadrant for CPS Protection Platforms. This accolade highlights Nozomi's expertise in OT, IoT, and CPS security, particularly its AI-powered platform for asset discovery, threat detection, and vulnerability management. The recognition underscores Nozomi's commitment to securing critical infrastructure and enhancing resilience against evolving cyber threats.
Market Concentration & Characteristics:
The market concentration in South Korea’s Cyber-Physical Systems (CPS) market is relatively high, with a few dominant players shaping the landscape. Large multinational corporations such as Siemens AG, Honeywell, and ABB, along with local tech giants like Samsung Electronics and LG Electronics, hold a significant market share. These companies leverage their extensive resources, research capabilities, and technological expertise to drive the development and deployment of CPS solutions across industries like manufacturing, automotive, and energy. The CPS market is characterized by rapid technological advancements, including the integration of IoT, AI, and machine learning, which are enhancing the functionality and efficiency of CPS applications. The market also reflects a strong push towards Industry 4.0, with a focus on smart manufacturing, automation, and real-time data analytics. This focus on innovation, combined with government support for digital transformation, creates a competitive yet collaborative market environment.
Report Coverage:
The research report offers an in-depth analysis based on Component, Deployment and End-Use Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- South Korea’s CPS market will experience continued growth driven by the government’s digital transformation initiatives, particularly the "Digital New Deal."
- Increased adoption of Industry 4.0 technologies will expand CPS use across manufacturing and automotive sectors, enhancing automation and operational efficiency.
- The smart city development projects will drive demand for CPS solutions in urban infrastructure, focusing on energy management and traffic systems.
- IoT and AI integration will enhance the capabilities of CPS, enabling more intelligent and autonomous systems across industries.
- The healthcare sector will see expanded CPS applications for patient monitoring, diagnostics, and personalized care solutions.
- Advancements in robotics and autonomous vehicles will foster the growth of CPS in transportation and logistics.
- Cloud-based CPS solutions will grow as businesses seek scalable, flexible, and cost-effective deployment options.
- South Korea will strengthen its position as a hub for CPS research and development, further advancing innovation in the field.
- Cybersecurity measures will become a key focus to address vulnerabilities in the highly connected CPS ecosystem.
- The demand for skilled professionals in CPS-related fields will increase, spurring educational and training initiatives across the country.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the South Korea Cyber Physical Systems Market?
What factors are driving the growth of the South Korea Cyber Physical Systems market?
What are some challenges faced by the South Korea Cyber Physical Systems market?
Who are the major players in the South Korea Cyber Physical Systems Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 South Korea Cyber Physical Systems Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 South Korea Cyber Physical Systems Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5335.1 million → 2032: USD 12072.65 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 South Korea Cyber Physical Systems Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. South Korea Cyber Physical Systems Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 South Korea Cyber Physical Systems Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 South Korea Cyber Physical Systems Drivers
- 3.3 South Korea Cyber Physical Systems Restraints & Challenges
- 3.4 South Korea Cyber Physical Systems Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 South Korea Cyber Physical Systems Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 South Korea Cyber Physical Systems Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, South Korea Cyber Physical Systems category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 South Korea Cyber Physical Systems Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. South Korea Cyber Physical Systems Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2024)
- 5.1.2 Export Volume by Destination Country (2024) (Where Applicable)
- 5.1.3 Import Value by Source Country (2024)
- 5.1.4 Import Volume by Source Country (2024) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to South Korea Cyber Physical Systems in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 South Korea Cyber Physical Systems Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 South Korea Cyber Physical Systems Share Analysis – 2024
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 South Korea Cyber Physical Systems Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in South Korea Cyber Physical Systems (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in South Korea Cyber Physical Systems
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. South Korea Cyber Physical Systems – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. South Korea Cyber Physical Systems – Priority Domestic Market 1
Chapter 10. South Korea Cyber Physical Systems – Priority Domestic Market 2
Chapter 11. South Korea Cyber Physical Systems – Priority Domestic Market 3
Chapter 12. South Korea Cyber Physical Systems – Priority Domestic Market 4
Chapter 13. South Korea Cyber Physical Systems Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
