
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Spastic paraplegia 50 (SPG50) market Size 2023 | USD 135.5 million |
| Spastic paraplegia 50 (SPG50) market, CAGR | 10.10% |
| Spastic paraplegia 50 (SPG50) market Size 2032 | USD 292.57 million |
Market Overview:
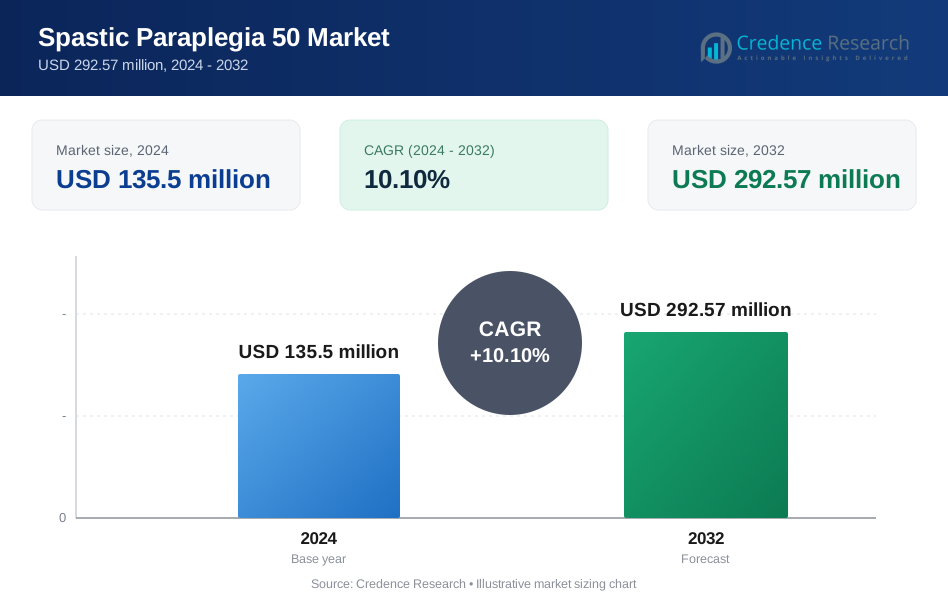
The global spastic paraplegia 50 (SPG50) market is projected to expand from USD 135.5 million in 2024 to USD 292.57 million by 2032, reflecting a compound annual growth rate (CAGR) of 10.10%. SPG50, a rare genetic disorder within the hereditary spastic paraplegias (HSPs) group, primarily affects motor function, leading to progressive muscle stiffness and weakness, particularly in the lower limbs. Currently, there is no cure for SPG50, with treatments focused on managing symptoms and enhancing patients' quality of life. The market encompasses a variety of therapeutic approaches, including gene therapy, physical therapy, and emerging drug treatments aimed at addressing underlying neurological dysfunction. As the demand for effective treatments increases, the market is set to experience substantial growth driven by ongoing research and new therapeutic developments.
Several factors are driving the growth of the SPG50 market. A key driver is the increased focus on rare genetic disorders and the substantial research investments aimed at developing innovative treatments. Gene therapy, for instance, has gained considerable attention, with experimental treatments in clinical trials showing promise for SPG50. Additionally, advances in genomics and diagnostics have improved the early detection of hereditary spastic paraplegias, facilitating timely intervention. Government grants and financial incentives for rare disease research further encourage pharmaceutical companies and research institutions to invest in SPG50 therapies. The increasing awareness about SPG50 among healthcare providers and patients also contributes to the demand for novel therapeutic options.
Regionally, North America holds the largest share of the SPG50 market, driven by advanced healthcare infrastructure, significant research funding, and a higher rate of early diagnosis through genetic testing. The United States, in particular, has a well-established network of rare disease centers and leading pharmaceutical companies engaged in SPG50 research and clinical trials. Europe follows closely, with robust public health initiatives focused on rare diseases and increasing investments in gene therapy research. The Asia-Pacific region is expected to witness the fastest growth over the forecast period due to improving healthcare systems, growing awareness about rare genetic disorders, and increasing healthcare expenditure in countries such as China and Japan. This regional distribution underscores the global commitment to advancing treatments for rare diseases like SPG50.
Market Drivers:
Growing Investment in Rare Disease Research:
The rising focus on rare genetic disorders has led to increased investment in SPG50 research and treatment development. Many governments and organizations provide funding and incentives to support the research and development of therapies for rare diseases. For example, the U.S. National Institutes of Health (NIH) and the European Union have both established programs specifically to fund rare disease studies. This commitment has encouraged pharmaceutical companies to pursue innovative therapies, such as gene therapies, for rare disorders like SPG50, offering hope for improved treatment outcomes and even potential cures.
Advancements in Gene Therapy and Genetic Testing:
Gene therapy advancements significantly drive the SPG50 market, as this technology holds the potential to address the genetic root of the disorder. For instance, recent breakthroughs in CRISPR-Cas9 and other gene-editing technologies have shown promise in correcting genetic mutations at the DNA level. Biotech companies are investing heavily in gene therapy platforms to develop treatments that could potentially halt or reverse the progression of diseases like SPG50. Additionally, advances in genetic testing facilitate earlier and more accurate diagnoses, allowing for timely intervention. These improvements in diagnostics enable healthcare providers to identify SPG50 mutations sooner, optimizing treatment planning and patient outcomes.
Increased Awareness and Patient Advocacy:
The growth of patient advocacy organizations focused on hereditary spastic paraplegias has played a crucial role in raising awareness about SPG50. Groups like the Hereditary Spastic Paraplegia Society and the Global Genes organization work to promote understanding, support research, and foster connections between patients, healthcare providers, and researchers. These organizations often collaborate with healthcare professionals and researchers to highlight the need for advanced therapeutic options, thus attracting attention to the challenges faced by SPG50 patients. This heightened awareness leads to greater public and private investment in research and more comprehensive care options for patients.
Supportive Government Policies and Regulatory Incentives:
Supportive government policies and regulatory incentives are essential drivers of the SPG50 market. Many countries offer incentives like tax credits, grants, and exclusivity extensions for companies developing treatments for rare diseases. For example, the U.S. Orphan Drug Act provides significant benefits for the development of orphan drugs, which include treatments for conditions affecting fewer than 200,000 people. Similarly, the European Medicines Agency (EMA) provides incentives for rare disease research, reducing the financial risks for companies working on therapies for conditions like SPG50. These regulatory measures help to stimulate innovation and encourage the development of effective treatments for rare and underserved patient populations.
Market Trends:
Emergence of Gene Therapy as a Key Treatment Option:
Gene therapy has emerged as a pivotal trend in the treatment landscape for SPG50. With the potential to correct the underlying genetic mutations causing the disorder, gene therapy offers a long-term solution beyond symptomatic treatment. Several biotech companies and research institutions are developing experimental gene therapies specifically for SPG50, building on the success seen in other rare genetic disorders. For example, Spark Therapeutics has developed gene therapies for rare conditions like retinal diseases, demonstrating the feasibility and efficacy of this approach. This progress has encouraged more research into gene therapy applications for SPG50, paving the way for potentially transformative treatments.
Growing Focus on Patient-Centric Treatment Models:
There is a marked shift towards patient-centric care models, focusing on improving the overall quality of life for SPG50 patients. This trend is driven by an increasing recognition of the unique challenges faced by individuals with SPG50, who often require multidisciplinary care, including physical therapy, speech therapy, and assistive devices. For instance, the National Institutes of Health (NIH) has emphasized the importance of personalized treatment plans that cater to the diverse needs of SPG50 patients. This patient-centric approach fosters collaboration among neurologists, genetic counsellors, physical therapists, and other specialists, resulting in comprehensive care models that improve daily functioning and quality of life.
Advancements in Telemedicine and Digital Health Solutions:
The rise of telemedicine and digital health solutions has improved access to specialized care for SPG50 patients, particularly in remote areas. Telehealth platforms facilitate virtual consultations with neurologists and genetic specialists, allowing patients to receive expert guidance without the need for extensive travel. For example, platforms like Teladoc and Amwell have expanded their services to include genetic counselling and neurological assessments, which are essential for SPG50 patients. Additionally, mobile health applications that track symptoms and therapy progress empower patients to manage their condition more effectively, providing real-time data to healthcare providers and aiding in treatment adjustments.
Increased Collaboration and Research Partnerships:
Collaborations and partnerships are on the rise, as pharmaceutical companies, research institutions, and advocacy groups work together to accelerate SPG50 treatment development. Joint initiatives, such as those funded by the European Commission’s Horizon Europe program, aim to bring together scientific expertise and resources to foster innovation in rare disease research. For instance, collaborations between biotech firms and academic institutions enable knowledge sharing and resource pooling, facilitating faster progress in clinical trials for SPG50 therapies. These partnerships are essential to overcoming the unique challenges of developing treatments for rare conditions, providing a path for more efficient and effective solutions.
Market Challenges Analysis:
High Development Costs and Limited Financial Incentives:
The development of treatments for rare genetic disorders like SPG50 is costly and requires substantial financial investment. Due to the limited patient population, pharmaceutical companies often struggle to justify the high costs of research and clinical trials, which are comparable to those for more common conditions. Although government authorities such as the U.S. Food and Drug Administration (FDA) offer incentives like orphan drug designation to encourage development, these incentives may not fully offset the high costs involved. Additionally, treatments for rare diseases often face high pricing pressures, which can limit the financial viability for companies to pursue innovative therapies in this field.
Regulatory Hurdles and Lengthy Approval Processes:
Regulatory requirements for the approval of SPG50 treatments are stringent, particularly in gene therapy and other emerging treatment modalities. Agencies like the European Medicines Agency (EMA) and the FDA require extensive clinical data to ensure safety and efficacy, which can significantly lengthen the approval timeline. These requirements add complexity to the development process, as trials for rare diseases often face challenges such as small patient populations and limited clinical data. Navigating these regulatory hurdles requires substantial time and resources, which can deter smaller biotech companies from entering the market.
Limited Awareness and Diagnostic Challenges:
SPG50, like many rare diseases, suffers from limited awareness among both healthcare providers and the general public. The rarity of the condition means that many primary care providers may not be familiar with its symptoms, leading to delays in diagnosis. Furthermore, genetic testing, while becoming more accessible, is still not universally available, particularly in regions with limited healthcare resources. This lack of awareness and diagnostic capability contributes to delayed intervention and missed opportunities for early treatment. Efforts by public health authorities, such as the National Institutes of Health (NIH), to increase awareness are ongoing but need further expansion to reach more healthcare professionals and patient communities.
Challenges in Patient Recruitment for Clinical Trials:
Given the small patient population, recruiting participants for clinical trials on SPG50 therapies is inherently challenging. Clinical trials for rare diseases frequently face issues with recruitment, as eligible patients are geographically dispersed and often unaware of available trials. Government agencies like the FDA have implemented programs to support rare disease research and facilitate clinical trial design. However, recruiting sufficient patients to generate robust data remains a significant hurdle, affecting the pace of research and delaying the development of new therapies.
Market Segmentation Analysis:
By Type
The Spastic Paraplegia 50 (SPG50) market can be segmented by treatment types, which include gene therapy, physical therapy, and drug therapy. Gene therapy is rapidly gaining attention, as it offers a promising approach for targeting the genetic basis of SPG50. Gene therapies have shown potential in early trials to modify or correct genetic mutations, potentially altering the disease progression. Physical therapy remains an essential component for managing symptoms, helping patients maintain mobility and muscle strength. Additionally, drug therapies, primarily symptomatic treatments, address spasticity and associated symptoms, improving patients’ quality of life.
By Technology
In terms of technology, the market includes advanced gene-editing techniques, such as CRISPR-Cas9 and AAV-based gene delivery systems, which are employed in gene therapy development for SPG50. These technologies enable precise targeting of genetic mutations responsible for the disorder, with the potential to alter disease progression. Furthermore, wearable and assistive devices are used as supportive technologies, enhancing patient mobility and independence. The integration of telemedicine platforms is also growing, providing remote monitoring and virtual therapy sessions to improve accessibility and continuity of care for patients with limited mobility.
By End User
The end-user segment consists of hospitals, specialized clinics, and research institutions. Hospitals and specialized clinics hold a substantial share, as they provide comprehensive diagnostic and therapeutic services for SPG50 patients. These facilities offer physical therapy, drug therapy, and gene therapy options as part of multidisciplinary care programs. Research institutions are critical for driving innovation in SPG50 treatments, conducting clinical trials and contributing to advancements in gene therapy. Additionally, patient advocacy organizations often collaborate with these institutions to facilitate awareness and expand access to cutting-edge treatments for SPG50 and other rare disorders.
Segmentations:
By Treatment Type- Medication
- Physiotherapy
- Surgery
- Assistive Devices
- Others
- Oral
- Injectable
- Topical
- Others
- Hospitals & Clinics
- Rehab Centers
- Home Care Settings
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the SPG50 market, accounting for approximately 40% of global revenue. The region's dominance is driven by advanced healthcare infrastructure, extensive research funding, and robust support for rare disease research. In the United States, agencies such as the National Institutes of Health (NIH) prioritize rare genetic disorders, providing grants and funding for SPG50 research and clinical trials. The presence of specialized medical centers and well-established pharmaceutical companies enables rapid progress in gene therapy and other innovative treatment modalities. Canada also contributes to the regional market with a strong emphasis on rare disease awareness and public health initiatives that support diagnostic and treatment advancements for SPG50 and other hereditary spastic paraplegias.
Europe
Europe represents around 30% of the SPG50 market, with countries such as Germany, the United Kingdom, and France at the forefront of research and treatment. The European Union’s Horizon Europe program provides funding to support research into rare diseases, including SPG50, with a focus on gene therapy and other advanced treatment methods. The European Medicines Agency (EMA) has streamlined regulatory pathways for orphan drugs, which has encouraged companies to invest in SPG50 treatments. Germany, in particular, has a well-established network of research institutions focused on neurological disorders and genetic conditions. The United Kingdom’s National Health Service (NHS) supports genetic testing and specialized care for rare diseases, increasing the accessibility of SPG50 diagnostics and therapies. These factors collectively contribute to Europe’s significant market share in SPG50 treatment development.
Asia-Pacific
The Asia-Pacific region accounts for approximately 20% of the SPG50 market and is expected to experience the fastest growth over the forecast period. Rapid advancements in healthcare infrastructure, rising healthcare expenditures, and increasing awareness of rare diseases drive the market in countries like China, Japan, and India. China, with its expanding research capabilities and government initiatives to support rare disease treatment, is emerging as a key player. The Chinese government’s Rare Diseases Catalog has increased visibility and access to treatments for conditions like SPG50, helping to foster a supportive environment for research and development. Japan’s pharmaceutical industry is also highly invested in innovative therapies, including gene therapy, supported by favorable regulatory policies from the Pharmaceuticals and Medical Devices Agency (PMDA).
Latin America
Latin America holds around 5% of the SPG50 market, with Brazil and Mexico being primary contributors. While the region faces challenges such as limited healthcare resources, ongoing efforts to improve rare disease awareness are enhancing treatment availability. In Brazil, initiatives led by the Ministry of Health focus on providing access to genetic testing and therapies for rare conditions, including SPG50. Mexico has implemented public health programs to promote genetic research and improve diagnostics. However, the region’s limited infrastructure for advanced therapies such as gene therapy means that market growth is expected to be gradual.
Middle East and Africa
The Middle East and Africa together represent approximately 5% of the global SPG50 market. Wealthier countries in the Middle East, such as Saudi Arabia and the United Arab Emirates, invest in healthcare advancements and support rare disease research, driven by government initiatives and collaborations with international health organizations. These countries are increasingly adopting advanced genetic testing and gene therapy approaches. In Africa, South Africa leads in providing rare disease treatments, although access remains limited in much of the continent due to economic constraints. Increased awareness and healthcare initiatives from global health organizations aim to improve access to diagnostic and therapeutic options, gradually expanding the region’s market presence.
Key Player Analysis:
- Pfizer
- Sanofi
- Novartis
- GlaxoSmithKline (GSK)
- Johnson & Johnson
- Merck & Co.
- AstraZeneca
- Bayer
- Boehringer Ingelheim
- Amgen
Competitive Analysis:
The Spastic Paraplegia 50 (SPG50) market is moderately competitive, with several major pharmaceutical companies such as Pfizer, Sanofi, and Novartis leading due to their strong research and development capabilities in rare diseases and gene therapy. These companies are leveraging advanced technologies, including CRISPR and adeno-associated viral vectors, to develop innovative gene therapies aimed at treating the underlying genetic mutations associated with SPG50. Emerging biotech firms like Elpida Therapeutics are also notable players, driven by specialized research on SPG50 and other hereditary spastic paraplegias. Collaborative partnerships between pharmaceutical companies and research institutions are a defining characteristic of this market, as they facilitate access to resources and expertise essential for developing targeted therapies. High barriers to entry, owing to complex regulatory requirements and significant development costs, limit new entrants, ensuring that established companies maintain a competitive edge by advancing breakthrough treatments and building on established rare disease treatment portfolios.
Recent Developments:
- In 2024, Elpida Therapeutics received FDA approval to initiate a Phase III trial for its gene therapy, Melpida, aimed at treating SPG50. This therapy, which uses an adeno-associated virus (AAV) to deliver a modified AP4M1 gene, addresses the genetic basis of the disorder. The trial, involving eight pediatric participants, is set to provide insights into the efficacy of gene therapy for SPG50, potentially paving the way for targeted, disease-modifying treatments in the rare disease landscape.
- Sanofi increased its investment in rare disease research, particularly focusing on hereditary spastic paraplegias, in 2023. This expansion includes collaborations with international genetic research institutions to enhance understanding and develop treatments for conditions like SPG50. Sanofi’s commitment aims to accelerate the discovery of targeted therapies, leveraging its expertise in neurology and genetic research to bring novel solutions to patients with rare neurological disorders.
- In 2023, Pfizer emphasized its commitment to rare neurological disorders, including SPG50, within its development pipeline. The company has expanded its research on biologics and gene therapies, exploring advanced techniques such as CRISPR-Cas9 for potential therapeutic applications. This focus is part of Pfizer’s broader strategy to address unmet medical needs in rare genetic disorders by developing innovative treatments through both in-house research and collaborations with academic partners.
- Novartis strengthened its gene therapy capabilities in 2022 by investing in new technology platforms and expanding its pipeline to include rare neurological conditions. The company’s focus on hereditary spastic paraplegias, including SPG50, reflects its strategy to apply advanced genetic research and gene-editing technologies to develop long-term solutions for rare diseases. This investment aligns with Novartis’s ongoing efforts to leverage gene therapy as a cornerstone of its treatment offerings in neurology.
Market Concentration & Characteristics:
The Spastic Paraplegia 50 (SPG50) market is moderately concentrated, with a few key players such as Pfizer, Sanofi, and Novartis driving innovation in gene therapy and rare disease treatment. These companies leverage extensive research and development capabilities to explore advanced therapies, including CRISPR and adeno-associated virus (AAV)-based gene therapies, which aim to address the genetic root causes of SPG50. The market is characterized by high barriers to entry due to the significant costs and complex regulatory requirements associated with developing treatments for rare diseases. Collaborative partnerships are also a prominent feature, as pharmaceutical companies work closely with research institutions to pool resources and expertise. Given the small patient population, companies focus on niche treatment approaches and benefit from regulatory incentives, such as orphan drug status, which provide financial support and extended market exclusivity. This environment fosters ongoing innovation, positioning major players to lead advancements in SPG50 therapeutics.
Report Coverage:
The research report offers an in-depth analysis based on Treatment Type, Route of Administration, End User, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increased investment in gene therapy research will continue, driven by promising clinical results in addressing genetic causes of SPG50.
- Advancements in CRISPR and other gene-editing technologies are expected to enhance therapeutic precision, allowing targeted modifications to treat SPG50 effectively.
- Government and regulatory incentives, such as orphan drug designations, will promote further development by offering financial support and market exclusivity.
- Collaborations between pharmaceutical companies and academic institutions will facilitate resource sharing and accelerate clinical trial progress.
- Expansion of patient advocacy and awareness initiatives will increase diagnosis rates and improve early intervention for SPG50, supporting more comprehensive patient care.
- Improved access to genetic testing will lead to earlier detection and personalized treatment plans, as healthcare systems integrate advanced diagnostics.
- Telemedicine growth will support remote management and consultation for SPG50 patients, particularly in areas with limited access to specialized care.
- Companies will explore combination therapies that include physical and drug therapies alongside gene therapy to provide holistic care options.
- Market entry of smaller biotech firms focusing on rare diseases will foster competition, spurring innovation in niche treatment solutions for SPG50.
- Ongoing advancements in assistive technologies, such as wearable devices, will support improved mobility and quality of life for SPG50 patients.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Investment in Rare Disease Research
Increased funding from governments and organizations, such as the NIH and EU, is accelerating the development of innovative therapies for SPG50. This financial support encourages pharmaceutical companies to pursue advanced treatments, including gene therapies, for this rare disorder.
Advancements in Gene Therapy and Genetic Testing
Breakthroughs in gene-editing technologies like CRISPR-Cas9 and improved genetic diagnostics are enabling earlier and more accurate identification of SPG50, as well as the development of targeted therapies that address the underlying genetic mutations.
Supportive Government Policies and Regulatory Incentives
Policies such as the U.S. Orphan Drug Act and incentives from the European Medicines Agency reduce financial risks and provide market exclusivity, motivating companies to invest in SPG50 treatment development.
Increased Awareness and Patient Advocacy
Patient advocacy groups and awareness campaigns are improving recognition of SPG50 among healthcare providers and the public, leading to earlier diagnosis, increased research funding, and greater demand for novel therapeutic options.
Expansion of Telemedicine and Digital Health Solutions
The adoption of telemedicine platforms and digital health tools is improving access to specialized care and ongoing management for SPG50 patients, particularly in regions with limited healthcare infrastructure.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Spastic Paraplegia 50 Market?
What factors are driving the growth of the Spastic Paraplegia 50 market?
What are some challenges faced by the Spastic Paraplegia 50 market?
Who are the major players in the Spastic Paraplegia 50 Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals & Clinics
- 1.2.2 Rehab Centers
- 1.2.3 Home Care Settings
- 1.3 By Treatment Type
- 1.3.1 Medication
- 1.3.2 Physiotherapy
- 1.3.3 Surgery
- 1.3.4 Assistive Devices
- 1.3.5 Others
- 1.4 By Route of Administration
- 1.4.1 Oral
- 1.4.2 Injectable
- 1.4.3 Topical
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 135.5 million → 2032: USD 292.57 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Spastic Paraplegia 50 Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Spastic Paraplegia 50 Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Spastic Paraplegia 50 Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Spastic Paraplegia 50 Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Spastic Paraplegia 50 Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Spastic Paraplegia 50 Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Spastic Paraplegia 50 Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Spastic Paraplegia 50 Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 135.5 million → 2032: USD 292.57 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Spastic Paraplegia 50 Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals & Clinics
- 12.3.7.2 Rehab Centers
- 12.3.7.3 Home Care Settings
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Treatment Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Medication
- 12.4.7.2 Physiotherapy
- 12.4.7.3 Surgery
- 12.4.7.4 Assistive Devices
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Route of Administration - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oral
- 12.5.7.2 Injectable
- 12.5.7.3 Topical
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Spastic Paraplegia 50 End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Spastic Paraplegia 50 Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Spastic Paraplegia 50 Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Spastic Paraplegia 50 Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Pfizer
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sanofi
- 18.4 Novartis
- 18.5 GlaxoSmithKline (GSK)
- 18.6 Johnson & Johnson
- 18.7 Merck & Co.
- 18.8 AstraZeneca
- 18.9 Bayer
- 18.10 Boehringer Ingelheim
- 18.11 Amgen
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

