
Market Overview:
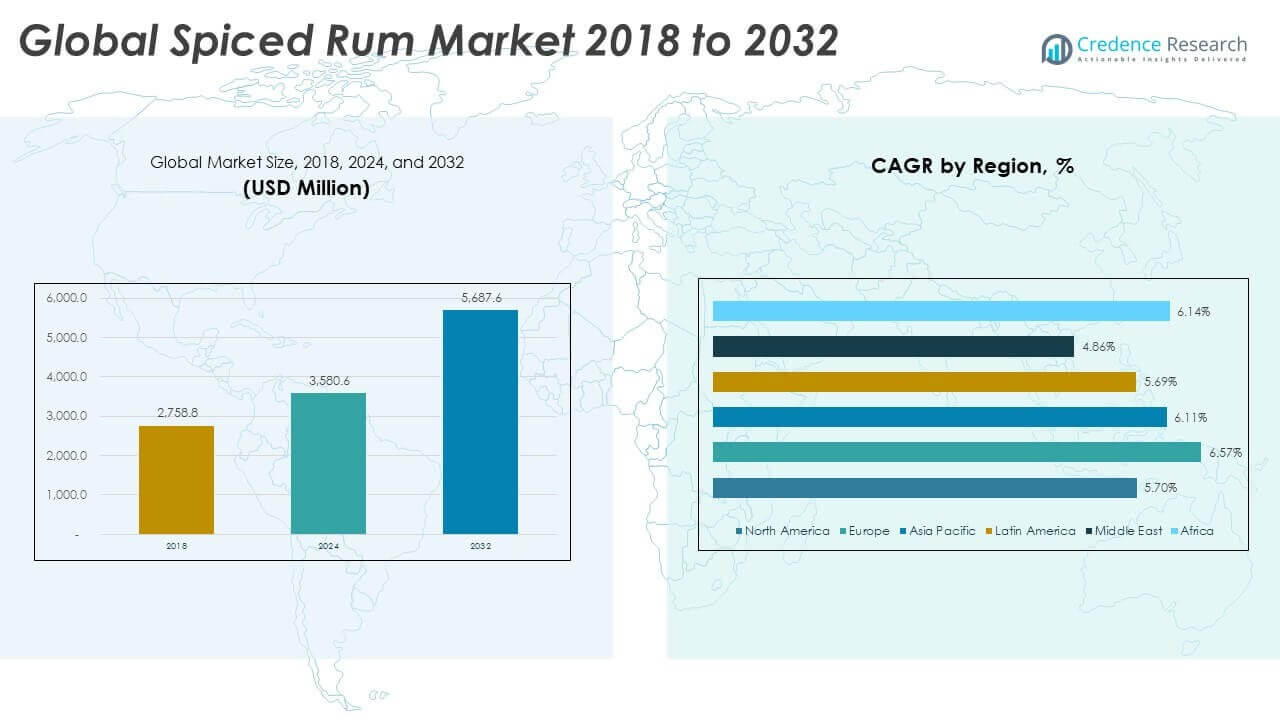
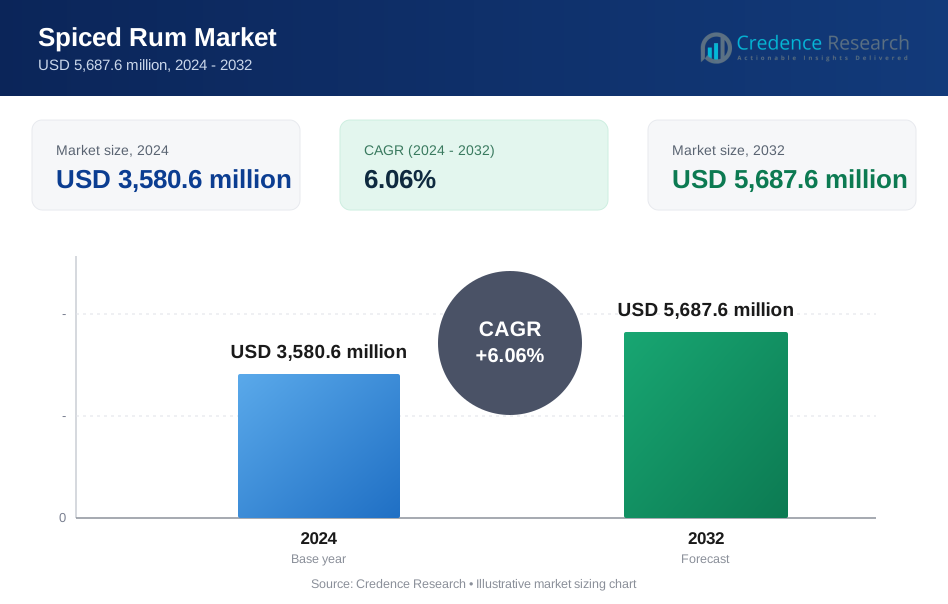
The Global Spiced Rum Market size was valued at USD 2,758.8 million in 2018 to USD 3,580.6 million in 2024 and is anticipated to reach USD 5,687.6 million by 2032, at a CAGR of 6.06% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Spiced Rum Market Size 2024 | USD 3,580.6 Million |
| Spiced Rum Market, CAGR | 6.06% |
| Spiced Rum Market Size 2032 | USD 5,687.6 Million |
Growing consumer interest in flavored spirits and premium alcoholic beverages is driving market expansion. Young adults seek unique, bold profiles that enhance cocktail experiences. Spiced rum fits this demand through its versatile blend of spices, affordability, and brand-driven identity. Premiumization trends are pushing distillers to offer small-batch and craft variants. Digital promotions, e-commerce platforms, and on-trade innovation have improved accessibility and awareness. Stronger engagement through heritage storytelling and mixology culture is deepening loyalty across both mainstream and niche audiences.
Asia Pacific leads market share due to rising disposable incomes, urban nightlife, and a shift in consumer preference toward western spirits. North America follows, driven by craft innovation and high RTD consumption. Europe remains a strong premium market with brand-conscious buyers in the UK and Germany. Latin America, the Middle East, and Africa show steady growth supported by tourism, trade expansion, and increasing acceptance of flavored alcoholic beverages. Each region plays a distinct role in the global growth landscape.
Market Insights:
- The Global Spiced Rum Market was valued at USD 2,758.8 million in 2018 and reached USD 3,580.6 million in 2024. It is projected to hit USD 5,687.6 million by 2032, growing at a CAGR of 6.06% during the forecast period.
- Asia Pacific leads the market with a 34.88% share in 2024, driven by urbanization, rising incomes, and cocktail culture in India, China, and Southeast Asia. Europe follows with 27.82%, supported by premium demand in the UK, Germany, and France. North America holds 23.63%, with strong brand presence and RTD product innovation.
- Africa is the fastest-growing region with a 6.14% CAGR, supported by expanding retail infrastructure, young demographics, and tourism-led alcohol consumption.
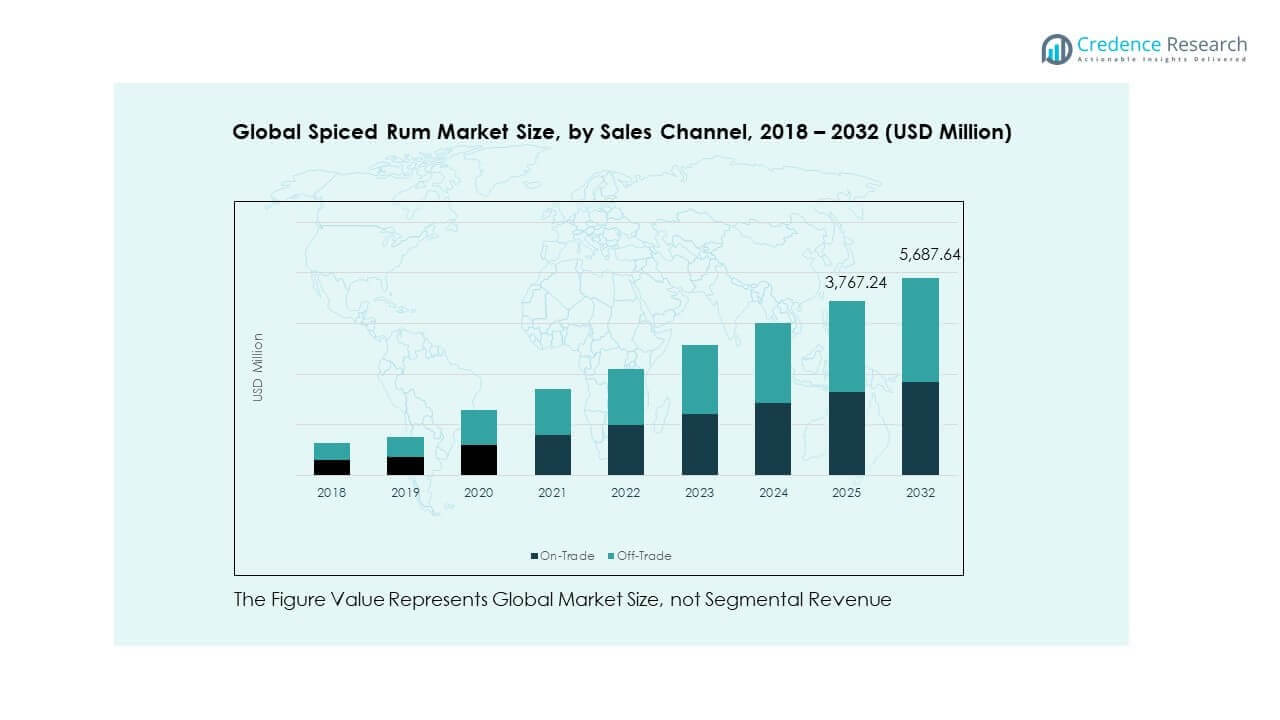
- In 2024, Off-Trade channels held 59% of the market, driven by retail stores, supermarkets, and e-commerce.
- On-Trade channels accounted for 41%, gaining momentum in bars, restaurants, and hospitality sectors post-pandemic.
Market Drivers
Rising Demand for Flavored Alcoholic Beverages Among Young Adult Consumers Worldwide
Flavored spirits continue gaining popularity among younger demographics. Consumers in their 20s and 30s seek diverse taste profiles over traditional liquors. The Global Spiced Rum Market benefits from this shift as spiced rum blends bold flavors and versatility. It appeals to casual drinkers and cocktail enthusiasts alike. Brand-driven marketing and storytelling connect with consumers seeking lifestyle alignment. These buyers look beyond ABV and price, focusing on flavor experience. The growing cocktail culture across urban bars supports this trend. Spiced rum’s adaptability in tropical and classic mixes adds value.
- For instance, Bacardi launched Bacardi Caribbean Spiced Rum in March 2023, blending aged rum with pineapple, coconut water, cinnamon, and vanilla to target cocktail enthusiasts.
Premiumization of Spirits Segment Fuels Interest in Spiced and Infused Varieties
Consumers increasingly choose premium and craft spirits that offer perceived quality and unique origins. The Global Spiced Rum Market aligns with this trend through small-batch production and aged options. Distillers introduce limited-edition bottles infused with exotic spices to cater to refined tastes. Buyers seek authenticity and ingredient traceability. Premium packaging, heritage branding, and curated tasting notes attract attention. This segment sees growth through online exclusives and subscription models. Value shifts from volume to experience, raising average selling prices. Retailers and distributors support shelf placement for premium lines.
Increased On-Trade and Off-Trade Alcohol Sales Post-COVID Boost Segment Revenues
Bars and restaurants have resumed full operations globally, driving up alcoholic beverage sales. The Global Spiced Rum Market benefits from refreshed menus and signature drinks using spiced rum as a base. On-trade settings create discovery opportunities for new consumers. Off-trade sales also surge through supermarkets, convenience stores, and e-commerce platforms. Home-mixology remains popular post-pandemic. Spiced rum’s compatibility with fruit juices, cola, and bitters makes it a staple in personal bars. Cross-promotional campaigns with mixers and ready-to-drink options improve reach. QR codes and digital recipes encourage repeat purchases.
- For instance, Captain Morgan was featured in Diageo’s 2024 RTD launch with Pepsi Max in the UK, placed across Tesco and Asda shelves, reinforcing both off-trade and at-home consumption trends.
Expanding E-Commerce and DTC Channels Widen Product Availability and Brand Reach
Brands now bypass traditional channels through direct-to-consumer platforms. The Global Spiced Rum Market leverages this shift to showcase niche offerings. Online sales allow personalization, subscriptions, and bundled deals. Digital ads target age-verified consumers based on preferences. E-commerce improves visibility for new entrants and heritage labels. Fast shipping and user reviews boost conversion rates. Global platforms facilitate cross-border sales where legal. Data analytics from online platforms guide new product development and targeted campaigns. It shortens go-to-market timeframes for emerging spiced rum lines.
Market Trends
Infusion with Unconventional Spices and Botanicals to Differentiate Brand Identity
Spiced rum makers now experiment with new flavoring agents to stand out in a crowded shelf. The Global Spiced Rum Market sees launches with chili, coffee, cardamom, saffron, and tamarind. These unconventional profiles target consumers seeking novelty and seasonal appeal. Limited-edition runs drive urgency and social media buzz. Distillers highlight local spice sourcing and heritage methods to build brand loyalty. Craft-focused labels adopt botanical infusions to mimic gin success. It expands usage across new drink formats like warm cocktails and spiced punches. Holiday themes further amplify uptake.
- For instance, Kraken Black Spiced Rum is produced using a blend of 11 natural spices, including cinnamon and clove, a formulation highlighted in brand disclosures to support its bold flavor positioning.
Partnerships with Mixologists and Bars Fuel Customized Cocktail Promotions
Collaboration between rum producers and hospitality professionals is shaping brand narratives. The Global Spiced Rum Market gains exposure through curated bar menus and signature drinks. Mixologists prefer spiced rum for its layered flavors and easy pairing with fruits and syrups. Some brands create bar-only editions or sponsor regional cocktail events. These tie-ups increase visibility and trial among upscale customers. Training programs help staff present spiced rum cocktails confidently. Brands also tap influencers to amplify cocktail content. Engagement rises when consumers can replicate recipes shared online.
Cultural Storytelling and Heritage Branding Influence Consumer Connection and Recall
Narratives rooted in regional spice trade, naval history, and island traditions build emotional ties. The Global Spiced Rum Market benefits from this trend by blending marketing with cultural depth. Brands now highlight Caribbean origins or historical rum routes in campaigns. Packaging often reflects maps, logbooks, or vintage iconography. It creates a sense of authenticity that modern consumers value. Brand websites detail distillery stories and ancestral techniques. Story-driven videos and immersive content shape perceptions. It strengthens premium positioning while inviting curiosity across age groups.
- For instance, Diplomático promotes heritage through its rum-making legacy in Venezuela, with storytelling-driven content and packaging centered around Don Juancho, tying product experience to regional authenticity.
Sustainable Packaging and Ethical Ingredient Sourcing Shape Brand Perception
Eco-conscious consumers now expect transparency in production and packaging. The Global Spiced Rum Market responds through recyclable bottles, cork stoppers, and paper-based labels. Some brands use locally sourced spices to lower emissions. Certifications for fair-trade and organic inputs influence shelf choices. Distilleries reduce water and energy use during fermentation and bottling. Marketing materials increasingly mention carbon reduction goals. Brands that invest in ethical storytelling earn repeat customers. Sustainability messaging appeals to high-income urban buyers concerned about footprint.
Market Challenges Analysis
Intense Competition from Other Flavored Spirits and Category Overlap Risks
Flavored vodka, gin, and ready-to-drink beverages compete directly with spiced rum for shelf space. The Global Spiced Rum Market struggles to maintain consumer mindshare amid overlapping options. Price promotions often favor larger players or trending spirits. Emerging brands face difficulty in establishing identity among crowded labels. Retailers prioritize fast-moving SKUs, limiting exposure for niche offerings. Brand loyalty in this segment remains volatile. Packaging similarity also creates confusion across product lines. Consumer education gaps hinder adoption in non-traditional markets. Without distinct positioning, spiced rum risks being overshadowed.
Regulatory Variations, Taxation, and Age Restrictions Affect Distribution Scope
Alcohol markets operate under fragmented regulatory landscapes. The Global Spiced Rum Market faces limitations in advertising, licensing, and cross-border transport. Import tariffs raise prices in emerging markets. Varying definitions of “spiced” under national laws affect formulation. Some countries limit permissible alcohol volumes in flavored variants. Tax hikes on spirits reduce affordability for mid-tier products. Labels must meet language and health-warning mandates. Digital marketing gets restricted in certain regions, impacting e-commerce expansion. Compliance costs strain small distilleries aiming for global presence.
Market Opportunities
Rising Popularity of Craft Spirits in Emerging Markets Across Asia and Latin America
Urban consumers in countries like India, Thailand, Brazil, and Colombia are exploring premium alcohol. The Global Spiced Rum Market can tap into this trend by positioning spiced rum as a versatile lifestyle spirit. Local events and cocktail festivals introduce new audiences to infused options. Distribution via modern trade and duty-free channels expands availability. Regional flavor adaptations enhance relevance. Influencer and digital campaigns work well in youth-centric markets. Category education through mixology workshops drives conversion. Tourism tie-ins support tasting experiences.
Product Expansion into Low-ABV and Ready-to-Drink Categories for Lifestyle Fit
Low-alcohol drinks gain favor among health-conscious buyers and casual social drinkers. The Global Spiced Rum Market holds potential in launching 4–6% ABV premixed formats. RTDs with tropical fruit and spice blends match light-drinking occasions. Slim cans and small bottles suit on-the-go consumption. These products appeal in warm-climate countries and event settings. Bars can promote them as alternatives to beer or cider. Brands reduce entry barriers by offering sampler packs. Packaging innovation supports impulse buying at retail counters.
Market Segmentation Analysis:
By Product Segment
The Global Spiced Rum Market is segmented into traditional, flavored, premium, craft, and RTD variants. Traditional spiced rum maintains strong loyalty among mature consumers. Flavored spiced rum is gaining momentum, supported by younger drinkers seeking variety. Premium and super-premium products appeal to quality-conscious buyers, often favoring aged blends. Craft and small-batch variants see steady growth through storytelling, authenticity, and local sourcing. RTD and cocktail-based offerings expand rapidly, driven by demand for convenience and on-the-go consumption, especially in urban regions.
By Consumer Segment
Millennials represent the dominant buyer group, fueling market expansion through flavor exploration and premium interest. Gen-Z consumers are emerging as a key cohort, especially in legal-age markets with vibrant nightlife and social media influence. Premium and lifestyle-led consumers favor exclusive, well-branded products aligned with aspirational living. Value-driven consumers continue supporting affordable segments, especially in off-trade retail and entry-level offerings. The Global Spiced Rum Market caters to a wide spectrum of drinking preferences, making tailored positioning essential.
- For instance, Pernod Ricard introduced Seagram’s Xclamat!on rum portfolio in India in December 2025, specifically targeting young consumers with bold packaging and lifestyle marketing.
By Price Tier Segment
Economy and mid-range tiers remain critical for volume, with strong presence in developing markets. Premium and craft segments command higher margins and reflect the shift toward quality and brand engagement. Luxury and limited-edition labels serve niche collectors and gift-oriented buyers. It sustains a balanced portfolio across pricing brackets, allowing brands to target both mass-market and discerning audiences.
- For instance, Diplomático’s Distillery Collection features limited releases like No. 3 Pot Still Rum, appealing to connoisseurs in the super-premium tier through specialty retail and curated online drops.
By Sales Channel Segment
Off-trade dominates through supermarkets, liquor chains, and rising e-commerce channels. Online platforms expand access, especially in Tier 1 and Tier 2 cities. On-trade gains traction post-pandemic, with bars and pubs using spiced rum in signature mixes. Hotels and tourism-led outlets also contribute to premium product visibility.
Segmentation:
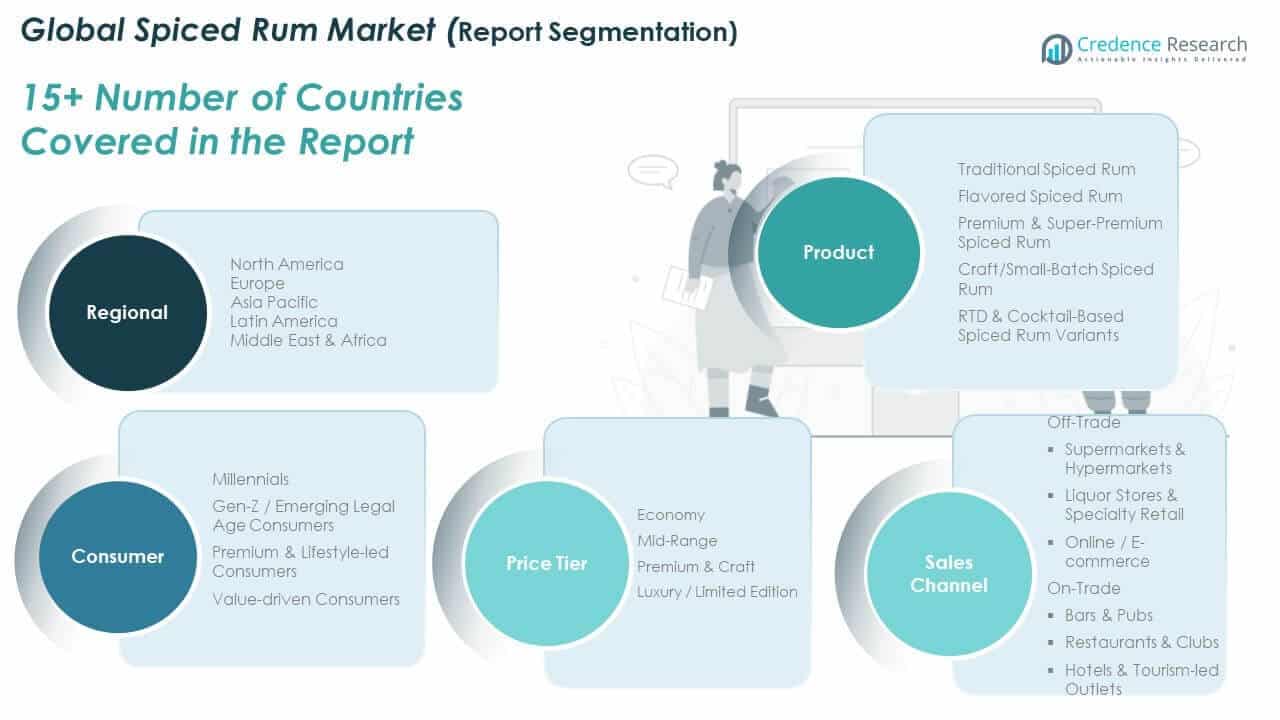
By Product Segment
- Traditional Spiced Rum
- Flavored Spiced Rum
- Premium & Super-Premium Spiced Rum
- Craft/Small-Batch Spiced Rum
- RTD & Cocktail-Based Spiced Rum Variants
By Consumer Segment
- Millennials
- Gen-Z / Emerging Legal Age Consumers
- Premium & Lifestyle-led Consumers
- Value-driven Consumers
By Price Tier Segment
- Economy
- Mid-Range
- Premium & Craft
- Luxury / Limited Edition
By Sales Channel Segment
- Off-Trade
- Supermarkets & Hypermarkets
- Liquor Stores & Specialty Retail
- Online / E-commerce
- On-Trade
- Bars & Pubs
- Restaurants & Clubs
- Hotels & Tourism-led Outlets
By Region
- North America (U.S., Canada, Mexico)
- Europe (UK, France, Germany, Italy, Spain, Russia, Rest of Europe)
- Asia Pacific (China, Japan, South Korea, India, Australia, Southeast Asia, Rest of APAC)
- Latin America (Brazil, Argentina, Rest of Latin America)
- Middle East (GCC Countries, Israel, Turkey, Rest of Middle East)
- Africa (South Africa, Egypt, Rest of Africa)
Regional Analysis:
North America
The North America Global Spiced Rum Market size was valued at USD 665.14 million in 2018 to USD 846.25 million in 2024 and is anticipated to reach USD 1,308.16 million by 2032, at a CAGR of 5.70% during the forecast period. North America accounts for 23.63% of the global market share in 2024. The region is driven by a strong cocktail culture, premiumization trends, and consumer preference for flavored spirits. The U.S. remains the largest contributor, followed by Canada and Mexico. Consumers in urban areas show high engagement with craft and RTD variants. Spiced rum brands collaborate with bars and restaurants to offer unique flavor profiles and seasonal promotions. E-commerce expansion has enabled niche labels to reach younger audiences. It benefits from well-developed distribution networks and a mature spirits consumption base. Private-label and mid-range offerings also perform well in mass retail.
Europe
The Europe Global Spiced Rum Market size was valued at USD 744.87 million in 2018 to USD 995.92 million in 2024 and is anticipated to reach USD 1,643.73 million by 2032, at a CAGR of 6.57% during the forecast period. Europe holds a 27.82% market share in 2024, making it a key region for global players. The UK leads in consumption, followed by Germany, France, and Spain. Consumers in Western Europe show high interest in heritage branding and super-premium variants. Flavored rum is gaining ground among Gen-Z buyers, often supported by digital campaigns. Traditional spiced rum maintains traction among older demographics. Duty-free and travel retail contribute to tourist-driven demand. Local distilleries in Eastern Europe are introducing craft alternatives. It benefits from diversified consumer segments and strong retail coverage.
Asia Pacific
The Asia Pacific Global Spiced Rum Market size was valued at USD 959.50 million in 2018 to USD 1,248.71 million in 2024 and is anticipated to reach USD 1,990.68 million by 2032, at a CAGR of 6.11% during the forecast period. Asia Pacific contributes 34.88% of the global market share in 2024, making it the largest regional market. India, China, and Southeast Asia are key growth drivers due to rising disposable incomes and urban nightlife expansion. The premium segment is growing across metros, while flavored and RTD variants perform well among younger consumers. Distribution is expanding through modern retail and foodservice channels. Tourism and social media influence elevate interest in western drinking patterns. Domestic brands are introducing local spice blends to attract regional buyers. It shows strong long-term potential due to population size and evolving tastes.
Latin America
The Latin America Global Spiced Rum Market size was valued at USD 205.53 million in 2018 to USD 261.38 million in 2024 and is anticipated to reach USD 403.82 million by 2032, at a CAGR of 5.69% during the forecast period. Latin America holds a 7.30% share of the global market in 2024. Brazil leads consumption, followed by Argentina and Colombia. Consumers are receptive to spiced rum due to existing rum culture and warm climate. Mid-range and flavored variants dominate, while premium offerings are gaining presence in urban centers. RTDs have picked up traction through event-based marketing. Distribution is concentrated in supermarkets, with e-commerce slowly growing. Local festivals and tourism influence seasonal demand. It remains price-sensitive but brand-aware.
Middle East
The Middle East Global Spiced Rum Market size was valued at USD 131.87 million in 2018 to USD 160.72 million in 2024 and is anticipated to reach USD 233.19 million by 2032, at a CAGR of 4.86% during the forecast period. The region represents 4.49% of the global market share in 2024. Growth is led by the UAE and Israel, supported by high-end hospitality and duty-free sales. Consumption is limited to licensed zones but sees steady growth in tourism-driven hubs. Luxury hotels and bars are primary outlets for premium spiced rum. Online sales remain restricted due to legal frameworks. Craft and RTD segments are underdeveloped. Product availability depends heavily on imported brands. It holds potential in select high-income urban centers.
Africa
The Africa Global Spiced Rum Market size was valued at USD 51.87 million in 2018 to USD 67.62 million in 2024 and is anticipated to reach USD 108.07 million by 2032, at a CAGR of 6.14% during the forecast period. Africa accounts for 1.89% of the global market share in 2024. South Africa leads regional sales, followed by Egypt and Kenya. Informal markets and local spirits still dominate, though branded spiced rum is growing. Mid-range products are most common, with rising interest in RTDs. Youth demographics and urbanization support long-term demand. Distribution is improving through modern retail and tourism venues. Flavor innovation and small-batch imports attract premium buyers. It remains a developing but promising region.
Key Player Analysis:
- Diageo plc
- Proximo Spirits
- Bacardi Limited
- William Grant & Sons
- Halewood Artisanal Spirits
- Sazerac Co. Inc.
- Pernod Ricard
- Sanghera Rum Co.
- Other Key Players
Competitive Analysis:
The Global Spiced Rum Market features a mix of legacy players and emerging craft distillers. Diageo, Bacardi, and Pernod Ricard lead the space through broad distribution, high brand recall, and diverse product portfolios. Companies like Proximo Spirits and William Grant & Sons strengthen mid-tier and premium offerings with region-specific labels. Craft entrants such as Halewood Artisanal Spirits and Sanghera Rum Co. target niche segments with limited batches and unique spice blends. It remains fragmented, with top five players holding a moderate share due to rising competition from private labels and RTD innovations. Mergers, new launches, and bar partnerships drive visibility and volume. Branding, heritage storytelling, and flavor innovation shape differentiation. Players expand across on-trade and off-trade channels while boosting online presence for direct consumer reach. Competitive intensity is increasing across regions, especially in premium and flavored segments.
Recent Developments:
- In December 2025, Pernod Ricard launched Seagram's Xclamat!on rum, blending Jamaican rum with Indian jaggery rum as part of a five-spirit premium portfolio targeting young consumers in India with phased nationwide rollout.
- In September 2024, Diageo plc partnered with PepsiCo to launch a ready-to-drink (RTD) product featuring Captain Morgan Original Spiced Rum and Pepsi Max, available immediately in Great Britain at major retailers like Tesco and Asda.
Report Coverage:
The research report offers an in-depth analysis based on Product Segment, Consumer Segment, Price Tier Segment, Sales Channel Segment and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for flavored and infused spirits will continue to push product diversification.
- Premium and super-premium categories are expected to gain share through quality and branding efforts.
- E-commerce and DTC sales channels will accelerate market penetration across underserved regions.
- RTD and cocktail-based variants will see strong traction in urban and on-the-go consumption settings.
- Younger demographics, including Gen-Z, will influence product innovation and marketing narratives.
- Craft and small-batch producers will gain ground by offering authenticity and local sourcing stories.
- Global players will focus on mergers, limited-edition releases, and bar partnerships for market consolidation.
- Growth in Asia Pacific will remain strong due to rising incomes, urban nightlife, and evolving tastes.
- Sustainability in packaging and ethical ingredient sourcing will shape consumer preferences and loyalty.
- On-trade recovery and tourism rebound will support premium visibility and experiential marketing worldwide.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Popularity of Flavored and Infused Spirits Among Young Adults
Younger consumers, especially Millennials and Gen-Z, are increasingly seeking unique, bold flavors and cocktail experiences, making spiced rum - with its versatile spice blends and mixability - a preferred choice in both casual and premium settings.
Premiumization and Craft Innovation
Rising consumer interest in premium, small-batch, and craft spirits is driving distillers to launch higher-quality, limited-edition spiced rums with authentic ingredients and heritage branding, which elevates average selling prices and attracts discerning buyers.
Expansion of E-Commerce and Direct-to-Consumer Channels
The growth of online retail and DTC platforms has made spiced rum more accessible, allowing brands to reach new audiences, offer personalized experiences, and quickly launch niche or limited-run products, especially in urban and emerging markets.
On-Trade Recovery and Cocktail Culture Resurgence
Post-pandemic reopening of bars, restaurants, and hospitality venues has boosted on-trade sales, with spiced rum featured in signature cocktails and seasonal promotions, increasing trial and brand engagement among urban consumers.
Regional Growth in Asia Pacific and Africa
Rising disposable incomes, urbanization, and evolving nightlife in Asia Pacific, along with expanding retail infrastructure and young demographics in Africa, are accelerating spiced rum adoption and driving robust regional market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Spiced Rum Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Spiced Rum Market projected to grow between 2024 and 2032?
Which Global Spiced Rum Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Spiced Rum Market?
Who are the leading companies in the Global Spiced Rum Market?
Which region commanded the largest share of the Global Spiced Rum Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Segment
- 1.2.1 Traditional Spiced Rum
- 1.2.2 Flavored Spiced Rum
- 1.2.3 Premium & Super-Premium Spiced Rum
- 1.2.4 Craft/Small-Batch Spiced Rum
- 1.2.5 RTD & Cocktail-Based Spiced Rum Variants
- 1.3 By Consumer Segment
- 1.3.1 Millennials
- 1.3.2 Gen-Z / Emerging Legal Age Consumers
- 1.3.3 Premium & Lifestyle-led Consumers
- 1.3.4 Value-driven Consumers
- 1.4 By Price Tier Segment
- 1.4.1 Economy
- 1.4.2 Mid-Range
- 1.4.3 Premium & Craft
- 1.4.4 Luxury / Limited Edition
- 1.5 By Sales Channel Segment
- 1.5.1 Off-Trade (Supermarkets & Hypermarkets, Liquor Stores & Specialty Retail, Online / E-commerce)
- 1.5.2 On-Trade (Bars & Pubs, Restaurants & Clubs, Hotels & Tourism-led Outlets)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,580.6 million → 2032: USD 5,687.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Spiced Rum Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Spiced Rum Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Spiced Rum Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Spiced Rum Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Spiced Rum Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Spiced Rum Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Spiced Rum Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Spiced Rum Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,580.6 million → 2032: USD 5,687.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Spiced Rum Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Segment - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Traditional Spiced Rum
- 12.3.7.2 Flavored Spiced Rum
- 12.3.7.3 Premium & Super-Premium Spiced Rum
- 12.3.7.4 Craft/Small-Batch Spiced Rum
- 12.3.7.5 RTD & Cocktail-Based Spiced Rum Variants
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Consumer Segment - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Millennials
- 12.4.7.2 Gen-Z / Emerging Legal Age Consumers
- 12.4.7.3 Premium & Lifestyle-led Consumers
- 12.4.7.4 Value-driven Consumers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Price Tier Segment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Economy
- 12.5.7.2 Mid-Range
- 12.5.7.3 Premium & Craft
- 12.5.7.4 Luxury / Limited Edition
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Channel Segment - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Off-Trade (Supermarkets & Hypermarkets, Liquor Stores & Specialty Retail, Online / E-commerce)
- 12.6.7.2 On-Trade (Bars & Pubs, Restaurants & Clubs, Hotels & Tourism-led Outlets)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Spiced Rum Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Spiced Rum Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Spiced Rum Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Diageo plc
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Bacardi Limited
- 17.4 Pernod Ricard
- 17.5 Proximo Spirits
- 17.6 William Grant & Sons
- 17.7 Halewood Artisanal Spirits
- 17.8 Sazerac Co. Inc.
- 17.9 Sanghera Rum Co.
- 17.10 Campari Group
- 17.11 Heaven Hill Brands
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

