
Styrene Petrochemicals Market Overview:
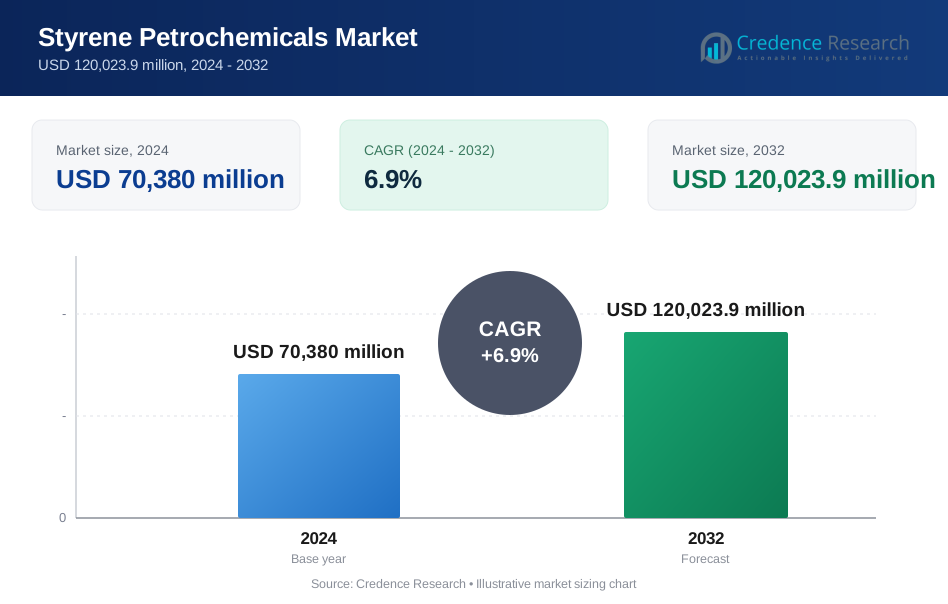
The Styrene Petrochemicals market size was valued at USD 70,380 million in 2024 and is anticipated to reach USD 120,023.9 million by 2032, at a CAGR of 6.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Styrene Petrochemicals Market Size 2024 | USD 70,380 million |
| Styrene Petrochemicals Market, CAGR | 6.9% |
| Styrene Petrochemicals Market Size 2032 | USD 120,023.9 million |
The Styrene Petrochemicals market is led by major players including INEOS, SABIC, BASF SE, Dow Chemical Company, Reliance Industries Limited, Covestro AG, Formosa Plastics Corporation, and Chevron Phillips Chemical Company. These companies dominate through integrated operations, wide product portfolios, and regional production hubs. INEOS and SABIC maintain strong global reach, while BASF and Dow focus on specialty derivatives and sustainable innovations. Asia-Pacific holds the largest regional share, accounting for 45.3% of the global market in 2024, driven by high consumption in China, India, and Southeast Asia. North America and Europe follow, supported by mature end-use industries and technological advancements. Strategic expansions, feedstock optimization, and circular economy initiatives remain central to competitive positioning.

Styrene Petrochemicals Market Insights
- The Styrene Petrochemicals market was valued at USD 70,380 million in 2024 and is projected to reach USD 120,023.9 million by 2032, growing at a CAGR of 6.9%.
- Growth is driven by rising demand from packaging, automotive, and consumer electronics sectors, with polystyrene holding over 35% share by product type.
- A key trend is the shift toward recyclable and sustainable styrenics, supported by investments in chemical recycling and bio-based production by major players like INEOS and Covestro.
- The market faces restraints due to raw material price volatility and growing regulatory pressure on styrene-based products related to toxicity and plastic waste.
- Asia-Pacific leads with 45.3% market share, followed by North America at 20% and Europe at 18%; packaging remains the top end-user segment, accounting for over 30% of total demand.
Styrene Petrochemicals Market Segmentation Analysis:
By Product Type
Polystyrene holds the largest share in the Styrene Petrochemicals market, accounting for over 35% of the total volume in 2024. Its dominance stems from widespread use in packaging, insulation, and disposable consumer goods. Lightweight, rigidity, and cost-effectiveness support its popularity across industrial applications. Acrylonitrile Butadiene Styrene (ABS) follows, driven by demand in electronics and automotive interiors due to its impact resistance and glossy finish. Styrene Butadiene Rubber (SBR) remains crucial in tire production, supported by consistent automotive output. Other product types cater to niche uses in adhesives, paints, and insulation foams.
- For instance, INEOS Styrolution produces general-purpose polystyrene with melt flow rates between 2 and 8 g/10 min for food trays and protective packaging.
By End-User Industry
Packaging emerged as the leading end-user segment in 2024, representing over 30% of the Styrene Petrochemicals market. High-volume use of polystyrene and styrene copolymers in food containers, trays, and cushioning material drives the segment. The construction sector follows closely due to its use of expanded polystyrene in insulation and soundproofing. Consumer goods and electronics also contribute significantly, especially through durable housing materials for appliances and gadgets. The automotive and transportation segment leverages ABS and SBR in interiors and tire manufacturing. Other end-users include medical and furniture industries with specialized material demands.
- For instance, TotalEnergies supplies expandable polystyrene beads with expansion densities as low as 10 kg/m³ for food containers and cushioning.
By Distribution Channel
The offline distribution channel dominates the market, accounting for more than 80% of total sales in 2024. Bulk procurement by industrial buyers through authorized distributors, petrochemical suppliers, and chemical resellers supports this lead. Long-term contracts and material safety regulations further reinforce the preference for offline sourcing. However, the online channel is gaining momentum, especially among small and mid-sized processors seeking price visibility and flexible ordering. Digital marketplaces and B2B platforms are expanding their footprint by offering delivery tracking, certification support, and product comparisons, enhancing reach among emerging regional buyers.
Styrene Petrochemicals Market Key Growth Drivers
Rising Demand from Packaging and Consumer Goods Industries
The packaging and consumer goods sectors are key growth engines for the styrene petrochemicals market. Polystyrene and styrene-based copolymers are widely used in protective packaging, disposable containers, insulation foams, and consumer products due to their lightweight and durable nature. The shift toward single-use packaging in food service, healthcare, and e-commerce has accelerated styrene consumption globally. Emerging economies in Asia-Pacific, particularly China and India, are witnessing rapid urbanization and lifestyle changes, fueling demand for packaged products. This trend supports steady volume growth for styrene derivatives. Moreover, global brands are expanding their product lines with innovative designs using polystyrene and ABS, particularly in cost-sensitive markets.
- For instance, INEOS Styrolution supplies crystal polystyrene grades with density near 1.05 g/cm³ for food containers and protective trays.
Expansion of Automotive and Construction Sectors
Styrene-based materials play a vital role in the automotive and construction industries, both of which are expanding steadily across emerging and developed economies. Acrylonitrile Butadiene Styrene (ABS) and Styrene Butadiene Rubber (SBR) are extensively used in automotive interiors, dashboards, exterior trims, and tire manufacturing. Their impact resistance, design flexibility, and thermal stability make them ideal for lightweight vehicle designs. Simultaneously, expanded polystyrene is widely used in construction insulation, roofing, and soundproofing. Green building codes and energy-efficiency standards are prompting developers to adopt materials with strong insulation properties, thereby driving demand for styrene-based foams. Government-backed infrastructure programs in South Asia, Southeast Asia, and the Middle East are creating steady construction material demand.
- For instance, Synthos manufactures SBR grades for tires with tensile strength exceeding 20 MPa for passenger vehicles.
Growing Penetration of Electronics and Appliance Manufacturing
The growth of electronics, appliances, and electrical equipment manufacturing is boosting demand for styrene-based polymers. ABS is the material of choice for casings, housings, connectors, and structural components in devices such as laptops, TVs, washing machines, and HVAC units. Its excellent aesthetic finish, dimensional stability, and processability make it ideal for high-volume production. Consumer electronics brands increasingly focus on lightweight, ergonomic, and durable designs, where styrene polymers outperform metal and other rigid plastics in terms of cost and flexibility. Additionally, rising appliance ownership in emerging markets and increased replacement rates in developed economies contribute to higher consumption. Government initiatives to boost domestic electronics manufacturing, such as India's PLI schemes and Vietnam’s FDI-friendly policies, are creating robust downstream demand for styrene derivatives.
Styrene Petrochemicals Market Key Trends & Opportunities
Shift Toward Recyclable and Sustainable Styrenics
Sustainability is reshaping the styrene petrochemicals market, creating opportunities for recyclable and bio-based alternatives. While styrene-based materials have long faced criticism for environmental persistence, new recycling technologies are addressing these concerns. Chemical recycling of polystyrene into monomers allows closed-loop production, helping reduce raw material dependency and emissions. Industry players such as INEOS Styrolution and Trinseo are investing in circular economy solutions to meet regulatory and consumer expectations. Bio-based styrene production from renewable feedstocks is gaining attention as part of long-term decarbonization strategies. Additionally, lightweight styrenic foams help reduce energy consumption in construction and transportation, aligning with global climate goals. As sustainability-linked investments and ESG reporting gain momentum, companies adopting recyclable styrenics are likely to gain market share.
- For instance, INEOS Styrolution operates chemical recycling (depolymerization) that converts polystyrene waste back into its original building block, styrene monomer, with a purity level exceeding 99.9%.
Strategic Capacity Expansions and Regional Shifts
Production capacity expansions in Asia-Pacific and the Middle East are reshaping global styrene supply chains. China remains the largest consumer and producer of styrene monomer, and companies are expanding integrated facilities to serve downstream demand in packaging, electronics, and automotive segments. Recent capacity additions in Zhejiang and Jiangsu aim to reduce import dependence and serve high-growth regional markets. Middle Eastern petrochemical firms are leveraging low-cost feedstocks and export-focused production to gain global market share. Strategic joint ventures and technology partnerships are helping companies expand styrenics production efficiently. At the same time, Western producers are shifting focus toward value-added copolymers and recycled grades.
Styrene Petrochemicals Market Key Challenges
Volatility in Feedstock Prices and Supply Chain Disruptions
Styrene production depends heavily on key petrochemical feedstocks such as benzene and ethylene, both of which are subject to high price volatility. Fluctuating crude oil prices, refinery outages, and supply disruptions from geopolitical tensions affect raw material availability and cost structures. This volatility impacts margins for styrene producers and downstream converters, especially in price-sensitive applications like packaging and automotive. Global trade routes for styrene monomer and derivatives also face disruption from container shortages, port congestion, and shifting trade policies. The market's reliance on specific regions such as China, South Korea, and the Middle East for bulk production exposes it to localized risks.
Environmental Regulations and Plastic Waste Concerns
Environmental concerns around plastic waste and styrene’s toxicity pose regulatory risks for market participants. Governments and environmental agencies worldwide are tightening controls on single-use plastics and expanding compliance obligations for petrochemical manufacturers. The European Union’s REACH regulations and restrictions on expanded polystyrene in packaging and food-contact applications highlight growing scrutiny. Additionally, styrene monomer has been classified as a potential human carcinogen by regulatory bodies like the IARC, which has triggered stricter handling and labeling mandates. These factors pressure producers to shift toward safer, recyclable alternatives, incurring R&D and retrofitting costs. Public opposition to non-degradable plastics also affects brand perception in consumer-facing sectors.
Styrene Petrochemicals Market Regional Analysis
Asia-Pacific
Asia-Pacific dominates the styrene petrochemicals market with over 45% share in 2024, driven by strong demand across packaging, construction, automotive, and consumer electronics sectors. China remains the largest contributor, supported by its vast manufacturing base and integrated petrochemical facilities. India, South Korea, and Southeast Asian countries also show rapid growth due to rising urbanization and infrastructure spending. Major producers are expanding styrene monomer and derivative capacities to meet domestic and export demand. The region benefits from cost-effective feedstock, competitive labor, and government-backed industrialization programs, positioning it as a global hub for styrene-based product manufacturing.
North America
North America holds around 20% market share in the global styrene petrochemicals industry, supported by well-established automotive, construction, and packaging sectors. The U.S. leads regional demand with high consumption of ABS and polystyrene in appliances, consumer goods, and insulation applications. Advanced recycling infrastructure and sustainability initiatives are fostering interest in circular styrenics. Market players focus on specialty grades and performance-enhancing additives to meet evolving customer needs. While domestic demand remains steady, exports to Latin America and Asia support production volumes. Regulatory compliance and technological innovation play a central role in maintaining regional competitiveness.
Europe
Europe accounts for approximately 18% of the global styrene petrochemicals market, characterized by mature demand and a strong focus on sustainability. Key applications include insulation materials in construction, lightweight components in automotive, and rigid packaging. Germany, France, and Italy lead consumption, with many producers transitioning toward recycled and bio-based styrene materials. Strict EU regulations and environmental standards are pushing manufacturers to innovate in waste recovery and closed-loop solutions. The region’s advanced infrastructure and policy-driven incentives support adoption of eco-friendly derivatives, although high energy costs and regulatory burdens present ongoing challenges for profitability and expansion.
Middle East & Africa
The Middle East & Africa region holds about 8% of the global market share, supported primarily by the Middle East’s strong petrochemical base and low-cost feedstock advantage. Countries like Saudi Arabia and the UAE continue to invest in integrated styrene production facilities as part of broader diversification strategies. Demand is driven by construction, automotive components, and growing packaging needs in urbanizing economies. Africa remains an emerging market, with rising consumption of affordable consumer goods and infrastructure products. However, limited local production and import dependency restrict regional growth potential, creating opportunities for regional expansion.
Latin America
Latin America captures around 7% of the global styrene petrochemicals market, with Brazil and Mexico leading consumption across automotive, consumer goods, and packaging sectors. Domestic production is limited, leading to a reliance on imports for both styrene monomer and derivatives. Rising middle-class consumption and increasing investment in manufacturing support regional demand growth. Governments are gradually pushing sustainability initiatives, encouraging local players to explore recyclable and cost-effective materials. However, supply chain constraints and economic volatility pose challenges. Strategic collaborations and regional trade agreements are helping improve market access and reduce dependency on external suppliers.
Styrene Petrochemicals Market Segmentations:
By Product Type
- Polystyrene
- Acrylonitrile Butadiene Styrene
- Styrene Butadiene Rubber
- Other product types
By End-User Industry
- Packaging
- Construction
- Consumer Goods
- Automotive and Transportation
- Electrical and Electronics
- Other end-user industries
By Distribution Channel
- Offline
- Online
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Styrene Petrochemicals market is highly competitive and features a blend of global chemical giants and regionally focused players. Key companies include INEOS, BASF SE, Shell Plc, SABIC, Dow Chemical Company, Covestro AG, and Reliance Industries Limited. These firms compete on production scale, feedstock integration, product innovation, and global distribution networks. INEOS and BASF leverage their integrated manufacturing and supply chain strengths, while Dow and Covestro focus on specialty styrenics and sustainability. Companies like Formosa Plastics and Nova Chemicals strengthen their regional presence through capacity expansions. Strategic alliances, R&D investments in recyclable styrenics, and forward integration remain core competitive strategies. Players are also shifting focus toward lightweight and durable applications in automotive, electronics, and packaging to capture value-added margins. As regulatory scrutiny and sustainability demands grow, firms with circular product portfolios and efficient operations are expected to retain a long-term edge. Market concentration remains moderate with continuous reshuffling based on innovation and regional demand shifts.
Key Player Analysis
- Covestro AG
- Chevron Phillips Chemical Company, LLC
- Nova Chemicals Corporation
- Repsol
- Formosa Plastics Corporation
- INEOS
- Oil Corporation Limited
- SABIC
- Alpek SAB DE CV
- Bayer Material Science, LLC
- Dow Chemical Company
- Toray Industries, Inc.
- Reliance Industries Limited
- BASF SE
- Shell Plc
Recent Developments
- In November 2025, Trinseo announced the availability of polystyrene (PS), ABS, and SAN resins made from chemically recycled styrene monomer (rSM) sourced from a new recycling facility by partner Indaver in Antwerp, Belgium. The plant, operational since August 2025, focuses on recovering styrene from post-consumer polystyrene packaging waste.
- In September 2025, the first truckloads of recycled styrene monomers arrived at INEOS Styrolution's Antwerp site, supplied by Indaver from its depolymerization facility, the first dedicated to polystyrene recycling in Europe.
- In 2025, Denka Company Limited launched its D-NODE brand to promote the recycling and remanufacturing of styrene materials as part of its commitment to sustainability.
Report Coverage
The research report offers an in-depth analysis based on Product Type, End-User Industry, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for polystyrene and ABS will grow steadily across packaging and automotive industries.
- Recyclable and bio-based styrenics will gain market share due to regulatory pressure.
- Asia-Pacific will remain the dominant region, led by China and India’s industrial expansion.
- Investments in chemical recycling technologies will strengthen circular economy practices.
- Consumer electronics growth will support increased use of high-performance styrenic polymers.
- Capacity expansions in the Middle East and Asia will reshape global supply chains.
- Stringent environmental norms will push innovation in low-emission production processes.
- Strategic mergers and partnerships will improve global market positioning for key players.
- Lightweight and energy-efficient construction materials will drive demand for styrene foams.
- E-commerce and food delivery sectors will continue to support growth in disposable packaging.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in Packaging and Consumer Goods
The increasing use of polystyrene and styrene-based copolymers in protective packaging, disposable containers, and consumer products is fueling market expansion, especially in food service, healthcare, and e-commerce sectors. Rapid urbanization and rising packaged goods consumption in Asia-Pacific further accelerate this trend.
Expansion of Automotive and Construction Sectors
Styrene derivatives like ABS and SBR are essential for lightweight automotive components and tire manufacturing, while expanded polystyrene is widely used for insulation in construction. Infrastructure development and green building initiatives in emerging markets are driving demand for these materials.
Rising Electronics and Appliance Manufacturing
ABS and other styrenics are increasingly used in casings and structural parts for electronics and appliances due to their durability and design flexibility. Growth in consumer electronics ownership and domestic manufacturing incentives in Asia are boosting styrene consumption.
Shift Toward Recyclable and Sustainable Styrenics
Regulatory pressure and consumer demand for sustainability are prompting investments in chemical recycling and bio-based styrene production. Companies adopting circular economy practices and recyclable styrenics are gaining competitive advantage and expanding their market share.
Strategic Capacity Expansions in Asia-Pacific and Middle East
Major investments in new production facilities and integrated complexes in China, Southeast Asia, and the Middle East are reshaping global supply chains, reducing import dependence, and supporting regional demand growth for styrene petrochemicals.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Styrene Petrochemicals market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Styrene Petrochemicals market projected to grow between 2024 and 2032?
Which Styrene Petrochemicals market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Styrene Petrochemicals market?
Who are the leading companies in the Styrene Petrochemicals market?
Which region commanded the largest share of the Styrene Petrochemicals market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Polystyrene
- 1.2.2 Acrylonitrile Butadiene Styrene
- 1.2.3 Styrene Butadiene Rubber
- 1.2.4 Other product types
- 1.3 By End-User Industry
- 1.3.1 Packaging
- 1.3.2 Construction
- 1.3.3 Consumer Goods
- 1.3.4 Automotive and Transportation
- 1.3.5 Electrical and Electronics
- 1.3.6 Other end-user industries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 70,380 million → 2032: USD 120,023.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Styrene Petrochemicals Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Styrene Petrochemicals Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Styrene Petrochemicals Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Styrene Petrochemicals Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Styrene Petrochemicals Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Styrene Petrochemicals Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Styrene Petrochemicals Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Styrene Petrochemicals Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 70,380 million → 2032: USD 120,023.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Styrene Petrochemicals Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Polystyrene
- 12.3.7.2 Acrylonitrile Butadiene Styrene
- 12.3.7.3 Styrene Butadiene Rubber
- 12.3.7.4 Other product types
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Packaging
- 12.4.7.2 Construction
- 12.4.7.3 Consumer Goods
- 12.4.7.4 Automotive and Transportation
- 12.4.7.5 Electrical and Electronics
- 12.4.7.6 Other end-user industries
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Styrene Petrochemicals End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Styrene Petrochemicals Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Styrene Petrochemicals Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Styrene Petrochemicals Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 INEOS
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 SABIC
- 18.4 BASF SE
- 18.5 Dow Chemical Company
- 18.6 Covestro AG
- 18.7 Reliance Industries Limited
- 18.8 Formosa Plastics Corporation
- 18.9 Chevron Phillips Chemical Company
- 18.10 Nova Chemicals Corporation
- 18.11 Shell Plc
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

