
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Super Capacitors and Ultra Capacitors Market Size 2024 | USD 5,165 Million |
| Super Capacitors and Ultra Capacitors Market, CAGR | 20.25% |
| Super Capacitors and Ultra Capacitors Market Size 2032 | USD 22,581.4 Million |
Market Overview
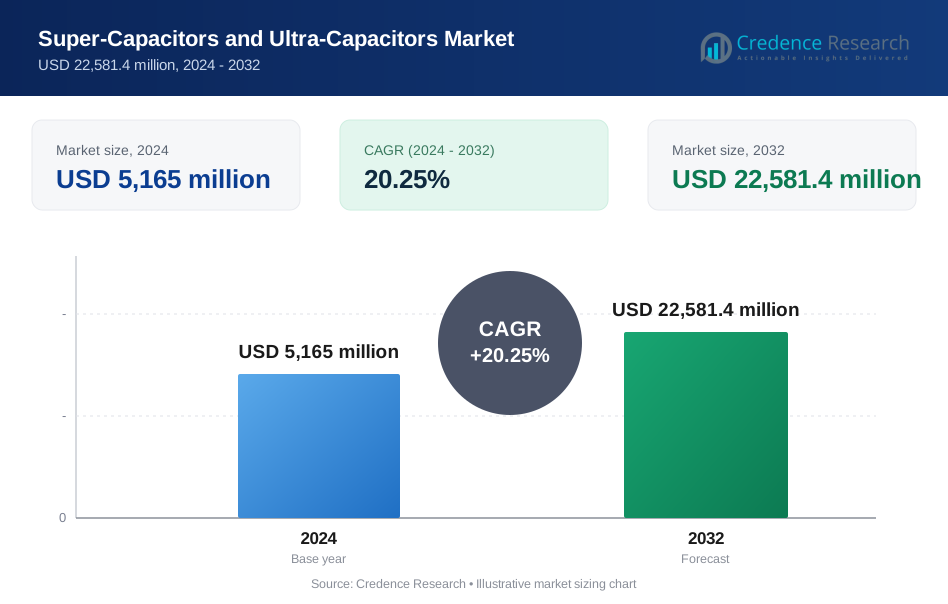
The Super Capacitors and Ultra Capacitors Market is projected to grow from USD 5,165 million in 2024 to USD 22,581.4 million by 2032, at a remarkable CAGR of 20.25%.
The Super Capacitors and Ultra Capacitors market is driven by increasing demand for energy storage solutions in electric vehicles, renewable energy systems, and consumer electronics. Key trends include advancements in capacitor technology, improving energy density and efficiency. The shift towards sustainable energy solutions is further propelling market growth, as these capacitors provide rapid charge and discharge cycles, supporting applications in grid stabilization and hybrid systems. Additionally, the miniaturization of electronic devices and growing adoption of electric vehicles are fostering the demand for compact and high-performance energy storage solutions, reinforcing the market's expansion.
The global market for supercapacitors and ultra capacitors is driven by strong demand across regions such as North America, Europe, and Asia-Pacific. North America is a key market, fueled by advancements in electric vehicles, renewable energy, and industrial applications. Europe also sees significant growth due to increasing focus on energy efficiency and sustainability. Key players in the market include companies like KEMET Corporation, Eaton Corporation, Skeleton Technologies, Maxwell Technologies, and Panasonic Corporation. These companies are at the forefront, driving innovation in energy storage solutions and contributing to the global adoption of supercapacitor technologies.
Market Drivers
Renewable Energy Integration
Supercapacitors are becoming increasingly vital in renewable energy systems, particularly for solar and wind power, which are inherently intermittent. For instance, a study by the International Journal of Energy Research found that integrating supercapacitors with photovoltaic systems significantly improves power oscillation management, ensuring a stable energy supply. These systems rely on the ability to store and smooth out power delivery, ensuring a stable energy supply. Supercapacitors' ability to charge and discharge rapidly makes them ideal for managing fluctuations in energy production, enhancing grid stability. This capability is crucial as global energy grids transition to incorporate more renewable energy sources, helping to balance supply and demand and mitigate the challenges of renewable energy's variability.
Electric Vehicles (EVs)
In the electric vehicle (EV) sector, supercapacitors provide significant advantages by complementing traditional battery systems. For instance, the International Energy Agency reports that nearly one in five cars sold in 2023 was electric, highlighting the growing importance of efficient energy storage solutions. Their ability to deliver quick bursts of power for acceleration and regenerative braking extends the life of EV batteries and improves overall vehicle performance. As the EV market continues to grow, supercapacitors are becoming an integral component in enhancing energy efficiency, reducing wear on batteries, and increasing the range and power of electric vehicles. This synergy between supercapacitors and batteries is helping to make EVs more practical and sustainable.
Energy Storage Systems (ESS)
Supercapacitors are also essential in energy storage systems (ESS), where they offer high power density and rapid charging/discharging capabilities. For instance, the U.S. Department of Energy highlights that supercapacitors are crucial for backup power applications in critical infrastructure such as data centers and medical facilities. These characteristics make them particularly suited for backup power applications in critical infrastructure such as data centers, telecommunications, and medical facilities. Supercapacitors can quickly supply energy during power outages or fluctuations, providing reliable and efficient energy storage solutions. As the demand for continuous power and reliability increases, especially in sectors where downtime is costly, supercapacitors are becoming a preferred choice for ESS.
Advancements and Industrial Applications
Ongoing advancements in materials science, such as the development of graphene and carbon nanotubes, are improving the performance and reducing the cost of supercapacitors. These innovations are expanding their use across various sectors, including consumer electronics, where supercapacitors enable rapid charging and extended battery life in portable devices like smartphones and tablets. In industrial applications, they are crucial for automation, robotics, and energy-efficient operations, where reliable and efficient power delivery is essential. Furthermore, government policies and incentives promoting renewable energy adoption and energy efficiency are driving the global demand for supercapacitors, ensuring their continued growth in the market.
Market Trends
Technological Advancements Driving Supercapacitor Performance
Recent technological advancements are significantly enhancing the performance and efficiency of supercapacitors. Key developments in advanced materials, such as graphene and carbon nanotubes, are improving energy density, charging speed, and lifespan, making supercapacitors more competitive with traditional energy storage technologies. Hybrid energy storage systems that combine supercapacitors with batteries are gaining traction, providing a balanced approach to power delivery. These hybrid systems optimize both quick power delivery and long-term energy storage, making them ideal for high-performance applications like electric vehicles (EVs) and renewable energy storage. As these technologies continue to evolve, supercapacitors are poised to become integral to next-generation energy systems, with enhanced capabilities that meet the growing demand for efficient, reliable, and sustainable power solutions.
Increasing Demand Across Key Industries and Rising Focus on Sustainability
Supercapacitors are seeing increasing demand across several key industries, driven by their unique properties and versatility. In the electric vehicle (EV) sector, supercapacitors complement batteries by providing quick bursts of power for acceleration and regenerative braking, extending battery life and improving overall performance. In the electric vehicle (EV) sector, supercapacitors complement batteries by providing quick bursts of power for acceleration and regenerative braking, extending battery life and improving overall performance. They are also becoming crucial in renewable energy systems, where they store excess energy generated from intermittent sources like solar and wind, thus enhancing grid stability and energy efficiency. In consumer electronics, supercapacitors enable faster charging and longer battery life, particularly in portable devices like smartphones and tablets. Their applications extend to industrial sectors, where they support automation and robotics, offering reliable and efficient power delivery. Additionally, in transportation systems, supercapacitors are used for energy storage and peak power delivery in buses, trains, and other modes of transit.
Market Challenges Analysis
Limitations in Energy Density and Storage Efficiency
One of the key challenges for supercapacitors is their lower energy density compared to traditional batteries. For instance, supercapacitors typically have an energy density of 5–10 Wh/kg, whereas batteries can reach up to 265 Wh/kg. While supercapacitors excel in power density delivering quick bursts of energy their ability to store large amounts of energy over extended periods is limited. This makes them less suitable for applications that require long-term energy storage, such as in grid energy storage or electric vehicle batteries where high energy retention is essential. Additionally, supercapacitors experience self-discharge, which leads to a gradual loss of stored energy over time, further limiting their effectiveness in applications where energy needs to be retained for long durations. This self-discharge can be a significant drawback for sectors such as consumer electronics or backup power systems that require consistent energy availability over extended periods. These limitations in both energy storage capacity and retention make it challenging for supercapacitors to fully replace traditional batteries in many energy storage applications.
Challenges in Manufacturing, Cost, and Standardization
Supercapacitors face several other challenges related to their manufacturing, cost, and standardization. The materials and complex manufacturing processes involved in producing high-performance supercapacitors can drive up their initial costs, making them more expensive than conventional batteries. The high cost of materials such as graphene and carbon nanotubes, along with the precision required in their production, contributes to these elevated expenses. Furthermore, despite advancements in production techniques, the manufacturing processes remain specialized, requiring advanced equipment and expertise, which can limit scalability and increase costs for mass production. Another significant issue is the lack of standardized testing protocols and interoperability standards for supercapacitors. This lack of industry-wide consistency can slow down adoption across different sectors, as manufacturers and users struggle to ensure compatibility and performance consistency in diverse applications. Additionally, while supercapacitors are known for their long cycle life, they are not immune to degradation over time, particularly when subjected to frequent charging and discharging cycles. These challenges combined with the impact of extreme temperature fluctuations on their performance and lifespan further limit the widespread adoption of supercapacitors in various markets.
Market Segmentation Analysis:
By Type:
The supercapacitor and ultra capacitor market can be segmented by type into Double Layered Capacitors, Pseudocapacitors, and Hybrid Capacitors, each offering distinct advantages and application potentials. Double Layered Capacitors (EDLCs) are the most widely used type, known for their high power density and long cycle life. They store energy through electrostatic charge accumulation, making them ideal for applications requiring quick energy bursts, such as in electric vehicles (EVs) and renewable energy systems. Pseudocapacitors, on the other hand, store energy through reversible faradaic reactions, offering higher energy density compared to EDLCs but with slightly lower cycle life. These are increasingly used in energy storage systems (ESS) and consumer electronics. Hybrid capacitors combine the characteristics of both EDLCs and pseudocapacitors, offering a balance between power and energy density. This type is gaining traction in EVs and grid stabilization applications, where both quick bursts of power and sustained energy storage are needed. Each type is optimized for specific applications, with EDLCs dominating in high power applications, while pseudocapacitors and hybrids are being explored for energy-dense, long-lasting storage solutions.
By Electrode Material:
Supercapacitors are further segmented by electrode material, including Carbon, Metal Oxide, Conducting Polymers, and Composites. Carbon-based electrodes, often made from activated carbon, are the most common due to their high surface area and conductivity, which provide excellent power density and long cycle life. These are widely used in double-layer capacitors for applications such as grid energy storage and EVs. Metal Oxide electrodes, while less common, offer enhanced capacitance and energy density, making them suitable for pseudocapacitors and hybrid capacitors. Their superior electrochemical properties make them ideal for energy storage systems requiring both high power and energy density. Conducting Polymers, known for their high capacitance and flexibility, are gaining attention in niche applications such as flexible electronics and wearable devices. Finally, Composite materials, combining carbon with metal oxides or polymers, are emerging as a promising alternative, providing a balance of power density, energy density, and cost-effectiveness. These composites are expected to see increased adoption across various industries, particularly in high-performance applications like electric vehicles and renewable energy systems.
Segments:
Based on Type:
- Double Layered Capacitors
- Pseudocapacitors
- Hybrid Capacitors
Based on Electrode Material
- Carbon
- Metal Oxide
- Conducting Polymers
- Composites
Based on Application
- Automotive
- Energy
- Consumer Electronics
- Industrial
- Aerospace
- Medical
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America dominates the global supercapacitors and ultra capacitors market, accounting for a significant market share of approximately 35%. This region benefits from the presence of key players, strong government initiatives supporting renewable energy, and growing demand for electric vehicles (EVs). The U.S. is the primary contributor to this market share, driven by its robust industrial base, adoption of clean energy solutions, and advancements in electric transportation infrastructure. The increasing adoption of renewable energy sources, particularly solar and wind, has led to a rise in the need for efficient energy storage solutions like supercapacitors. Additionally, the automotive sector in North America is increasingly incorporating supercapacitors into EVs for quick bursts of power, regenerative braking, and overall vehicle efficiency. The region’s focus on reducing carbon emissions and advancing energy storage technologies is further boosting market growth. With continued technological advancements in materials such as graphene and carbon nanotubes, North America is expected to maintain its leading position in the market for the foreseeable future, contributing to global innovations in supercapacitor applications.
Asia-Pacific
The Asia-Pacific region is projected to witness the fastest growth in the supercapacitor and ultra capacitor market, with a market share of approximately 30%. This rapid growth is largely attributed to the increasing demand from emerging economies like China, Japan, and India, where significant investments in renewable energy, electric vehicles, and industrial automation are taking place. China, in particular, is a major player in the market due to its dominance in manufacturing and the adoption of supercapacitors in various sectors such as public transportation, industrial automation, and energy storage systems. The government’s supportive policies promoting green technologies and EV infrastructure are further driving market expansion. Additionally, Japan and India are also seeing increased demand for supercapacitors in consumer electronics, industrial applications, and transportation systems. The Asia-Pacific region benefits from cost-effective manufacturing and the rapid deployment of new technologies, positioning it as a key player in the global supercapacitor market. With growing investments in research and development, the region is set to expand its share, positioning itself as a leader in the evolving energy storage market.
Key Player Analysis
- KEMET Corporation (YAGEO Group)
- Skeleton Technologies
- Panasonic Corporation
- CAP-XX
- LS Mtron Co., Ltd.
- Maxwell Technologies
- NEC Corporation
- Nippon Chemi-Con Corporation
- KYOCERA AVX Corporation
- Eaton Corporation
- Ness Electronics, Inc.
- ELNA CO., LTD.
Competitive Analysis
The supercapacitor and ultra capacitor market is highly competitive, with several leading players driving innovation and market growth. Companies like KEMET Corporation, Eaton Corporation, Skeleton Technologies, Maxwell Technologies, Panasonic Corporation, CAP-XX, LS Mtron Co., Ltd., Nippon Chemi-Con Corporation, and others are continuously improving their product offerings. Leading players in the market focus on technological advancements such as the development of advanced materials like graphene and carbon nanotubes, which enhance performance and efficiency. Companies also prioritize hybrid energy storage solutions, combining supercapacitors with batteries to extend life cycles and improve performance. The competition is further fueled by the increasing adoption of supercapacitors in industries such as electric vehicles, renewable energy, consumer electronics, and industrial applications. As demand for energy-efficient solutions grows, manufacturers aim to reduce costs, improve energy density, and deliver superior power delivery for diverse applications.
Recent Developments
- In October 2023, KYOCERA AVX Components Corporation introduced Gen-II PrizmaCap Capacitors. These products have extensive applications across industrial, energy, medical, telecommunications, and automotive sectors. They operate at a wider range of temperatures and offer better voltage, capacitance, and energy density as compared to the previous generation.
- In July 2023, Nippon Chemi-Con introduced a supercapacitor module tailored for high-voltage and large-current uses.
- In March 2023, KEMET Corporation introduced a new supercapacitor for the automotive industry that can operate effectively at temperatures ranging from -40 to 105 degree Celsius. The FMU series of supercapacitors offers extended life, high power density, and high reliability in a range of applications for autonomous vehicles, ADAS, and central gateway ECUs.
- In February 2022, CAP-XX signed a sourcing agreement with Continental Automotive GmbH, a Tier 1 automotive supplier, to provide CAP-XX DMT220 prismatic supercaps for one of Continental’s key automotive programs.
Market Concentration & Characteristics
The market for supercapacitors and ultra-capacitors exhibits moderate concentration, with a mix of well-established global players and emerging companies driving innovation. Key manufacturers dominate the market, benefiting from extensive research and development capabilities, strategic partnerships, and strong distribution networks. These companies focus on advancing supercapacitor technologies, including the development of high-performance materials such as graphene and carbon nanotubes, which offer improved energy density and longer life cycles. The market is also witnessing increasing competition from regional players offering cost-effective solutions. The industry is characterized by rapid technological advancements, with a strong emphasis on energy efficiency, sustainability, and the integration of supercapacitors into hybrid energy storage systems. As demand for energy storage solutions grows across diverse sectors-ranging from electric vehicles to industrial applications-the market is becoming more dynamic, with a shift toward improved performance, lower costs, and customized solutions to meet specific industry needs.
Report Coverage
The research report offers an in-depth analysis based on Type, Electrode Material, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Supercapacitors and ultra-capacitors are expected to see increasing adoption in electric vehicles, offering enhanced energy storage and quick power delivery for improved performance.
- The demand for renewable energy storage solutions will drive growth in the supercapacitor market, especially for applications in solar and wind energy systems.
- Technological advancements in materials, such as graphene and carbon nanotubes, will significantly enhance energy density and lifespan, making supercapacitors more competitive with traditional batteries.
- Hybrid energy storage systems combining supercapacitors with batteries will gain popularity due to their ability to provide both high power and energy efficiency.
- The rise in industrial automation and robotics will lead to greater use of supercapacitors in these sectors, ensuring efficient power delivery and reducing downtime.
- Government policies promoting energy efficiency and renewable energy integration will support market growth and encourage innovation in supercapacitor technologies.
- In consumer electronics, supercapacitors will continue to improve rapid charging and extend battery life in devices like smartphones, wearables, and laptops.
- The increasing need for backup power in critical infrastructure like data centers and telecommunications will drive demand for high-capacity supercapacitors in energy storage systems.
- As production volumes rise, economies of scale will reduce costs, making supercapacitors more affordable for widespread applications.
- Environmental concerns will push the market toward more sustainable supercapacitor solutions, with longer lifespans and fewer environmental impacts compared to traditional batteries.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Renewable Energy Integration
The increasing adoption of solar and wind power, which are intermittent by nature, is driving demand for supercapacitors to stabilize energy supply and manage power fluctuations, making them essential for grid stability and renewable energy storage.
Electric Vehicle (EV) Adoption
Supercapacitors are increasingly used in EVs for rapid power delivery during acceleration and regenerative braking, extending battery life and improving vehicle performance, which is critical as the global EV market expands.
Advancements in Materials Science
Innovations in electrode materials such as graphene and carbon nanotubes are enhancing the energy density, efficiency, and lifespan of supercapacitors, making them more competitive with traditional batteries and expanding their application scope.
Industrial Automation and Backup Power
The need for reliable, high-power backup solutions in critical infrastructure like data centers, telecommunications, and industrial automation is boosting the adoption of supercapacitors due to their rapid charge/discharge capabilities and long cycle life.
Miniaturization and Consumer Electronics
The trend toward smaller, more powerful electronic devices is increasing demand for compact, high-performance supercapacitors that enable rapid charging and longer battery life in smartphones, wearables, and portable electronics.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Super Capacitors and Ultra Capacitors market?
What factors are driving the growth of the Super Capacitors and Ultra Capacitors?
What are the key segments within the Super Capacitors and Ultra Capacitors market?
What are some challenges faced by the Super Capacitors and Ultra Capacitors?
Who are the major players in the Super Capacitors and Ultra Capacitors market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Double Layered Capacitors
- 1.2.2 Pseudocapacitors
- 1.2.3 Hybrid Capacitors
- 1.3 By Application
- 1.3.1 Automotive
- 1.3.2 Energy
- 1.3.3 Consumer Electronics
- 1.3.4 Industrial
- 1.3.5 Aerospace
- 1.3.6 Medical
- 1.4 By Electrode Material
- 1.4.1 Carbon
- 1.4.2 Metal Oxide
- 1.4.3 Conducting Polymers
- 1.4.4 Composites
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,165 million → 2032: USD 22,581.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Super-Capacitors and Ultra-Capacitors Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Super-Capacitors and Ultra-Capacitors Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Super-Capacitors and Ultra-Capacitors Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Super-Capacitors and Ultra-Capacitors Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Super-Capacitors and Ultra-Capacitors Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Super-Capacitors and Ultra-Capacitors Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Super-Capacitors and Ultra-Capacitors Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Super-Capacitors and Ultra-Capacitors Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,165 million → 2032: USD 22,581.4 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Super-Capacitors and Ultra-Capacitors Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Double Layered Capacitors
- 12.3.7.2 Pseudocapacitors
- 12.3.7.3 Hybrid Capacitors
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Automotive
- 12.4.7.2 Energy
- 12.4.7.3 Consumer Electronics
- 12.4.7.4 Industrial
- 12.4.7.5 Aerospace
- 12.4.7.6 Medical
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Electrode Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Carbon
- 12.5.7.2 Metal Oxide
- 12.5.7.3 Conducting Polymers
- 12.5.7.4 Composites
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Super-Capacitors and Ultra-Capacitors End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Super-Capacitors and Ultra-Capacitors Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Super-Capacitors and Ultra-Capacitors Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Super-Capacitors and Ultra-Capacitors Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 KEMET Corporation (YAGEO Group)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Skeleton Technologies
- 18.4 Panasonic Corporation
- 18.5 CAP-XX
- 18.6 LS Mtron Co., Ltd.
- 18.7 Maxwell Technologies
- 18.8 NEC Corporation
- 18.9 Nippon Chemi-Con Corporation
- 18.10 KYOCERA AVX Corporation
- 18.11 Eaton Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

