
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| System-On-Chip MarketSize 2024 | USD 209155 Million |
| System-On-Chip Market, CAGR | 7.23% |
| System-On-Chip Market Size 2032 | USD 365593.69 Million |
Market Overview:
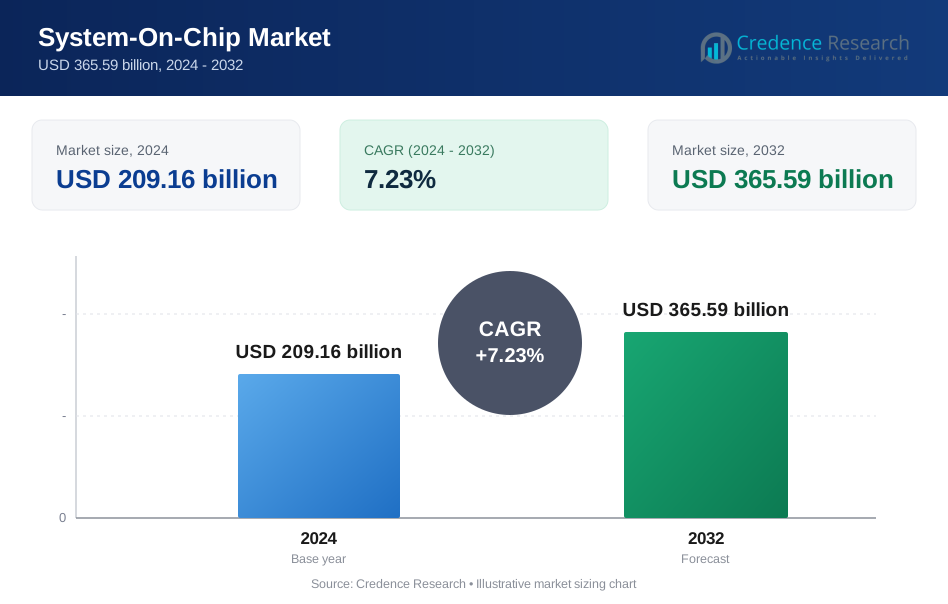
The System-On-Chip Market is projected to grow from USD 209155 million in 2024 to an estimated USD 365593.69 million by 2032, with a compound annual growth rate (CAGR) of 7.23% from 2024 to 2032.
Key drivers for the SoC market include the growing demand for high-performance computing in compact form factors and the increasing adoption of IoT devices, which rely heavily on SoCs for their multifunctional capabilities. As consumers demand more sophisticated, energy-efficient devices, manufacturers are compelled to design SoCs that offer greater performance while consuming less power. Additionally, the rapid expansion of 5G networks and the rise in demand for AI-based applications in autonomous vehicles, smart devices, and industrial automation are driving the market forward. The SoC architecture allows for integrating various components like processors, memory, and connectivity elements into a single chip, reducing the need for multiple discrete components and enhancing overall system efficiency. This growing need for customization, coupled with technological advancements, is expected to accelerate SoC development and adoption.
The Asia-Pacific region dominates the System-On-Chip market, largely due to its strong electronics manufacturing base in countries like China, South Korea, and Taiwan. These nations are home to leading semiconductor manufacturers and consumer electronics companies that drive the demand for SoCs. Additionally, the region benefits from the rising demand for smartphones, tablets, and wearable devices. North America is also a significant market, driven by advancements in automotive technology, especially in autonomous and electric vehicles, where SoCs are essential for processing complex data in real-time. Europe is emerging as a key player in the SoC market, with a growing focus on industrial automation and automotive innovation, while the Middle East and Africa are gradually seeing increased adoption, particularly in telecommunications and defense sectors.
Market Drivers:
Increasing Demand for High-Performance and Compact Devices:
The growing need for compact and high-performance electronic devices is one of the primary drivers of the System-On-Chip (SoC) market. For instance, Intel's SoCs are currently powering infotainment, displays, and digital instrument clusters in more than 50 million vehicles. Consumers are increasingly demanding devices that offer multifunctionality within smaller and more efficient designs. This shift is especially evident in consumer electronics like smartphones, tablets, and wearable devices, which require complex processing capabilities within minimal space. SoCs provide a solution by integrating various components such as CPUs, GPUs, memory, and input/output interfaces onto a single chip, allowing manufacturers to produce smaller, faster, and more energy-efficient devices. This trend towards miniaturization and enhanced performance continues to drive demand for advanced SoC designs.
Growth of IoT and Connected Devices:
The rapid proliferation of the Internet of Things (IoT) and connected devices is another key driver for the SoC market. For example, by end of 2023 the connected IoT devices reached 16.6 billion and is projected to grow to 18.8 billion by 2024. IoT applications demand highly integrated and versatile solutions that can handle multiple functions, such as sensing, communication, and data processing, within a compact footprint. SoCs enable these functions by offering a single-chip solution that supports real-time processing, low power consumption, and wireless connectivity. The increasing deployment of smart home devices, wearable health monitors, and industrial IoT solutions all rely on the advantages that SoC architecture provides. As the IoT ecosystem expands, the need for customizable, high-performance SoCs is expected to grow exponentially.
Advancements in 5G Technology:
The global roll-out of 5G networks is accelerating the demand for System-On-Chip solutions. 5G technology requires highly efficient and powerful chips that can manage higher data speeds, lower latency, and more connected devices simultaneously. SoCs are essential for supporting the diverse range of applications enabled by 5G, including enhanced mobile broadband, massive IoT, and ultra-reliable low-latency communication (URLLC). In smartphones, SoCs help manage the intense data processing requirements needed for seamless 5G performance, while in autonomous vehicles and smart cities, they play a critical role in enabling real-time data processing and communication. The ongoing global adoption of 5G is expected to be a key growth catalyst for the SoC market over the next several years.
Automotive Sector and AI Integration:
The automotive industry is increasingly adopting SoCs as vehicles become more reliant on advanced computing systems. The rise of electric and autonomous vehicles, along with the growing need for sophisticated in-car infotainment systems, has led to a surge in demand for SoCs. These chips are used to process data from sensors, cameras, and radar systems in real-time, enabling autonomous driving functions and advanced driver-assistance systems (ADAS). Moreover, the integration of artificial intelligence (AI) in automotive applications requires SoCs capable of handling complex algorithms for decision-making processes, enhancing safety and vehicle performance. This intersection of automotive innovation and AI is set to further boost the System-On-Chip market, as the industry continues to evolve towards smarter, more connected vehicles.
Market Trends:
Increasing Integration of AI and Machine Learning Capabilities:
A significant trend in the System-On-Chip (SoC) market is the growing integration of artificial intelligence (AI) and machine learning (ML) capabilities within SoC designs. As AI and ML applications become more prominent across industries, there is a rising demand for chips that can efficiently handle the processing of large data sets and perform complex algorithms. SoCs with AI and ML capabilities are increasingly used in smart devices, autonomous vehicles, robotics, and industrial automation systems. These chips enhance the ability of devices to perform tasks such as natural language processing, image recognition, and predictive analytics, driving innovation in AI-based solutions. This trend is expected to continue shaping the future of SoC development, as industries seek more intelligent and adaptive computing solutions.
Shift Towards Smaller Process Nodes:
Another notable trend in the SoC market is the ongoing transition to smaller process nodes, such as 5nm and 3nm technologies. Semiconductor manufacturers are continuously pushing the boundaries of miniaturization to increase chip performance and energy efficiency. Smaller process nodes allow for more transistors to be packed into the same chip area, leading to faster processing speeds, reduced power consumption, and improved heat dissipation. This trend is particularly relevant for consumer electronics, where there is a constant need for more powerful yet energy-efficient devices like smartphones and wearables. As technology advances, SoCs produced using smaller process nodes are expected to dominate the market, offering enhanced performance in a wide range of applications. For instance, TSMC's 3nm process technology has seen increasing adoption, with the company's revenue share from 3nm chips expected to surpass 20% of its total revenue in 2024.
Growth of Edge Computing:
The rise of edge computing is another important trend influencing the SoC market. Edge computing involves processing data closer to the source of data generation, reducing latency and the need for cloud-based processing. SoCs play a critical role in enabling edge computing by providing the necessary processing power and functionality in compact, energy-efficient chips. This trend is particularly relevant in applications like autonomous vehicles, IoT devices, and smart city infrastructure, where real-time data processing is essential. As edge computing continues to expand across industries, the demand for powerful and versatile SoCs capable of supporting these applications is expected to grow significantly.
Customization and Specialization of SoCs:
The increasing demand for customized and specialized SoC solutions is also a prominent trend in the market. Different industries have varying requirements for processing power, connectivity, and energy efficiency, leading to the development of application-specific SoCs (ASICs) tailored to meet specific needs. For example, in the automotive industry, SoCs are designed to handle the high-speed data processing required for autonomous driving, while in the telecommunications sector, SoCs are optimized for 5G connectivity and network performance. This trend towards customization allows manufacturers to create more efficient and optimized solutions for particular use cases, further driving innovation and differentiation in the SoC market.
Market Restraints and Challenges:
High Development Costs:
One of the key restraints in the System-On-Chip (SoC) market is the high cost of development. Designing and manufacturing an SoC involves complex processes, requiring significant investments in research and development (R&D), advanced design tools, and specialized manufacturing equipment. The shift towards smaller process nodes, such as 5nm and 3nm, further increases production costs, as it demands cutting-edge fabrication technologies and highly skilled engineers. These high initial costs can pose a barrier to entry for smaller companies and startups, limiting innovation and competition in the market. Additionally, the financial risk involved in SoC development may deter manufacturers from investing in new designs, particularly in highly specialized applications where the market size is smaller.
Supply Chain Disruptions:
The global semiconductor supply chain remains vulnerable to disruptions, which is another significant challenge for the SoC market. Factors such as geopolitical tensions, natural disasters, and pandemic-related production delays have exposed the fragility of the supply chain. SoCs rely on the availability of advanced semiconductor materials and components, and any disruptions in the supply chain can lead to production delays, increased lead times, and higher costs. Additionally, the semiconductor industry’s reliance on a limited number of fabrication facilities, especially for cutting-edge nodes, makes it difficult to quickly scale production in response to sudden demand spikes. These challenges can hinder the timely delivery of SoCs, particularly for industries like automotive and consumer electronics, which require high volumes of components.
Increasing Complexity in Design:
The growing complexity of SoC designs also presents a challenge for manufacturers. As SoCs integrate more functions onto a single chip, ensuring compatibility and optimizing performance becomes more difficult. Designing chips that can handle multiple tasks efficiently, such as processing, connectivity, and AI, requires advanced design tools and methodologies, which are not always readily available. This complexity can slow down the design and production processes, potentially delaying time-to-market for new SoC products.
Market Segmentation Analysis:
By Type, SoCs can be categorized into digital, mixed-signal, and analog SoCs. Digital SoCs dominate the market due to their widespread use in consumer electronics and communication devices, while mixed-signal SoCs are increasingly in demand for automotive and medical applications, which require both analog and digital processing. Analog SoCs serve niche markets such as RF devices and power management.
By End-Use Industry, the consumer electronics sector holds the largest share, driven by demand for smart devices. The automotive and transportation sector is also growing rapidly, with SoCs playing a pivotal role in vehicle automation and electric vehicle technologies. IT and telecommunications continue to rely on SoCs for network infrastructure and 5G deployment, while the healthcare, aerospace and defense, and power utilities sectors represent emerging markets with specialized requirements.
Segmentation:
By Type
- Digital
- Mixed
- Analog
By End Use Industry
- Consumer Electronics
- Automotive and Transportation
- IT & Telecommunication
- Aerospace & Defense
- Healthcare
- Power & Utility
- Others
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis:
Asia-Pacific
The Asia-Pacific region dominates the System-On-Chip (SoC) market, holding the largest share at over 40% in 2023. This region's leadership is primarily driven by the presence of major semiconductor manufacturers in countries such as China, Taiwan, South Korea, and Japan. These nations are home to leading companies like TSMC, Samsung, and MediaTek, which contribute significantly to global SoC production. The booming consumer electronics industry, particularly in China and South Korea, further boosts demand for SoCs in smartphones, tablets, and wearables. Additionally, the rapid adoption of 5G technology and the growth of the automotive and industrial automation sectors in the region are accelerating SoC development. Asia-Pacific’s strong electronics manufacturing ecosystem, supported by favorable government policies and investments in R&D, positions it as a key player in the global SoC market.
North America
North America holds a significant share of the global SoC market, accounting for around 30% in 2023. The region’s growth is fueled by the presence of major technology companies such as Apple, Qualcomm, and Intel, which drive demand for SoCs in various applications, including consumer electronics, IT, and telecommunications. The increasing adoption of autonomous driving technologies and electric vehicles in the U.S. and Canada is another key driver of SoC demand in the automotive sector. Additionally, the robust development of AI, cloud computing, and IoT in North America is accelerating the need for advanced SoCs with integrated processing capabilities. The region’s focus on technological innovation and its leadership in the development of cutting-edge semiconductor technologies contribute to its strong market position.
Europe
Europe represents approximately 20% of the global SoC market in 2023, driven by its leadership in automotive technology, industrial automation, and renewable energy sectors. The region’s automotive industry, particularly in countries like Germany and France, is a major consumer of SoCs, especially for advanced driver-assistance systems (ADAS) and electric vehicle technologies. Europe’s push towards Industry 4.0, which involves smart manufacturing and automation, also creates a growing demand for SoCs in industrial applications. Moreover, the region is witnessing increased adoption of SoCs in healthcare devices and telecommunication networks, particularly as 5G infrastructure expands. The European Union’s focus on strengthening its semiconductor supply chain and reducing dependency on external sources is expected to bolster local SoC production in the coming years.
Rest of the World
The Rest of the World, which includes regions such as Latin America, the Middle East, and Africa, holds around 10% of the global SoC market. While smaller in comparison to other regions, these markets are gradually emerging, particularly in telecommunications and industrial sectors. Countries in the Middle East are investing in 5G and smart city projects, creating new opportunities for SoC adoption. In Latin America and Africa, increasing mobile phone penetration and digitalization efforts are driving demand for affordable SoC solutions in consumer electronics and telecommunications. As these regions continue to develop their technological infrastructures, the demand for SoCs is expected to rise.
Key Player Analysis:
- Broadcom Inc.
- Intel Corporation
- Microchip Technology Inc.
- NXP Semiconductors NV
- Qualcomm Incorporated
- Samsung Electronics Co. Ltd
- STMicroelectronics NV
- Taiwan Semiconductor Manufacturing Company Limited (TSMC)
- Toshiba Corporation
Competitive Analysis:
The System-On-Chip (SoC) market is highly competitive, with several leading global companies dominating the landscape. Key players include Qualcomm, Apple, Intel, Samsung Electronics, Broadcom, and MediaTek, all of which have established strong footholds through continuous innovation and R&D investment. These companies focus on enhancing performance, energy efficiency, and integration of advanced features like AI and 5G capabilities to maintain a competitive edge. Semiconductor manufacturing giants such as TSMC and Samsung Foundry are crucial to the supply chain, offering cutting-edge fabrication technologies, particularly at smaller process nodes (5nm and below). New entrants and smaller players face high barriers to entry due to the capital-intensive nature of SoC design and manufacturing. In addition to technological advancements, competition is also driven by the ability to meet the growing demand for customized and application-specific SoCs, especially in industries like automotive, telecommunications, and healthcare.
Recent Developments:
- In June 2024, Intel Corporation announced plans to launch its upcoming processor series. The new SoC introduces multiple enhancements over the current Meteor Lake SoCs, including Intel Core and Core Ultra processors. Key improvements feature greater power efficiency, a fourfold increase in NPU processing capability, a 50% faster Intel Arc GPU powered by the next-generation Arc Battlemage architecture, and integrated on-chip memory for a more compact design and faster memory access.
- In February 2024, MaxLinear, Inc. launched the MXL17xxx series, also known as the 'Sierra' platform. This SoC is specifically designed for 4G/5G radio units for O-RAN. The Sierra platform offers a flexible, all-in-one solution that can be deployed across a range of radio unit applications, including traditional macro, massive MIMO, picocell, and integrated small cells.
- In January 2024, Robert Bosch GmbH and Qualcomm Technologies, Inc. introduced a vehicle computer that integrates infotainment and ADAS capabilities within a single SoC. Powered by the Snapdragon Ride™ Flex SoC, this central computer is part of Bosch's cockpit and ADAS integration platform. The collaboration continues the companies' long-term partnership in advancing software-defined vehicle solutions.
- In September 2023, MediaTek and TSMC announced the development of their first chip using TSMC’s advanced 3nm technology. This milestone marks the tape-out of MediaTek’s flagship Dimensity SoC, with volume production expected in 2024. This joint effort highlights the strategic partnership between the companies, leveraging their design and manufacturing strengths to produce high-performance, low-power SoCs.
- In April 2023, Broadcom Inc. introduced Jericho3-AI, delivering the industry’s highest-performance fabric for AI networks. This SoC enables best-in-class capabilities like perfect load balancing, congestion-free operation, ultra-high radix, and Zero-Impact Failover, significantly reducing job completion times for AI workloads.
Market Concentration & Characteristics:
The System-On-Chip (SoC) market is moderately concentrated, with a few key players, such as Qualcomm, Intel, Samsung, and MediaTek, holding significant market shares. These companies dominate the market due to their advanced research and development capabilities, strong intellectual property portfolios, and the ability to produce cutting-edge SoCs with smaller process nodes and higher integration levels. However, there is growing competition from smaller players and startups that are focusing on niche applications and custom SoC designs, particularly in industries like automotive and IoT. The market is characterized by rapid technological advancements, with a focus on increasing processing power, energy efficiency, and integration of AI and 5G capabilities. High development costs and the complexity of SoC designs create barriers to entry, contributing to market consolidation around established players. Customization and application-specific designs are becoming key differentiators in this competitive landscape.
Report Coverage:
The research report offers an in-depth analysis based on By Type and By End Use Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Advancements in AI and machine learning integration will drive demand for more powerful and specialized SoCs.
- The shift toward smaller process nodes, such as 3nm and below, will enhance chip performance and energy efficiency.
- Growing adoption of 5G technology will expand SoC use in telecommunications, automotive, and smart devices.
- The automotive sector, especially with autonomous and electric vehicles, will become a major growth driver for SoCs.
- Increasing demand for edge computing will push SoC innovation to support real-time processing in compact devices.
- Rising consumer demand for portable electronics and wearables will sustain the market’s expansion in consumer electronics.
- IoT proliferation will drive the development of low-power, multi-functional SoCs for connected devices across industries.
- Customization and application-specific SoCs will be crucial for industries like healthcare, aerospace, and industrial automation.
- Geopolitical tensions and supply chain disruptions may impact SoC production, creating challenges in maintaining stable supply.
- Collaborative efforts between semiconductor manufacturers and tech companies will accelerate innovation and market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for High-Performance and Compact Devices
Consumers and industries are seeking devices that deliver greater functionality and processing power in smaller, more energy-efficient form factors. SoCs enable this by integrating multiple components onto a single chip, driving adoption in smartphones, wearables, and other compact electronics.
Growth of IoT and Connected Devices
The proliferation of IoT devices across consumer, industrial, and healthcare sectors requires highly integrated chips capable of real-time processing, connectivity, and low power consumption. SoCs are essential for enabling these features, fueling market expansion as IoT ecosystems grow.
Advancements in 5G Technology
The global rollout of 5G networks demands SoCs that can handle higher data speeds, lower latency, and support for massive device connectivity. This is accelerating SoC adoption in mobile devices, automotive applications, and smart infrastructure.
Automotive Sector and AI Integration
The shift toward electric and autonomous vehicles, along with advanced driver-assistance systems (ADAS), is increasing the need for SoCs that can process complex sensor data and AI algorithms in real time, making automotive a rapidly growing segment for SoC deployment.
Shift to Smaller Process Nodes
Continuous innovation in semiconductor manufacturing, such as the move to 5nm and 3nm nodes, allows for more powerful and energy-efficient SoCs. This technological progress is enabling new applications and driving replacement cycles in consumer and industrial markets.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the System-On-Chip market?
What are the key drivers of the SoC market?
Which region dominates the SoC market?
What are the main challenges facing the SoC market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Digital
- 1.2.2 Mixed
- 1.2.3 Analog
- 1.3 By Application
- 1.3.1 Smartphones & Tablets
- 1.3.2 Wearables
- 1.3.3 Automotive Electronics
- 1.3.4 Industrial Automation
- 1.3.5 Networking & Communication Devices
- 1.4 By Process Node
- 1.4.1 Above 10nm
- 1.4.2 7nm-10nm
- 1.4.3 5nm-7nm
- 1.4.4 Below 5nm
- 1.5 By End Use Industry
- 1.5.1 Consumer Electronics
- 1.5.2 Automotive and Transportation
- 1.5.3 IT & Telecommunication
- 1.5.4 Aerospace & Defense
- 1.5.5 Healthcare
- 1.5.6 Power & Utility
- 1.5.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 209.16 billion → 2032: USD 365.59 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global System-On-Chip Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global System-On-Chip Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global System-On-Chip Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global System-On-Chip Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global System-On-Chip Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global System-On-Chip Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global System-On-Chip Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global System-On-Chip Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 209.16 billion → 2032: USD 365.59 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global System-On-Chip Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Digital
- 12.3.7.2 Mixed
- 12.3.7.3 Analog
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Smartphones & Tablets
- 12.4.7.2 Wearables
- 12.4.7.3 Automotive Electronics
- 12.4.7.4 Industrial Automation
- 12.4.7.5 Networking & Communication Devices
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Process Node - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Above 10nm
- 12.5.7.2 7nm-10nm
- 12.5.7.3 5nm-7nm
- 12.5.7.4 Below 5nm
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End Use Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Consumer Electronics
- 12.6.7.2 Automotive and Transportation
- 12.6.7.3 IT & Telecommunication
- 12.6.7.4 Aerospace & Defense
- 12.6.7.5 Healthcare
- 12.6.7.6 Power & Utility
- 12.6.7.7 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global System-On-Chip End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global System-On-Chip Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global System-On-Chip Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global System-On-Chip Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Qualcomm Incorporated
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Intel Corporation
- 18.4 Samsung Electronics Co. Ltd
- 18.5 Broadcom Inc.
- 18.6 MediaTek Inc.
- 18.7 NXP Semiconductors NV
- 18.8 STMicroelectronics NV
- 18.9 Taiwan Semiconductor Manufacturing Company Limited (TSMC)
- 18.10 Microchip Technology Inc.
- 18.11 Toshiba Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

