
Market Overview:
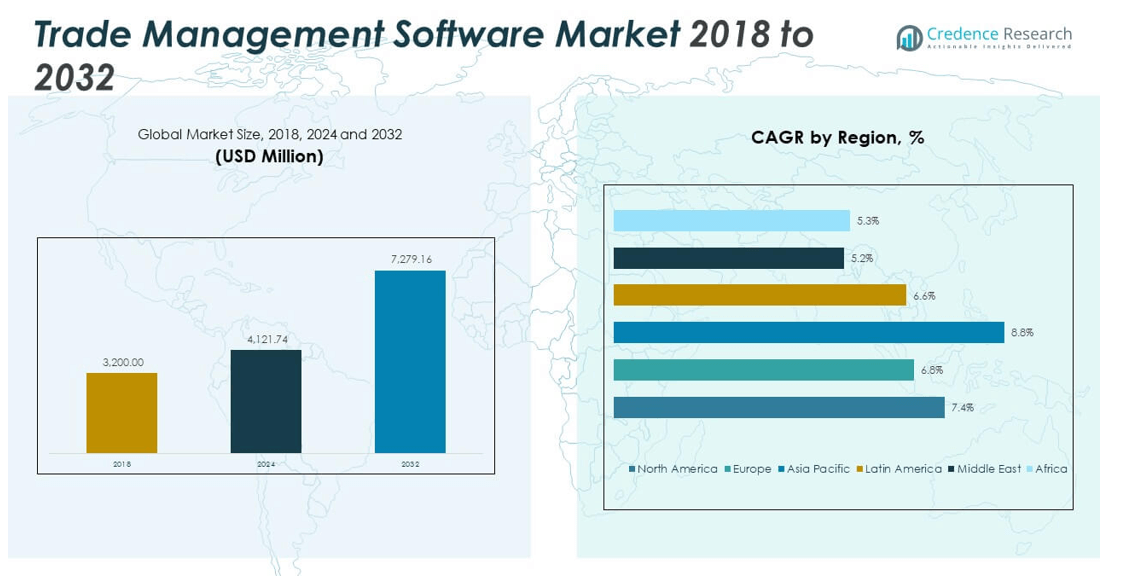
The Global Trade Management Software Market size was valued at USD 3,200.00 million in 2018 to USD 4,121.74 million in 2024 and is anticipated to reach USD 7,279.16 million by 2032, at a CAGR of 7.44% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Trade Management Software Market Size 2024 | USD 4,121.74 million |
| Trade Management Software Market, CAGR | 7.44% |
| Trade Management Software Market Size 2032 | USD 7,279.16 million |
Strong adoption of advanced digital trade solutions drives the Global Trade Management Software Market. Many enterprises use automation to streamline classification, duty management, and regulatory filings. Global supply chains depend on real-time alerts that reduce shipment delays. Cloud platforms improve collaboration across internal trade, finance, and logistics teams. Trade rules change faster across major economies, which increases demand for adaptive compliance tools. Firms also invest in analytics to improve cost planning and reduce operational risk. AI-based engines help detect compliance mistakes before cargo reaches checkpoints. Digital workflows support stronger governance in import and export cycles.
North America leads due to strict customs rules, wider digital adoption, and strong investment by large exporters. Europe follows with steady upgrades driven by regional harmonization efforts and compliance needs across member states. Asia Pacific emerges as the fastest-growing region due to rising export activity and expanding manufacturing hubs in China, India, and Southeast Asia. The Middle East gains momentum from logistics modernization and broader use of digital trade corridors. Latin America strengthens its position as governments upgrade customs systems to support smoother cross-border flows.
Market Insights:
- The Global Trade Management Software Market was valued at USD 3,200.00 million in 2018, reached USD 4,121.74 million in 2024, and is projected to hit USD 7,279.16 million by 2032, registering a CAGR of 7.44% during the forecast period.
- North America (35.36%), Europe (27.43%), and Asia Pacific (24.59%) held the top three regional shares in 2024, driven by strict compliance rules, heavy digitalization, and high export volume across advanced supply chains.
- Asia Pacific, with 59% share, stands as the fastest-growing region due to rapid manufacturing expansion, rising export flows, and strong digital trade reform across China, India, Japan, and Southeast Asia.
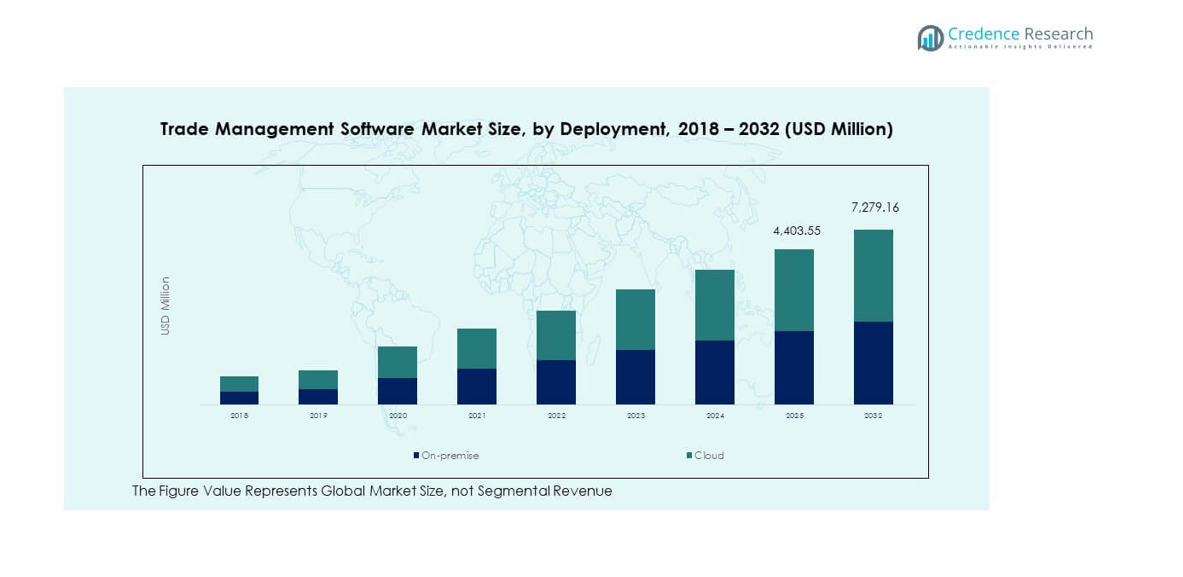
- Cloud deployment dominated the market structure in the chart, representing roughly 60% share, supported by faster scaling, remote integration, and lower infrastructure costs.
- On-premise deployment accounted for an estimated 40% share, maintained by firms that prioritize internal data control, fixed-infrastructure setups, and higher security-driven trade environments.
Market Drivers:
Rising Focus On Automated Compliance And Global Trade Visibility
The Global Trade Management Software Market gains strong momentum due to rising pressure to meet complex global trade rules. Many firms seek automated platforms that reduce errors in classification and documentation. It supports faster clearance by guiding teams through required checks. Cloud systems help trade teams improve visibility across supply chains. Companies also use smart tools to track regulatory updates in real time. Strong interest in digital workflows pushes wider platform use across large enterprises. Predictive engines help identify possible compliance gaps early. Firms adopt unified dashboards to manage trade tasks across multiple regions.
- For instance, SAP Global Trade Services (SAP GTS) automates restricted-party screening and handles compliance checks across large enterprises. The system is designed to monitor every transaction in real-time, regardless of volume, helping businesses ensure compliance and avoid potential fines and penalties.
Growing Dependence On Real-Time Shipment Tracking And Risk Control
Global trade teams depend on live data to manage cross-border risks. Many companies use digital platforms that track every shipment step and raise alerts quickly. It supports better planning across procurement and logistics units. Firms adopt structured workflows that cut delays across import and export cycles. Strong pressure to limit penalties drives adoption of automated screening tools. Companies use document-matching systems that verify key records before dispatch. Wider interest in predictive risk control increases the need for integrated systems. Digital adoption grows as trade lanes expand across new markets.
- For instance, Descartes MacroPoint provides real-time visibility for over 500,000 carriers and tracks millions of shipments each year, supporting precise risk assessments across routes.
Expansion Of Cloud-Based Trade Platforms Across Large And Mid-Sized Enterprises
Cloud platforms gain attention due to easy integration and lower setup needs. Many firms shift from legacy tools to flexible systems that scale with trade volume. It improves user access across global teams through shared dashboards. Companies use cloud tools to test new features without long upgrade cycles. Strong demand for remote access supports faster rollout across large units. Cloud systems also support modular deployments that cut IT workload. Vendors expand security layers to protect sensitive trade data. Firms prefer platforms that offer faster updates aligned with global trade laws.
Increasing Need For Integrated Trade, Finance, And Logistics Workflows
Trade teams need tighter links with finance and logistics systems to reduce process gaps. Many companies use integrated layers that connect duty management, cost checks, and shipment tasks. It improves control over landed cost forecasting and invoice matching. Firms gain better accuracy by linking trade data with ERP modules. Automation reduces the manual load on small compliance teams. Predictive tools help teams understand cost impact before confirming orders. Integrated workflows reduce bottlenecks across supply chains. Companies prefer systems that unify all trade functions under one structure.
Market Trends:
Rising Use Of AI-Driven Analytics For Trade Forecasting And Compliance Precision
The Global Trade Management Software Market sees strong interest in AI tools that improve decision quality. Many firms use models that forecast duty impact and identify high-risk routes. It improves cost planning across multi-country operations. Companies adopt AI engines that scan documents to verify required fields. Strong interest in faster processing pushes firms toward smart automation. Vendors expand AI features to support real-time compliance checks. Predictive scoring tools guide teams toward safer trade choices. Firms seek AI systems that reduce the chance of regulatory breaches.
- For instance, Thomson Reuters ONESOURCE uses AI-led classification engines that process over 2.5 million product classifications annually, helping companies reduce compliance errors.
Expansion Of Blockchain Pilots For Secure Documentation And Trade Validation
Many organizations explore blockchain to verify trade documents and prevent tampering. It offers better trust between exporters, importers, and customs officers. Companies run pilots to test document authentication across high-risk lanes. Strong interest in tamper-proof formats drives wider testing across major ports. Vendors design platforms that support faster document exchange through shared ledgers. Blockchain improves transparency during audits and dispute checks. Firms use digital identities to validate partner details during shipment stage. Wider blockchain use grows across sensitive product categories.
- For instance, IBM–Maersk TradeLens processed more than 36 million documents and tracked over 70 million container shipments before its closure. While the platform technically demonstrated blockchain’s ability to secure documentation at a massive scale, it ultimately failed to achieve the necessary commercial viability and industry-wide adoption, primarily due to competitive concerns, governance issues, and regulatory hurdles.
Adoption Of Low-Code Platforms For Faster Workflow Customization
Low-code systems gain traction as companies seek faster development cycles. The Global Trade Management Software Market benefits from tools that simplify workflow design for non-technical staff. It helps teams build custom steps linked to their trade processes. Companies use drag-and-drop tools to standardize approvals and checks. Low-code layers reduce time spent coding complex rules. Vendors add libraries that offer ready templates for trade tasks. Firms prefer systems that allow easy adjustment to new customs rules. Low-code adoption grows across firms with mixed trade requirements.
Greater Emphasis On End-To-End Supply Chain Collaboration And Data Sharing
Trade teams aim to improve collaboration with carriers, brokers, and suppliers. Many firms use shared portals that display shipment status in real time. It supports smoother planning across internal teams and partners. Unified data layers reduce miscommunication during cross-border moves. Companies deploy tools that allow partners to upload documents directly. Strong interest in transparency drives wider use of shared dashboards. Vendors invest in APIs that strengthen data flow across systems. Firms prefer platforms that create a single version of truth across the supply chain.
Market Challenges Analysis:
Complex Regulatory Shifts And High Compliance Burden Across Trade Lanes
The Global Trade Management Software Market faces pressure from rapidly changing global trade rules. Many firms struggle to update processes when new duties or rules arrive. It raises the risk of compliance errors during busy cycles. Companies deal with different document formats across many countries. Small teams often lack time to manage repeated checks manually. Vendors must track frequent changes to maintain platform accuracy. Strong global uncertainty makes compliance planning difficult. Firms face rising pressure to avoid penalties during clearance.
Integration Difficulties And Limited Digital Skills Across Trade Functions
Many firms face challenges while linking trade platforms with old ERP and logistics systems. It slows deployment timelines across global teams. Companies also lack staff trained to handle advanced digital workflows. It raises the need for strong vendor support during setup. Firms struggle to maintain consistency across multi-country operations. Data mismatches create delays during shipment processing. Integration gaps reduce the value gained from automation. Teams need training to manage evolving digital tools across complex trade networks.
Market Opportunities:
Growth Potential In Emerging Export Hubs And Mid-Sized Enterprise Adoption
The Global Trade Management Software Market gains new opportunities due to expansion across fast-growing export regions. Many countries modernize customs systems to support smoother flows. It creates demand for scalable tools that fit mid-sized exporters. Firms in developing markets look for systems that simplify document work. Vendors gain growth as more companies shift from manual checks. Wider export activity increases need for tracking and compliance tools. Firms prefer flexible cloud tools due to cost benefits. Rising trade activity supports long-term adoption.
Rising Demand For Digital Trade Corridors And Automated Partner Verification
Digital trade corridors create fresh scope for smarter and safer global routes. Companies use automated partner checks to reduce fraud risk during shipments. The Global Trade Management Software Market benefits from tools that validate trade partners quickly. It helps firms maintain trust across global networks. Vendors expand features that screen partners using multiple data sources. Strong demand for faster clearance increases interest in advanced workflows. Improved digital infrastructure supports easy platform expansion. Companies look for systems that connect all partners under one structure.
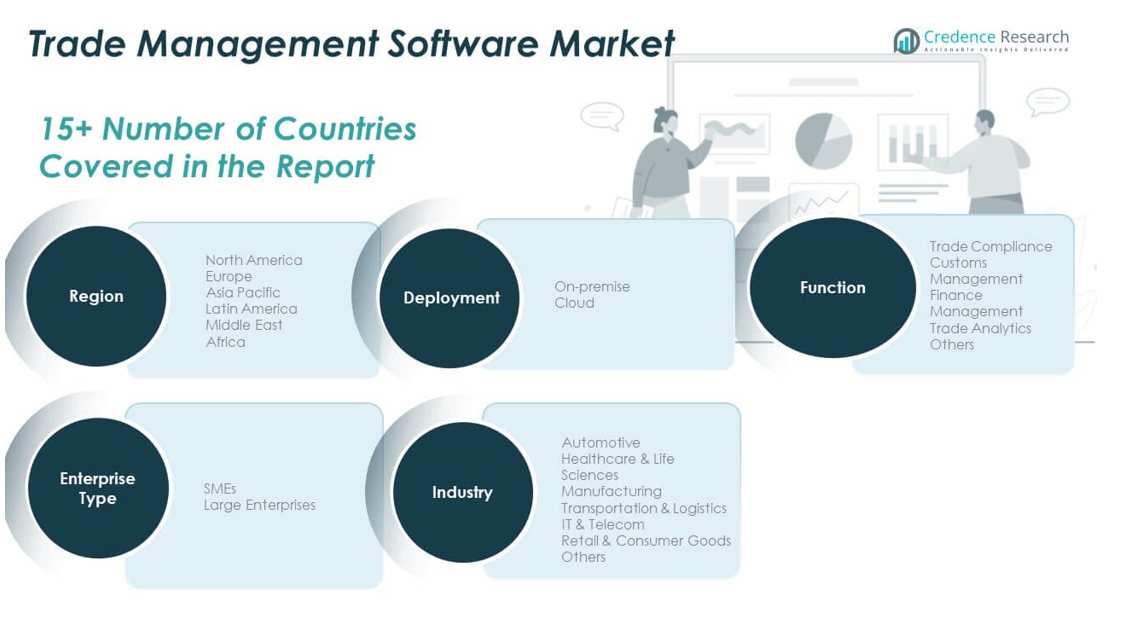
Market Segmentation Analysis:
By Deployment
The Global Trade Management Software Market covers on-premise and cloud systems that support varied enterprise needs. On-premise platforms attract firms that require strict data control and internal hosting. It supports organizations with sensitive trade workflows and fixed infrastructure. Cloud platforms gain strong momentum due to flexible scaling and lower setup needs. Many firms prefer cloud systems for faster upgrades and real-time access across global teams. Cloud adoption increases due to integration benefits with ERP and logistics tools. Companies select deployment modes based on security needs and digital readiness.
- For instance, Oracle Cloud SCM supports global trade workflows at scale and is part of the broader Oracle Cloud platform, which handles millions of enterprise resource planning (ERP) transactions every hour across its systems. The platform is designed for high volume and high velocity transactions to meet the demands of growing digital business.
By Function
Key functions include trade compliance, customs management, finance management, trade analytics, and other specialized tools. Trade compliance modules guide teams through rule checks and documentation steps. Customs management tools support classification, duty review, and clearance tasks. Finance management helps firms track landed cost and duty impact. Trade analytics offers insights that improve planning across regions. Other tools support partner screening and product validation.
- For instance, MIC Customs Solutions supports customers in over 55 countries with automated customs filing across 48 electronic customs systems, which is among the widest global coverage in the industry.
By Enterprise Type
SMEs adopt digital systems to reduce manual errors and improve trade visibility. It helps small firms manage tasks with limited compliance staff. Large enterprises deploy advanced systems to handle complex, multi-country operations. Both groups invest in tools that support fast regulatory alignment and predictable workflows.
By Industry
Automotive, healthcare and life sciences, manufacturing, transportation and logistics, IT and telecom, retail and consumer goods, and other sectors use trade software to manage global flows. It supports strict quality checks in regulated industries. Firms across each sector rely on digital platforms to reduce delays and maintain compliance during cross-border movement.
Segmentation:
By Deployment
- On-premise
- Cloud
By Function
- Trade Compliance
- Customs Management
- Finance Management
- Trade Analytics
- Others
By Enterprise Type
- SMEs
- Large Enterprises
By Industry
- Automotive
- Healthcare & Life Sciences
- Manufacturing
- Transportation & Logistics
- IT & Telecom
- Retail & Consumer Goods
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Global Trade Management Software Market size was valued at USD 1,145.60 million in 2018 to USD 1,457.42 million in 2024 and is anticipated to reach USD 2,570.29 million by 2032, at a CAGR of 7.4% during the forecast period. North America holds 35.36% market share in 2024. The Global Trade Management Software Market grows here due to strict trade rules and strong digital adoption across large enterprises. It gains support from advanced customs systems and secure digital workflows. Firms in the U.S. lead adoption due to high export activity and strong regulatory oversight. Canada improves usage through modern border tools and automated checks. Mexico expands digital processes to support manufacturing trade flows. Vendors gain wider presence through regional partnerships. Cloud rollouts grow due to strong interest in scalable compliance platforms.
Europe
The Europe Global Trade Management Software Market size was valued at USD 911.14 million in 2018 to USD 1,131.43 million in 2024 and is anticipated to reach USD 1,896.10 million by 2032, at a CAGR of 6.8% during the forecast period. Europe holds 27.43% market share in 2024. The market gains strength through harmonized trade rules and structured digital systems. The Global Trade Management Software Market benefits from strong compliance needs under regional frameworks. It supports firms that handle multi-country shipments with fixed audit needs. EU exporters use automated platforms to manage duties and documentation steps. Germany and France lead growth through advanced digital tools. Southern Europe raises adoption to reduce clearance delays. Vendors gain traction through cloud migration and centralized data systems.
Asia Pacific
The Asia Pacific Global Trade Management Software Market size was valued at USD 753.92 million in 2018 to USD 1,015.78 million in 2024 and is anticipated to reach USD 1,986.49 million by 2032, at a CAGR of 8.8% during the forecast period. Asia Pacific holds 24.59% market share in 2024. Strong export activity drives market expansion across China, India, and Southeast Asia. The Global Trade Management Software Market gains support from rising manufacturing output and complex supply chains. It helps firms manage large shipment volumes under varied rules. Japan and South Korea adopt advanced tools to support precision-driven trade cycles. India increases usage due to rapid digital reforms. Export hubs across ASEAN push firms toward cloud adoption. Vendors expand presence due to growing interest in automated compliance.
Latin America
The Latin America Global Trade Management Software Market size was valued at USD 230.40 million in 2018 to USD 294.25 million in 2024 and is anticipated to reach USD 486.76 million by 2032, at a CAGR of 6.6% during the forecast period. Latin America holds 7.13% market share in 2024. The region strengthens adoption due to customs modernization and export reforms. The Global Trade Management Software Market helps firms reduce delays at busy borders. It supports logistics networks across Brazil, Mexico-linked routes, and regional trade corridors. Brazil leads with strong investment in digital trade tools. Chile and Colombia show interest in real-time systems that support faster clearance. Firms adopt cloud tools due to lower cost and easier scaling. Wider digital reforms support long-term software adoption.
Middle East
The Middle East Global Trade Management Software Market size was valued at USD 78.40 million in 2018 to USD 91.06 million in 2024 and is anticipated to reach USD 135.43 million by 2032, at a CAGR of 5.2% during the forecast period. The region holds 2.21% market share in 2024. Trade hubs such as UAE and Saudi Arabia drive digital adoption. The Global Trade Management Software Market supports wider logistics upgrades linked to free zones and large ports. It helps firms handle rising trade flows tied to regional diversification plans. GCC economies expand digital customs tools that improve clearance. Israel boosts usage across technology-driven exporters. Turkey grows demand due to complex multi-route operations. Vendors gain space through integration with regional logistics systems.
Africa
The Africa Global Trade Management Software Market size was valued at USD 80.54 million in 2018 to USD 131.79 million in 2024 and is anticipated to reach USD 204.10 million by 2032, at a CAGR of 5.3% during the forecast period. Africa holds 3.19% market share in 2024. Growth improves due to customs reforms and wider interest in digital workflows. The Global Trade Management Software Market helps firms manage rising intra-Africa trade under new agreements. It supports exporters that deal with varied border rules across multiple economies. South Africa leads adoption due to strong logistics networks. East Africa increases usage to support trade corridors. Nigeria shows interest in cloud tools to improve shipment tracking. Vendors gain opportunities through modernization efforts across new trade zones.
Key Player Analysis:
- Amber Road, Inc. (USA)
- Aptean, Inc. (USA)
- Livingston International, Inc. (Canada)
- MIC Customs Solutions (Austria)
- MIQ Logistics LLC (USA)
- Precision Software (USA)
- SAP SE (Germany)
- Oracle Corporation (USA)
- Descartes Systems Group Inc. (Canada)
- Infor (USA)
- Integration Point, Inc. (USA)
- QuestaWeb, Inc. (USA)
- MercuryGate International, Inc. (USA)
- Thomson Reuters Corporation (Canada)
- Kewill, Inc. (USA)
- AEB SE (Germany)
- WiseTech Global (Australia)
Competitive Analysis:
The Global Trade Management Software Market features strong competition driven by vendors focused on automation, compliance intelligence, and cloud scalability. It includes established software providers that deliver wide integration support across ERP, logistics, and financial systems. Firms enhance platforms through AI tools that improve classification accuracy, duty prediction, and risk screening. Vendors expand global presence through regional partnerships that support multi-country deployments. New entrants target SMEs with flexible cloud-based systems. Large providers strengthen portfolios through analytics engines that support high-volume operations. Competitive intensity grows as firms upgrade security layers and accelerate feature rollout cycles.
Recent Developments:
- In April 2025, Aptean announced a transformative acquisition that marks a significant milestone for the industry. The company, a global provider of AI-first, mission-critical enterprise software applications, completed its acquisition of Logility, a leader in AI-driven supply chain management software applications. This powerful combination of applications, which heavily leverage artificial intelligence, accelerates the development of transformational capabilities and enables customers to build competitive advantage in rapidly changing markets. The merger delivers a fully integrated, end-to-end planning experience that translates disjointed data and process information into actionable business insights. According to TVN Reddy, CEO of Aptean, this acquisition represents exponential supply chain management success from factory floor to last-mile delivery, with capabilities that move companies from "what happened" to "what's coming."
- Following this strategic move, in May 2025, Aptean expanded its manufacturing and supply chain capabilities through another significant acquisition of Germanedge. Germanedge, headquartered in Munich, Germany, is a provider of industrial software for discrete and process manufacturers. The acquisition strengthens Aptean's position as a leader in industrial software solutions, with Germanedge's portfolio including Advanced Planning & Scheduling, Intelligent Production Management (MES), Statistical Quality Management, and Connected Worker solutions accessible through their Edge. One platform. This addition greatly expands Aptean's manufacturing capabilities, enabling the company to better serve its global enterprise resource planning (ERP) customer base.
Report Coverage:
The research report offers an in-depth analysis based on By Deployment, By Function, By Enterprise Type, and By Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Adoption of AI-led compliance tools will expand across high-volume exporters.
- Cloud-based platforms will gain traction due to lower deployment barriers.
- Automated partner verification will support safer global trade operations.
- Integrated ERP and logistics linkages will become standard across enterprises.
- SMEs will accelerate usage to reduce manual errors and improve visibility.
- Local trade rule updates will push vendors to strengthen content libraries.
- Predictive analytics will support faster decision cycles in complex routes.
- Large enterprises will invest in deeper security layers for trade systems.
- Regional trade reforms will increase demand for scalable digital platforms.
- Automation will drive strong modernization across regulated industries.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Trade Management Software Market?
At what Compound Annual Growth Rate is the Global Trade Management Software Market projected to grow between 2025 and 2032?
What factors are driving the growth of the Trade Management Software Market?
What are some challenges faced by the Trade Management Software Market?
Who are the major players in the Trade Management Software Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Trade Management Software Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Trade Management Software Market Snapshot
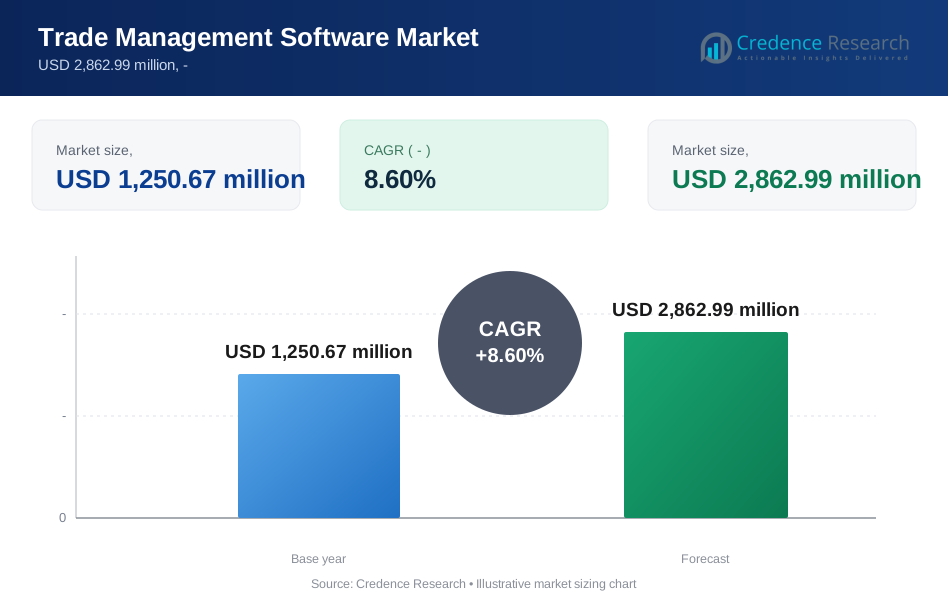
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 1,250.67 million → forecast year: USD 2,862.99 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Trade Management Software Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Trade Management Software Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Trade Management Software Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Trade Management Software Market Drivers
- 3.3 Trade Management Software Market Restraints & Challenges
- 3.4 Trade Management Software Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Trade Management Software Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Trade Management Software Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Trade Management Software category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Trade Management Software Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Trade Management Software Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Trade Management Software market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Trade Management Software Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Trade Management Software Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Trade Management Software Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Trade Management Software (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Trade Management Software Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Trade Management Software Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Trade Management Software Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Trade Management Software Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Trade Management Software Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Trade Management Software Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Trade Management Software Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Trade Management Software Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Trade Management Software Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
