
Market Overview
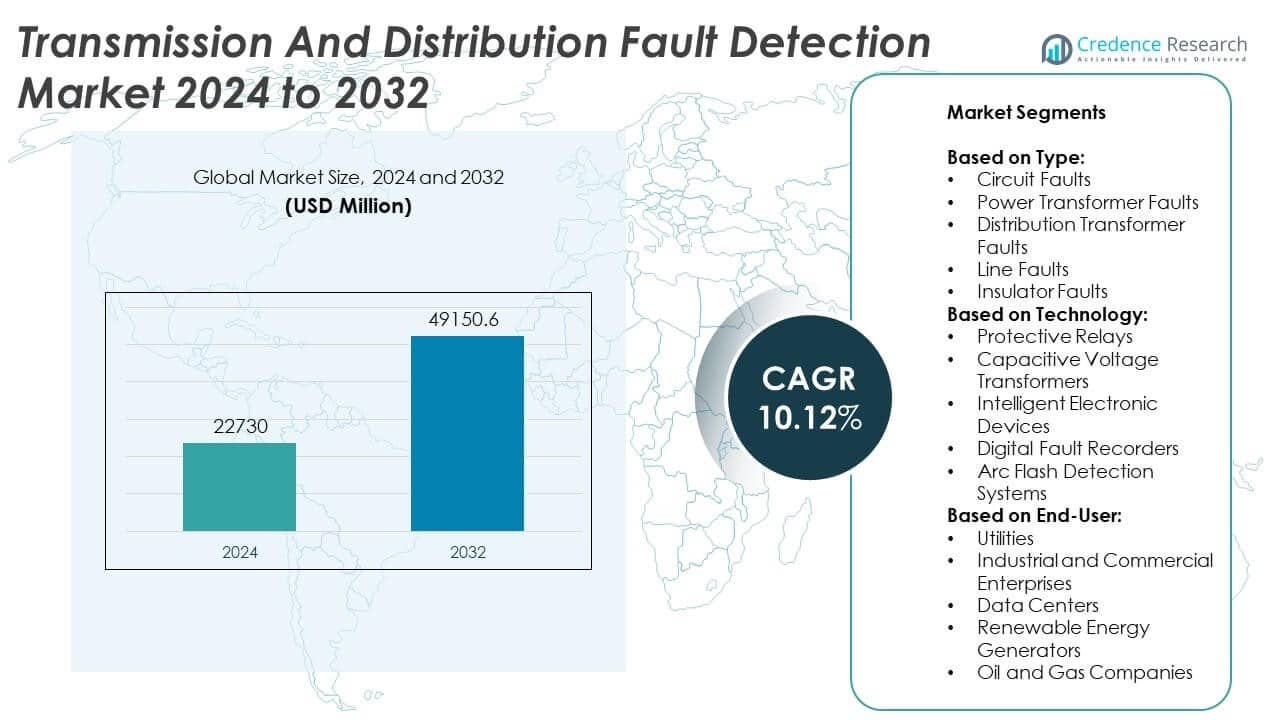
The Transmission and Distribution Fault Detection Market size was valued at USD 22,730 million in 2024 and is anticipated to reach USD 49,150.6 million by 2032, growing at a CAGR of 10.12% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Transmission and Distribution Fault Detection Market Size 2024 | USD 22,730 Million |
| Transmission and Distribution Fault Detection Market, CAGR | 10.12% |
| Transmission and Distribution Fault Detection Market Size 2032 | USD 49,150.6 Million |
The Transmission and Distribution Fault Detection market grows on the strength of grid modernization, aging infrastructure replacement, and rising integration of renewable energy. Utilities invest in real-time monitoring systems to enhance outage response and minimize equipment damage. Increasing demand for predictive maintenance and regulatory pressure for grid reliability further accelerate adoption. Trends include the integration of AI and machine learning for accurate fault prediction, deployment of IoT-based monitoring across distribution networks, and expansion of digital substations.
The Transmission and Distribution Fault Detection market exhibits strong growth across North America, Europe, and Asia-Pacific, driven by infrastructure modernization, regulatory mandates, and renewable energy expansion. North America leads in technology adoption due to established smart grid programs, while Europe focuses on grid reliability and digital substations. Asia-Pacific benefits from rapid electrification and utility-scale investments across emerging economies. Key players shaping the competitive landscape include Schneider Electric, Siemens, and ABB, who offer advanced fault detection solutions integrated with digital automation systems.
Market Insights
- The Transmission and Distribution Fault Detection market was valued at USD 22,730 million in 2024 and is expected to reach USD 49,150.6 million by 2032, growing at a CAGR of 10.12%.
- Grid modernization initiatives, aging power infrastructure, and renewable energy integration are key drivers fueling the adoption of real-time fault detection systems.
- AI-driven analytics, IoT-based monitoring, and digital substations are major trends shaping the market's technological evolution.
- Major players such as Schneider Electric, Siemens, ABB, and Eaton compete through innovation, software integration, and advanced grid automation offerings.
- High capital costs and the complexity of integrating fault detection systems with legacy infrastructure restrain market expansion in cost-sensitive regions.
- North America leads in adoption due to regulatory pressure and advanced smart grid deployment, while Asia-Pacific shows rapid growth through rural electrification and industrial expansion.
- Vendors focus on developing cybersecure, compact, and scalable detection platforms to meet diverse utility, industrial, and renewable energy requirements.
Market Drivers
Growing Grid Modernization Initiatives Across Developed and Emerging Economies
Grid modernization programs drive the deployment of intelligent fault detection systems across transmission and distribution networks. Governments and utilities invest in advanced monitoring infrastructure to improve outage response, enhance operational transparency, and support integration of renewable energy. Real-time fault detection supports predictive maintenance, reducing unplanned downtime. The Transmission and Distribution Fault Detection market benefits from smart grid projects aimed at enhancing grid stability and resilience. It enables faster localization of faults, improving customer satisfaction and reducing restoration time. Countries such as the United States, China, and Germany prioritize automation in grid upgrades, accelerating the demand for these technologies.
- For instance, Siemens deployed its SICAM Fault Detection system in India’s solar corridor in Gujarat, integrating over 850 MW of renewable capacity across 16 grid-connected installations.
Rising Renewable Energy Integration Requires Enhanced Fault Management
The rapid adoption of renewable energy sources increases grid complexity and creates new fault management challenges. Variable energy input from solar and wind farms causes fluctuations in voltage and frequency, necessitating dynamic detection capabilities. It requires sophisticated fault identification tools that operate under intermittent load conditions. Utilities adopt digital substations and fault location systems to prevent equipment damage and maintain power quality. The Transmission and Distribution Fault Detection market addresses these needs by providing real-time alerts and analytics for proactive grid balancing. It aligns with global sustainability goals and supports high renewable penetration without compromising reliability.
- For instance, Schneider Electric upgraded 132 substations in France’s Île-de-France region with its EcoStruxure Grid Monitoring system, enabling predictive maintenance and detecting over 3,200 fault events annually.
Aging Power Infrastructure Elevates the Demand for Early Fault Detection
Legacy grid components such as transformers, cables, and switchgear increase the likelihood of faults due to wear and operational stress. Many regions, particularly in North America and Western Europe, face challenges related to aging infrastructure. Early detection systems minimize costly blackouts and infrastructure damage by identifying issues before they escalate. It supports condition-based monitoring strategies and helps utilities extend asset lifecycles. Deployment of sensors, IoT devices, and remote diagnostics becomes essential for operational continuity. The market sees strong traction among utilities seeking to modernize fault detection without full-scale equipment replacement.
Regulatory Mandates and Reliability Standards Promote Adoption of Detection Systems
Governments and regulatory bodies impose strict reliability and outage response standards on power distribution entities. Compliance with regulations such as IEEE 1366 or regional grid codes necessitates robust monitoring and fast fault recovery. It encourages utilities to deploy advanced detection systems that support real-time event logging and remote diagnostics. These systems reduce Mean Time to Repair (MTTR) and improve System Average Interruption Duration Index (SAIDI) scores. The Transmission and Distribution Fault Detection market aligns with performance-based incentives and penalty frameworks, driving steady adoption. Vendors respond by offering customizable solutions that integrate with existing SCADA and distribution management systems.
Market Trends
Increased Adoption of AI and Machine Learning in Fault Detection Systems
Utilities implement AI and machine learning algorithms to analyze real-time data from grid sensors and identify fault patterns with higher accuracy. These technologies support self-healing grid architectures and adaptive fault location. Predictive analytics enables proactive maintenance and reduces service disruptions. The Transmission and Distribution Fault Detection market incorporates intelligent solutions that learn from historical faults and recommend corrective actions. It helps operators reduce false positives and enhance fault isolation efficiency. AI-driven platforms also integrate with SCADA and GIS systems for advanced visualization and decision support.
- For instance, Schweitzer Engineering Laboratories collaborated with Florida Power & Light to deploy over 2,500 SEL-751 relays across their distribution network, reducing MTTR by nearly 43,000 labor hours within the first operational year.
Expansion of IoT-Based Monitoring Infrastructure Across Distribution Networks
The shift toward distributed energy resources increases the complexity of power flows in distribution grids. Utilities deploy IoT-based monitoring devices to collect granular data and enable decentralized fault detection. It enhances grid visibility, supports remote diagnostics, and accelerates outage restoration efforts. The Transmission and Distribution Fault Detection market reflects a growing reliance on smart sensors and edge computing devices. These tools provide real-time updates on voltage anomalies, equipment conditions, and short circuit events. Utilities leverage this infrastructure to automate inspection routines and minimize manual intervention.
- For instance, Eaton deployed more than 5,800 IoT-enabled fault indicators and line sensors across several U.S. Midwest utility networks.
Rising Deployment of Digital Substations and Advanced Communication Protocols
Digital substations replace legacy systems with intelligent electronic devices and fiber-optic communication networks. They facilitate faster fault detection, isolation, and reconfiguration across transmission lines. The Transmission and Distribution Fault Detection market aligns with this trend by offering solutions compatible with IEC 61850 and other standardized protocols. It enables seamless data exchange between protection relays, breakers, and central control units. Utilities use digital substations to enhance fault response speed and integrate advanced diagnostics into their protection schemes. This shift supports the broader digital transformation of grid operations.
Focus on Cybersecure Fault Detection Platforms in Critical Infrastructure
Utilities strengthen the cybersecurity posture of fault detection systems to mitigate the risk of malicious grid disruptions. Integration of fault detection into critical infrastructure requires secure communication channels and tamper-proof data collection. It prompts vendors to incorporate encryption, authentication, and compliance features into their platforms. The Transmission and Distribution Fault Detection market sees growing demand for NERC CIP-compliant and ISO 27001-certified solutions. Utilities invest in secure firmware updates and network segmentation to safeguard operational technologies. These trends reflect the increasing convergence of power reliability and cyber resilience strategies.
Market Challenges Analysis
High Capital Costs and Integration Complexity Across Legacy Infrastructure
The deployment of advanced fault detection technologies requires substantial capital investment, particularly for utilities with large and aging transmission and distribution networks. Many utilities face budget constraints that limit the adoption of sensor-based monitoring and real-time analytics. Integrating new systems with legacy infrastructure introduces technical challenges, including interoperability issues, data format incompatibility, and lack of standardized protocols. The Transmission and Distribution Fault Detection market must address these integration barriers to accelerate deployment. It also contends with the need for skilled technicians who can manage hybrid systems combining old and new components. Utilities often delay upgrades due to the high cost and disruption risk to existing operations.
Limited Availability of Skilled Workforce and Technical Know-How
Utilities struggle to attract and retain professionals with expertise in grid analytics, automation systems, and AI-based diagnostics. The shortage of technical talent delays fault detection deployment and increases system downtime during integration or maintenance. It restricts the scalability of digital fault monitoring platforms in remote and resource-constrained regions. The Transmission and Distribution Fault Detection market experiences friction in implementation due to the steep learning curve associated with new technologies. Training programs, vendor support, and academic partnerships remain insufficient to meet market demand. Workforce limitations hinder the realization of full system capabilities and weaken return on investment for utilities.
Market Opportunities
Expansion of Electrification in Rural and Underserved Regions
Governments and utilities invest in extending grid infrastructure to remote and underserved areas, creating new demand for fault detection solutions. These regions often lack legacy systems, enabling direct adoption of modern, digital fault monitoring platforms. The Transmission and Distribution Fault Detection market benefits from rural electrification programs that prioritize reliability and cost-efficient maintenance. It supports deployment of compact, low-cost sensors that operate in harsh environmental conditions and limited access zones. Utilities implement remote diagnostics and wireless communication tools to monitor isolated grid segments. This opportunity strengthens market presence in emerging economies across Africa, South Asia, and Latin America.
Development of Utility-Scale Battery Storage and Microgrid Systems
The rise of microgrids and large-scale energy storage installations increases grid complexity and requires accurate, localized fault identification. Utilities integrate detection systems that can isolate faults within segmented networks while maintaining supply from alternative sources. The Transmission and Distribution Fault Detection market aligns with the decentralization of energy by offering modular and scalable solutions. It supports the operational continuity of islanded grids and ensures fast fault clearance in hybrid power architectures. Vendors develop tools tailored for storage nodes, inverters, and distributed control systems. These trends open new avenues in industrial campuses, military bases, and disaster-prone regions adopting energy resilience strategies.
Market Segmentation Analysis:
By Type:
Line faults lead the market due to their high frequency in overhead transmission and distribution networks. Weather-related disruptions, vegetation contact, and conductor fatigue drive demand for real-time fault detection across transmission corridors. Circuit faults follow, with utilities deploying monitoring systems to identify phase-to-ground and phase-to-phase anomalies. Power transformer and distribution transformer faults command attention in urban and industrial grids where asset failure impacts large load segments. The Transmission and Distribution Fault Detection market also sees growth in detecting insulator faults, especially in high-humidity and coastal regions prone to flashovers and tracking issues.
- For instance, Hubbell Power Systems deployed more than 7,400-line monitoring sensors across Texas utility networks to reduce fault location time from 6 hours to under 30 minutes.
By Technology:
Protective relays dominate adoption due to their established use in grid protection schemes and ability to isolate faults within milliseconds. Intelligent electronic devices (IEDs) gain traction for their multi-functionality, integrating fault detection with control and communication tasks. Capacitive voltage transformers contribute to voltage measurement and fault sensing in high-voltage environments. Digital fault recorders support post-event analysis and help utilities refine protection settings based on waveform data. Arc flash detection systems address worker safety and equipment integrity in substations and control centers, offering rapid detection of internal electrical discharges.
- For instance, General Electric deployed IEDs across 560 grid nodes in Western Europe, integrating monitoring, protection, and SCADA compatibility in one system. Capacitive voltage transformers contribute to voltage measurement and fault sensing in high-voltage environments
By End-User:
Utilities represent the largest segment, driven by grid modernization efforts and regulatory mandates to improve reliability indices. Industrial and commercial enterprises invest in localized fault detection to prevent downtime in critical operations. Renewable energy generators require dynamic monitoring tools to manage fluctuating loads and inverter-based connections. The Transmission And Distribution Fault Detection market also serves data centers, which demand high-availability power and fast isolation of electrical faults. Oil and gas companies deploy detection systems in hazardous zones to ensure equipment protection and minimize fire risk.
Segments:
Based on Type:
- Circuit Faults
- Power Transformer Faults
- Distribution Transformer Faults
- Line Faults
- Insulator Faults
Based on Technology:
- Protective Relays
- Capacitive Voltage Transformers
- Intelligent Electronic Devices
- Digital Fault Recorders
- Arc Flash Detection Systems
Based on End-User:
- Utilities
- Industrial and Commercial Enterprises
- Data Centers
- Renewable Energy Generators
- Oil and Gas Companies
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America accounts for a market share of 32.6%, driven by strong investment in grid modernization, aging infrastructure replacement, and wide deployment of digital fault monitoring systems. Utilities in the United States and Canada prioritize fault location and isolation technologies to meet federal reliability standards and avoid penalties related to prolonged outages. The presence of advanced utility analytics platforms and smart grid programs accelerates integration of intelligent electronic devices, digital fault recorders, and arc flash detection systems. It supports early adoption of AI and machine learning in grid fault prediction. Growth also stems from large-scale renewable energy integration in California, Texas, and Ontario, increasing the need for adaptive protection systems. Vendors in this region deliver solutions tailored to NERC compliance, which reinforces regional leadership in fault detection deployment.
Europe
Europe holds a market share of 24.9%, supported by proactive regulatory frameworks and cross-border electricity trading that demands high grid reliability. Countries such as Germany, France, and the UK upgrade transmission networks to align with decarbonization and distributed energy goals. The Transmission And Distribution Fault Detection market in Europe is shaped by digital substation expansion, utility-scale battery storage, and microgrid development. It gains momentum from regional commitments to reduce outage duration and frequency, guided by ENTSO-E standards and local distribution codes. Utilities adopt AI-based diagnostic tools and standardized communication protocols to support interoperable grid operations. The demand for cybersecure detection platforms grows with rising attention to energy system resilience and infrastructure security.
Asia-Pacific
Asia-Pacific commands a market share of 28.7%, reflecting large-scale grid expansion, rural electrification programs, and increasing industrial energy consumption. China, India, Japan, and South Korea drive demand for real-time fault detection as part of their national energy security and modernization plans. Utilities deploy high-voltage fault monitoring systems and low-cost sensors to improve fault visibility across remote and urban regions. The Transmission And Distribution Fault Detection market in Asia-Pacific is characterized by state-sponsored smart grid rollouts, integration of renewable energy sources, and rising electricity demand from transport electrification. Local manufacturers supply cost-efficient technologies, supporting wide-scale adoption. Investments in AI and IoT platforms further expand monitoring capabilities in emerging economies.
Latin America
Latin America represents a market share of 7.3%, supported by upgrades to aging transmission lines and vulnerability to climate-related outages. Countries like Brazil, Mexico, and Chile invest in fault detection systems to improve response times and restore service quickly during storms or infrastructure failures. Regional utilities focus on extending fault monitoring into rural areas with poor grid reliability. It also benefits from solar and wind projects that require advanced protection and monitoring tools. Limited budgets delay full digitization, but international funding and partnerships with global vendors improve access to modern solutions.
Middle East & Africa
The Middle East & Africa account for a market share of 6.5%, driven by electricity infrastructure expansion, industrial development, and grid reliability improvements. Gulf countries invest in high-voltage fault detection systems to support large-scale power transmission and critical infrastructure. In Africa, transmission and distribution networks experience frequent faults due to equipment age and overloading. Governments and donors support modernization through smart metering, digital substations, and remote diagnostics. The Transmission asnd Distribution Fault Detection market in this region grows gradually, supported by hybrid grid models, mini-grids, and increased attention to power quality in urban centers.
Key Player Analysis
- Rockwell Automation
- ZIV
- nVent Electric
- General Electric
- Quanta Technology
- Basler Electric Company
- Siemens
- Raytheon
- Schneider Electric
- Schweitzer Engineering Laboratories
- Amphenol
- Hubbell
- S Electric Company
- ABB
- Eaton
Competitive Analysis
The Transmission and Distribution Fault Detection market features strong competition among leading players such as Schneider Electric, Siemens, General Electric, ABB, Eaton, Rockwell Automation, Hubbell, Schweitzer Engineering Laboratories, Basler Electric Company, Amphenol, Quanta Technology, Raytheon, ZIV, nVent Electric, and S Electric Company. These companies compete through innovation, broad product portfolios, and strong utility partnerships. They focus on advanced solutions integrating real-time monitoring, AI-driven analytics, and digital communication protocols to enhance fault detection accuracy. Product reliability, grid compatibility, and response speed remain key differentiators across competitive offerings. Market leaders invest in R&D to develop compact, modular devices capable of functioning under harsh environmental conditions and complex grid architectures. Strategic collaborations with power utilities and government bodies support large-scale deployments and compliance with regional regulatory standards. Players expand geographic reach by tailoring solutions for mature and emerging grid environments, including digital substations and microgrids. Mergers, acquisitions, and partnerships further strengthen technical expertise and service capabilities across end-user segments. The competitive environment rewards companies that deliver scalable, cybersecure, and cost-effective technologies aligned with evolving grid modernization trends.
Recent Developments
- In October 2024, Schneider Electric the company advanced its digital grid offerings by launching solutions for distribution substations featuring a net‑zero dashboard, enhanced grid resiliency, and improved grid flexibility to optimize smart‑grid energy‑flow management
- In February 2024, Siemens rolled out SICAM PQS along with the PQ Advisor Compact software tools. These solutions integrate fault records and power‑quality data in a single system, deploying AI‑based analytics for early anomaly detection and fault prevention across industrial, infrastructure, and utility environments
Market Concentration & Characteristics
The Transmission and Distribution Fault Detection market demonstrates moderate concentration, with a mix of global technology providers and specialized engineering firms holding significant market influence. It is characterized by high technical complexity, regulatory alignment, and strong end-user dependence on proven grid reliability. The market favors companies with advanced product portfolios that integrate real-time analytics, remote diagnostics, and communication protocol compliance. Large players focus on scalable solutions suitable for utility-scale applications, while niche firms offer tailored systems for industrial, renewable, and microgrid installations. The market relies heavily on integration with existing SCADA, DMS, and substation automation platforms. It exhibits a strong emphasis on standards such as IEEE, IEC 61850, and cybersecurity certifications. Long project cycles, multi-phase deployments, and utility procurement norms shape its commercial dynamics. The presence of aging infrastructure and rapid expansion of decentralized energy assets create parallel demand streams for both retrofit and greenfield installations.
Report Coverage
The research report offers an in-depth analysis based on Type, Technology, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Utilities will expand deployment of real-time fault detection systems to support grid modernization and improve service reliability.
- Integration of AI and machine learning will enhance predictive maintenance and fault localization accuracy.
- Adoption of digital substations will accelerate, driving demand for intelligent fault monitoring devices.
- Renewable energy growth will increase complexity in distribution networks, requiring adaptive fault detection solutions.
- Governments will mandate stricter outage response standards, pushing utilities to invest in advanced fault detection tools.
- Vendors will focus on compact, modular, and interoperable solutions to meet varied grid configurations.
- Emerging economies will increase investments in fault detection as part of rural electrification and infrastructure upgrades.
- Cybersecurity features will become essential in fault detection platforms deployed in critical grid infrastructure.
- Cloud-based analytics and edge computing will support scalable fault monitoring across large power networks.
- Strategic partnerships between utilities and technology firms will accelerate innovation and deployment across regions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Grid Modernization Initiatives
Governments and utilities are investing heavily in upgrading aging transmission and distribution infrastructure, driving the adoption of advanced fault detection systems to improve outage response, operational transparency, and integration of renewable energy.
Rising Renewable Energy Integration
The increasing penetration of solar and wind energy introduces new grid complexities and variability, necessitating sophisticated, real-time fault detection and management solutions to maintain grid stability and power quality.
Aging Power Infrastructure
Many regions face reliability challenges due to aging transformers, cables, and switchgear, making early fault detection essential to prevent costly blackouts, extend asset lifecycles, and support condition-based maintenance strategies.
Regulatory Mandates for Grid Reliability
Stricter reliability standards and outage response regulations require utilities to deploy robust monitoring and fault detection systems, reducing downtime and ensuring compliance with performance-based incentives and penalties.
Adoption of AI, IoT, and Digital Substations
The integration of AI-driven analytics, IoT-based monitoring, and digital substations enables more accurate, predictive, and automated fault detection, supporting utilities in minimizing manual intervention and enhancing grid resilience.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Transmission and Distribution Fault Detection market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Transmission and Distribution Fault Detection Market projected to grow between 2025 and 2032?
Which Transmission and Distribution Fault Detection market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Transmission and Distribution Fault Detection market?
Who are the leading companies in the Transmission and Distribution Fault Detection Market?
Which region commanded the largest share of the Transmission and Distribution Fault Detection market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Circuit Faults
- 1.2.2 Power Transformer Faults
- 1.2.3 Distribution Transformer Faults
- 1.2.4 Line Faults
- 1.2.5 Insulator Faults
- 1.3 By End-User
- 1.3.1 Utilities
- 1.3.2 Industrial and Commercial Enterprises
- 1.3.3 Data Centers
- 1.3.4 Renewable Energy Generators
- 1.3.5 Oil and Gas Companies
- 1.4 By Technology
- 1.4.1 Protective Relays
- 1.4.2 Capacitive Voltage Transformers
- 1.4.3 Intelligent Electronic Devices
- 1.4.4 Digital Fault Recorders
- 1.4.5 Arc Flash Detection Systems
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 22,730 million → 2032: USD 49,150.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Transmission and Distribution Fault Detection Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Transmission and Distribution Fault Detection Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Transmission and Distribution Fault Detection Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Transmission and Distribution Fault Detection Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Transmission and Distribution Fault Detection Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Transmission and Distribution Fault Detection Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Transmission and Distribution Fault Detection Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Transmission and Distribution Fault Detection Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 22,730 million → 2032: USD 49,150.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Transmission and Distribution Fault Detection Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Circuit Faults
- 12.3.7.2 Power Transformer Faults
- 12.3.7.3 Distribution Transformer Faults
- 12.3.7.4 Line Faults
- 12.3.7.5 Insulator Faults
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Utilities
- 12.4.7.2 Industrial and Commercial Enterprises
- 12.4.7.3 Data Centers
- 12.4.7.4 Renewable Energy Generators
- 12.4.7.5 Oil and Gas Companies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Protective Relays
- 12.5.7.2 Capacitive Voltage Transformers
- 12.5.7.3 Intelligent Electronic Devices
- 12.5.7.4 Digital Fault Recorders
- 12.5.7.5 Arc Flash Detection Systems
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Transmission and Distribution Fault Detection End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Transmission and Distribution Fault Detection Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Transmission and Distribution Fault Detection Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Transmission and Distribution Fault Detection Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Schneider Electric
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Siemens
- 18.4 ABB
- 18.5 Eaton
- 18.6 General Electric
- 18.7 Rockwell Automation
- 18.8 Hubbell
- 18.9 Schweitzer Engineering Laboratories
- 18.10 Basler Electric Company
- 18.11 Raytheon
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

