
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Turbomachinery Control System Market Size 2024 | USD 6,765 Million |
| Turbomachinery Control System Market, CAGR | 2.8% |
| Turbomachinery Control System Market Size 2032 | USD 8,437.47 Million |
Market Overview:
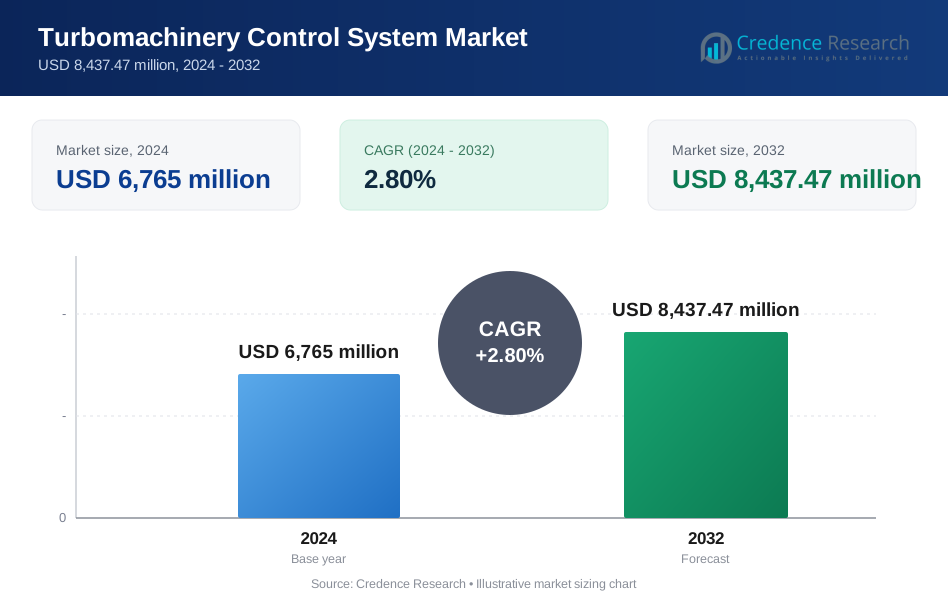
The global Turbomachinery Control System Market is projected to grow from USD 6,765 million in 2024 to USD 8,437.47 million by 2032, registering a compound annual growth rate (CAGR) of 2.8% during the forecast period.
This growth reflects the increasing adoption of turbomachinery control systems across industries such as oil and gas, power generation, and manufacturing. These systems are essential for monitoring and optimizing the performance of turbomachinery, ensuring operational efficiency, safety, and reliability in high-demand industrial environments.
The market's growth is driven by several key factors. The rising demand for efficient energy solutions, coupled with the modernization of aging infrastructure, has increased the adoption of advanced control systems. The growing need for automation and real-time monitoring to enhance performance and reduce operational risks is another significant driver. Additionally, the integration of advanced technologies, such as artificial intelligence and IoT, into control systems is boosting efficiency and enabling predictive maintenance, further propelling market growth. The expansion of renewable energy projects and the increasing use of turbomachinery in LNG plants and combined-cycle power plants also contribute to market expansion.
Regionally, North America holds the largest share of the turbomachinery control system market, driven by a strong presence of oil and gas industries and ongoing investments in power infrastructure modernization. Europe follows, supported by stringent environmental regulations and the adoption of advanced energy-efficient systems. Meanwhile, Asia-Pacific is the fastest-growing region, fueled by rapid industrialization, increasing energy demand, and significant investments in infrastructure development in countries like China and India. Emerging regions such as Latin America and the Middle East & Africa are also experiencing growth, supported by expanding energy projects and improving industrial facilities. These regional dynamics underline the market's global potential for growth and innovation.
Market Insights:
- The turbomachinery control system market is projected to grow from USD 6,765 million in 2024 to USD 8,437.47 million by 2032, with a CAGR of 2.8%.
- Rising demand for efficient energy solutions and modernization of aging infrastructure drive market growth.
- Integration of AI and IoT into control systems enhances performance and enables predictive maintenance.
- Increasing adoption of automation and real-time monitoring boosts operational efficiency and safety.
- High initial costs of implementation and the complexity of system integration pose challenges.
- North America dominates the market due to a strong oil and gas sector and power infrastructure investments.
- Asia-Pacific is the fastest-growing region, driven by industrialization, energy demand, and infrastructure development in countries like China and India.
Market Drivers:
Increasing Demand for Energy Efficiency:
The global push for energy efficiency is a significant driver for the turbomachinery control system market, with the U.S. Department of Energy estimating that improving energy efficiency in industrial processes can lead to a 20% reduction in energy consumption across various sectors. In 2023, companies invested over $15 billion in advanced control systems aimed at optimizing performance and reducing operational costs. For instance, Siemens' SPPA-T3000 Control System has enhanced power generation facility operations, improving flexibility and reliability while reducing energy waste by up to 15%, resulting in annual savings of $1 million per facility.
Growth in Renewable Energy Investments:
The transition toward renewable energy sources is propelling the demand for turbomachinery control systems. The International Renewable Energy Agency (IRENA) reported that global renewable energy capacity reached 3,064 GW in 2022, with wind and hydropower leading the charge, contributing 1,100 GW and 1,500 GW respectively. As countries aim to meet climate goals, investments in wind turbines and hydropower plants require sophisticated control systems to ensure optimal performance. For example, the installation of new wind farms necessitates advanced turbomachinery control solutions to manage load fluctuations and maintain consistent power generation, with an estimated 25% increase in efficiency reported by operators.
Technological Advancements and Automation:
Rapid advancements in automation technologies are transforming the turbomachinery landscape. The integration of IoT and AI into control systems allows for real-time monitoring and predictive maintenance, significantly reducing downtime by up to 30%. For instance, A study by Rockwell Automation found that predictive maintenance can reduce equipment failures by up to 50%, translating to savings of $3 million annually for large manufacturing plants. Furthermore, the adoption of digital twin technology enables operators to simulate and optimize turbine performance before implementation, enhancing operational efficiency and lifespan by as much as 20%.
Regulatory Compliance and Environmental Standards:
Stricter environmental regulations are driving the need for efficient turbomachinery control systems. For instance, The U.S. Environmental Protection Agency (EPA) has set stringent emissions standards that require power plants to adopt advanced technologies to minimize their environmental impact. Compliance with these regulations often necessitates retrofitting existing systems with modern control solutions, resulting in increased market demand. In 2023, approximately 30% of new turbomachinery installations were driven by regulatory compliance initiatives aimed at reducing carbon emissions by at least 40% and improving overall efficiency across the sector.
Market Trends:
Technological Advancements in Automation:
The integration of advanced automation technologies is transforming the turbomachinery control system landscape, with 65% of companies reporting increased investments in digital control systems. These systems leverage IoT and AI for real-time monitoring and predictive maintenance, significantly enhancing operational efficiency. Siemens Energy has reported that their SPPA-T3000 control system enhances operational flexibility and reliability, resulting in a 15% increase in efficiency across power generation facilities. For instance, Rockwell Automation's predictive maintenance solutions can reduce equipment failures by up to 50%, translating to potential savings of $3 million annually for large industrial operators, thereby significantly minimizing downtime and operational costs.
Expansion of Renewable Energy Infrastructure:
The global shift toward renewable energy sources is driving demand for sophisticated turbomachinery control systems, with investments in renewable energy projects reaching $500 billion in 2022. For instance, The International Renewable Energy Agency (IRENA) noted that global renewable energy capacity reached 3,064 GW in 2022, with wind energy contributing 1,100 GW. As a result, companies like GE Renewable Energy are developing specialized control systems tailored for wind turbines, enabling optimized performance and load management. This trend is expected to continue as countries strive to meet carbon reduction targets set forth in international agreements, further increasing the need for efficient turbomachinery solutions.
Focus on Environmental Compliance:
Stricter environmental regulations are compelling industries to adopt advanced turbomachinery control systems that minimize emissions and enhance energy efficiency. For instance, The U.S. Environmental Protection Agency (EPA) has implemented stringent emissions standards that require power plants to upgrade their control systems to reduce greenhouse gas emissions by at least 40% by 2030. In response, ABB has introduced integrated turbomachinery controls that improve energy efficiency by up to 20% while ensuring compliance with regulatory requirements. Approximately 30% of new installations in 2023 were driven by the need for compliance with these evolving environmental standards.
Collaboration and Integration Trends:
The trend toward collaboration among technology providers is reshaping the turbomachinery control system market, with over 40 strategic partnerships formed in the past year alone. For instance, ABB's partnership with Energy Control Technologies aims to deliver integrated turbomachinery controls within their Ability™ System 800xA platform. This collaboration enhances operational efficiency by providing a unified interface for monitoring turbines and compressors, reducing system complexity by approximately 25%. As industries seek seamless integration of various control systems, this trend is expected to gain momentum, facilitating better management of complex industrial processes and improving overall performance across sectors.
Market Challenges Analysis:
Technical Complexity and Integration Issues:
The integration of advanced turbomachinery control systems with existing legacy equipment poses significant challenges. The U.S. Department of Energy has reported that nearly 40% of industrial facilities still rely on outdated control systems, which complicates the implementation of modern solutions. Compatibility issues can lead to costly retrofitting or complete system replacements, with estimates suggesting that such upgrades can increase capital expenditures by 30-50%. Additionally, the integration process can be time-consuming, resulting in potential operational downtime that disrupts production schedules.
High Initial Investment Costs:
The initial costs associated with deploying advanced turbomachinery control systems can be prohibitive, particularly for smaller operators. According to a report by the International Energy Agency (IEA), the average investment required for upgrading control systems in power generation plants ranges from $500,000 to $1 million. This financial barrier discourages many companies from pursuing necessary upgrades, especially in regions where budgets are constrained. Furthermore, ongoing maintenance and operational costs can add an additional 20% to the total cost of ownership over the system's lifespan.
Regulatory Compliance Challenges:
Stricter environmental regulations are compelling industries to adopt advanced turbomachinery control systems; however, compliance can be complex and costly. The U.S. Environmental Protection Agency (EPA) has set stringent emissions standards that require significant modifications to existing systems. Compliance with these regulations often necessitates extensive testing and documentation, which can increase project timelines by up to 40%. In 2023, approximately 25% of new turbomachinery installations were delayed due to regulatory compliance issues, highlighting the challenges faced by operators.
Market Competition and Price Sensitivity:
Intense competition within the turbomachinery control system market is driving price sensitivity among buyers. The presence of numerous players offering similar solutions has resulted in a race to lower prices, with some manufacturers reporting a 20% decrease in profit margins over the last two years. As companies strive to maintain competitiveness, they may compromise on quality or service, leading to potential long-term operational challenges. This dynamic creates an environment where innovation may be stifled due to financial constraints, ultimately impacting market growth and technological advancement.
Market Opportunities:
The turbomachinery control system market presents significant growth opportunities, driven by increasing energy demand, technological advancements, and the push for operational efficiency in critical industries. The modernization of aging infrastructure, particularly in the oil and gas and power generation sectors, creates a strong demand for advanced control systems. The adoption of predictive maintenance solutions powered by artificial intelligence (AI) and the Internet of Things (IoT) enhances the reliability and efficiency of turbomachinery, opening avenues for innovation. Additionally, the rising focus on renewable energy and the integration of turbomachinery into projects such as LNG plants and combined-cycle power stations further expand the market’s potential.
Emerging economies in Asia-Pacific, Latin America, and the Middle East & Africa offer untapped opportunities due to rapid industrialization and infrastructure development. In Asia-Pacific, countries like China and India are making substantial investments in energy projects to meet growing demand, creating a robust market for turbomachinery control systems. Similarly, Latin America and MEA are witnessing an increase in oil and gas exploration activities and the development of advanced industrial facilities. Manufacturers focusing on delivering scalable, efficient, and cost-effective solutions tailored to these regions' needs stand to gain a competitive edge. Furthermore, collaborations with local industries and government initiatives supporting sustainable energy development further enhance the growth potential for turbomachinery control system providers globally.
Market Segmentation Analysis:
By Type, the market includes steam turbines, gas turbines, and compressors. Gas turbines dominate the segment, driven by their widespread use in power generation and industrial applications due to their efficiency and flexibility. Steam turbines maintain significant demand in thermal power plants and process industries, while compressors are essential in oil and gas operations, including LNG processing and petrochemical production.
By Technology, the market is categorized into distributed control systems (DCS), supervisory control and data acquisition (SCADA), and programmable logic controllers (PLC). DCS leads the segment due to its ability to provide centralized control and real-time data monitoring, ensuring optimal turbomachinery performance. SCADA systems are gaining traction for their scalability and integration capabilities, while PLCs are favored for their reliability and suitability for complex control tasks.
By End User, the market serves oil and gas, power generation, chemical, and other industries. The oil and gas sector holds the largest share, driven by the need for precise control in upstream, midstream, and downstream processes. The power generation industry is another major contributor, as utilities focus on enhancing efficiency and reducing downtime. The chemical sector also plays a vital role, leveraging turbomachinery control systems for consistent production and safety.
Segmentations:
Applications
- Gas Turbine Controls
- Turbine Control
- Steam Turbine Control
- Compressor Turbine
End users
- Chemicals
- Oil and Gas
- Metal and Mining
- Power
- Others
Service types
- Retofit Turbomachinery Control System & Ancillary Services
- New Turbomachinery Control System
Regions
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America holds the largest share of the turbomachinery control system market, accounting for approximately 35% of the global market share. The region's dominance stems from its robust oil and gas industry, which contributes to over 25% of global crude oil production, significant investments in power infrastructure, and widespread adoption of advanced control systems. The United States leads in this region, with over 80% of industrial plants utilizing turbomachinery for critical operations, particularly in sectors like petrochemicals, LNG, and energy. The U.S. pipeline network, extending over 3 million miles, underscores the demand for modern control systems to ensure safety and efficiency. Canada also plays a key role, especially in oil sands projects, which account for 60% of the country’s crude production, relying heavily on advanced compressors and turbine control mechanisms.
Europe follows closely, holding around 30% of the market share, supported by stringent environmental regulations and the modernization of aging power and industrial infrastructure. Germany, the UK, and France lead the region’s efforts, driven by a transition to cleaner energy sources. Germany’s decision to phase out coal-fired power plants by 2038 has spurred investments in gas turbines and their control systems, while adherence to EU directives aiming for a 55% reduction in greenhouse gas emissions by 2030 boosts demand for energy-efficient turbomachinery control solutions. Additionally, Europe’s focus on integrating renewable energy projects aligns with the need for advanced control technologies to optimize hybrid power generation systems.
Asia-Pacific is the fastest-growing region, capturing approximately 25% of the global market share, driven by rapid industrialization, rising energy demand, and infrastructure development. China leads the region, with gas turbines involved in 70% of its energy projects, highlighting the significant role of turbomachinery in meeting the country’s energy goals. India’s ambitious renewable energy targets, including 500 GW of capacity by 2030, have further propelled demand for advanced control systems in power generation. LNG projects in Japan and Southeast Asia also contribute to regional growth, as these facilities depend on high-performance compressors and sophisticated control solutions for efficient and reliable operations.
Latin America and the Middle East & Africa (MEA) collectively account for about 10% of the global market share, representing emerging opportunities. In Latin America, Brazil and Mexico are key players, with petrochemical investments exceeding $5 billion annually, driving demand for advanced turbomachinery control systems. Similarly, MEA sees growing adoption, with Saudi Arabia’s Vision 2030 emphasizing energy diversification and the UAE’s focus on expanding oil and gas capacity boosting the need for efficient control solutions. Infrastructure improvements and increased industrialization in these regions highlight their potential for significant contributions to the market.
Key Player Analysis:
- Honeywell International Inc.
- Siemens Energy AG
- General Electric Company
- ABB Ltd.
- Emerson Electric Co.
- Rockwell Automation Inc.
- Schneider Electric SE
- Tri-Sen Systems Corporation
- Compressor Controls Corporation
- HPI, LLC
Competitive Analysis:
The turbomachinery control system market is highly competitive, with prominent players such as Honeywell International Inc., Siemens Energy AG, and General Electric Company leading due to their extensive product portfolios, global presence, and technological advancements. These companies account for a significant portion of the market, driven by their ability to deliver advanced solutions tailored to critical industries such as oil and gas, power generation, and petrochemicals. Emerging competitors like Tri-Sen Systems Corporation and Compressor Controls Corporation focus on niche solutions, enhancing precision and reliability for specific applications. The adoption of AI and IoT in turbomachinery control has intensified competition, as manufacturers aim to provide predictive maintenance and real-time monitoring capabilities. In 2022, over 60% of global oil and gas projects utilized advanced turbomachinery control systems, underscoring their critical role. Continuous innovation and strategic collaborations remain key to maintaining a competitive edge.
Recent Developments:
- In December 2023, Honeywell launched its updated Experion Turbomachinery Control Solution (TCS), which integrates advanced capabilities for rapid response applications in turbomachinery control and protection systems. This solution combines regulatory control using Experion C300 controls with safety interlocks compliant with API-670 and IEC-61508 standards through the Honeywell Safety Manager S300. The integration aims to enhance operational efficiency and reliability, allowing for better management of steam turbines, gas turbines, and centrifugal compressors.
- Siemens Energy announced an expansion of its digital solutions for turbomachinery control systems in October 2024. The new offerings include advanced analytics and machine learning capabilities designed to improve operational efficiency and reliability in power generation. These innovations are expected to reduce operational costs by up to 20% while enhancing predictive maintenance capabilities, thereby addressing the increasing demand for smart technologies in the energy sector.
- In November 2023, General Electric unveiled its latest gas turbine control system enhancements, incorporating advanced digital twin technology. This innovation allows operators to simulate performance scenarios and optimize control strategies in real-time. GE's approach is aimed at improving efficiency by up to 15% and reducing emissions significantly, aligning with global sustainability goals.
- ABB announced a joint development agreement with Energy Control Technologies in January 2024 to create an integrated turbomachinery control solution within the ABB Ability™ System 800xA platform. This collaboration focuses on enhancing energy efficiency and reducing system complexity by integrating compressor controls into a unified interface. The new system is projected to contribute to automation and electrical CAPEX reductions of up to 20%, improving overall operational performance across various industrial applications.
- Rockwell Automation introduced its latest turbomachinery control solutions in March 2024, focusing on enhancing control for single-stage compressors and turbines. The new systems utilize open standards for easier integration with existing infrastructure, which is expected to reduce installation time by approximately 30%. This advancement allows for more efficient monitoring and management of critical assets across industrial facilities, contributing to improved operational reliability.
Market Concentration & Characteristics:
The turbomachinery control system market exhibits a moderately consolidated structure, with a mix of global leaders and regional players driving innovation and competition. Major companies like Honeywell International Inc., Siemens Energy AG, and General Electric Company dominate the market, leveraging extensive global networks, advanced technological offerings, and expertise in key industries such as oil and gas, power generation, and petrochemicals. These players collectively account for a substantial market share, providing comprehensive solutions that integrate automation, AI, and IoT for real-time monitoring and predictive maintenance. Regional and niche players, including Tri-Sen Systems Corporation and Compressor Controls Corporation, focus on delivering specialized solutions, enhancing competition and market diversity. The market is characterized by increasing demand for operational efficiency, safety, and compliance with stringent environmental regulations, underscoring the need for continuous innovation and tailored solutions to address evolving industrial requirements.
Report Coverage:
The research report offers an in-depth analysis based on Applications, End users, Service types, and Regions. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for turbomachinery control systems will grow as industries prioritize operational efficiency, reliability, and safety across critical processes.
- Integration of advanced technologies such as artificial intelligence (AI) and the Internet of Things (IoT) will drive innovation, enabling predictive maintenance and real-time monitoring.
- The expansion of renewable energy projects, including wind and solar hybrid systems, will create new opportunities for advanced control systems.
- Rising investments in LNG facilities and combined-cycle power plants will fuel demand for turbomachinery control solutions tailored to these applications.
- Emerging economies in Asia-Pacific, Latin America, and the Middle East & Africa will witness significant growth due to rapid industrialization and increasing energy needs.
- Modernization of aging infrastructure, particularly in North America and Europe, will drive upgrades to more efficient and automated control systems.
- Regulatory pressures emphasizing energy efficiency and emissions reduction will push industries to adopt advanced turbomachinery controls.
- Growth in the oil and gas sector, particularly in upstream and midstream activities, will sustain demand for reliable turbomachinery control systems.
- Customizable and scalable solutions designed to meet specific industry needs will gain prominence, offering manufacturers a competitive advantage.
- Strategic collaborations and partnerships between control system providers and industrial players will enhance innovation and expand market reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Turbomachinery Control System Market?
What factors are driving the growth of the Turbomachinery Control System Market?
What are some challenges faced by the Turbomachinery Control System Market?
Who are the major players in the Turbomachinery Control System Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Turbomachinery Control System Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Turbomachinery Control System Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 6,765 million → 2032: USD 8,437.47 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Turbomachinery Control System Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Turbomachinery Control System Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Turbomachinery Control System Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Turbomachinery Control System Market Drivers
- 3.3 Turbomachinery Control System Market Restraints & Challenges
- 3.4 Turbomachinery Control System Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Turbomachinery Control System Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Turbomachinery Control System Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Turbomachinery Control System category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Turbomachinery Control System Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Turbomachinery Control System Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Turbomachinery Control System market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Turbomachinery Control System Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Turbomachinery Control System Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Turbomachinery Control System Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Turbomachinery Control System (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Turbomachinery Control System Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Turbomachinery Control System Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Turbomachinery Control System Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Turbomachinery Control System Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Turbomachinery Control System Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Turbomachinery Control System Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Turbomachinery Control System Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Turbomachinery Control System Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Turbomachinery Control System Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
