
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| UAE Contract Cleaning Services Market Size 2023 | USD 801.19 million |
| UAE Contract Cleaning Services Market, CAGR | 4.03% |
| UAE Contract Cleaning Services Market Size 2032 | USD 1,145.90 million |
Market Overview
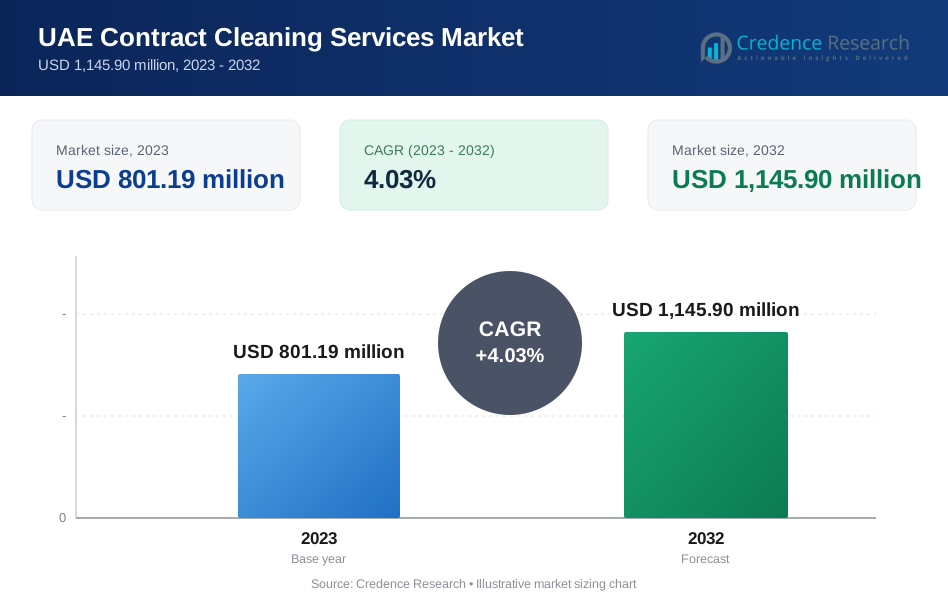
The UAE Contract Cleaning Services Market is expected to grow from USD 801.19 million in 2023 to USD 1,145.90 million by 2032, with a compound annual growth rate (CAGR) of 4.03%.
The UAE contract cleaning services market is driven by the increasing demand for professional cleaning solutions across commercial, residential, and industrial sectors. The rapid growth of the real estate and hospitality industries, along with heightened awareness of hygiene standards, fuels market expansion. Additionally, the rise in government initiatives promoting cleanliness and health safety, particularly in public spaces, further propels demand. The growing preference for outsourced cleaning services due to cost-efficiency and the need for specialized expertise also contributes to market growth. Key trends include the adoption of eco-friendly and sustainable cleaning practices, with a focus on using green cleaning products and technologies. Moreover, the integration of advanced cleaning technologies, such as robotics and automation, is becoming increasingly prevalent, improving service efficiency and quality. These drivers and trends are expected to support the continued growth of the UAE contract cleaning services market in the coming years.
The UAE contract cleaning services market is geographically diverse, with key players operating across major regions such as Dubai, Abu Dhabi, Sharjah, and Ajman. Dubai and Abu Dhabi dominate the market due to their thriving commercial and residential sectors, while Sharjah and Ajman are emerging markets driven by industrial and residential developments. Key players in the market include AISS Group, Blue Diamond Facilities Management, Adeeb Group, and Transguard Group, among others. These companies offer a range of services from general cleaning to specialized solutions for sectors like hospitality, healthcare, and education. International players such as Sodexo and Dussmann Group also have a strong presence in the UAE, bringing global expertise and advanced cleaning technologies. As the demand for professional and sustainable cleaning solutions grows, these key players continue to innovate, leveraging technological advancements and eco-friendly practices to meet the evolving needs of the market.
Market Insights
- The UAE contract cleaning services market was valued at USD 801.19 million in 2023 and is projected to reach USD 1,145.90 million by 2032, growing at a CAGR of 4.03%.
- The increasing demand for cleanliness in commercial, residential, and industrial spaces drives market growth.
- The rise in eco-friendly and sustainable cleaning solutions is shaping market trends, with a growing preference for green cleaning services.
- Technology integration, including automation and AI, is improving service efficiency and reducing costs in the cleaning sector.
- Intense competition among local and international players puts pressure on pricing and profitability.
- Labor shortages and high turnover rates in the cleaning industry can impact service quality and efficiency.
- Dubai and Abu Dhabi hold the largest market share, with rapid urbanization and infrastructure development fueling demand for cleaning services in these regions.
Market Drivers
Expansion of the Real Estate and Hospitality Industries
The rapid growth of the real estate and hospitality sectors in the UAE is another key factor driving the contract cleaning services market. For instance, the UAE hospitality market is projected to grow significantly, driven by the increasing presence of hotel chains and luxury establishments. The development of new residential complexes, commercial properties, and luxury hotels has created a demand for regular and specialized cleaning services. As property owners and managers seek to maintain high standards of cleanliness and appearance, outsourced cleaning services are increasingly becoming the preferred solution. The expansion of large-scale infrastructure projects such as Expo 2020 Dubai has also contributed to the growth of the cleaning services market.
Adoption of Sustainable and Technologically Advanced Cleaning Practices
The increasing adoption of eco-friendly cleaning solutions and advanced technologies is shaping the future of the UAE contract cleaning services market. For example, the Ministry of Industry and Advanced Technology (MoIAT) has emphasized the importance of integrating advanced technologies and sustainable practices in various sectors. There is a growing preference for green cleaning products that minimize environmental impact, as businesses and consumers become more environmentally conscious. Additionally, the integration of technology such as robotics, automation, and AI-driven solutions is improving the efficiency and quality of cleaning services. These innovations not only enhance service delivery but also meet the rising demand for sustainable practices in the cleaning industry.
Growing Demand for Hygiene and Cleanliness
The increasing focus on hygiene and cleanliness across various sectors in the UAE is a significant driver for the contract cleaning services market. In the wake of the COVID-19 pandemic, there has been a heightened awareness of the importance of maintaining clean environments, especially in commercial and public spaces. The government’s emphasis on health and safety standards has further escalated the demand for professional cleaning services. This trend is particularly evident in high-traffic areas such as shopping malls, airports, and office buildings, where maintaining cleanliness is crucial for the well-being of employees, visitors, and customers.
Shift Towards Outsourcing Cleaning Services
Many businesses in the UAE are shifting towards outsourcing their cleaning needs rather than managing in-house cleaning teams. This shift is driven by the need to reduce operational costs and improve efficiency. Outsourcing cleaning services allows businesses to focus on their core operations while ensuring that cleaning tasks are handled by professionals with the right expertise and equipment. Moreover, outsourced cleaning services provide flexibility in terms of scheduling and service customization, further making them an attractive option for businesses.
Market Trends
Increasing Demand for Green Cleaning Solutions
A significant trend in the UAE contract cleaning services market is the growing demand for eco-friendly and sustainable cleaning solutions. For instance, a report by Imdaad highlights that the UAE's Vision 2030 plan has significantly influenced the adoption of green cleaning practices. With rising environmental awareness, businesses and consumers are increasingly prioritizing the use of green cleaning products that are non-toxic and environmentally safe. The UAE government’s push for sustainability and green initiatives has also influenced this trend, encouraging companies to adopt practices that reduce their carbon footprint. As a result, contract cleaning service providers are incorporating biodegradable cleaning agents, energy-efficient equipment, and eco-friendly waste disposal methods to cater to this demand.
Integration of Advanced Cleaning Technologies
The use of advanced technologies is a prominent trend in the UAE’s contract cleaning services sector. Automation, robotics, and artificial intelligence (AI) are being integrated into cleaning practices to improve efficiency, reduce labor costs, and enhance service quality. Robotic vacuum cleaners and automated floor scrubbers, for instance, are being deployed in large facilities and commercial buildings to ensure thorough and consistent cleaning. AI-based solutions are also helping cleaning companies optimize their operations by predicting cleaning schedules and resource allocation. These technological advancements are driving the evolution of the cleaning services market towards smarter, more efficient solutions.
Customization of Cleaning Services
There is an increasing trend towards the customization of cleaning services in the UAE market. Businesses and property owners are seeking tailored cleaning solutions that meet their specific needs, rather than relying on generic services. This trend is particularly evident in the commercial and hospitality sectors, where cleaning requirements vary significantly based on the size of the facility, the type of industry, and the volume of foot traffic. Cleaning service providers are offering more flexible contracts and personalized plans, allowing clients to adjust services according to their schedules and preferences. This shift towards customization enhances customer satisfaction and loyalty.
Focus on Health and Safety Standards
As health and safety continue to be top priorities, particularly in high-traffic public and commercial spaces, cleaning service providers in the UAE are increasingly focusing on maintaining high sanitation standards. For example, Dubai Municipality has implemented stringent health and safety regulations to ensure high standards of cleanliness in public and commercial spaces. This trend is driven by stricter regulations, including those implemented in response to the pandemic, which have raised the bar for cleanliness in public spaces, offices, and healthcare facilities. As businesses and institutions strive to ensure a safe environment for employees, customers, and visitors, they are turning to professional cleaning services to meet these elevated hygiene standards. This focus on health and safety is expected to remain a key trend in the market moving forward.
Market Challenges Analysis
High Competition and Pricing Pressure
One of the primary challenges in the UAE contract cleaning services market is the intense competition among service providers. The market is saturated with numerous players, ranging from large, established companies to small local firms, each vying for contracts across various sectors. This high level of competition often leads to pricing pressure, where companies are forced to offer services at lower rates to remain competitive. As a result, many cleaning service providers struggle to maintain profitability while still delivering high-quality services. Smaller businesses, in particular, may face difficulties in sustaining operations due to the thin margins and the constant need to invest in advanced equipment and skilled labor to meet customer expectations.
Labor Shortages and Dependence on Skilled Workforce
Another significant challenge is the reliance on a skilled and consistent workforce. For example, the UAE Labour Market Observatory has reported that the cleaning industry faces high turnover rates and a shortage of skilled labor. The UAE contract cleaning services market is highly dependent on labor, with many companies hiring workers from overseas. However, issues such as labor shortages, high turnover rates, and the need for specialized cleaning skills can affect service quality and operational efficiency. The fluctuating availability of skilled labor, compounded by strict labor regulations and visa policies, creates an ongoing challenge for cleaning service providers in maintaining a stable and trained workforce. Additionally, training and retaining employees can be costly, especially in a competitive labor market, making it difficult for companies to consistently deliver high-standard services.
Market Opportunities
The UAE contract cleaning services market presents several significant opportunities driven by the country's ongoing development and demand for cleanliness and hygiene. As the real estate, hospitality, and tourism industries continue to expand, there is a growing need for reliable, professional cleaning services to maintain high standards of cleanliness in commercial buildings, residential complexes, hotels, and public spaces. This growth offers ample opportunities for cleaning service providers to secure long-term contracts, particularly in high-demand sectors like healthcare, education, and retail. With the UAE's focus on infrastructure development, especially in major cities like Dubai and Abu Dhabi, businesses can tap into new opportunities by offering specialized cleaning services for newly constructed buildings, malls, and office spaces.
Another key opportunity lies in the increasing trend toward sustainability and eco-friendly practices. The demand for green cleaning solutions, including biodegradable products and energy-efficient equipment, is rapidly gaining traction among both businesses and consumers in the UAE. Cleaning service providers that adopt sustainable practices and offer eco-friendly cleaning options can differentiate themselves in a crowded market, attracting environmentally conscious clients. Additionally, the integration of advanced technologies such as automation, robotics, and artificial intelligence (AI) in cleaning operations presents a promising opportunity for service providers to enhance efficiency, reduce costs, and improve service quality. By investing in these technologies, cleaning companies can position themselves as leaders in innovation while meeting the evolving demands of the market.
Market Segmentation Analysis:
By Service Type:
The UAE contract cleaning services market can be segmented based on service types, including window cleaning, floor and carpet cleaning, upholstery cleaning, construction cleaning, and other specialized services. Window cleaning remains a high-demand service, particularly in commercial buildings with large glass facades. Floor and carpet cleaning services are essential across various sectors, with a growing demand for professional cleaning solutions to maintain the appearance and hygiene of high-traffic areas. Upholstery cleaning, driven by the need to maintain clean and sanitized furniture, is gaining traction in the hospitality and office sectors. Construction cleaning, focusing on removing debris and ensuring safety after construction projects, is another key segment that caters to the booming real estate and infrastructure developments in the UAE. Additionally, the “Others” category includes niche services, such as specialized cleaning for industries like aviation, healthcare, and more, which are seeing steady growth due to sector-specific hygiene and safety requirements.
By End-use:
The contract cleaning services market in the UAE is also segmented based on end-use, with residential, industrial, and commercial sectors being the primary contributors. The residential segment is driven by the growing number of luxury properties and apartments in urban areas. The industrial segment requires specialized cleaning for factories and warehouses, with a focus on maintaining hygiene in production environments. The commercial segment encompasses a wide range of end-users, including healthcare facilities, educational institutions, hotels, restaurants, retail outlets, corporate offices, and financial institutions. Healthcare and medical facilities require high standards of sanitation and infection control, driving the demand for professional cleaning services. Educational institutions and corporate offices require regular cleaning to ensure a clean and conducive environment. The hospitality sector, including hotels and restaurants, represents a large portion of the market, requiring both regular cleaning and specialized services to maintain hygiene standards. Retail outlets and financial institutions also demand high-quality cleaning solutions to create a welcoming and hygienic environment for their clients and customers.
Segments:
Based on Service Type:
- Window Cleaning
- Floor & Carpet Cleaning
- Upholstery Cleaning
- Construction Cleaning
- Others
Based on End-use:
- Residential
- Industrial
- Commercial
- Healthcare & Medical Facilities
- Educational Institutions
- Hotels & Restaurants
- Retail Outlets
- Corporate Offices
- Financial Institutions
- Others
Based on the Geography:
- Abu Dhabi
- Dubai
- Sharjah
- Ajman
- Fujairah
- Ras Al Khaimah
- Umm Al Quwain
Regional Analysis
Abu Dhabi and Dubai
Abu Dhabi and Dubai dominate the UAE contract cleaning services market, accounting for the largest market share. Dubai leads with approximately 40% of the market share due to its position as the commercial and tourism capital of the UAE. Its rapid urban development, including high-rise buildings, luxury hotels, malls, and office complexes, drives the demand for cleaning services. Abu Dhabi follows closely with around 35% market share, benefiting from its status as the capital and a hub for government buildings, healthcare facilities, and large-scale infrastructure projects. Both regions continue to experience strong growth in the real estate, hospitality, and commercial sectors, further fueling the demand for professional cleaning services.
Sharjah and Ajman
Sharjah holds a notable share of the contract cleaning services market, contributing about 12% due to its industrial base and growing commercial and residential sectors. The expansion of industrial zones, factories, warehouses, and residential complexes in Sharjah drives the need for specialized cleaning services. Ajman, with around 6% of the market share, is an emerging market with a focus on residential development and growing demand for cleaning services in both commercial and hospitality sectors. As tourism and infrastructure development continue to grow in Ajman, the demand for cleaning services in hotels, restaurants, and retail outlets is also increasing, further supporting the market’s growth in this region.
Fujairah and Ras Al Khaimah
Fujairah and Ras Al Khaimah are experiencing steady growth, though they contribute a smaller share to the overall UAE market. Fujairah holds approximately 3% of the market share, driven by its expanding tourism and residential sectors. The region’s development of hotels, resorts, and residential complexes creates a growing demand for professional cleaning services. Similarly, Ras Al Khaimah, with around 4% market share, benefits from its expanding real estate and tourism sectors, particularly in hospitality and residential spaces. Both regions are expected to see continued growth in cleaning services demand as infrastructure development progresses.
Umm Al Quwain
Umm Al Quwain holds a smaller share of the UAE contract cleaning services market, contributing around 1% of the total market. Despite being the smallest emirate in the UAE, Umm Al Quwain is witnessing gradual economic diversification and infrastructure growth. The region’s expanding residential and commercial developments, as well as the government's plans to attract businesses, create potential for cleaning service providers to cater to emerging needs in both public and private sectors. As the region continues to develop, its share of the market is expected to grow in the coming years.
Key Player Analysis
- AISS Group
- Blue Diamond Facilities Management
- Adeeb Group
- Transguard Group
- SPS Facilities Management
- Dussmann Group
- Emirates Facilities Management
- CLEANCO
- Sodexo
- Klüh Service Management GmbH
- Dussmann Group
- Berner Group
- Clean Group
- Atlas Facilities Management Ltd.
- Stratus Building Solutions
- Eco Group Services
Competitive Analysis
The UAE contract cleaning services market is highly competitive, with a mix of local and international players offering a range of services. Leading players include AISS Group, Blue Diamond Facilities Management, Adeeb Group, Transguard Group, SPS Facilities Management, Dussmann Group, Emirates Facilities Management, CLEANCO, Sodexo, Klüh Service Management GmbH, Berner Group, Clean Group, Atlas Facilities Management Ltd., Stratus Building Solutions, and Eco Group Services. Competition is driven by the demand for efficient, reliable, and specialized services, particularly in high-demand sectors such as healthcare, hospitality, and commercial real estate. Companies are differentiating themselves through technological advancements, such as automation, AI-based cleaning solutions, and eco-friendly cleaning products. The shift toward sustainability is a significant trend, with service providers integrating green cleaning methods to appeal to environmentally-conscious customers. The market also faces intense price competition, as players seek to maintain profitability while offering cost-effective solutions. Companies are increasingly focused on service quality and customer satisfaction to gain long-term contracts. Additionally, the demand for specialized cleaning services, such as medical and post-construction cleaning, has become a key area of focus, allowing companies to tap into niche markets. To stay competitive, businesses are investing in employee training, quality control, and the latest cleaning technologies. As the market continues to evolve, firms will need to continuously adapt their strategies, balancing innovation with operational efficiency, to sustain their position in this growing and dynamic sector.
Recent Developments
- In September 2024, OCS UK & I, a subsidiary of OCS Group Holdings Ltd., acquired Exclusive Services Group, a leading provider of contract cleaning services in the UK and Ireland. This acquisition will strengthen OCS's position in key sectors like education, data centers, leisure, media, and retail. Both companies share similar values and a focus on operational excellence, ensuring smooth integration. This move is a significant step towards OCS's goal of becoming a leading facilities service provider, with the company aiming to double its revenue in the UK and Ireland over the next five years.
- In October 2023, Principle Cleaning Services partnered with Skyline Robotics to bring autonomous window-cleaning robots to London. The partnership will help complete the window cleaning up to three times faster than humans, and it will be a more effective alternative to humans.
- In September 2023, United Global, specializing in providing commercial services for cleaning in Western Australia, partnered with Perth Glory. The partnership will help the company in enhancing its business in Australia.
- In July 2023, The ServiceMaster Company, LLC. partnered with Aspire Software to provide commercial cleaning business management system technology for the effective growth of the organization.
- In April 2022, KBS, a portfolio company of Cerberus Capital Management, acquired Kimco, a leading provider of commercial cleaning and facility maintenance services. This acquisition will strengthen KBS's position in the business and industrial sectors, allowing it to offer a wider range of services to its clients. By combining their expertise and technology, KBS and Kimco aim to enhance operational performance and set new industry standards.
Market Concentration & Characteristics
The UAE contract cleaning services market exhibits moderate concentration, with a mix of large international players and smaller regional companies competing for market share. While global service providers offer advanced cleaning solutions and benefit from their extensive experience and resources, local players leverage their deep understanding of the regional market and customer preferences. This combination fosters a competitive environment where companies continuously innovate and improve their service offerings. The market is characterized by a high demand for specialized cleaning services, particularly in sectors such as healthcare, hospitality, and commercial real estate. This includes services like post-construction cleaning, deep cleaning, and maintenance of large facilities. The industry is also witnessing a shift towards sustainable and eco-friendly cleaning solutions, with companies adopting green cleaning technologies and environmentally conscious practices to align with both regulatory requirements and consumer preferences. Another key characteristic of the market is the heavy reliance on labor, with many cleaning companies outsourcing or employing large workforces to meet the increasing demand for cleaning services. This often leads to challenges in labor management, including high turnover rates and the need for ongoing training to ensure quality standards. As the demand for contract cleaning services grows, firms are focusing on improving service efficiency, enhancing customer satisfaction, and incorporating technological advancements to differentiate themselves in a competitive market.
Report Coverage
The research report offers an in-depth analysis based on Service Type, End-use, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The UAE contract cleaning services market is expected to continue growing, driven by increasing urbanization and infrastructure development.
- The demand for eco-friendly and sustainable cleaning solutions will rise as businesses and consumers prioritize green practices.
- Technological advancements, such as AI and automation, will enhance operational efficiency and reduce cleaning costs.
- The growing hospitality and healthcare sectors will create a steady demand for specialized cleaning services.
- The adoption of smart cleaning technologies, such as IoT-based monitoring and robotic cleaners, will increase in commercial spaces.
- There will be a rising trend toward offering customized cleaning solutions to meet the specific needs of different industries.
- Companies will focus on employee training and retention to maintain high service standards in a competitive labor market.
- Digital platforms and mobile apps for booking and managing cleaning services will become more common.
- The government’s support for sustainability and innovation in the cleaning industry will boost market growth.
- Increased awareness of hygiene and cleanliness, especially post-pandemic, will drive demand for cleaning services across all sectors.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the UAE Contract Cleaning Services Market?
What factors are driving the growth of the UAE Contract Cleaning Services Market?
What are the key segments within the UAE Contract Cleaning Services Market?
What are some challenges faced by the UAE Contract Cleaning Services Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UAE Contract Cleaning Services Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UAE Contract Cleaning Services Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 801.19 million → 2032: USD 1,145.90 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UAE Contract Cleaning Services Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UAE Contract Cleaning Services Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UAE Contract Cleaning Services Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UAE Contract Cleaning Services Market Drivers
- 3.3 UAE Contract Cleaning Services Market Restraints & Challenges
- 3.4 UAE Contract Cleaning Services Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UAE Contract Cleaning Services Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UAE Contract Cleaning Services Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UAE Contract Cleaning Services category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UAE Contract Cleaning Services Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UAE Contract Cleaning Services Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UAE Contract Cleaning Services market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UAE Contract Cleaning Services Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UAE Contract Cleaning Services Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UAE Contract Cleaning Services Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UAE Contract Cleaning Services (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UAE Contract Cleaning Services Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UAE Contract Cleaning Services Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UAE Contract Cleaning Services Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UAE Contract Cleaning Services Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UAE Contract Cleaning Services Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UAE Contract Cleaning Services Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UAE Contract Cleaning Services Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UAE Contract Cleaning Services Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UAE Contract Cleaning Services Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
