
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| UAE Digital Signature Market Size 2024 | USD 53.30 million |
| UAE Digital Signature Market, CAGR | 30.28% |
| UAE Digital Signature Market Size 2032 | USD 442.39 million |
Market Overview:
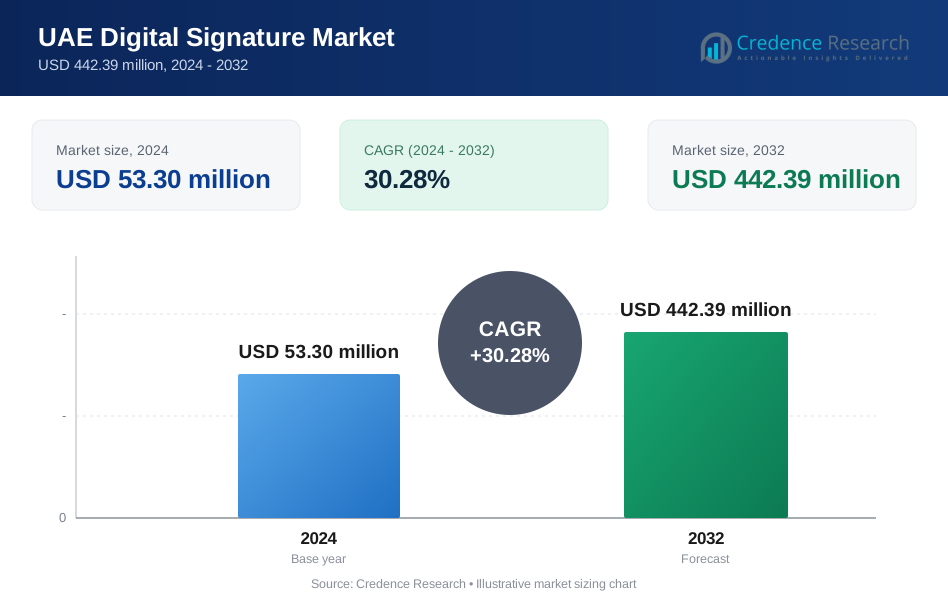
The UAE Digital Signature Market is projected to grow from USD 53.30 million in 2024 to an estimated USD 442.39 million by 2032, with a compound annual growth rate (CAGR) of 30.28% from 2024 to 2032.
Several factors are propelling the growth of the digital signature market in the UAE. Foremost is the government's strong emphasis on digitalization, exemplified by initiatives aimed at enhancing e-governance and promoting paperless transactions. The legal recognition of digital signatures has further facilitated their adoption across various sectors, including finance, healthcare, and government services. Additionally, the increasing need for secure and efficient digital transactions, especially in the wake of remote work trends and the expansion of e-commerce, has heightened the demand for reliable digital signature solutions. The integration of advanced technologies such as AI and blockchain into digital signature platforms is also enhancing their security and functionality, thereby attracting more users. Furthermore, growing awareness of data privacy and compliance regulations is pushing enterprises to adopt verifiable and encrypted communication tools.
Within the Middle East and Africa (MEA) region, the UAE stands out as a leader in the digital signature market. The country's proactive approach to digital infrastructure development and regulatory support has positioned it at the forefront of digital signature adoption in the region. The UAE's market is expected to continue its rapid expansion, outpacing other countries in the region in terms of growth rate. This leadership is further reinforced by the presence of key global players such as DocuSign Inc., Adobe Inc., and OneSpan Inc., which are actively operating in the UAE market, offering advanced digital signature solutions to meet the growing demand. The country's advanced telecommunications ecosystem and high internet penetration provide a solid foundation for widespread adoption. In addition, strategic partnerships between government bodies and private tech firms are accelerating the deployment of secure digital identity and authentication solutions across various sectors.
Market Insights:
- The UAE Digital Signature Market will expand from USD 53.30 million in 2024 to USD 442.39 million by 2032 at a CAGR of 30.28%.
- The Global Digital Signature Market is projected to grow significantly, from USD 7,885.08 million in 2024 to USD 76,046.14 million by 2032, reflecting a strong CAGR of 32.75% during the forecast period.
- The government’s strong emphasis on digitalization through initiatives like the UAE Digital Government Strategy and Smart Dubai drives widespread adoption of paperless transactions.
- Legal recognition under the Electronic Transactions and Commerce Law boosts confidence, enabling finance, healthcare, and logistics sectors to integrate e-signature workflows.
- Remote work trends and e-commerce growth heighten demand for secure, tamper-proof transaction authorizations that streamline approvals and reduce manual errors.
- Vendors leverage AI, blockchain, and biometrics to enhance security, traceability, and user experience, while cloud-based SaaS models simplify deployment and scaling.
- The UAE leads the Middle East and Africa region in digital signature uptake, outpacing peers thanks to its advanced telecom infrastructure and high internet penetration.
- Strategic partnerships between government bodies and private tech firms accelerate deployment of secure digital identity and authentication solutions across sectors.
Report Scope
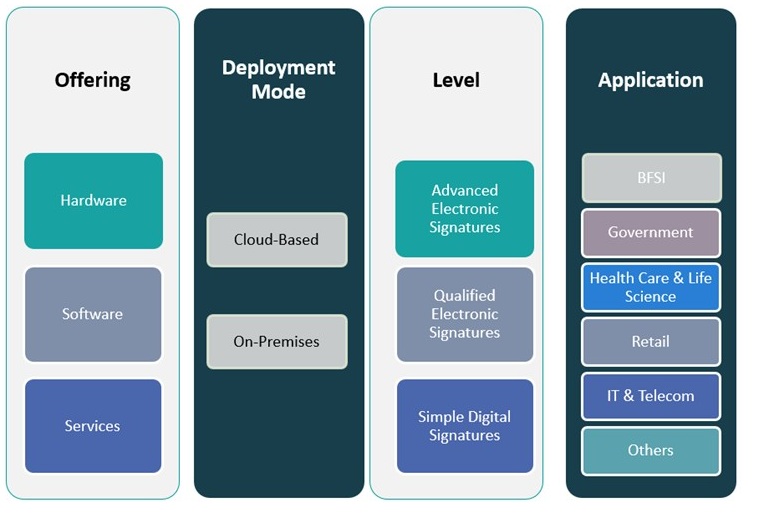
This report segments the UAE Digital Signature Market as follow
Market Drivers:
Government-led Digital Transformation Initiatives
One of the primary drivers of the UAE digital signature market is the government’s unwavering commitment to digital transformation. The UAE has consistently advanced policies and frameworks that encourage the transition from traditional documentation to electronic processes. Initiatives such as the UAE Digital Government Strategy and Smart Dubai have laid the foundation for widespread adoption of digital tools, including digital signatures. For instance, As of December 2021, all Dubai government departments became fully paperless, saving over $350 million in revenues, 336 million sheets of paper, and more than 14 million man-hours. These efforts aim to enhance service delivery, increase transparency, and reduce dependency on paper-based systems. As a result, public and private institutions are increasingly embracing digital signature solutions to align with national goals and regulatory compliance requirements.
Legal Recognition and Regulatory Support
Legal validation of digital signatures has played a critical role in accelerating their adoption across sectors. The UAE’s legal framework, supported by the Electronic Transactions and Commerce Law, provides the necessary recognition and enforceability of digital signatures. This has instilled confidence among businesses and consumers to utilize electronic authentication methods in place of traditional signatures. For instance, Qualified electronic signatures (QES), issued by accredited trust service providers, are considered equivalent to handwritten signatures and are admissible in UAE courts. Regulatory clarity has also encouraged industries such as banking, insurance, healthcare, and logistics to integrate digital signature systems into their operational workflows. The compliance-driven environment in the UAE further ensures that digital signatures meet international standards, bolstering their credibility and fostering market growth.
Rising Demand for Secure and Efficient Transactions
As businesses continue to digitalize their operations, there is a growing need for secure, efficient, and tamper-proof methods of transaction authorization. Digital signatures meet this demand by offering robust encryption, identity verification, and audit capabilities. In sectors such as real estate, legal services, and financial institutions, digital signatures help streamline document approvals, reduce turnaround time, and eliminate manual errors. The accelerated shift to remote work and digital communication particularly after the pandemic has heightened the demand for seamless, location-independent approval mechanisms. Consequently, enterprises across the UAE are adopting digital signature platforms to enhance workflow automation and ensure secure digital interactions.
Integration of Advanced Technologies and Vendor Innovation
The continuous integration of emerging technologies such as artificial intelligence (AI), blockchain, and biometrics is transforming digital signature solutions. These technologies not only enhance the security and traceability of signatures but also enable dynamic and user-friendly platforms. Vendors operating in the UAE are leveraging these innovations to offer customized solutions tailored to the specific needs of different industries. The availability of cloud-based platforms and Software-as-a-Service (SaaS) models has further simplified deployment and scalability for organizations of all sizes. As competition intensifies, innovation in digital signature offerings continues to act as a significant market catalyst, enabling wider adoption and sustained growth.
Market Trends:
Growing Adoption Across Non-Traditional Sectors
While banking, legal, and government services have traditionally led the adoption of digital signatures, new sectors are increasingly embracing this technology in the UAE. The education sector, for instance, has witnessed a sharp rise in the use of digital signatures for student records, certificates, and administrative approvals. For instance, eMudhra reports that electronic signatures now authenticate student records, facilitate remote signing of consent forms for field trips, and enable faculty to execute contracts and grading documents digitally. Similarly, the hospitality and retail sectors are digitizing their customer onboarding and internal documentation processes. This trend is driven by the growing need for operational agility and enhanced customer experience in competitive service environments. As digital literacy spreads and more industries recognize the value of secure and authenticated documentation, the application scope of digital signatures continues to expand.
Mobile-Based Signature Solutions on the Rise
The increasing penetration of smartphones and mobile internet in the UAE is fueling the demand for mobile-based digital signature solutions. Businesses and individuals are seeking more convenient ways to execute documents on-the-go, particularly in industries that involve frequent client interaction or fieldwork. In response, solution providers are developing mobile-friendly platforms that enable remote identity verification, real-time signing, and integration with messaging and cloud storage services. The trend toward mobile-first enterprise solutions reflect the broader shift toward digital convenience and is expected to significantly influence product development in the digital signature space.
Enhanced Integration with Digital Identity Frameworks
Another key trend shaping the UAE digital signature market is the alignment with national digital identity systems. For instance, Wasl Group, a major real estate company, has incorporated UAE PASS digital signatures into its lease contract process, reducing lease processing times by up to 80% and enabling customers to sign contracts remotely with full authentication and security. This integration is streamlining access to secure e-services and boosting user confidence in signing processes. The interoperability between digital signatures and national ID programs is also helping reduce fraud and improve regulatory compliance. This convergence of identification and authentication systems reflects the UAE's strategic investment in building a secure digital infrastructure that fosters trust in electronic transactions.
Sustainability and Cost Efficiency Driving Corporate Adoption
Sustainability goals and cost rationalization efforts are pushing UAE-based businesses to transition from paper-intensive processes to digital alternatives. Organizations are increasingly factoring environmental responsibility into their operational decisions, and digital signatures offer an effective way to minimize paper usage. In addition, companies are realizing tangible savings in terms of printing, courier services, storage, and administrative overhead by digitizing their approval and documentation processes. The dual benefit of reducing environmental impact and lowering operational costs is encouraging widespread adoption of digital signature technologies, especially among SMEs aiming to remain competitive in a technology-driven marketplace.
Market Challenges Analysis:
Fragmented Regulatory Alignment Across Sectors
Despite the presence of a national legal framework that supports digital signatures, inconsistencies in sector-specific regulations pose a notable challenge in the UAE market. For example, while Federal Decree Law No. 46 of 2021 and its executive regulations provide legal recognition for digital signatures across most sectors, certain industries-such as real estate and some commercial contracts-maintain exceptions or require additional verification steps, complicating the adoption of a single unified solution. Different industries follow varying standards for electronic documentation and verification protocols, which complicates the integration of a unified digital signature solution. This fragmentation often results in compliance ambiguities for service providers and delays in implementation for businesses. Additionally, smaller organizations without dedicated legal or IT teams may struggle to interpret or adhere to overlapping regulatory requirements, limiting the scalability of digital signature solutions across the broader economy.
Limited Awareness and Resistance to Change
Another significant restraint is the limited awareness among small and mid-sized enterprises regarding the benefits and legality of digital signatures. Many businesses continue to rely on traditional, paper-based processes due to comfort with legacy systems or concerns over data security. This resistance is often rooted in misconceptions about the validity, security, or complexity of digital signature tools. Furthermore, the lack of sufficient education and training around the use of digital signatures, especially among non-technical staff, can hinder effective adoption. While larger corporations are quick to adopt digital innovations, a notable portion of the UAE's business landscape still exhibits reluctance, which can slow overall market growth.
High Initial Implementation Costs and Integration Complexity
The cost and complexity of integrating digital signature systems with existing enterprise workflows can also act as a barrier. Although cloud-based solutions have made adoption more accessible, enterprises with legacy systems or diverse operational platforms often face challenges in seamless integration. Customization, compliance testing, and staff training contribute to upfront implementation costs, making the transition less appealing for resource-constrained organizations. As a result, these financial and technical hurdles continue to act as deterrents, especially for sectors with minimal exposure to digital transformation.
Market Opportunities:
The UAE digital signature market presents significant growth opportunities driven by the country's rapid digital transformation and increasing focus on cybersecurity. As businesses and government agencies continue to transition toward paperless operations, the demand for secure, efficient, and legally compliant digital authentication methods is rising. The UAE's Vision 2031 initiative, which emphasizes technological innovation and smart governance, creates a favorable environment for digital signature providers to expand their footprint. Additionally, the growth of sectors such as fintech, e-commerce, and digital healthcare presents new avenues for the application of digital signature technologies, particularly in customer onboarding, transaction authentication, and secure document management.
An emerging opportunity lies in the integration of digital signatures with blockchain-based identity solutions and artificial intelligence tools, enhancing both verification accuracy and user experience. As regulatory bodies increasingly require robust digital identity and compliance protocols, vendors offering interoperable and scalable solutions are well-positioned to capture market share. Furthermore, the rising number of SMEs seeking cost-effective and mobile-friendly platforms offers a niche for cloud-based and subscription-based digital signature services. Strategic collaborations between local firms and global technology providers could also accelerate innovation and adoption, opening up new business models and sector-specific customizations. As digital trust and operational efficiency become core to business success in the UAE, digital signature solutions stand to play a central role in enabling secure digital ecosystems.
Market Segmentation Analysis:
The UAE digital signature market is segmented
By offering into hardware, software, and services. Among these, the software segment holds a dominant position, driven by growing demand for scalable, user-friendly platforms that support seamless document authentication across devices. The services segment is also expanding steadily as organizations increasingly rely on managed services and consulting to implement secure signature solutions. Hardware, though essential for physical security and biometric integration, represents a smaller portion of the market.
By deployment mode, cloud-based solutions are witnessing significant traction in the UAE, owing to their flexibility, cost-effectiveness, and ease of integration with existing enterprise systems. On-premises deployment remains relevant in highly regulated sectors, such as government and BFSI, where data control and internal infrastructure management are prioritized.
By level, advanced electronic signatures dominate due to their strong legal standing and widespread use in enterprise workflows. Qualified electronic signatures are gaining momentum as organizations seek higher levels of assurance and regulatory compliance. Simple digital signatures, while widely used for internal communications and low-risk approvals, are limited in legal enforceability.
By application, the BFSI sector leads the market, utilizing digital signatures for secure transactions, regulatory compliance, and digital customer onboarding. The government segment follows closely, supported by national digitization efforts. Healthcare & life sciences are increasingly adopting digital signatures for patient records and electronic prescriptions. Retail, IT & telecom, and other sectors are also showing growing adoption as digital transformation initiatives continue to influence operational practices across industries.
Segmentation:
By Offering Segment:
- Hardware
- Software
- Services
By Deployment Mode Segment:
- Cloud-Based
- On-Premises
By Level Segment:
- Advanced Electronic Signatures
- Qualified Electronic Signatures
- Simple Digital Signatures
By Application Segment:
- BFSI (Banking, Financial Services, and Insurance)
- Government
- Healthcare & Life Sciences
- Retail
- IT & Telecom
- Others
Regional Analysis:
In the UAE digital signature market, the Dubai region holds the leading position with a market share of 51%, driven by its advanced digital infrastructure, high concentration of financial institutions, and strong government-led digitization initiatives. Dubai’s Smart Government initiative has played a pivotal role in driving the adoption of digital signature technologies across both public and private sectors. The city’s thriving fintech ecosystem and robust legal frameworks surrounding e-signatures have fostered a secure and compliant environment, encouraging widespread enterprise-level adoption. Additionally, Dubai's high internet penetration and digitally literate workforce continue to fuel demand for secure, efficient digital transaction systems.
The Abu Dhabi region accounts for 32% of the UAE’s digital signature market, supported by substantial investment in digital transformation across governmental and defense sectors. Abu Dhabi’s Vision 2030 agenda has prioritized the integration of advanced digital technologies into governance, public services, and healthcare systems. The presence of large state-owned enterprises and multinational corporations has also boosted demand for secure and authenticated digital document handling solutions. Furthermore, increasing adoption across sectors such as oil & gas, utilities, and education is strengthening Abu Dhabi’s role in shaping the national digital signature landscape.
The Northern Emirates collectively represent 17% of the market, with Sharjah, Ras Al Khaimah, and Ajman showing gradual but steady uptake. These regions are increasingly aligning with the UAE’s federal digital transformation strategy, resulting in greater implementation of e-signature platforms across SMEs and local government entities. While the infrastructure in these emirates is still evolving compared to Dubai and Abu Dhabi, rising awareness about cybersecurity, data authenticity, and compliance is creating a favorable environment for market expansion. Government incentives and digital literacy campaigns are expected to further accelerate adoption in the coming years.
Key Player Analysis:
- Digital Trust
- Etisalat Group
- DarkMatter
- Smartworld
- Emirates ID Authority
Competitive Analysis:
The UAE digital signature market features a dynamic competitive landscape characterized by the presence of both international technology giants and emerging regional providers. Leading global players such as DocuSign Inc., Adobe Inc., and OneSpan Inc. maintain a strong foothold by offering robust, scalable, and compliant solutions tailored to diverse industry needs. These companies continuously invest in innovation, integrating advanced technologies like AI and blockchain to enhance platform security and user experience. Simultaneously, regional firms are gaining traction by delivering localized solutions aligned with UAE regulations and customer expectations. Strategic partnerships between vendors and government agencies further strengthen market penetration, particularly in sectors like banking, healthcare, and public services. With digital transformation accelerating across industries, competition is intensifying, prompting providers to prioritize user-centric features, data sovereignty, and seamless integration capabilities. This evolving environment encourages continuous innovation and service excellence, shaping the future trajectory of the UAE digital signature market.
Recent Developments:
- In May 2024, DocuSign agreed to acquire Lexion, an AI-powered agreement management software company, for $165 million. This acquisition is set to enhance DocuSign’s Intelligent Agreement Management (IAM) platform with advanced AI capabilities, streamlining contract workflows and centralizing agreement processes for enterprise customers. Lexion’s team will join DocuSign, further strengthening its AI and engineering expertise.
- In March 2025, Adobe launched the Adobe Experience Platform Agent Orchestrator, a tool that enables businesses to build and manage AI agents for customer experiences and marketing workflows. This launch is supported by strategic partnerships with major technology companies, including Microsoft, SAP, and ServiceNow, ensuring seamless integration and execution across various AI-driven use cases.
Market Concentration & Characteristics:
The UAE digital signature market demonstrates moderate to high market concentration, with a few global players dominating the landscape while regional firms continue to emerge with niche offerings. Multinational corporations like Adobe Inc. and DocuSign Inc. hold significant market share, leveraging their global expertise, established credibility, and advanced platforms to serve enterprise clients across sectors. However, the market also supports a growing number of local and regional solution providers that cater to industry-specific needs and regulatory frameworks. Key market characteristics include a strong emphasis on compliance, cybersecurity, and cloud-based deployment, driven by the UAE’s robust digital governance ecosystem. The market is also defined by high customer expectations for secure, seamless, and mobile-enabled solutions. As digital transformation progresses, the UAE market continues to shift towards integrated platforms that combine electronic signatures with digital identity, workflow automation, and document management capabilities—creating opportunities for differentiated offerings and strategic innovation.
Report Coverage:
The research report offers an in-depth analysis based on Offering, Deployment Mode, Level and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing integration of digital signatures with national digital identity programs will enhance authentication reliability.
- Expansion of cloud-based solutions will support scalability for SMEs and enterprise users.
- Rising demand for mobile-first platforms will drive innovation in app-based signature tools.
- Advancements in blockchain and AI technologies will strengthen document security and fraud prevention.
- Legal updates and cross-sector regulatory harmonization will streamline adoption across industries.
- Strategic partnerships between global vendors and local firms will boost solution localization.
- Growing use in sectors like education, logistics, and e-commerce will diversify application scope.
- Continued government investment in smart infrastructure will create a favorable growth environment.
- Increased focus on sustainability will encourage businesses to shift from paper-based workflows.
- Competitive pressure will lead to more affordable, feature-rich offerings tailored to regional needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the UAE Digital Signature Market?
What factors are driving the growth of the UAE Digital Signature Market?
are some challenges faced by the UAE Digital Signature Market?
Who are the major players in the UAE Digital Signature Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UAE Digital Signature Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UAE Digital Signature Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 53.30 million → 2032: USD 442.39 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UAE Digital Signature Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UAE Digital Signature Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UAE Digital Signature Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UAE Digital Signature Market Drivers
- 3.3 UAE Digital Signature Market Restraints & Challenges
- 3.4 UAE Digital Signature Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UAE Digital Signature Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UAE Digital Signature Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UAE Digital Signature category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UAE Digital Signature Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UAE Digital Signature Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UAE Digital Signature market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UAE Digital Signature Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UAE Digital Signature Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UAE Digital Signature Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UAE Digital Signature (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UAE Digital Signature Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UAE Digital Signature Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UAE Digital Signature Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UAE Digital Signature Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UAE Digital Signature Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UAE Digital Signature Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UAE Digital Signature Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UAE Digital Signature Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UAE Digital Signature Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
