
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| UAE Feminine Hygiene Products market Size 2023 | USD 52.59 million |
| UAE Feminine Hygiene Products market, CAGR | 4.76% |
| UAE Feminine Hygiene Products market Size 2032 | USD 80.12 million |
Market Overview:
UAE Feminine Hygiene Products size was valued at USD 52.59 million in 2023 and is anticipated to reach USD 80.12 million by 2032, at a CAGR of 4.76% during the forecast period (2023-2032).
The growth of the UAE feminine hygiene products market is primarily driven by increased awareness and education surrounding menstrual health. Government campaigns and educational initiatives have played a significant role in breaking taboos and promoting open discussions about menstrual hygiene. As a result, more women are adopting feminine hygiene products. Additionally, there is a growing preference for organic and eco-friendly feminine hygiene products, as consumers become more health-conscious and environmentally aware. This shift reflects a broader trend toward natural, sustainable product in the market. Furthermore, the rise of e-commerce has transformed how consumers access feminine hygiene products. With the convenience and privacy offered by online shopping platforms, more consumers are turning to e-commerce, making these products more accessible and further driving market growth.
The UAE is a key player in the broader Middle East and Africa feminine hygiene products market. The region is witnessing increasing government focus on improving feminine healthcare and raising awareness about menstrual health. Initiatives like educational campaigns and materials such as the "Girl Talk" comic booklet have been effective in reducing the stigma associated with menstruation and increasing product adoption. Additionally, with rising quality of life and evolving consumer preferences, the UAE market benefits from these regional shifts. The increasing availability and accessibility of feminine hygiene products, combined with changing attitudes toward menstruation, position the UAE as a significant market within the region.
Market Insights:
- The UAE feminine hygiene products market, valued at USD 52.59 million in 2023, is projected to reach USD 80.12 million by 2032, growing at a CAGR of 4.76%.
- The global feminine hygiene products market, valued at USD 23,490.00 million in 2023, is projected to reach USD 43,917.35 million by 2032, growing at a CAGR of 7.2% from 2023 to 2032.
- Increased awareness and education surrounding menstrual health, driven by government initiatives and campaigns, are key factors contributing to market growth.
- The rising preference for organic and eco-friendly products is reshaping the market, as consumers shift towards natural and biodegradable options.
- E-commerce expansion is making feminine hygiene products more accessible, with online platforms offering convenience and privacy, further fueling market growth.
- Government support, through policies such as free menstrual product distribution and healthcare initiatives, plays a crucial role in improving product accessibility.
- Cultural sensitivities and taboos surrounding menstruation continue to hinder the widespread adoption of feminine hygiene products in certain segments of the population.
- High product costs, particularly for premium and eco-friendly options, limit market growth in price-sensitive consumer segments, particularly in rural areas.
Report scope
This report segments the UAE Feminine Hygiene Products Market as follow: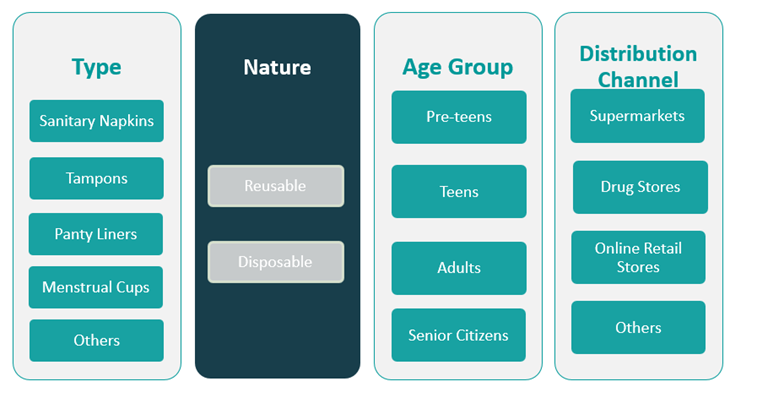
Market Drivers:
Increased Awareness and Education
One of the primary drivers of the UAE feminine hygiene products market is the increased awareness and education regarding menstrual health. Government campaigns and educational initiatives have played a crucial role in breaking taboos and promoting open conversations about menstrual hygiene. These efforts have successfully encouraged women to prioritize their health and well-being by using hygiene products that ensure comfort and cleanliness during menstruation. Over the years, educational programs and social media influencers have contributed significantly to raising awareness, ultimately leading to a higher adoption of feminine hygiene products across various age groups.
Shift Toward Organic and Eco-friendly Products
As consumers become more health-conscious, there is a growing demand for organic and eco-friendly feminine hygiene products. Many women are increasingly opting for products made from natural materials, such as organic cotton, as these alternatives are perceived as safer and more sustainable. For instance, companies are responding with eco-friendly products and packaging; for instance, DivaMe Period Panties are made from organic, biodegradable fabrics and are designed for long-term use, replacing hundreds of disposable products over their lifespan. The growing awareness of environmental issues has also contributed to the shift toward biodegradable and eco-friendly options, which appeal to environmentally conscious consumers. This shift is aligned with broader trends of sustainability and natural living, and manufacturers are responding by introducing a range of organic and eco-friendly feminine hygiene products to meet this demand, further driving market growth.
Expansion of E-commerce and Convenience
The rapid expansion of e-commerce has revolutionized the way consumers purchase feminine hygiene products in the UAE. Online shopping platforms provide a convenient and discreet way for women to access a variety of products from the comfort of their homes. This has been particularly significant for those who may feel uncomfortable purchasing these products in physical stores due to cultural sensitivities. The convenience of online shopping, combined with the ability to compare products, read reviews, and enjoy home delivery, has led to an increase in the number of women purchasing feminine hygiene products online. E-commerce platforms have made these products more accessible, leading to a larger customer base and further accelerating market growth.
Government Support and Initiatives
Government support plays a pivotal role in driving the growth of the feminine hygiene products market in the UAE. The government has implemented policies and initiatives that focus on improving the overall health and well-being of women, with a particular focus on menstrual health. Awareness campaigns, the provision of free menstrual products in schools and universities, and government-endorsed healthcare initiatives have contributed to a cultural shift in how menstruation is perceived and managed. For instance, the Dubai Foundation for Women and Children (DFWAC) distributed free sanitary napkins, donated by Orgabliss, to women and girls seeking shelter, highlighting efforts to ensure access to essential hygiene products for disadvantaged groups. Additionally, the availability of menstrual products in pharmacies, supermarkets, and convenience stores across the country has made them easily accessible to women of all socio-economic backgrounds. These government efforts have helped normalize the use of feminine hygiene products, leading to an increase in product consumption and overall market growth.
Market Trends:
Rising Preference for Premium Products
The UAE feminine hygiene products market is witnessing a shift towards premium products that offer superior quality and advanced features. Women in the UAE are increasingly opting for products that offer additional benefits such as improved comfort, better absorbency, and enhanced protection. Premium brands are also introducing innovative solutions such as odor control, skin-friendly materials, and long-lasting protection, catering to a more discerning consumer base. For instance, PECTIV’s pads, which are free from harmful chemicals like phthalates and plastics, have resonated with UAE consumers, as evidenced by the sale of over 100,000 packs in under two years and an 80% repeat customer rate. As disposable income in the region increases, consumers are willing to invest in high-quality products that prioritize health and comfort, driving the demand for premium feminine hygiene products. This trend reflects a growing awareness of personal well-being and hygiene, particularly in urban centers where women are more likely to prioritize product quality.
Technological Advancements in Product Development
Technological advancements are playing an increasingly significant role in the development of feminine hygiene products in the UAE. Brands are leveraging new technologies to create products that are not only more effective but also more comfortable and sustainable. For instance, the use of advanced fabrics such as breathable, moisture-wicking materials enhances the user experience by providing a more comfortable fit and reducing the risk of irritation. Additionally, manufacturers are focusing on improving the design of sanitary pads, tampons, and menstrual cups to make them more discreet and efficient. The ongoing innovation in product development is reshaping the market and catering to the evolving preferences of consumers in the UAE.
Shift Toward Sustainability
Sustainability has become a significant trend in the UAE feminine hygiene products market. As environmental concerns grow, an increasing number of consumers are choosing sustainable alternatives such as biodegradable sanitary pads and organic cotton tampons. Brands are responding by focusing on reducing the environmental impact of their products, with many introducing eco-friendly packaging and materials. For instance, Saathi’s biodegradable pads, made from banana and bamboo fibers, degrade within six months 1,200 times faster than conventional plastic pads and are produced without chemicals, ensuring a rash- and irritation-free experience. This trend is supported by a broader shift toward sustainable living in the region, with consumers becoming more aware of the long-term environmental effects of their choices. The demand for environmentally friendly products is expected to continue rising, as the UAE government and companies place greater emphasis on sustainability across industries.
Influence of Social Media and Digital Platforms
Social media and digital platforms are significantly influencing the UAE feminine hygiene products market. Platforms like Instagram, YouTube, and TikTok have become key channels for brands to engage with their target audiences, especially younger generations. Social media influencers and content creators are playing a pivotal role in shaping consumer preferences, promoting various brands and products, and educating their followers about menstrual health and hygiene. Additionally, digital platforms allow brands to reach a wider audience through targeted advertising and e-commerce solutions. The rise of social media is not only driving brand visibility but also helping to normalize discussions around menstruation and feminine hygiene, further contributing to the market’s growth.
Market Challenges Analysis:
Cultural Sensitivities and Taboos
Despite growing awareness, cultural sensitivities and taboos surrounding menstruation continue to pose significant challenges in the UAE feminine hygiene products market. In certain segments of the population, there remains reluctance to openly discuss menstrual health, which can result in hesitation to purchase and use feminine hygiene products. Traditional views on menstruation may influence women’s purchasing decisions, particularly in more conservative areas where privacy is highly valued. These cultural barriers can limit the overall adoption of feminine hygiene products, hindering market growth in specific demographics.
High Product Costs
The relatively high cost of premium feminine hygiene products can be a barrier for a significant portion of the population in the UAE. While disposable income has increased, the price of organic and eco-friendly products, as well as premium brands, can be prohibitive for some consumers. The expense associated with these products may discourage price-sensitive consumers from switching to higher-end options, particularly in a market that is already accustomed to using more affordable alternatives. This pricing challenge may slow the overall market expansion, particularly in price-sensitive segments.
Limited Availability in Rural Areas
Although feminine hygiene products are widely available in urban centers, there remains limited access in rural and less developed regions of the UAE. Distribution channels in these areas are not as robust, leading to lower availability of certain products. Women in rural or less affluent areas may face challenges in accessing the full range of feminine hygiene options, which can limit market penetration in these regions. Bridging this gap in distribution would require significant investment in logistics and retail infrastructure.
Environmental Concerns and Product Disposal
As consumers become more aware of the environmental impact of disposable feminine hygiene products, concerns about disposal have emerged as a challenge. Traditional pads and tampons often contain non-biodegradable plastics, contributing significantly to landfill waste. For instance, Diva’Me Period Panties in the UAE are marketed as a sustainable alternative, using low-impact dyes and reducing water consumption in production. The company highlights that traditional products can take up to 500 years to decompose, underscoring the urgency for eco-friendly solutions and the growing consumer shift toward reusable or biodegradable menstrual product.
Market Opportunities:
The UAE feminine hygiene products market presents several opportunities, particularly in the growing demand for organic and eco-friendly alternatives. As consumer awareness of environmental issues increases, there is a significant shift towards products made from sustainable materials, such as organic cotton and biodegradable sanitary pads. This presents an opportunity for brands to expand their product lines to include more sustainable options, catering to the environmentally conscious segment of the population. With increasing consumer preference for natural and eco-friendly products, companies can capitalize on this trend by offering high-quality, biodegradable feminine hygiene products that align with both health and environmental concerns. The growing focus on sustainability also aligns with the UAE's broader environmental goals, providing a potential market for brands that focus on eco-friendly packaging and manufacturing processes.
Another promising opportunity lies in the expansion of e-commerce, which has become an increasingly vital channel for feminine hygiene product sales in the UAE. With the convenience and privacy that online shopping offers, especially for personal products, there is a growing demand for e-commerce platforms to cater to this segment. This trend is particularly relevant in a market where traditional retail stores may not always provide the desired level of accessibility or comfort for consumers. E-commerce platforms also enable brands to reach a wider audience, including those in remote or underserved areas, further expanding market reach. By investing in online sales channels and digital marketing strategies, companies can tap into a growing consumer base and position themselves as leaders in the UAE feminine hygiene products market.
Market Segmentation Analysis:
The UAE feminine hygiene products market is characterized by diverse segments that cater to the specific needs of different consumer groups.
By Type:
Sanitary napkins dominate the market, driven by their widespread use and availability in various sizes and absorbency options. Tampons and panty liners follow as key products, offering more discrete and comfortable alternatives. Menstrual cups, though growing in popularity due to their eco-friendliness and cost-effectiveness, still represent a smaller market share. Other products, including intimate hygiene washes and wipes, complement the core offerings.
By Nature:
The market is divided into reusable and disposable products. Disposable items, particularly sanitary napkins and tampons, continue to lead the market due to convenience and ease of use. However, there is a noticeable shift towards reusable products, such as menstrual cups, driven by growing environmental awareness and consumer demand for sustainable options.
By Age-Group:
The market serves various age groups, from pre-teens to senior citizens. Sanitary products for pre-teens and teens are typically designed for comfort and light absorbency. Adults form the largest consumer base, requiring a wide range of products tailored to different needs, while senior citizens are increasingly opting for products that offer extra protection and comfort.
By Distribution Channel:
Supermarkets and drug stores remain the primary distribution channels for feminine hygiene products in the UAE. However, online retail stores are rapidly gaining popularity, providing consumers with convenience and privacy. Other distribution channels, including convenience stores and pharmacies, contribute to the overall market growth by offering easy access to products.
Segmentation:
By Type
- Sanitary Napkins
- Tampons
- Panty Liners
- Menstrual Cups
- Others
By Nature
- Reusable
- Disposable
By Age-Group
- Pre-teens
- Teens
- Adults
- Senior Citizens
By Distribution Channel
- Supermarkets
- Drug Stores
- Online Retail Stores
- Others
Regional Analysis:
The UAE stands as a significant player in the broader Middle East and North Africa (MENA) feminine hygiene products market, which continues to grow steadily due to shifting consumer behaviors, increasing awareness, and improving product availability. The market in the UAE is particularly strong due to the country’s advanced infrastructure, high disposable income, and strong government support for women's health initiatives. In addition, UAE’s increasing population of women in the reproductive age group contributes to the growth of the feminine hygiene market, as the demand for menstrual products such as sanitary pads, tampons, and menstrual cups rises.
The UAE’s market share within the MENA region for feminine hygiene products is substantial, driven by its status as a leading economic hub. In 2022, the UAE accounted for approximately 20% of the total feminine hygiene products market share in the MENA region. This is largely attributed to its growing urban population, with Dubai and Abu Dhabi being central markets. The urbanization trend in the UAE results in increased awareness of menstrual health and hygiene, as well as greater access to a wide variety of products in supermarkets, pharmacies, and e-commerce platforms. Additionally, the UAE’s well-established retail and e-commerce sectors have enabled widespread distribution of feminine hygiene products, further boosting the market.
The broader MENA region also displays significant growth potential, with countries like Saudi Arabia, Egypt, and Qatar contributing to the increasing demand for feminine hygiene products. However, the UAE remains the leader in the region due to its progressive approach toward women’s health and its higher purchasing power compared to neighboring countries. Saudi Arabia follows closely behind the UAE in market share, with around 18%, due to its large population and growing acceptance of modern hygiene products. In contrast, other countries in the region, such as Egypt and Algeria, account for smaller portions of the market, mainly due to varying levels of awareness, cultural sensitivities, and limited availability of products in certain areas.
The UAE’s position as a regional leader in the feminine hygiene market is expected to strengthen in the coming years, driven by continuing social and cultural shifts, as well as government and private sector initiatives promoting menstrual health and sustainability. The country’s commitment to improving healthcare access for women, alongside its growing focus on sustainable and eco-friendly products, will further solidify its dominance in the MENA feminine hygiene products market.
Key Player Analysis:
- Johnson & Johnson
- Procter & Gamble
- Kimberly-Clark
- Essity Aktiebolag
- Kao Corporation
- Daio Paper Corporation
- Unicharm Corporation
- Premier FMCG
- Ontex
- Hengan International Group Company Ltd
- Drylock Technologies
- Natracare LLC
- First Quality Enterprises, Inc
- Ontex Group NV
Competitive Analysis:
The UAE feminine hygiene products market is characterized by a competitive landscape featuring both multinational corporations and regional players. Leading global companies such as Procter & Gamble, Kimberly-Clark, and Unilever have established a strong presence in the UAE, offering well-known brands like Always, Kotex, and Carefree. These companies leverage their extensive distribution networks and brand recognition to maintain a significant market share. Additionally, regional companies are emerging, focusing on catering to local preferences and introducing innovative, eco-friendly products to meet the growing demand for sustainable options. The market is witnessing a shift towards premium and organic products, driven by increasing consumer awareness of health and environmental concerns. This trend presents opportunities for brands to differentiate themselves through product innovation and sustainability initiatives. E-commerce platforms are also playing an increasingly important role, providing consumers with convenient access to a wide range of products. Companies that effectively utilize digital channels for marketing and distribution are gaining a competitive edge in reaching a broader audience. Overall, the competitive dynamics in the UAE feminine hygiene products market are evolving, with both established and emerging players adapting to changing consumer preferences and market trends.
Recent Developments:
- In September 2024, Adaye, a UAE-based FemTech startup, launched a new range of certified organic, endocrine-safe, and sustainable menstrual care products across the GCC region. This product line includes organic pads, tampons, and pantyliners, all formulated without harmful chemicals such as dioxins and lead, and packaged in recyclable, plastic-free materials. The launch aims to address the region’s growing need for safer, toxin-free menstrual products, particularly given the high prevalence of conditions like PCOS and uterine fibroids among women in the Gulf.
- In July 2022, PECTIV, a Dubai-based FemTech company, continued to make headlines with its nanotechnology-based feminine hygiene products, including sanitary pads, liners, and wipes. These products are designed to prevent bacterial growth, rashes, and irritation, addressing common issues associated with conventional sanitary pads. PECTIV’s direct-to-doorstep subscription model has gained significant traction, with over 100,000 packs sold and a 200% year-over-year growth rate reported in the first half of 2022.
Market Concentration & Characteristics:
The UAE feminine hygiene products market exhibits moderate concentration, with a blend of global and regional players. Leading multinational companies such as Procter & Gamble, Kimberly-Clark, and Unilever dominate the market, leveraging their established brand presence and extensive distribution networks. These companies offer a wide range of products, including sanitary pads, tampons, panty liners, and intimate washes, catering to diverse consumer preferences. Their strong market presence is further bolstered by significant investments in marketing and product innovation. In addition to global brands, regional players are gaining traction by focusing on local consumer needs and preferences. These companies often emphasize affordability and cultural sensitivity in their product offerings. The market is characterized by a growing demand for organic and eco-friendly products, driven by increasing consumer awareness of health and environmental issues. This trend has led to the introduction of sustainable product lines by both multinational and regional companies. E-commerce platforms are playing an increasingly significant role in the distribution of feminine hygiene products, providing consumers with convenient access to a wide range of products and facilitating market growth. Overall, the UAE market is evolving with a mix of established global brands and emerging regional players, responding to changing consumer preferences and trends.
Report Coverage:
The research report offers an in-depth analysis based on Type, Nature, Age-Group and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The UAE feminine hygiene products market will continue to expand due to increasing consumer awareness and education around menstrual health.
- Demand for organic and eco-friendly products will rise, driven by growing environmental and health consciousness.
- The shift towards premium products will intensify, as consumers seek higher quality and additional benefits such as better comfort and absorbency.
- E-commerce will play a larger role, enabling brands to reach broader audiences through convenient online shopping platforms.
- Government initiatives to improve women’s health will support increased consumption and awareness of feminine hygiene products.
- Technological advancements in product development will lead to innovations like breathable materials and improved product design.
- Local brands focusing on culturally relevant products will gain market share alongside global players.
- Sustainable packaging solutions will become a key competitive differentiator as consumer demand for eco-conscious options grows.
- The market will see increased competition as new entrants focus on both affordability and premium options.
- Enhanced distribution networks across both urban and rural areas will improve product availability, driving broader market penetration.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increased Awareness and Education
Government campaigns and educational initiatives in the UAE have broken taboos around menstruation, leading to greater adoption of feminine hygiene products across all age groups.
Shift Toward Organic and Eco-friendly Products
Growing health and environmental consciousness among UAE consumers is driving demand for organic, biodegradable, and sustainable feminine hygiene products, prompting brands to expand their eco-friendly offerings.
Expansion of E-commerce and Convenience
The rise of online retail platforms in the UAE has made feminine hygiene products more accessible and discreet to purchase, especially for consumers in conservative or remote areas, fueling market growth.
Government Support and Initiatives
Policies such as free menstrual product distribution in schools and healthcare initiatives have improved accessibility and normalized product usage, increasing overall market penetration.
Rising Preference for Premium Products
With increasing disposable income and a focus on personal well-being, UAE consumers are opting for premium feminine hygiene products that offer enhanced comfort, absorbency, and innovative features.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the UAE Feminine Hygiene Products Market?
What factors are driving the growth of the UAE Feminine Hygiene Products market?
What are the key segments within the UAE Feminine Hygiene Products market?
Who are the major players in the UAE Feminine Hygiene Products Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Sanitary Napkins
- 1.2.2 Tampons
- 1.2.3 Panty Liners
- 1.2.4 Menstrual Cups
- 1.2.5 Others
- 1.3 By Nature
- 1.3.1 Reusable
- 1.3.2 Disposable
- 1.4 By Age-Group
- 1.4.1 Pre-teens
- 1.4.2 Teens
- 1.4.3 Adults
- 1.4.4 Senior Citizens
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 52.59 million → 2032: USD 80.12 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 UAE Feminine Hygiene Products Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 UAE Feminine Hygiene Products Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 UAE Feminine Hygiene Products Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 UAE Feminine Hygiene Products Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 UAE Feminine Hygiene Products Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 UAE Feminine Hygiene Products Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 UAE Feminine Hygiene Products Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 UAE Feminine Hygiene Products Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 52.59 million → 2032: USD 80.12 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 UAE Feminine Hygiene Products Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Sanitary Napkins
- 12.3.7.2 Tampons
- 12.3.7.3 Panty Liners
- 12.3.7.4 Menstrual Cups
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Nature - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Reusable
- 12.4.7.2 Disposable
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Age-Group - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pre-teens
- 12.5.7.2 Teens
- 12.5.7.3 Adults
- 12.5.7.4 Senior Citizens
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 UAE Feminine Hygiene Products Geographic Market Outlook, 2023-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 UAE Feminine Hygiene Products Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 UAE Feminine Hygiene Products Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Procter & Gamble
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Kimberly-Clark
- 17.4 Johnson & Johnson
- 17.5 Essity Aktiebolag
- 17.6 Unicharm Corporation
- 17.7 Kao Corporation
- 17.8 Daio Paper Corporation
- 17.9 Ontex Group NV
- 17.10 Natracare LLC
- 17.11 Premier FMCG
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

