
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
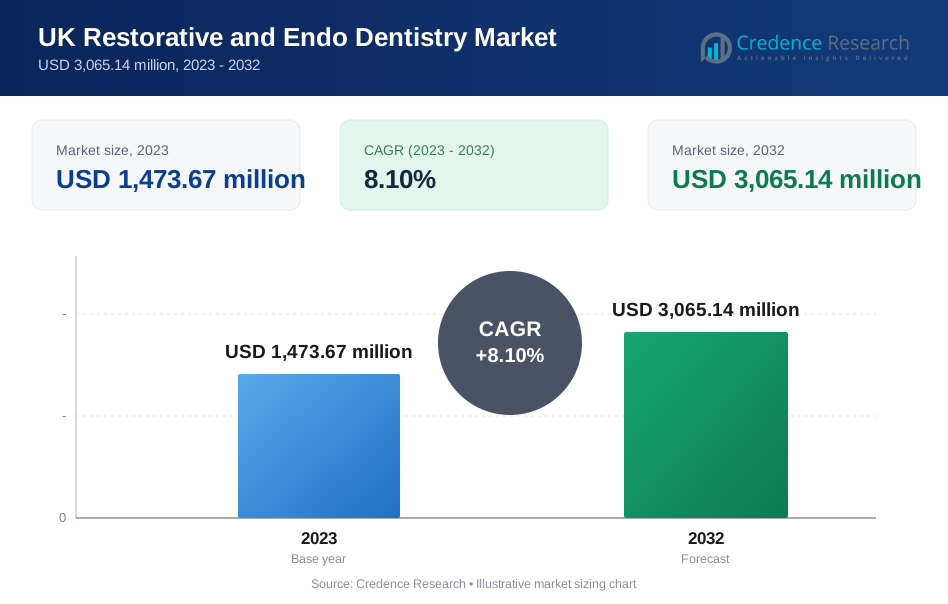
| UK Restorative and Endo Dentistry Market Size 2024 | USD 1,473.67 million |
| UK Restorative and Endo Dentistry Market, CAGR | 8.10% |
| UK Restorative and Endo Dentistry Market Size 2032 | USD 3,065.14 million |
Market Overview
The UK Restorative and Endo Dentistry market is projected to grow from USD 1,473.67 million in 2023 to an estimated USD 3,065.14 million by 2032, reflecting a compound annual growth rate (CAGR) of 8.10% from 2024 to 2032. This substantial growth is driven by rising demand for advanced dental care solutions, increased awareness of oral health, and the aging population in the region.
Key drivers propelling this market include the rising prevalence of dental conditions such as cavities, periodontal diseases, and tooth loss. Innovations in restorative materials, such as biocompatible and durable solutions, and technological advancements in endodontic treatments, including digital imaging and minimally invasive procedures, are enhancing treatment efficacy and patient outcomes. Additionally, growing consumer preference for aesthetic dentistry and an increasing focus on preventive care further fuel market demand.
Geographically, the market exhibits significant activity in urban centers like London, Birmingham, and Manchester, driven by the concentration of dental clinics and specialized healthcare providers. The National Health Service (NHS) initiatives and private sector collaborations are also fostering accessibility to dental care. Key players in the UK Restorative and Endo Dentistry market include Dentsply Sirona, 3M, Straumann, Zimmer Biomet, and Henry Schein. These companies are actively investing in research and development to introduce innovative products and maintain a competitive edge in the growing market.
Market Drivers
Rising Prevalence of Dental Disorders
The increasing prevalence of dental disorders such as cavities, periodontal diseases, and tooth loss is a major driver of the UK Restorative and Endo Dentistry market. Factors such as poor oral hygiene, high sugar consumption, and lifestyle habits like smoking contribute to the rising number of dental issues. According to the Oral Health Foundation, nearly one-third of adults in the UK have untreated tooth decay, while gum disease remains a leading cause of tooth loss among older populations. This growing patient pool has heightened the demand for restorative and endodontic treatments, including fillings, crowns, implants, and root canal therapies. As awareness about the importance of oral health improves, more individuals are seeking timely dental care, which boosts market growth. Recent data from a UK government survey reveals that 23.7% of 5-year-old children in England had experience of dentinal decay, with each affected child having an average of 3.5 teeth with decay experience. Furthermore, GlobalData epidemiologists forecast a sharp rise in dental disease cases if access to dental services is not improved swiftly, potentially causing economic hardship and increasing health burdens.
Advancements in Dental Technology and Materials
Technological innovations in restorative and endodontic dentistry are significantly enhancing treatment outcomes, reducing patient discomfort, and increasing procedural efficiency. Digital tools such as 3D imaging, intraoral scanners, and CAD/CAM systems are revolutionizing the way dental procedures are planned and executed. These technologies enable precise diagnosis, treatment planning, and the creation of custom restorative solutions like crowns, bridges, and dentures. Additionally, advancements in dental materials, including biocompatible ceramics, resin composites, and antibacterial coatings, have improved the durability and aesthetics of restorative products. These innovations attract both dental practitioners and patients, driving the adoption of modern restorative and endodontic procedures across the UK. For instance, the integration of artificial intelligence (AI) is automating complex diagnostic processes, enabling faster and more accurate analyses of dental imaging, while virtual reality (VR) is enhancing patient education and treatment planning. The introduction of biomimetic materials and smart composites is setting new standards for restorative and cosmetic procedures, with these materials designed to mimic and restore the natural characteristics of oral tissues.
Aging Population and Rising Dental Care Needs
The UK's aging population is a key demographic factor influencing the growth of the restorative and endo dentistry market. According to the Office for National Statistics (ONS), the proportion of individuals aged 65 and older is projected to increase significantly in the coming decades. This population segment is more susceptible to dental problems such as tooth loss, wear, and periodontal disease due to natural aging processes and chronic health conditions like diabetes. The elderly often require complex restorative and endodontic treatments, including dental implants, bridges, and root canals, to restore functionality and aesthetics. The increasing focus on enhancing the quality of life for older individuals further emphasizes the importance of accessible and advanced dental care services, fueling market expansion. A recent study projects that by 2050, around 9.6 million UK over-60s will have tooth decay, nearly doubling from 5 million in 2020. This shift in the burden of tooth decay and gum diseases from younger adults to older adults highlights the critical need for good dental care access for people currently in their 30s and 40s.
Growing Demand for Aesthetic Dentistry and Preventive Care
The rising awareness of oral health's impact on overall well-being has encouraged individuals to prioritize both preventive and aesthetic dental care. A growing number of consumers in the UK are seeking treatments that not only address functional issues but also enhance the appearance of their teeth. Procedures such as veneers, composite bonding, and cosmetic crowns are becoming increasingly popular, particularly among younger and middle-aged adults. Furthermore, educational initiatives and campaigns by organizations like the NHS and private entities have promoted routine dental check-ups, professional cleanings, and the use of fluoride treatments to prevent severe dental problems. This proactive approach to oral health has spurred demand for restorative and endodontic solutions, as timely interventions can preserve natural teeth and prevent complications. The adoption of Digital Smile Design (DSD) technology in 2024 offers patients a realistic preview of their smile before undergoing treatment, using advanced digital imaging to accurately show the results of procedures such as veneers, braces, or teeth whitening. This innovation enhances communication between patients and dental professionals, ensuring expectations are fully understood and incorporated into treatment plans.
Market Trends
Integration of Digital Dentistry Technologies
Digital dentistry is reshaping the landscape of the UK restorative and endo dentistry market by improving precision, efficiency, and patient experience. Technologies such as computer-aided design and computer-aided manufacturing (CAD/CAM), 3D printing, and intraoral scanners are increasingly being adopted by dental practices. CAD/CAM systems enable dental professionals to create customized restorative solutions such as crowns, bridges, and veneers with unmatched accuracy and speed. Additionally, 3D printing has gained traction for its ability to produce dental models, surgical guides, and even implant components at a fraction of the traditional cost and time. The integration of digital workflows reduces the need for multiple patient visits, enhances treatment outcomes, and minimizes procedural errors. These advancements align with the growing demand for personalized and minimally invasive dental care, positioning digital dentistry as a pivotal trend in the market. 60% of respondents believe digital dentistry is at the forefront of future growth in the sector.
Focus on Biocompatible and Aesthetic Materials
The shift toward biocompatible and aesthetically appealing dental materials is a notable trend in the UK restorative and endo dentistry market. Patients are increasingly prioritizing restorations that closely mimic the natural appearance of teeth, leading to higher demand for materials like zirconia, lithium disilicate, and advanced resin composites. These materials offer superior strength, durability, and translucency, ensuring long-lasting results without compromising on aesthetics. Furthermore, there is a growing emphasis on materials with antibacterial properties to reduce the risk of post-treatment complications. Innovations in restorative materials not only cater to patient preferences but also provide dental practitioners with advanced options to enhance clinical outcomes. This trend underscores the importance of research and development in developing materials that meet both functional and aesthetic expectations. Zirconia, for instance, has gained widespread popularity due to its high strength, biocompatibility, and natural appearance, making it ideal for crowns, bridges, and implants.
Rise of Minimally Invasive Procedures
Minimally invasive dentistry has emerged as a prominent trend, driven by advancements in techniques and patient preferences for less painful and time-intensive treatments. In endodontics, tools like rotary instruments and reciprocating files have streamlined root canal treatments, reducing the time required for procedures and enhancing accuracy. Similarly, adhesive bonding techniques and advancements in composite materials have allowed for minimally invasive restorations that preserve as much of the natural tooth structure as possible. Patients increasingly prefer procedures that ensure faster recovery times, reduced discomfort, and minimal risk of complications. This trend aligns with the broader healthcare movement toward conservative treatments and preventive care, making minimally invasive dentistry a key area of focus in the UK market. Laser dentistry, for example, is gaining popularity due to its minimally invasive nature and broad applications in procedures such as gum reshaping, cavity detection, and teeth whitening.
Growth of Private Dental Clinics and Specialty Practices
The increasing number of private dental clinics and specialized practices across the UK is significantly influencing market dynamics. While the National Health Service (NHS) provides essential dental care, limitations in funding and long waiting times have prompted many patients to seek services from private providers. Private clinics often offer advanced restorative and endodontic procedures, including aesthetic treatments and implantology, which may not be readily available through NHS services. These clinics also emphasize patient-centric care, leveraging modern technologies and high-quality materials to differentiate themselves in a competitive market. Additionally, many private practices are adopting flexible financing options to make advanced dental treatments more accessible, further driving the demand for restorative and endodontic solutions. Recent data indicates that 80% of UK dental providers now offer private treatment, with 97% of Scottish clinics offering private services, the highest in the UK.
Market Challenges
High Treatment Costs and Accessibility Issues
One of the primary challenges facing the UK restorative and endo dentistry market is the high cost of advanced treatments and the associated accessibility issues. While the National Health Service (NHS) provides essential dental care, there are often limitations on the range of services covered, particularly for more complex restorative and endodontic procedures. This leaves patients with the option of seeking private care, which can be expensive, especially for treatments such as dental implants, crowns, and root canal therapy. The cost barrier can deter some patients from seeking timely dental care, potentially leading to worsened oral health and more complex treatments later on. Additionally, the uneven distribution of dental services across rural and urban areas further exacerbates accessibility challenges. As a result, a significant portion of the population, particularly in underserved areas, may experience delays in receiving necessary dental treatments, affecting overall market growth.
Shortage of Skilled Dental Professionals
The shortage of skilled dental professionals is another key challenge affecting the UK restorative and endo dentistry market. The growing demand for advanced restorative and endodontic procedures requires an adequate number of trained specialists, but the UK has been experiencing a shortage of qualified dental professionals, particularly in specialized fields like endodontics and implantology. This shortage is exacerbated by the aging workforce, insufficient recruitment into dental schools, and the increasing migration of professionals to other countries due to better work opportunities or living conditions. The lack of specialists can lead to longer waiting times for patients, increased pressure on existing practitioners, and a reduced capacity for handling the growing demand for complex treatments. Addressing this shortage through increased training, retention programs, and recruitment of international talent is essential for ensuring the continued growth and sustainability of the restorative and endo dentistry market in the UK.
Market Opportunities
Expansion of Private Dental Practices and Specialist Clinics
A significant market opportunity within the UK restorative and endo dentistry sector lies in the continued expansion of private dental practices and specialist clinics. As NHS coverage for advanced restorative treatments remains limited, an increasing number of patients are turning to private healthcare providers for more comprehensive and specialized services. This trend is expected to grow as patients demand higher quality care, including cosmetic and implant dentistry. The rise in dental tourism, where patients from other countries seek high-quality, cost-effective treatments in the UK, further expands the potential for private practice growth. Investing in modern, state-of-the-art dental equipment, improving patient care, and offering flexible payment options could provide private clinics with a competitive edge in a growing market.
Advancement in Digital Dentistry and Innovative Treatment Modalities
The integration of digital technologies and innovative treatment options presents another major opportunity for growth in the UK Restorative and Endo Dentistry market. With increasing adoption of tools such as intraoral scanners, 3D imaging, and CAD/CAM systems, dental practices can provide more accurate diagnoses, faster treatment times, and better patient outcomes. Additionally, advancements in minimally invasive techniques, regenerative endodontics, and biologically based restorative materials offer promising opportunities to enhance both functional and aesthetic treatment outcomes. For dental manufacturers and service providers, this translates into a growing market for digital equipment, innovative dental materials, and advanced treatment protocols. Developing new products and solutions tailored to these technological advancements could position companies to capitalize on the increasing demand for efficient, personalized, and cutting-edge dental care.
Market Segmentation Analysis
By Material
In restorative dentistry, various materials are used based on their specific advantages. Amalgams, although less popular due to concerns about mercury content and aesthetics, remain a cost-effective choice for posterior restorations due to their durability. Composite resins are increasingly favored for aesthetic dentistry, especially in anterior restorations, as they closely resemble natural tooth structure and offer strong bonding capabilities. Glass ionomer cements are commonly used in pediatric dentistry and for patients with high caries risk, thanks to their adhesive properties and fluoride release. Metals such as gold, stainless steel, and titanium continue to be used for crowns, bridges, and implants due to their durability and strength, though they are less aesthetically pleasing than ceramics. Ceramics, particularly zirconia and lithium disilicate, are preferred for their natural appearance, strength, and biocompatibility, making them the material of choice for crowns, bridges, veneers, and implant abutments in aesthetic-focused treatments.
By Instruments
Handheld instruments, such as dental scalers, probes, and excavators, remain essential in restorative and endodontic procedures, particularly for manual cavity preparation and detailed root canal treatments. In contrast, rotary instruments, including dental drills and root canal files, are widely utilized for their precision, speed, and efficiency in both restorative and endodontic procedures. These instruments enhance tooth preparation and canal cleaning, ultimately improving treatment outcomes and patient satisfaction.
Segments
Based on Material
- Amalgams
- Composites
- Glass Ionomer Cements
- Metals
- Ceramics
Based on Instruments
- Handheld Instruments
- Rotary Instruments
Based on Equipment
- Diagnostic Instruments
- Intraoral Scanner
- Dental X-Ray
- Light Cutting Equipment
- CAD/CAM Systems
Based on End User
- Dental Hospitals & Clinics
- Academic & Research Institutes
- Others
Based on Region
- South East
- Midlands
- North West
- South West
- North East
Regional Analysis
South East and London (40%)
The South East and London regions dominate the UK Restorative and Endo Dentistry market, accounting for approximately 40% of the market share. This dominance is primarily due to the higher density of dental clinics, hospitals, and private practices offering specialized services in urban areas like London. The region benefits from a large, diverse population, with an increasing focus on both aesthetic and functional dental treatments. The availability of advanced dental technologies, including CAD/CAM systems, intraoral scanners, and digital imaging, further supports the region’s strong market presence. Additionally, London, as a hub for medical tourism, attracts patients from both domestic and international markets seeking high-quality dental care, which further fuels market growth.
Midlands (25%)
The Midlands region holds a significant share of the market at approximately 25%. The region is home to a growing number of dental hospitals, specialized clinics, and academic institutions focused on advancing dental research. The increase in disposable incomes, alongside heightened awareness of dental aesthetics and preventative care, has spurred demand for restorative and endodontic services. Moreover, the Midlands benefits from a relatively higher concentration of dental schools, which helps to drive the adoption of advanced dental technologies and materials. As private dental clinics expand and more patients opt for specialized care, the market share in this region is expected to continue its steady growth.
Key players
- Envista
- Dentsply Sirona USA
- Septodont USA
- 3M
- Nobel BioCare
- Zimmer Biomet Holdings, Inc.
Competitive Analysis
The UK Restorative and Endo Dentistry market is highly competitive, with leading players like Envista, Dentsply Sirona, and Nobel BioCare driving innovation and market expansion. Envista holds a strong market position with its diverse portfolio of dental products, including diagnostic, restorative, and endodontic solutions, backed by a global distribution network. Dentsply Sirona stands out with its comprehensive product offerings, including advanced CAD/CAM systems and endodontic instruments, making it a key player in the market. Septodont USA, known for its strong presence in dental anesthetics and endodontic materials, focuses on innovation in root canal treatment products. 3M and Zimmer Biomet continue to make inroads with their advanced materials and implant systems. Nobel BioCare leads in dental implantology, focusing on high-quality implants and restorative solutions. The competition among these players is characterized by product innovation, strategic acquisitions, and a focus on expanding their technological capabilities to meet the growing demand for restorative and endodontic procedures in the UK.
Recent Developments
- In November 2024, Septodont, along with Acteon, completed the acquisition of Laboratorios Inibsa, a global pharmaceutical group specializing in dental products. This acquisition is aimed at expanding Septodont's sales of dental products globally.
- In August 2023, 3M completed the sale of its dental local anesthetic portfolio assets to Pierrel S.p.A. This divestiture was part of 3M's strategy to focus on its core Oral Care technologies.
- In January 2023, Nobel Biocare, in partnership with Mimetis Biomaterials S.L., launched creos syntogain, a biomimetic bone graft substitute. This product expands their regenerative solutions portfolio and aligns with the demand for synthetic alternatives in dental regeneration.
Market Concentration and Characteristics
The UK Restorative and Endo Dentistry market is moderately concentrated, with a few dominant players holding significant market share, including global companies like Envista, Dentsply Sirona, 3M, and Nobel BioCare. These companies lead the market with their comprehensive product portfolios, which span diagnostic tools, restorative materials, endodontic instruments, and implant systems. The market is characterized by continuous innovation, particularly in digital dentistry, materials science, and minimally invasive techniques, which are key to meeting the growing demand for aesthetic and functional dental care. While the major players maintain a competitive edge, there is also room for regional and smaller specialized companies to serve niche markets, particularly in advanced technologies and high-quality restorative solutions. The presence of both large multinational corporations and specialized dental firms reflects the market’s dynamic and evolving nature.
Report Coverage
The research report offers an in-depth analysis based on Material, Instruments, Equipment, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to benefit from advancements in digital dentistry, including 3D imaging, CAD/CAM systems, and intraoral scanners. These technologies are expected to improve treatment precision, reduce procedure times, and enhance patient outcomes.
- As consumer awareness about aesthetic dentistry rises, there will be higher demand for procedures like veneers, crowns, and whitening. This trend will drive market growth, particularly in urban centers with higher disposable income.
- The shift towards minimally invasive restorative and endodontic treatments will continue, offering patients faster recovery times and reduced discomfort. Innovations in root canal therapy and conservative restorations are expected to grow in popularity.
- The aging UK population will contribute to a greater demand for restorative treatments like dental implants, bridges, and dentures. Older adults often require more complex dental care, increasing the need for specialized endodontic solutions.
- Private dental practices will play an increasing role in the market, driven by higher patient demand for advanced, personalized care not covered by the NHS. These practices will expand their service offerings to include premium restorative and endodontic treatments.
- The UK is likely to see an increase in dental tourism, as patients from other countries seek high-quality, cost-effective dental care. This trend will further fuel demand for advanced restorative and endodontic procedures in major urban areas.
- As patients prioritize safety and long-term outcomes, demand for biocompatible and durable restorative materials like zirconia, lithium disilicate, and resin composites will increase. These materials offer strength, aesthetics, and biocompatibility, driving market growth.
- The future will see growing integration of artificial intelligence (AI) and robotics in restorative and endodontic dentistry. AI can assist in diagnostics and treatment planning, while robotic-assisted surgeries will improve procedural accuracy.
- Dental implantology is expected to see sustained growth as more patients seek permanent solutions to tooth loss. Innovations in implant design and materials will make implants more accessible and effective, driving market demand.
- As preventive care becomes a priority in oral health, there will be a greater focus on early diagnosis and intervention. Restorative and endodontic procedures will increasingly be performed at earlier stages of dental conditions, improving long-term outcomes for patients.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the UK Restorative andEndo Dentistry Market in 2023 and 2032?
What factors are driving the growth of the UK Restorative and Endo Dentistry Market?
How is digital dentistry impacting the UK market?
Which regions are seeing the highest demand for restorative and endodontic dental care?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Restorative and Endo Dentistry Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UK Restorative and Endo Dentistry Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,473.67 million → 2032: USD 3,065.14 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Restorative and Endo Dentistry Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Restorative and Endo Dentistry Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Restorative and Endo Dentistry Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UK Restorative and Endo Dentistry Market Drivers
- 3.3 UK Restorative and Endo Dentistry Market Restraints & Challenges
- 3.4 UK Restorative and Endo Dentistry Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Restorative and Endo Dentistry Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Restorative and Endo Dentistry Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Restorative and Endo Dentistry category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Restorative and Endo Dentistry Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UK Restorative and Endo Dentistry Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UK Restorative and Endo Dentistry market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Restorative and Endo Dentistry Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UK Restorative and Endo Dentistry Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UK Restorative and Endo Dentistry Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Restorative and Endo Dentistry (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UK Restorative and Endo Dentistry Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UK Restorative and Endo Dentistry Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UK Restorative and Endo Dentistry Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UK Restorative and Endo Dentistry Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UK Restorative and Endo Dentistry Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UK Restorative and Endo Dentistry Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UK Restorative and Endo Dentistry Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UK Restorative and Endo Dentistry Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UK Restorative and Endo Dentistry Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
