
Market Overview
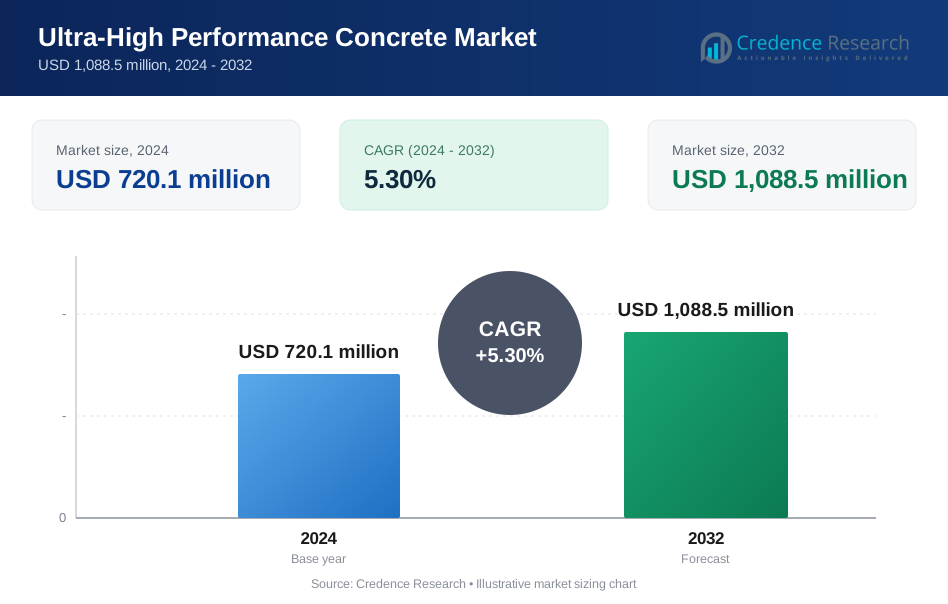
The Ultra-High Performance Concrete (UHPC) Market size was valued at USD 720.1 million in 2024 and is projected to reach USD 1,088.5 million by 2032, growing at a CAGR of 5.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Ultra-High Performance Concrete Market Size 2024 | USD 720.1 million |
| Ultra-High Performance Concrete Market, CAGR | 5.3% |
| Ultra-High Performance Concrete Market Size 2032 | USD 1,088.5 million |
The Ultra-High Performance Concrete Market grows through rising demand for durable, sustainable, and high-strength construction materials. It supports modern infrastructure projects such as bridges, highways, tunnels, and high-rise buildings requiring long service life and minimal maintenance.
North America leads the Ultra-High Performance Concrete Market with advanced infrastructure projects and strong government support for modernization programs. Europe follows with widespread adoption in sustainable construction, high-speed rail networks, and architectural applications emphasizing aesthetics and durability. Asia-Pacific records the fastest growth, driven by rapid urbanization, population expansion, and investments in smart cities and high-rise buildings. Latin America and the Middle East & Africa witness steady adoption, supported by infrastructure upgrades, urban development, and large-scale construction projects. Key players such as LafargeHolcim Ltd., Sika AG, Cemex S.A.B. de C.V., and Rampf Group play a vital role by investing in new formulations, fiber reinforcement technologies, and eco-friendly solutions. These companies collaborate with research institutions and governments to meet rising demand for high-performance materials. Innovation in precast applications, modular construction, and eco-efficient production strengthens their competitive position while addressing the increasing need for resilient, long-lasting construction solutions worldwide.
Market Insights
- The Ultra-High Performance Concrete Market was valued at USD 720.1 million in 2024 and is projected to reach USD 1,088.5 million by 2032, registering a CAGR of 5.3% during the forecast period.
- Market drivers include rising demand for durable, high-strength materials in bridges, tunnels, and high-rise buildings, supported by government-backed infrastructure investments and growing urbanization.
- Market trends highlight the integration of sustainable practices, with eco-friendly formulations, recycled materials, and energy-efficient manufacturing methods gaining traction to meet environmental standards.
- Competitive analysis shows key players such as LafargeHolcim Ltd., Cemex S.A.B. de C.V., Sika AG, and Rampf Group expanding through innovations in fiber reinforcement, precast applications, and modular construction.
- Market restraints include high production costs, limited local availability of raw materials, and technical complexities requiring skilled labor and advanced equipment for effective deployment.
- Regional analysis indicates North America leading with advanced infrastructure adoption, Europe focusing on sustainability and rail projects, and Asia-Pacific expanding rapidly through urbanization and smart city initiatives, while Latin America and the Middle East & Africa grow steadily through modernization programs.
- The market outlook remains positive as UHPC’s versatility in architectural, defense, marine, and industrial applications continues to expand, offering long-term opportunities for manufacturers investing in innovation, sustainability, and global partnerships.
Market Drivers
Rising Demand for High-Strength Infrastructure Solutions
The Ultra-High Performance Concrete Market grows through increasing need for durable and high-strength construction materials. It provides superior compressive strength, enhanced durability, and resistance to environmental degradation. Governments invest in bridges, highways, and high-rise buildings that require long-lasting materials. Urbanization drives demand for modern infrastructure with minimal maintenance. Construction companies prefer UHPC for projects requiring slim structural profiles and aesthetic flexibility. It supports lightweight designs without compromising strength, reducing overall material usage. Growing awareness of lifecycle cost benefits encourages broader adoption in public and private projects.
- For instance, LafargeHolcim's Ductal® UHPC was used in the Seonyu footbridge in South Korea. The bridge features a 120-meter arch span with a slab only 3 cm thick, which carried loads with compressive strengths exceeding 180 MPa.
Expansion in Transportation and Civil Engineering Projects
Infrastructure modernization in roads, bridges, and airports fuels UHPC adoption. It offers excellent fatigue resistance, ensuring long-term performance under heavy traffic. Engineers utilize UHPC in bridge decks, tunnel linings, and high-traffic pavements. The material reduces repair frequency and enhances safety standards. Transportation authorities increasingly specify UHPC for critical structures. Its ability to withstand freeze-thaw cycles supports projects in harsh climates. Rising investments in smart city initiatives further expand opportunities in civil engineering applications.
- For instance, Fort Miller Co., Inc. was contracted for the Kosciuszko Bridge replacement project to manufacture the precast concrete deck panels for the main span and the retaining walls.
Technological Advancements and Material Innovation
Continuous innovation strengthens the Ultra-High Performance Concrete Market. Manufacturers improve mix designs with nanomaterials, fibers, and supplementary cementitious components. It enhances workability, tensile strength, and durability while maintaining sustainability. New formulations allow faster curing and reduced construction timelines. Research in eco-friendly UHPC supports regulatory compliance and environmental standards. Collaborations between universities, research institutes, and construction firms accelerate adoption. Improved testing methods ensure consistent quality across large-scale projects.
Adoption in Specialized and Architectural Applications
UHPC finds increasing use in architectural facades, decorative panels, and complex structures. It enables thinner sections with intricate shapes while retaining structural integrity. Designers exploit its aesthetic versatility and smooth finishes for iconic buildings. Applications in defense, marine, and industrial facilities highlight performance under extreme conditions. It reduces maintenance costs and enhances lifecycle performance in specialized constructions. Growing interest from real estate developers drives uptake in high-end residential and commercial projects. Innovative use in combination with precast technology further expands market potential.
Market Trends
Integration of Sustainable and Eco-Friendly Practices
The Ultra-High Performance Concrete Market shows a strong shift toward sustainability in construction. It incorporates recycled materials, industrial by-products, and low-carbon cement substitutes. Developers prioritize projects that reduce environmental impact while maintaining performance. UHPC contributes to lower greenhouse gas emissions through reduced material consumption. Industry standards increasingly encourage eco-friendly mix designs. Companies adopt energy-efficient manufacturing processes to meet green certifications. Sustainability considerations drive wider acceptance across public and private sectors.
- For instance, the renovation of Switzerland's Chillon Viaduct in 2015 included the application of an Ultra-High Performance Fiber-Reinforced Cement-based Composite (UHPFRC). This material, a type of UHPC, was supplied by the company LafargeHolcim (now Holcim) and branded as Ductal®.
Growth in Precast and Modular Construction Applications
Precast and modular construction trends boost UHPC adoption in modern infrastructure. It supports faster assembly, uniform quality, and reduced labor costs. Manufacturers produce beams, panels, and structural elements off-site for efficient installation. It offers superior strength and durability in prefabricated components. Contractors prefer UHPC for complex geometries and lightweight modular designs. The material improves construction timelines and reduces on-site disruptions. Rising urbanization encourages modular solutions in residential, commercial, and industrial projects.
- For instance, RAMPF Group manufactures machine bed components using various materials, including the Ultra-High-Performance Concrete (UHPC) formulation known as EPUDUR. EPUDUR is used for high-precision, highly dynamic machine beds in the mechanical engineering industry, with UHPC materials capable of achieving compressive strengths over 200 MPa.
Adoption of Advanced Reinforcement and Fiber Technologies
UHPC increasingly integrates fiber reinforcement and high-performance admixtures to enhance durability. It provides crack resistance, tensile strength, and impact resilience in critical structures. Engineers combine steel, carbon, and synthetic fibers to optimize performance. It supports thinner sections and innovative architectural designs without compromising safety. Research continues to improve material consistency and longevity. Widespread testing ensures compliance with strict structural standards. Technological integration strengthens UHPC’s role in high-performance construction projects.
Rising Demand in High-Rise and Iconic Architectural Projects
Urban skylines drive adoption of UHPC in high-rise buildings and landmark structures. It allows slender, aesthetically appealing designs with minimal structural weight. Designers exploit its workability for complex façades and custom forms. It enhances durability in extreme weather and seismic conditions. Real estate developers seek premium materials that combine performance with visual appeal. UHPC reduces maintenance requirements in long-term building operations. Growing interest in signature projects sustains its market momentum globally.
Market Challenges Analysis
High Production Costs and Limited Raw Material Availability
The Ultra-High Performance Concrete Market faces challenges from elevated production costs. It relies on specialized materials, fibers, and high-quality cement, which increase manufacturing expenses. Contractors may hesitate to adopt UHPC for cost-sensitive projects. Limited local availability of essential raw materials further restricts widespread deployment. It requires precise mixing and curing processes to achieve expected performance, demanding skilled labor and advanced equipment. Price fluctuations in cement and additives impact project budgeting. Cost constraints slow adoption in emerging markets and small-scale infrastructure projects.
Technical Complexity and Limited Industry Expertise
Complexity in design and construction limits UHPC utilization in many applications. It requires specialized knowledge for structural calculations, formwork design, and fiber reinforcement integration. Mistakes in mixing or placement can compromise performance and durability. It demands strict quality control and testing protocols to meet safety standards. Contractors and engineers may lack experience with large-scale UHPC applications. Limited technical training and certification programs restrict market growth. Industry stakeholders must invest in expertise to maximize benefits of UHPC in advanced infrastructure projects.
Market Opportunities
Expansion in Smart Infrastructure and High-Performance Projects
The Ultra-High Performance Concrete Market benefits from growing investments in smart infrastructure projects. It supports long-lasting bridges, highways, and tunnels with minimal maintenance requirements. Urban development and high-density construction drive demand for durable, high-strength materials. It allows engineers to implement lightweight, slim-profile structures while maintaining structural integrity. Government initiatives promoting resilient infrastructure create new project opportunities. UHPC integration in transport, energy, and urban facilities enhances operational efficiency and safety. Rising adoption in public and private sectors strengthens market growth potential.
Adoption in Architectural, Decorative, and Specialized Applications
Innovative designs and premium construction projects fuel UHPC demand in architectural applications. It enables complex façades, thin panels, and sculptural elements with superior durability. Developers utilize it for marine, defense, and industrial facilities that require high-performance materials under extreme conditions. It reduces lifecycle costs and maintenance needs in specialized projects. Growing interest in iconic structures and sustainable buildings encourages broader material adoption. UHPC allows combination with precast and modular technologies for faster construction. Opportunities expand as architects and engineers explore creative and functional applications globally.
Market Segmentation Analysis:
By Material
The Ultra-High Performance Concrete Market by material includes cement, admixtures, fibers, and others. Cement forms the largest share due to its vital role in delivering compressive strength and durability. It ensures structural stability for bridges, tunnels, and high-rise buildings. Fibers, including steel, glass, and synthetic types, strengthen crack resistance and tensile performance. Admixtures improve workability and durability while supporting eco-friendly formulations. It helps manufacturers reduce cement usage while enhancing long-term performance. Expanding adoption of advanced fibers and sustainable admixtures increases demand across diverse construction projects.
- For instance, Lafarge supplied the Ultra-High Performance Concrete (UHPC) for the field-cast joints during the Pulaski Skyway deck rehabilitation, which took place between 2014 and 2018. The specific UHPC used, a proprietary mix called Ductal, had a specified compressive strength of 150 MPa (22,000 psi).
By Product
In product segmentation, the market divides into prefabricated elements and site-mixed formulations. Prefabricated components dominate due to rising adoption in modular and precast construction projects. They offer consistent quality, faster installation, and reduced labor requirements. It enables manufacturers to deliver customized panels, beams, and structural elements with high strength and durability. Site-mixed UHPC remains relevant in projects requiring on-site adjustments or unique structural demands. Contractors prefer prefabricated UHPC for infrastructure modernization, urban development, and smart city projects. Its role expands further as governments emphasize efficient, resilient infrastructure solutions.
By Application
Application analysis highlights demand across infrastructure, building construction, and military or specialized uses. Infrastructure projects lead due to large-scale adoption in bridges, tunnels, highways, and airports. It provides high durability and low maintenance for heavily loaded transport systems. Building construction embraces UHPC in high-rise structures, façades, and decorative panels, ensuring both strength and architectural appeal. Military and marine applications showcase its performance under extreme stress, corrosion, and environmental exposure. Demand grows in defense facilities, naval structures, and energy plants requiring advanced material reliability. Expanding urbanization and government-backed infrastructure investments reinforce its long-term role across these applications.
- For instance, full-scale industrial production of Ultra-High-Performance Fiber-Reinforced Concrete (UHPFRC) in Norway’s RMC plants achieved mixes with approximately 225 kg of micro steel fibers per cubic meter, enabling self-leveling UHPFRC suitable for bridge deck overlays with strengthening performance on par with lab-scale mixes.
Segments:
Based on Material
- Cement
- Sand
- Admixtures
- Others
Based on Product
- Structural Elements
- Facades
- Precast Elements
- Flooring
Based on Application
- Infrastructure
- Architectural
- Industrial
- Others
Based on End-use
- Construction Industry
- Architectural Industry
- Infrastructure Development
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest share of the Ultra-High Performance Concrete Market, accounting for 36% in 2024. The region benefits from early adoption of advanced concrete technologies and a strong focus on durable infrastructure. The United States drives demand through major investments in highways, bridges, and smart city initiatives. It also sees high adoption in defense facilities and energy projects requiring materials with superior strength and resistance. Canada contributes with sustainable urban development programs and the integration of UHPC in green-certified projects. Strict regulatory frameworks on construction quality and sustainability reinforce the use of advanced materials. Government-led infrastructure modernization plans continue to create growth opportunities across both public and private sectors.
Europe
Europe represents 28% of the market in 2024, supported by widespread emphasis on sustainable and energy-efficient construction practices. Countries such as Germany, France, and the United Kingdom adopt UHPC for bridges, tunnels, and high-speed rail projects. It also finds significant use in architectural applications, where design aesthetics and durability are critical. Europe’s strong environmental policies encourage eco-friendly formulations, further supporting UHPC adoption. Demand increases as countries upgrade transport networks and public facilities to meet urbanization pressures. Research institutes and industry collaborations drive material innovation and wider awareness across construction sectors. The region maintains a strong position due to technical expertise and regulatory alignment with green building standards.
Asia-Pacific
Asia-Pacific holds 22% of the Ultra-High Performance Concrete Market in 2024 and records the fastest growth rate. China and India lead demand due to rapid urbanization, population growth, and ambitious infrastructure projects. It supports the development of high-speed rail networks, airports, and smart cities. Japan and South Korea expand UHPC usage in both transportation and defense applications. The region benefits from rising investments in high-rise construction, driven by urban density and commercial expansion. Government-backed initiatives for resilient, disaster-proof infrastructure promote further adoption. Strong construction activity and innovation hubs accelerate the growth of UHPC across Asia-Pacific markets.
Latin America
Latin America accounts for 8% of the market in 2024, driven by infrastructure modernization and urban development programs. Brazil and Mexico lead regional adoption, focusing on transport networks, airports, and public facilities. It enhances the durability of infrastructure in regions exposed to tropical weather and environmental stress. Real estate projects in metropolitan areas integrate UHPC for premium construction and aesthetic value. Limited local availability of raw materials and technical expertise challenges widespread adoption. However, ongoing foreign investments in construction and energy sectors create new opportunities. Governments prioritize sustainable infrastructure, increasing UHPC potential in large-scale projects.
Middle East & Africa
The Middle East & Africa holds 6% of the Ultra-High Performance Concrete Market in 2024, with growth driven by ambitious urban development and mega infrastructure projects. The Gulf countries, particularly Saudi Arabia and the UAE, adopt UHPC in high-rise towers, luxury real estate, and landmark architectural projects. It provides resilience against extreme heat and environmental stress, making it suitable for regional conditions. Africa shows gradual adoption through urbanization and government-backed transport projects. Limited technical awareness and higher production costs restrict faster penetration in several markets. However, large-scale initiatives like Saudi Arabia’s Vision 2030 and Africa’s infrastructure investment programs expand opportunities. Strong focus on smart cities and durable construction positions the region for steady growth in UHPC adoption.\
Key Player Analysis
- EPC Engineering & Technologies GmbH
- CEMEX USA
- Sobute New Materials
- LafargeHolcim Ltd.
- Rampf Group
- Ductal (Lafarge Group)
- Cemex S.A.B. de C.V
- GCP Applied Technologies
- Sika AG
- Buzzi Unicem S.p.A
Competitive Analysis
Competitive landscape of the Ultra-High Performance Concrete Market features leading players such as LafargeHolcim Ltd., Cemex S.A.B. de C.V., Buzzi Unicem S.p.A., CEMEX USA, Sika AG, Ductal (Lafarge Group), EPC Engineering & Technologies GmbH, GCP Applied Technologies, Rampf Group, and Sobute New Materials. These companies compete by focusing on innovation, sustainable product development, and expanding applications in infrastructure and architectural projects. They invest heavily in research to improve material formulations, integrating fibers, nanomaterials, and eco-friendly admixtures to enhance durability and reduce environmental impact. Partnerships with government bodies, universities, and construction firms strengthen their position in large-scale projects worldwide. Many players expand their geographic reach by establishing new manufacturing facilities and distribution networks in rapidly growing regions such as Asia-Pacific and the Middle East. Competitive intensity is also shaped by demand for precast solutions, modular construction, and architectural applications where UHPC delivers unique performance benefits. The market remains dynamic, with continuous advancements in design flexibility, cost efficiency, and compliance with global construction standards driving leadership and differentiation among these companies.
Recent Developments
- In July 2025, Sika Corporation introduced a new line of UHPC products featuring advanced fiber-reinforcement technologies to boost structural performance and sustainability.
- In March 2024, LafargeHolcim expanded its UHPC production capacity in Europe. This increase boosts availability for high-performance construction material delivery.
- In 2024, Sika AG reported its revenue at CHF 11.763 billion, with a net income of CHF 1.248 billion, across 34,476 employees worldwide.
- In May 2023, Sika AG completed its acquisition of MBCC Group. This added over 6,200 employees, 95 global production sites, and significantly broadened Sika’s UHPC-supporting chemical portfolio
Report Coverage
The research report offers an in-depth analysis based on Material, Product, Application, End-use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with rising demand for durable and sustainable construction materials.
- Infrastructure modernization will drive adoption in bridges, highways, tunnels, and transport networks.
- Urbanization will increase UHPC use in high-rise buildings and smart city projects.
- Eco-friendly formulations and low-carbon mixes will gain greater industry acceptance.
- Precast and modular construction will boost demand for prefabricated UHPC components.
- Architectural applications will grow with rising interest in slim profiles and complex designs.
- Defense, marine, and energy projects will strengthen demand for high-performance concrete solutions.
- Asia-Pacific will record the fastest growth supported by government-backed development initiatives.
- Research in advanced fibers and nanomaterials will improve performance and application scope.
- Competitive strategies will focus on sustainability, cost efficiency, and global partnerships.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for High-Strength Infrastructure Solutions
The need for durable, high-strength materials in bridges, tunnels, and high-rise buildings is driving UHPC adoption, as it offers superior compressive strength, durability, and resistance to environmental degradation. Government investments in infrastructure and urbanization further accelerate this demand.
Expansion in Transportation and Civil Engineering Projects
Modernization of roads, bridges, and airports is fueling UHPC use due to its excellent fatigue resistance and long-term performance under heavy traffic. Its ability to withstand harsh climates and reduce repair frequency makes it a preferred choice for critical infrastructure.
Technological Advancements and Material Innovation
Continuous improvements in UHPC mix designs, including the integration of nanomaterials, fibers, and eco-friendly admixtures, are enhancing workability, strength, and sustainability. These innovations enable faster curing, reduced construction timelines, and compliance with environmental standards.
Growth in Precast and Modular Construction Applications
The trend toward precast and modular construction is boosting UHPC demand, as it allows for faster assembly, consistent quality, and reduced labor costs. Prefabricated UHPC components are increasingly used in urban development and smart city projects.
Integration of Sustainable and Eco-Friendly Practices
The market is seeing a strong shift toward sustainability, with UHPC formulations incorporating recycled materials and low-carbon cement substitutes. This aligns with stricter environmental standards and growing industry focus on reducing the carbon footprint of construction materials.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Ultra-High Performance Concrete, and what is its projected size in 2032?
Which Ultra-High Performance Concrete market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Ultra-High Performance Concrete market?
Who are the leading companies in the Ultra-High Performance Concrete market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-use
- 1.2.1 Construction Industry
- 1.2.2 Architectural Industry
- 1.2.3 Infrastructure Development
- 1.2.4 Others
- 1.3 By Product
- 1.3.1 Structural Elements
- 1.3.2 Facades
- 1.3.3 Precast Elements
- 1.3.4 Flooring
- 1.4 By Material
- 1.4.1 Cement
- 1.4.2 Sand
- 1.4.3 Admixtures
- 1.4.4 Fibers
- 1.4.5 Others
- 1.5 By Application
- 1.5.1 Infrastructure
- 1.5.2 Architectural
- 1.5.3 Industrial
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 720.1 million → 2032: USD 1,088.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Ultra-High Performance Concrete Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Ultra-High Performance Concrete Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Ultra-High Performance Concrete Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Ultra-High Performance Concrete Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Ultra-High Performance Concrete Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Ultra-High Performance Concrete Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Ultra-High Performance Concrete Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Ultra-High Performance Concrete Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 720.1 million → 2032: USD 1,088.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Ultra-High Performance Concrete Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Construction Industry
- 12.3.7.2 Architectural Industry
- 12.3.7.3 Infrastructure Development
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Structural Elements
- 12.4.7.2 Facades
- 12.4.7.3 Precast Elements
- 12.4.7.4 Flooring
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Cement
- 12.5.7.2 Sand
- 12.5.7.3 Admixtures
- 12.5.7.4 Fibers
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Infrastructure
- 12.6.7.2 Architectural
- 12.6.7.3 Industrial
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Ultra-High Performance Concrete End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Ultra-High Performance Concrete Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Ultra-High Performance Concrete Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Ultra-High Performance Concrete Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 LafargeHolcim Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sika AG
- 18.4 Cemex S.A.B. de C.V.
- 18.5 Rampf Group
- 18.6 Buzzi Unicem S.p.A
- 18.7 CEMEX USA
- 18.8 Ductal (Lafarge Group)
- 18.9 EPC Engineering & Technologies GmbH
- 18.10 GCP Applied Technologies
- 18.11 Sobute New Materials
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

