
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| UK Digital Oilfield Solutions Market Size 2024 | USD 1,297.06 million |
| UK Digital Oilfield Solutions Market, CAGR | 7.16% |
| UK Digital Oilfield Solutions Market Size 2032 | USD 2,254.74 million |
Market Overview
The UK Digital Oilfield Solutions Market is projected to grow from USD 1,297.06 million in 2024 to an estimated USD 2,254.74 million by 2032, reflecting a compound annual growth rate (CAGR) of 7.16% from 2025 to 2032. This growth is primarily driven by the increasing adoption of digital technologies aimed at enhancing operational efficiency and reducing carbon footprints in the oil and gas sector.
Key market drivers include the emphasis on energy security, environmental sustainability, and government support for offshore exploration in the North Sea. The integration of advanced technologies such as predictive analytics and the Internet of Things (IoT) is further propelling market expansion. These technologies facilitate real-time monitoring and data-driven decision-making, optimizing production processes.
Geographically, Europe leads the digital oilfield market, with significant investments in advanced technologies and a strong regulatory framework promoting digitalization in the oil and gas industry. In the UK, major players such as Schlumberger, Halliburton, Siemens Energy AG, Baker Hughes Company, and Weatherford International Ltd. are actively contributing to market growth through innovative solutions and services.
Market Insights
- The UK Digital Oilfield Solutions Market is projected to grow from USD 1,297.06 million in 2024 to USD 2,254.74 million by 2032, with a CAGR of 7.16% from 2025 to 2032.
- The Global Digital Oilfield Solutions Market is projected to grow from USD31,374.00 million in 2024 to USD 54,897.18 million by 2032, with a CAGR of 7.24% from 2025 to 2032.
- Increasing adoption of digital technologies like IoT and predictive analytics is optimizing production processes and reducing operational costs.
- Growing focus on sustainability and energy security is driving the adoption of digital solutions that reduce carbon footprints in the oil and gas sector.
- High initial investment costs and complex system integrations may limit adoption, particularly for smaller operators in the UK.
- Data security concerns and the need for robust cybersecurity measures pose challenges to the wide-scale implementation of digital solutions.
- Europe, with the UK leading, is the dominant region for digital oilfield solutions, driven by strong regulatory frameworks and significant investments in advanced technologies.
- Major players like Schlumberger, Halliburton, Siemens Energy, and Baker Hughes are central to the market’s growth, offering innovative solutions across various oilfield processes.
Market Drivers
Increased Focus on Operational Efficiency and Cost Reduction
The UK digital oilfield solutions market is significantly driven by the growing need for operational efficiency and cost reduction in the oil and gas industry. As operators face increasing pressures to improve profitability in a volatile market environment, digital solutions that streamline operations have become crucial. Technologies such as data analytics, real-time monitoring, and automation enable oilfield operators to optimize production, reduce downtime, and minimize the need for manual interventions. Predictive maintenance, enabled by Internet of Things (IoT) devices, also helps in identifying potential failures before they occur, allowing for timely repairs and minimizing costly disruptions. By leveraging digital solutions, oilfield operators can maximize asset utilization, reduce operating costs, and improve overall efficiency in managing oil and gas production operations. For instance, in the UK, the Oil and Gas Authority reported that improving production efficiency led to an additional 12 million barrels of oil equivalent being produced in a year, highlighting the impact of operational efficiency on output and profitability. Digital solutions such as real-time monitoring and automation have been instrumental in this improvement by reducing downtime and optimizing production processes. This has led to the widespread adoption of digital oilfield technologies in the UK, contributing to the market's growth.
Advancement of Digital Technologies and Automation
Technological advancements in the digital realm are another major driver of the UK digital oilfield solutions market. The oil and gas sector is increasingly adopting cutting-edge technologies such as artificial intelligence (AI), machine learning (ML), big data analytics, and IoT devices to enhance operational capabilities. These technologies allow for improved decision-making through real-time data collection, analysis, and processing. AI-driven predictive analytics enables operators to predict potential equipment failure and optimize maintenance schedules, leading to fewer unplanned outages and enhanced productivity. Automation also plays a critical role by reducing dependency on manual processes, minimizing human error, speeding up operations, reducing accident risks, and enhancing safety in the field. For instance, AI and machine learning technologies are being used to analyze vast datasets, including seismic surveys and well logs, to identify potential oil reservoirs more accurately and efficiently. This reduces exploration time and costs while minimizing environmental impact by focusing drilling efforts on high-potential areas. Additionally, AI-driven predictive analytics enable operators to predict equipment failures, optimize maintenance schedules, and reduce unplanned outages. The convergence of these digital technologies fosters improved efficiency, decision-making, and productivity, making it a significant market driver for digital oilfield solutions in the UK.
Government Regulations and Focus on Environmental Sustainability
The UK government's regulations and initiatives focusing on reducing the environmental impact of oil and gas operations are contributing to the growth of the digital oilfield solutions market. As part of its commitment to environmental sustainability and the reduction of carbon emissions, the UK government has been encouraging the adoption of technologies that can minimize the carbon footprint of energy operations. Digital oilfield solutions that enable real-time monitoring of emissions, energy consumption, and other environmental parameters are essential in ensuring compliance with these regulations. Furthermore, technologies such as carbon capture and storage (CCS) integrated into digital oilfield solutions are helping companies adhere to environmental regulations while optimizing production. By providing more sustainable solutions, digital oilfield technologies not only help the industry comply with governmental policies but also promote the UK's broader energy transition goals toward cleaner energy sources.
Enhancements in Data-Driven Decision-Making and Monitoring Systems
The increasing reliance on data-driven decision-making is a key driver of the digital oilfield solutions market in the UK. The ability to collect, analyze, and interpret vast amounts of data from various sensors, instruments, and equipment across the oilfield is transforming the way oil and gas operators manage their operations. Advanced data analytics and cloud computing enable real-time monitoring and analysis, allowing for better insights into field performance, resource allocation, and overall productivity. This data-driven approach leads to more accurate forecasting, risk management, and well-planning, as well as the optimization of production workflows. Furthermore, integrated monitoring systems ensure that oilfield operators have a comprehensive view of their assets, enabling proactive management and minimizing operational inefficiencies. As the volume and complexity of data in the oil and gas sector continue to grow, the need for sophisticated data analytics and monitoring systems becomes increasingly important, driving the demand for digital oilfield solutions in the UK.
Market Trends
Integration of Artificial Intelligence and Machine Learning for Predictive Maintenance
A significant trend in the UK digital oilfield solutions market is the growing integration of Artificial Intelligence (AI) and Machine Learning (ML) for predictive maintenance. Predictive maintenance helps oilfield operators anticipate equipment failures before they occur by analyzing large sets of data collected from sensors and monitoring devices. The predictive models built with AI and ML algorithms process historical data, identify patterns, and flag potential issues in real time. This shift from reactive to proactive maintenance not only improves equipment uptime but also reduces unplanned downtime, which can be highly costly in the oil and gas sector. Furthermore, predictive maintenance optimizes resource allocation by scheduling maintenance activities during non-peak times, minimizing disruptions to operations. For instance, companies like Shell have successfully implemented predictive maintenance using machine learning algorithms to analyze data from IoT sensors. This approach has allowed them to reduce downtime by 20% and improve equipment reliability by 15% by identifying potential failures early and scheduling maintenance accordingly. The UK oil and gas industry is embracing these technologies to drive cost-efficiency and improve productivity, making predictive maintenance one of the most notable trends in the digital oilfield solutions market.
Adoption of Cloud-Based Platforms for Enhanced Data Storage and Access
Another growing trend in the UK digital oilfield solutions market is the widespread adoption of cloud-based platforms for data storage and access. The oil and gas industry generates vast amounts of data, from sensor readings and operational data to maintenance logs and production statistics. Managing and storing this data in on-premise systems can be costly and inefficient, especially when considering the need for real-time access to vast datasets. Cloud computing addresses this challenge by providing scalable, secure, and cost-effective solutions for data storage. Moreover, cloud platforms allow for seamless integration of digital oilfield solutions across different assets, locations, and operational stages. For example, cloud computing enables oil and gas companies to manage vast datasets more efficiently. By leveraging cloud platforms, companies can process real-time data from sensors and IoT devices, which helps in optimizing drilling performance and detecting operational anomalies. This capability supports better decision-making and enhances operational efficiency across geographically dispersed environments. The ability to access and interpret data from any location ensures better communication across teams while enabling agile operations. As a result, the UK digital oilfield solutions market is witnessing increased investment in cloud technology, further driving digital transformation in the sector.
Use of IoT and Remote Monitoring for Enhanced Operational Control
The increasing deployment of Internet of Things (IoT) devices and remote monitoring systems is another prominent trend shaping the UK digital oilfield solutions market. IoT devices, embedded with sensors, are used to collect real-time data on equipment performance, environmental conditions, and operational metrics across oilfields. These devices are connected to centralized systems that allow for continuous monitoring of key variables such as pressure, temperature, and flow rate. IoT-based monitoring systems provide operators with a real-time overview of their assets, enabling them to make data-driven decisions that improve efficiency and mitigate risks. For instance, real-time alerts can be triggered when equipment is operating outside optimal conditions, allowing maintenance teams to address issues before they lead to significant downtime or damage. Additionally, IoT systems help optimize resource use by monitoring energy consumption and identifying opportunities for efficiency improvements. Remote monitoring capabilities are also becoming more advanced, enabling operators to manage oilfields and offshore platforms from centralized control rooms, thereby improving safety, reducing operational costs, and enhancing overall productivity.
Focus on Decarbonization and Sustainable Practices
A key trend that is gaining momentum in the UK digital oilfield solutions market is the growing emphasis on decarbonization and sustainable practices. As part of the UK's commitment to achieving net-zero carbon emissions by 2050, the oil and gas sector is under increasing pressure to adopt environmentally responsible practices. Digital oilfield technologies are playing a crucial role in this transition by helping operators monitor and reduce their carbon footprint. For example, solutions such as real-time emissions monitoring, data analytics for carbon tracking, and digital solutions for improving energy efficiency are becoming increasingly common. Additionally, digital technologies enable better resource management, waste reduction, and the efficient use of renewable energy sources in oilfields. Carbon capture and storage (CCS) technologies integrated into digital oilfield solutions are helping companies minimize their impact on the environment while maintaining production levels. Furthermore, digital solutions provide insights that enable companies to optimize production while reducing energy consumption, ultimately contributing to the industry's sustainability goals. This trend toward decarbonization and environmental sustainability is expected to continue to drive the adoption of digital oilfield solutions as companies seek to balance operational efficiency with their environmental responsibilities.
Market Challenges
High Initial Investment and Implementation Costs
One of the primary challenges facing the UK digital oilfield solutions market is the significant initial investment required for the adoption of advanced digital technologies. The integration of solutions such as Artificial Intelligence (AI), Machine Learning (ML), Internet of Things (IoT) devices, and cloud platforms involves substantial upfront costs for both hardware and software infrastructure. Additionally, implementing these technologies requires specialized personnel, training, and sometimes extensive system overhauls. For many operators, particularly smaller firms, these high costs can be a barrier to entry. For instance, the integration of advanced digital technologies like AI, ML, IoT devices, and cloud platforms often necessitates not only the purchase of hardware and software but also investments in training personnel and overhauling existing systems. For example, deploying data analytics and digital technologies for asset maintenance and operations on the UK Continental Shelf could potentially save £1.5 billion annually by improving production efficiency and reducing maintenance costs. However, achieving these benefits requires a considerable financial commitment upfront, which remains a challenge for many organizations. The return on investment (ROI) for digital oilfield solutions can take time to materialize due to the complexity of setting up these systems. Moreover, ongoing maintenance, software updates, and cybersecurity measures add to the long-term financial burden. While the long-term benefits-such as improved efficiency, reduced downtime, and optimized resource usage-can outweigh these costs, the high initial investment continues to deter many organizations from fully embracing digitalization in their operations.
Data Security and Integration Issues
As the UK oil and gas sector increasingly relies on digital technologies, the issue of data security and system integration becomes a critical challenge. Digital oilfield solutions generate large volumes of data, which must be securely stored and managed to prevent breaches, cyberattacks, or data loss. With the growing use of cloud platforms and IoT devices, the risk of cyber threats increases, and ensuring the security of sensitive operational data becomes more complex. Furthermore, integrating various digital solutions into existing legacy systems can present significant challenges. Compatibility issues may arise, leading to delays, additional costs, or system inefficiencies. Ensuring seamless integration across different platforms and maintaining cybersecurity while adopting new technologies is a delicate balancing act for oilfield operators. This creates a barrier for full-scale implementation, especially for firms that are not fully equipped to handle complex IT infrastructures and security requirements.
Market Opportunities
Expansion of Digitalization in Offshore and Onshore Operations
The UK Digital Oilfield Solutions Market presents significant opportunities for growth, particularly with the ongoing expansion of digital technologies in both offshore and onshore oil and gas operations. The UK’s oil and gas industry is increasingly focusing on enhancing operational efficiency, reducing costs, and ensuring environmental sustainability. Digital solutions that enable real-time monitoring, predictive maintenance, and data-driven decision-making are being adopted across oilfields to streamline production processes. As offshore oil and gas exploration in the North Sea continues to evolve, the need for advanced digital solutions to monitor and manage operations in remote and harsh environments is growing. Digital technologies like IoT sensors, AI-driven analytics, and automation systems offer substantial potential to optimize drilling, production, and reservoir management, ensuring that operators achieve greater cost-effectiveness and production efficiency. This demand for innovative solutions across both offshore and onshore sectors creates a substantial opportunity for companies providing digital oilfield technologies in the UK market.
Increasing Focus on Sustainability and Carbon Management
Another key market opportunity lies in the growing emphasis on sustainability and carbon management. As part of its commitment to achieving net-zero emissions by 2050, the UK government has set stringent regulations for reducing the carbon footprint of oil and gas operations. Digital oilfield solutions that enable real-time emissions monitoring, energy efficiency improvements, and carbon capture are well-positioned to meet these environmental goals. The integration of advanced technologies such as carbon capture and storage (CCS), digital energy management systems, and real-time environmental monitoring offers significant opportunities for companies that can provide innovative solutions to help the industry reduce its environmental impact. With the UK’s push towards greener energy, digital oilfield solutions that promote sustainability are set to experience accelerated demand in the coming years.
Market Segmentation Analysis
By Solution:
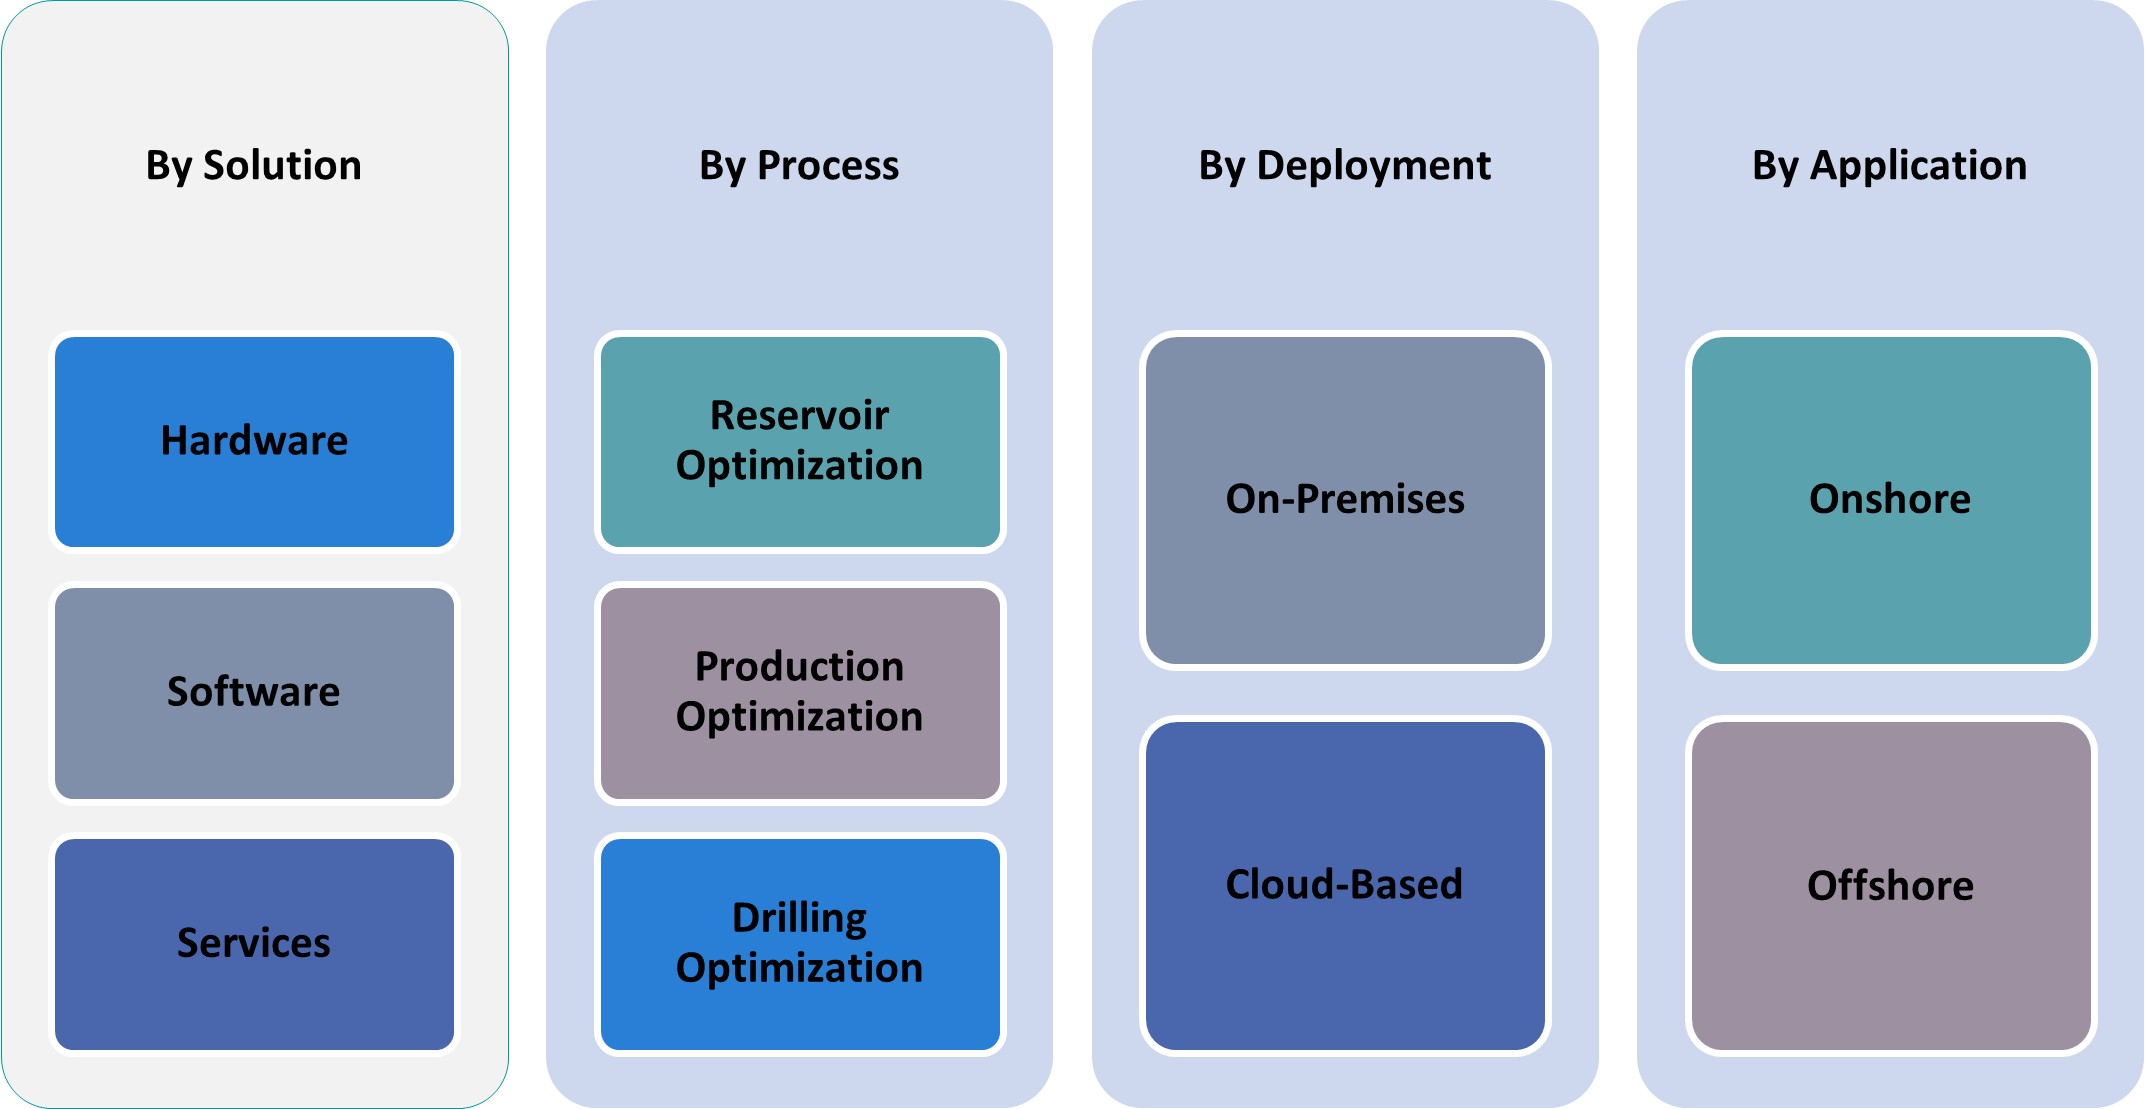
The market is divided into three main solution categories: hardware, software, and services. Hardware constitutes devices and equipment, including sensors, IoT devices, and communication infrastructure, enabling the digitalization of operations. Software solutions encompass applications for data analysis, cloud platforms, and automation tools that optimize decision-making, production processes, and performance monitoring. Services include consulting, system integration, maintenance, and support services necessary for the successful implementation and ongoing functionality of digital oilfield solutions. The software segment is projected to experience rapid growth as companies look to leverage data analytics and AI for enhanced decision-making.
By Application:
The market also segments by application, with significant activity in both onshore and offshore oil and gas operations. Offshore operations, particularly in the North Sea, are a key area for digital oilfield solutions due to the complexity and high costs of managing offshore oilfields. Digital technologies are crucial for remote monitoring, predictive maintenance, and optimizing drilling and production processes. Onshore operations also see a growing demand for digital solutions, especially in the context of improving operational efficiency, reducing costs, and ensuring safety and compliance.
Segments
Based on Solution
- Hardware
- Software
- Service
Based on Application
- Onshore
- Offshore
Based on Process
- Reservoir Optimization
- Production Optimization
- Drilling Optimization
Based on Deployment
- On-Premises
- Cloud-Based
Based on Region
- South East England
- North West England
- Scotland
- Other regions
Regional Analysis
South East England (45%)
South East England holds the largest market share in the UK Digital Oilfield Solutions Market, contributing approximately 45% of the total market. This region is a key hub for oil and gas activities, hosting major industry players, energy companies, and technological innovators. With the presence of leading firms such as BP and Royal Dutch Shell, South East England benefits from substantial investments in digital oilfield technologies. The region also hosts numerous research and development centers that focus on enhancing digital solutions, automation, and smart field technologies, thus promoting rapid adoption across the sector.
North West England (25%)
North West England follows with a market share of around 25%. This region has a high concentration of offshore oil and gas infrastructure in the North Sea, which drives the demand for digital oilfield solutions aimed at improving offshore production efficiency and safety. The growing need for remote monitoring, predictive maintenance, and data analytics in offshore operations positions the North West as a significant player in the market. Furthermore, the region benefits from strong partnerships between local technology providers and energy firms, ensuring the continuous integration of innovative digital solutions in the sector.
Key players
- ABB Ltd.
- Schneider Electric SE
- Kongsberg Gruppen ASA
- TechnipFMC plc
- Wipro Limited
- Rockwell Automation, Inc.
- IBM Corporation
- SAP SE
- Yokogawa Electric Corporation
Competitive Analysis
The UK Digital Oilfield Solutions Market is highly competitive, with major players offering a wide range of advanced digital technologies to enhance operational efficiency and sustainability in oil and gas operations. ABB Ltd. and Schneider Electric SE are leaders in providing automation and control systems, enabling optimized production processes. Kongsberg Gruppen ASA and TechnipFMC plc offer integrated solutions for offshore operations, focusing on real-time monitoring and automation. Wipro Limited and Rockwell Automation, Inc. bring expertise in data analytics, IoT, and digital transformation services. IBM Corporation and SAP SE provide cloud-based platforms and AI-driven analytics that enable data-driven decision-making. Yokogawa Electric Corporation stands out with its expertise in process control and monitoring systems. These companies are competing not only on technology but also on their ability to integrate solutions that improve efficiency, safety, and environmental sustainability.
Recent Developments
- In March 2025, Schneider Electric unveiled the One Digital Grid Platform, an AI-powered platform designed to enhance grid resiliency and efficiency. This platform is set to be available later in 2025. The company announced a $700 million investment plan in the U.S. to enhance energy infrastructure and AI capabilities.
- In April 2025, ABB India delivered integrated automation and digital solutions for IndianOil's cross-country pipeline network, enhancing efficiency and safety through real-time monitoring and robust cybersecurity.
- In March 2025, Kongsberg Digital participated in the IPTC 2025, focusing on digital transformation in the oil and gas sector
- In January 2025, SAP S/4HANA Cloud was highlighted as a key enabler for a smarter, more efficient energy ecosystem in the oil and gas industry.
- In April 2025, Schlumberger (SLB) announced a partnership with Shell to deploy Petrel™ subsurface software across Shell's global assets. This collaboration aims to enhance digital capabilities and operational efficiencies through advanced AI-driven seismic interpretation workflows. This development underscores SLB's ongoing commitment to advancing subsurface digital technology and fostering strategic partnerships in the energy sector.
Market Concentration and Characteristics
The UK Digital Oilfield Solutions Market exhibits a moderately concentrated competitive landscape, with a mix of global technology providers and specialized industry players. Leading companies such as ABB Ltd., Schneider Electric SE, TechnipFMC plc, and Yokogawa Electric Corporation dominate the market by offering comprehensive digital solutions ranging from automation, control systems, and IoT integration to AI-driven analytics and cloud platforms. These players are actively collaborating with oil and gas operators to enhance operational efficiency, reduce costs, and improve safety and sustainability. The market is characterized by rapid technological advancements, with continuous innovation in areas like predictive maintenance, real-time monitoring, and energy optimization. While large multinational corporations hold significant market shares, there is also room for specialized firms to offer niche solutions that cater to specific industry needs, fostering a dynamic and evolving market environment.
Report Coverage
The research report offers an in-depth analysis based on Solution, Application, Process, Deployment and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- AI and machine learning will play a crucial role in automating processes, enabling predictive maintenance, and improving decision-making, driving further adoption of digital oilfield solutions in the UK.
- The shift to cloud-based platforms will continue, providing scalable and cost-effective solutions for data storage, real-time analysis, and integration across oil and gas operations, enhancing overall efficiency.
- With a strong focus on reducing carbon emissions, digital oilfield solutions will increasingly incorporate technologies like carbon capture, storage (CCS), and real-time emissions monitoring to meet sustainability goals.
- IoT-enabled sensors and devices will proliferate, providing real-time monitoring and data collection across the entire oilfield, enabling operators to optimize performance and ensure operational continuity.
- Remote monitoring and control systems will gain traction, especially in offshore operations, reducing the need for on-site personnel and improving safety while maintaining operational effectiveness.
- Advanced data analytics will become more integrated with oilfield operations, providing actionable insights into production optimization, resource management, and risk mitigation for more informed decision-making.
- Government initiatives promoting digitalization in the oil and gas sector will continue, encouraging companies to adopt innovative technologies and providing financial incentives for the integration of digital solutions.
- The development and implementation of digital twin technologies will expand, allowing operators to create virtual replicas of oilfields for better simulation, monitoring, and optimization of processes.
- As digitalization grows, there will be a heightened emphasis on cybersecurity to protect critical infrastructure, data, and operations from potential cyber threats and breaches in the oilfield sector.
- Collaborations between technology providers, oilfield operators, and regulatory bodies will increase, fostering innovation and accelerating the adoption of digital oilfield solutions while ensuring compliance with industry standards and regulations.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the UK Digital Oilfield Solutions Market in 2024 and 2032?
What are the key drivers of the UK Digital Oilfield Solutions Market?
What is the geographical landscape of the UK Digital Oilfield Solutions Market?
Who are the key players in the UK Digital Oilfield Solutions Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Digital Oilfield Solutions Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 UK Digital Oilfield Solutions Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,297.06 million → 2032: USD 2,254.74 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Digital Oilfield Solutions Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Digital Oilfield Solutions Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Digital Oilfield Solutions Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 UK Digital Oilfield Solutions Drivers
- 3.3 UK Digital Oilfield Solutions Restraints & Challenges
- 3.4 UK Digital Oilfield Solutions Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Digital Oilfield Solutions Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Digital Oilfield Solutions Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Digital Oilfield Solutions category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Digital Oilfield Solutions Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. UK Digital Oilfield Solutions Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2024)
- 5.1.2 Export Volume by Destination Country (2024) (Where Applicable)
- 5.1.3 Import Value by Source Country (2024)
- 5.1.4 Import Volume by Source Country (2024) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to UK Digital Oilfield Solutions in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Digital Oilfield Solutions Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 UK Digital Oilfield Solutions Share Analysis – 2024
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 UK Digital Oilfield Solutions Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Digital Oilfield Solutions (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in UK Digital Oilfield Solutions
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. UK Digital Oilfield Solutions – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. UK Digital Oilfield Solutions – Priority Domestic Market 1
Chapter 10. UK Digital Oilfield Solutions – Priority Domestic Market 2
Chapter 11. UK Digital Oilfield Solutions – Priority Domestic Market 3
Chapter 12. UK Digital Oilfield Solutions – Priority Domestic Market 4
Chapter 13. UK Digital Oilfield Solutions Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
