
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| UK Meat Processing Equipment Market Size 2023 | USD 485.31 million |
| UK Meat Processing Equipment Market, CAGR | 5.11% |
| UK Meat Processing Equipment Market Size 2032 | USD 760.56 million |
Market Overview:
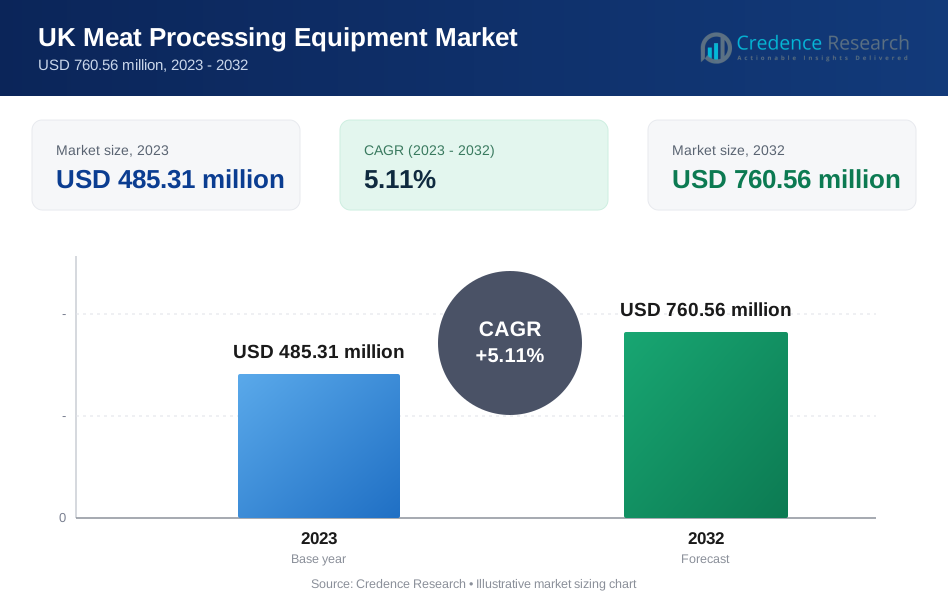
UK Meat Processing Equipment Market size was valued at USD 485.31 million in 2023 and is anticipated to reach USD 760.56 million by 2032, at a CAGR of 5.11% during the forecast period (2023-2032).
The growth of the UK Meat Processing Equipment Market is primarily fueled by rising consumer demand for processed and packaged meat products. Changing dietary preferences, coupled with busier lifestyles, have increased the consumption of ready-to-cook and processed meat, propelling demand for efficient meat processing solutions. Additionally, stringent government regulations regarding hygiene, food safety, and quality standards have compelled meat processors to invest in advanced machinery that ensures compliance while improving productivity. The shift towards automation, incorporating robotics and IoT-enabled monitoring systems, has further driven the adoption of modern meat processing equipment. The emphasis on sustainability and waste reduction in food processing also encourages investments in energy-efficient and resource-optimizing machinery.
The UK market for meat processing equipment is concentrated in regions with a high density of food processing industries, such as London, the Midlands, and the North West. These areas house major food production and processing facilities, benefiting from well-established supply chains and skilled labor availability. The South East and Scotland are also emerging as significant markets, supported by increasing investments in food processing infrastructure and rising consumer demand for processed meat products. Brexit-related trade policies have impacted the supply chain dynamics, encouraging local manufacturers to invest in domestically produced equipment rather than relying on imports. The increasing focus on sustainable meat processing solutions in the UK is also shaping regional investments in advanced, energy-efficient technologies.
Market Insights:
- The UK Meat Processing Equipment Market was valued at USD 485.31 million in 2023 and is projected to reach USD 760.56 million by 2032, growing at a CAGR of 5.11% during the forecast period.
- Increasing consumer demand for ready-to-eat, frozen, and convenience meat products is driving investment in advanced processing machinery, supported by the expansion of supermarkets and online retail platforms.
- Adoption of robotic butchering, AI-driven sorting, and IoT-enabled monitoring systems is enhancing efficiency, precision, and compliance with stringent food safety regulations.
- The Food Standards Agency (FSA) enforces strict hygiene and contamination control regulations, pushing manufacturers to invest in high-tech processing and automated cleaning solutions.
- Sustainability concerns are driving the shift towards energy-efficient, waste-reducing, and eco-friendly processing technologies, with government incentives supporting green initiatives.
- High capital investment, ongoing maintenance costs, and Brexit-related supply chain disruptions are key challenges, particularly for small and medium-sized enterprises (SMEs).
- London, the Midlands, and the North West remain dominant regions due to established processing hubs, while the South East and Scotland are emerging as high-growth areas with increasing infrastructure investments.
Market Drivers:
Rising Demand for Processed and Packaged Meat Products
The increasing consumer preference for processed and packaged meat products is a significant driver of the UK Meat Processing Equipment Market. Changing dietary habits, coupled with a fast-paced lifestyle, have led to a growing demand for ready-to-eat, frozen, and convenience meat products. Consumers seek products that offer longer shelf life, easy preparation, and enhanced taste, prompting meat processors to invest in advanced processing machinery. For instance, companies like Deighton Manufacturing UK Ltd specialize in producing innovative food processing equipment, such as forming, coating, and frying systems, to cater to this growing market. The expansion of supermarkets, hypermarkets, and online food retail platforms has also contributed to the growing sales of processed meat, further fueling the need for efficient and high-capacity meat processing equipment.
Technological Advancements and Automation in Meat Processing
The integration of automation and smart technologies in meat processing is reshaping the industry, improving efficiency, precision, and hygiene standards. Innovations such as robotic butchering, AI-driven sorting, and IoT-enabled monitoring systems are revolutionizing meat processing plants, reducing dependency on manual labor and enhancing productivity. Automation minimizes human contact with raw meat, ensuring better hygiene and compliance with stringent food safety regulations. For example, Tyson Foods uses robotic butchering systems to perform precise cuts on meat products, ensuring uniformity and reducing waste. Additionally, advanced equipment with real-time monitoring capabilities enhances traceability, optimizing production lines and reducing operational costs. The incorporation of high-tech machinery also addresses labor shortages by reducing reliance on skilled workers, making automation a key factor driving equipment adoption.
Stringent Food Safety and Hygiene Regulations
The UK's stringent food safety regulations play a crucial role in shaping the meat processing equipment market. Regulatory bodies such as the Food Standards Agency (FSA) impose strict guidelines to ensure hygiene, quality control, and contamination prevention in meat production. Compliance with these regulations necessitates the use of advanced processing equipment that meets international safety standards. For instance, Meat processors are increasingly investing in stainless steel machinery, automated cleaning systems, and antimicrobial surface technologies to maintain food safety and prevent contamination risks. The rising focus on hazard analysis and critical control points (HACCP) compliance and traceability measures further pushes companies to upgrade their equipment, reinforcing the market’s growth.
Sustainability and Energy-Efficient Processing Solutions
The growing emphasis on sustainable and energy-efficient meat processing solutions is another key driver of the UK meat processing equipment market. With increasing concerns over carbon emissions, water usage, and food waste, manufacturers are adopting eco-friendly processing technologies that optimize energy and resource consumption. Equipment innovations, such as low-energy freezing systems, precision portioning machines, and waste-reduction technologies, are becoming integral to modern meat processing plants. For instance, ESB Energy Business Solutions is working with ABP Food Group to implement innovative energy solutions that will drive energy efficiencies, guarantee significant cost savings, and help in reducing carbon footprint. Government incentives and industry initiatives promoting green processing methods further encourage investments in environmentally sustainable meat processing equipment. As sustainability gains traction across the food industry, the demand for resource-efficient and compliant processing machinery continues to rise.
Market Trends:
Growing Adoption of Plant-Based and Alternative Protein Processing
The UK meat processing industry is witnessing a notable shift towards plant-based and alternative protein processing, influencing the demand for adaptable meat processing equipment. As consumer preferences evolve towards meat alternatives, hybrid meat products, and lab-grown proteins, processing facilities are upgrading their machinery to accommodate these new formulations. Traditional meat processing equipment is being modified to handle alternative protein textures, extrusion processes, and specialized packaging requirements. Leading food manufacturers are investing in hybrid production lines that can efficiently process both traditional meat and plant-based alternatives, aligning with the expanding flexitarian consumer base in the UK. For instance, the UK's Naylor Farms has begun constructing a facility that it claims is the first in the world dedicated to extracting brassica protein.
Integration of AI and Data Analytics in Processing Equipment
The integration of artificial intelligence (AI) and data analytics into meat processing equipment is transforming production efficiency and quality control. AI-driven technologies enable predictive maintenance, automated quality assessment, and process optimization, reducing waste and improving operational performance. Real-time data monitoring systems allow manufacturers to enhance traceability, For instance, Völur brings value by applying smart technology to everyday cutting and processing decisions, returning improved margins through inventory availability and operational efficiencies. supply chain transparency, and production consistency, ensuring compliance with evolving regulatory standards. AI-powered vision inspection systems are increasingly being adopted to detect defects, measure portion accuracy, and maintain uniformity in processed meat products, enhancing both quality assurance and yield efficiency.
Rise in Demand for Customized and Modular Equipment Solutions
Customization and modularity in meat processing equipment are gaining traction as manufacturers seek flexible, scalable, and cost-effective solutions. Processing facilities are investing in modular machinery that can be easily reconfigured or expanded to meet changing production demands. For instance, a Dutch company invested in a modular extrusion machine that offers quick changeovers and individualized customization for products ranging from cookie pieces to protein chips. This trend is particularly driven by small and medium-sized meat processors, who require adaptable equipment to cater to diverse product lines without excessive capital expenditure. The ability to integrate interchangeable processing components, automated changeover systems, and specialized cutting or deboning units is becoming a key competitive advantage for equipment manufacturers in the UK market.
Increased Investment in High-Pressure Processing (HPP) and Advanced Preservation Technologies
High-Pressure Processing (HPP) and other advanced meat preservation technologies are gaining momentum as the industry shifts towards extending product shelf life while maintaining food safety and quality. HPP, a non-thermal pasteurization method, is increasingly being adopted to enhance microbial safety while preserving the natural texture and taste of meat products. For instance, JBT Corporation acquired Avure Technologies to enhance its high-pressure processing capabilities. Similarly, the development of ultraviolet (UV) light treatments, modified atmosphere packaging (MAP), and vacuum-sealing advancements is driving innovation in the meat processing equipment sector. These technologies align with consumer demand for minimally processed, preservative-free meat products, encouraging further investments in next-generation preservation systems.
Market Challenges Analysis:
High Initial Investment and Maintenance Costs
One of the primary restraints in the UK Meat Processing Equipment Market is the high initial investment and ongoing maintenance costs associated with advanced machinery. Meat processing equipment, particularly automated and AI-integrated systems, requires substantial capital expenditure, making it challenging for small and medium-sized enterprises (SMEs) to adopt these technologies. Additionally, the cost of maintaining and upgrading these machines is significant, as regular servicing, spare parts replacement, and software updates add to operational expenses. For businesses with limited financial resources, this barrier delays technological advancements, reducing overall industry growth potential.
Regulatory Compliance and Supply Chain Disruptions
Stringent food safety regulations and compliance requirements present another major challenge for meat processing equipment manufacturers and food processors. The UK Food Standards Agency (FSA) and other regulatory bodies impose strict guidelines on hygiene, contamination control, and waste management, necessitating frequent upgrades to processing equipment to meet evolving standards. Compliance with these regulations often requires additional investment in specialized machinery, automated cleaning systems, and traceability solutions, increasing operational complexity. Furthermore, supply chain disruptions, particularly post-Brexit trade policies, have impacted the availability of raw materials, spare parts, and imported equipment. Delays in procurement and increased import tariffs have raised overall costs, making it difficult for companies to maintain seamless production processes. These challenges underscore the need for localized manufacturing solutions and supply chain diversification to mitigate market risks.
Market Opportunities:
The increasing adoption of automation and smart technologies presents a significant growth opportunity in the UK Meat Processing Equipment Market. As food manufacturers seek to enhance efficiency, consistency, and hygiene, there is rising demand for robotic butchering systems, AI-powered sorting mechanisms, and IoT-enabled monitoring solutions. These innovations not only improve production speed and accuracy but also help reduce waste, energy consumption, and labor dependency. Companies investing in data-driven process optimization and predictive maintenance solutions can gain a competitive advantage by enhancing productivity and ensuring regulatory compliance. With labor shortages continuing to affect the industry, automation offers a sustainable path for long-term growth.
The shift towards sustainability and eco-friendly processing solutions is creating new opportunities for manufacturers of energy-efficient and low-emission meat processing equipment. The increasing focus on carbon footprint reduction, water conservation, and waste minimization is driving investments in high-pressure processing (HPP), precision portioning, and resource-efficient packaging technologies. Government incentives and regulatory support for green food processing initiatives further encourage businesses to adopt environmentally sustainable equipment. Companies that develop and market innovative, resource-efficient processing solutions will be well-positioned to capitalize on this growing demand, catering to both large-scale meat processors and emerging plant-based protein manufacturers looking to optimize production efficiency while meeting sustainability goals.
Market Segmentation Analysis:
By Type
The UK Meat Processing Equipment Market is segmented by equipment type, including slicing, bending, dicing, grinding, and massaging & marinating. Among these, slicing and grinding equipment hold a significant share due to their essential role in both large-scale industrial processing and small to mid-sized meat production facilities. The demand for automated and precision-based dicing and marinating machines is rising, driven by increasing consumer preference for marinated and value-added meat products. With advancements in smart processing technologies, manufacturers are integrating AI and IoT-enabled monitoring systems into these machines to enhance efficiency and consistency.
By Meat Type
Based on meat type, the market is categorized into beef, mutton, pork, and others. Beef and pork processing equipment dominate the market due to the high consumption of these meats in the UK. Mutton processing equipment is witnessing steady growth, driven by cultural preferences and increasing demand for premium lamb products. The others category, which includes poultry and alternative proteins, is expanding rapidly as plant-based and hybrid meat processing technologies gain traction.
By Product
The market is further segmented by processed meat products, including fresh processed meat, raw cooked meat, precooked meat, raw fermented sausage, and cured meat. Fresh processed and raw cooked meat segments hold the largest market shares, owing to the high demand for ready-to-cook and minimally processed products. The precooked and cured meat segments are gaining popularity, supported by changing consumer preferences for convenience foods and extended shelf-life products. Technological advancements in high-pressure processing (HPP) and vacuum-sealing equipment are further driving growth in these segments.
Segmentation:
By Type
- Slicing
- Bending
- Dicing
- Grinding
- Massaging & Marinating
By Meat Type
- Beef
- Mutton
- Pork
- Others
By Product
- Fresh processed meat
- Raw cooked meat
- Precooked meat
- Raw fermented sausage
- Cured meat
Regional Analysis:
London and the South East – Market Hub with Advanced Processing Facilities
London and the South East account for the largest share of the UK Meat Processing Equipment Market, contributing approximately 35% of the total market revenue. This dominance is driven by the presence of leading food processing companies, established supply chains, and high consumer demand for processed meat products. The region is home to state-of-the-art meat processing plants and distribution centers, enabling faster production and efficient supply chain management. Additionally, technological advancements in automation and AI-driven meat processing systems are widely adopted in these areas due to strong investment capabilities. The increasing demand for premium processed meat products, including organic and plant-based alternatives, further drives equipment upgrades and modernization.
Midlands – Manufacturing and Distribution Hub
The Midlands region holds a 25% market share, positioning itself as a key center for meat processing and equipment manufacturing. This region benefits from well-developed logistics infrastructure and proximity to major agricultural hubs, ensuring a steady supply of raw materials. The presence of several leading meat processing companies and equipment manufacturers makes the Midlands a significant contributor to the market. Investments in automated deboning, slicing, and packaging solutions are increasing, driven by the need for efficiency and compliance with strict hygiene regulations. Additionally, export-oriented meat processors in this region are adopting advanced technologies to meet international quality standards, further boosting demand for cutting-edge processing equipment.
North West and North East – Expanding Market with Growing Investments
The North West and North East regions together account for approximately 20% of the UK Meat Processing Equipment Market. These regions are witnessing steady expansion in meat processing facilities, supported by increasing investments in food technology innovation and sustainable processing methods. Government initiatives aimed at strengthening local food production and reducing reliance on imports are also driving market growth. The adoption of energy-efficient meat processing solutions is gaining traction, particularly among mid-sized and emerging meat processors looking to optimize production costs. Furthermore, the presence of food science research institutions in these regions is fostering collaborations for the development of advanced meat preservation and processing technologies.
Scotland and Wales – Emerging Markets with High Growth Potential
Scotland and Wales collectively contribute around 15% of the UK Meat Processing Equipment Market, with significant growth potential in specialized and premium meat processing. Scotland, known for its high-quality beef and lamb production, is experiencing increased demand for precision meat cutting, portioning, and packaging solutions to support exports and domestic consumption. Wales, with its focus on local meat production and sustainability, is seeing growing investments in eco-friendly processing technologies, such as high-pressure processing (HPP) and vacuum packaging solutions. The rising demand for organic and free-range meat products in both regions is encouraging meat processors to invest in modern, compliance-focused equipment, driving further market expansion.
Key Player Analysis:
- Mepaco
- Minerva Omega Group s.r.l
- Tomra Systems ASA
- JBT
- Nemco Food Equipment, LTD
- RAM Beef Equipment
- The Middleby Corporation
- Marel
- Equipamientos cárnicos
- S.L. (MAINCA)
- Bettcher Industries, Inc
- Fortifi Food Processing Solutions
- Kason Corporation
Competitive Analysis:
The UK Meat Processing Equipment Market is highly competitive, with a mix of global manufacturers and domestic players striving for market share. Leading companies focus on technological advancements, automation, and energy-efficient solutions to differentiate themselves. Established global brands leverage cutting-edge AI-driven processing systems, robotic automation, and IoT-enabled monitoring solutions to enhance efficiency and maintain compliance with stringent food safety regulations. Domestic manufacturers compete by offering cost-effective, customized, and modular equipment tailored to the specific needs of UK meat processors. For instance, Fortifi Food Processing Solutions, this company acquired LIMA S.A.S., a French company, to enhance protein processing capabilities. Additionally, post-Brexit trade regulations have driven an increasing preference for locally manufactured equipment, reducing reliance on imports. Key players are also investing in sustainability-focused innovations, such as high-pressure processing (HPP) and resource-efficient machinery, to align with the growing demand for eco-friendly solutions. Strategic partnerships, mergers, and acquisitions are shaping the competitive landscape, with companies striving to enhance their market presence and technological capabilities.
Recent Developments:
- In August 2024, Mepaco launched the ETD3000 Electric Tote Dumper, designed for food and operational safety and production efficiency. The electric dumper eliminates the maintenance and inefficiencies associated with hydraulics16. In October 2024, Mepaco announced the opening of its Validation Lab, a research and test facility for the food processing industry.
- In November 2024, Nemco announced key additions to its management team
Market Concentration & Characteristics:
The UK Meat Processing Equipment Market exhibits a moderate to high market concentration, with a mix of global industry leaders and domestic manufacturers competing for market share. A few key players dominate the market, leveraging technological advancements, automation, and compliance-driven innovations to maintain their competitive edge. Large-scale meat processing facilities primarily rely on established multinational companies, while small and medium-sized enterprises (SMEs) seek cost-effective and customized solutions from regional equipment suppliers. The market is characterized by rapid technological innovation, regulatory-driven product development, and increasing automation. Demand for energy-efficient, IoT-enabled, and AI-driven equipment is growing as companies prioritize operational efficiency, sustainability, and food safety compliance. Additionally, rising investments in alternative protein processing and hybrid meat technologies are shaping future market trends. With increasing consumer demand for processed and convenience meat products, the market continues to evolve, driving manufacturers to develop advanced and scalable processing solutions.
Report Coverage:
The research report offers an in-depth analysis based on By Type, By Meat Type and By Product. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increased adoption of robotic automation, AI-driven sorting, and IoT-enabled monitoring systems will enhance efficiency and precision in meat processing.
- Growing emphasis on energy-efficient, water-saving, and waste-reduction technologies will drive innovation in eco-friendly processing solutions.
- Expanding market for plant-based and lab-grown meat will create demand for adaptable processing equipment to accommodate hybrid and alternative protein products.
- Stricter food safety and hygiene regulations will push manufacturers to invest in high-tech, compliance-focused processing solutions.
- Increasing preference for flexible, scalable, and multi-functional processing equipment will cater to diverse product lines and production demands.
- Growth in high-pressure processing (HPP), vacuum packaging, and UV treatment technologies will extend shelf life while maintaining product quality.
- Post-Brexit trade challenges will encourage greater domestic production of meat processing equipment, reducing reliance on imports.
- The shift toward fully automated and data-driven meat processing plants will optimize production efficiency and traceability.
- Rising demand for premium, organic, and convenience-focused meat products will drive equipment innovation for specialized processing.
- Strategic partnerships, acquisitions, and technological collaborations will shape the competitive landscape, fostering innovation and market consolidation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the UK Meat Processing Equipment Market?
What factors are driving the growth of the UK Meat Processing Equipment Market?
What are some challenges faced by the UK Meat Processing Equipment Market?
Who are the major players in the UK Meat Processing Equipment Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Meat Processing Equipment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UK Meat Processing Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 485.31 million → 2032: USD 760.56 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Meat Processing Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Meat Processing Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Meat Processing Equipment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UK Meat Processing Equipment Market Drivers
- 3.3 UK Meat Processing Equipment Market Restraints & Challenges
- 3.4 UK Meat Processing Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Meat Processing Equipment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Meat Processing Equipment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Meat Processing Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Meat Processing Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UK Meat Processing Equipment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UK Meat Processing Equipment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Meat Processing Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UK Meat Processing Equipment Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UK Meat Processing Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Meat Processing Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UK Meat Processing Equipment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UK Meat Processing Equipment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UK Meat Processing Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UK Meat Processing Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UK Meat Processing Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UK Meat Processing Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UK Meat Processing Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UK Meat Processing Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UK Meat Processing Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
