
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. 3D bioprinting Market Size 2023 | USD 437.36 million |
| U.S. 3D bioprinting Market, CAGR | 12.51% |
| U.S. 3D bioprinting Market Size 2032 | USD 1,263.24 million |
Market Overview:
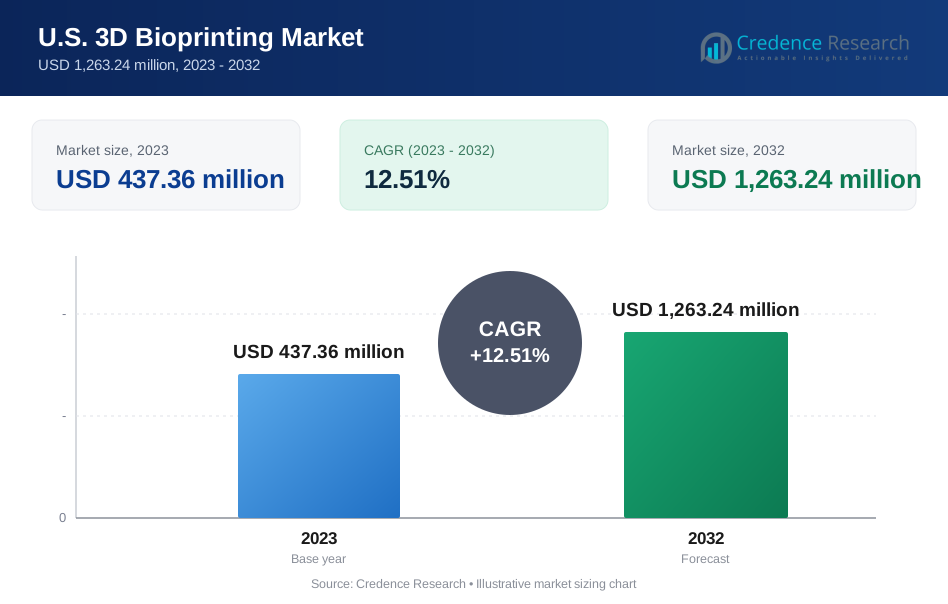
U.S. 3D bioprinting Market size was valued at USD 437.36 million in 2023 and is anticipated to reach USD 1,263.24 million by 2032, at a CAGR of 12.51% during the forecast period (2023-2032).
Several key factors are propelling the growth of the 3D bioprinting market in the United States. The increasing prevalence of chronic diseases and an aging population are driving the need for innovative medical solutions. Additionally, the shortage of organ donors has intensified interest in tissue engineering and regenerative medicine. Technological advancements in bioprinting, such as improved bioinks and printing precision, are enhancing the viability and functionality of printed tissues and organs. Moreover, substantial investments in research and development by both public and private sectors are accelerating innovation and application of 3D bioprinting technologies. Furthermore, the growing focus on personalized medicine and the potential for customized treatments are further fueling market expansion.
The United States stands at the forefront of the global 3D bioprinting market, accounting for a significant share of the market revenue. This leadership is attributed to the country's advanced healthcare infrastructure, substantial R&D investments, and the presence of leading bioprinting companies. The convergence of academic institutions, research organizations, and industry players fosters a collaborative environment conducive to technological advancements. Furthermore, favorable regulatory frameworks and funding mechanisms support the commercialization and adoption of 3D bioprinting solutions across various medical applications. The U.S. government's increasing support for innovation in bioprinting technologies, coupled with the region’s expertise in biomedical engineering, reinforces its dominance in the market.
Market Insights:
- The U.S. 3D bioprinting market was valued at USD 437.36 million in 2023 and is projected to reach USD 1,263.24 million by 2032, growing at a CAGR of 12.51%.
- The global 3D bioprinting market was valued at USD 1,500.00 million in 2023 and is projected to reach USD 4,295.25 million by 2032, growing at a CAGR of 12.4% during the forecast period (2023-2032).
- The increasing prevalence of chronic diseases, such as diabetes and cardiovascular diseases, is driving demand for advanced medical solutions, with bioprinting offering a way to create complex tissues for treatment and research.
- Continuous technological advancements in bioprinting, including the development of improved bioinks and more precise printing techniques, are enhancing the viability and functionality of printed tissues and organs.
- The shortage of organ donors in the U.S. is intensifying interest in bioprinting as a solution for tissue engineering and organ replacement, offering potential for addressing the organ transplant gap.
- The U.S. government's supportive regulatory environment and funding initiatives are accelerating the development and commercialization of bioprinting technologies, fostering innovation and collaboration in the sector.
- Despite the potential, high costs of bioprinting systems and materials remain a significant barrier to widespread adoption, particularly for smaller healthcare institutions and research labs.
- Regulatory and ethical concerns, along with the technical challenges of creating fully functional organs, are limiting the immediate potential of 3D bioprinting in clinical applications, though advancements continue to address these obstacles.
Report scope
This report segments the U.S. 3D bioprinting Market as follow: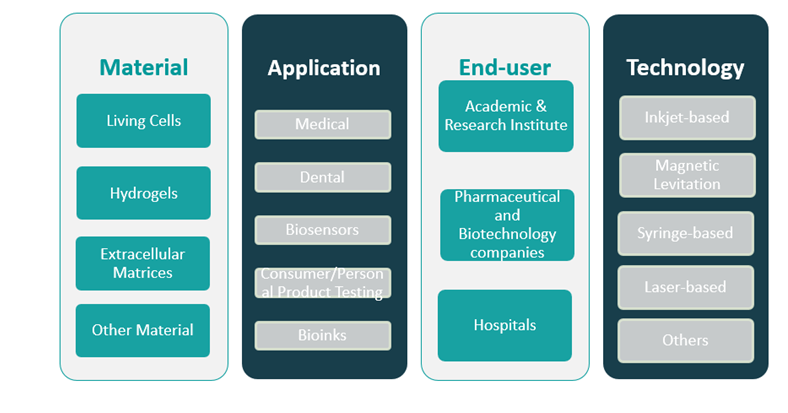
Market Drivers:
Increasing Healthcare Needs and Chronic Disease Prevalence
The increasing prevalence of chronic diseases in the U.S. is one of the primary drivers of the 3D bioprinting market. Conditions such as cardiovascular diseases, diabetes, and cancer continue to rise, creating a demand for more advanced and personalized healthcare solutions. For instance, the University of Texas at El Paso (UTEP) received a $1.2 million grant from the National Institutes of Health (NIH) to use 3D bioprinting for modeling diabetes-related heart problems, specifically studying how type 2 diabetes affects cardiac tissue function and drug response. Bioprinting offers the potential to revolutionize the way these diseases are treated, enabling the creation of complex tissues that could be used for disease modeling, drug testing, and even personalized treatment strategies. This growing healthcare need supports the advancement of 3D bioprinting technologies, fueling their adoption in medical research and clinical applications.
Technological Advancements in Bioprinting
Another key driver for the U.S. 3D bioprinting market is the continuous technological advancements in bioprinting technologies. For example, volumetric bioprinting and microfluidic-based techniques now allow for the creation of tissue constructs with resolutions down to tens of micrometers, closely mimicking the finest features of human tissue microarchitecture. Significant improvements in the precision and resolution of bioprinting techniques have made it possible to print more complex tissue structures with better functionality. The development of advanced bioinks—materials that can mimic the properties of human cells and tissues—has also enhanced the viability of printed tissues for medical applications. These advancements are not only improving the quality of printed tissues and organs but also expanding the potential applications of bioprinting in regenerative medicine, drug development, and organ transplantation.
Shortage of Organ Donors
The shortage of organ donors remains a significant challenge in the U.S. healthcare system, driving demand for alternative solutions like 3D bioprinting. The National Organ Transplant Act (NOTA) has long recognized the need for more organ donations, but the number of available organs continues to fall short of demand. 3D bioprinting offers a promising solution by enabling the printing of functional tissues and organs that could one day help address the shortage. Although it is still in the early stages of development, the ability to print organs for transplantation or create tissue for regenerative treatments holds the potential to transform the field of medicine and alleviate the burden on the organ transplant system.
Supportive Regulatory Environment and Government Initiatives
The U.S. government's supportive regulatory environment and funding initiatives are essential drivers of the 3D bioprinting market. Agencies such as the U.S. Food and Drug Administration (FDA) are working closely with bioprinting companies to establish clear guidelines for the development and approval of bioprinted tissues and organs. In addition, federal funding for bioprinting research and development is increasing, supporting innovation in this field. The growing recognition of bioprinting's potential by regulatory bodies and policymakers has paved the way for advancements in bioprinting technologies, providing the market with the necessary resources and frameworks to flourish. Government initiatives also encourage public-private partnerships, fostering collaboration between research institutions, universities, and industry players to accelerate the commercialization of bioprinting applications.
Market Trends:
Expansion in Bioprinting Applications
One of the most significant trends driving the U.S. 3D bioprinting market is the expansion of its applications across various medical fields. While initially limited to research and academic institutions, 3D bioprinting is now being explored in a wide range of medical applications, from drug discovery and testing to tissue regeneration and personalized medicine. Increasingly, bioprinting is being used to create patient-specific models, which can be utilized in preclinical trials and surgical planning. As the technology matures, its potential to revolutionize medical treatments continues to grow, with more hospitals and pharmaceutical companies investing in 3D bioprinting to enhance healthcare outcomes.
Rise of Personalized Medicine
Personalized medicine is another growing trend in the U.S. 3D bioprinting market. There is a significant shift toward treatments tailored to individual genetic profiles, which is made possible by advances in 3D bioprinting. The ability to print tissues or organ structures based on a patient's specific needs allows for more targeted therapies and reduced risks of rejection or complications. For instance, Brinter has developed modular 3D printing platforms that print patient-specific tumor models, allowing for personalized drug testing in cancer treatment. Personalized bioprinted tissues also enable more accurate testing of drugs on human-like tissues, leading to better drug efficacy and safety profiles. This trend is expected to increase demand for bioprinting solutions, particularly in the fields of cancer treatment, regenerative medicine, and genetic therapies.
Technological Integration with Other Innovations
The integration of 3D bioprinting with other cutting-edge technologies is a key trend within the U.S. market. These integrations include the use of artificial intelligence (AI), machine learning, and robotics to optimize printing precision and enhance the creation of functional tissue structures. AI is being employed to design and simulate complex tissue architectures, improving the overall quality and functionality of bioprinted tissues. For example, AI-driven generative design is helping companies like Prellis Biologics create vascularized tissue models for drug discovery, improving tissue viability by optimizing nutrient and oxygen delivery. Robotics are being used to automate the printing process, ensuring higher throughput and precision, which is crucial for clinical applications. These innovations are driving the development of bioprinting technologies, making them more efficient, scalable, and adaptable to various medical needs.
Growth of Public-Private Partnerships and Funding
Another important trend in the U.S. 3D bioprinting market is the increasing involvement of public-private partnerships and the growth of investment in this sector. Federal agencies such as the National Institutes of Health (NIH) and the Department of Defense (DoD) are providing funding to support the development of bioprinting technologies, particularly for applications in tissue engineering and organ regeneration. Additionally, venture capital and private equity investment are on the rise, as both large pharmaceutical companies and startup ventures recognize the long-term potential of 3D bioprinting. This trend of collaboration and investment is accelerating the pace of innovation and commercialization, driving further growth in the market.
Market Challenges Analysis:
High Costs of Technology and Implementation
One of the primary restraints in the U.S. 3D bioprinting market is the high cost associated with the technology and its implementation. Bioprinting systems, materials such as bioinks, and specialized equipment required for creating tissues and organs are expensive, which limits accessibility, especially for smaller research institutions and healthcare providers. Additionally, the complexity of maintaining and operating these systems increases operational costs, making widespread adoption a challenge. The high upfront investment required for both developing and implementing these technologies can delay the scalability of bioprinting solutions in clinical settings.
Regulatory and Ethical Concerns
Regulatory hurdles and ethical concerns also pose significant challenges to the growth of the U.S. 3D bioprinting market. The approval process for bioprinted tissues and organs is still in its infancy, with agencies like the U.S. Food and Drug Administration (FDA) working to establish clear guidelines. This lack of standardized regulations creates uncertainty for companies operating in the space. For instance, the FDA’s draft framework does not yet specify how regulations will be applied to point-of-care 3D printing facilities or clarify the risk classification of bioprinted products. Ethical concerns surrounding the creation of human tissues and organs, particularly with regard to potential misuse or unintended consequences, further complicate the development and adoption of 3D bioprinting technologies. These issues need to be addressed before bioprinting can fully realize its potential in healthcare.
Technical Limitations in Bioprinting Complexity
Despite advancements, the complexity of printing fully functional organs remains a significant challenge. Current bioprinting technologies are limited by their ability to accurately replicate the intricate structures and functionalities of human tissues and organs. While improvements in bioinks and printing techniques have enabled the production of simpler tissues, the ability to print complex, vascularized organs that can fully integrate with the human body is still an ongoing challenge. Until these technical limitations are overcome, the application of 3D bioprinting in organ transplantation and advanced regenerative medicine will remain limited.
Market Opportunities:
The U.S. 3D bioprinting market presents significant opportunities driven by the growing demand for personalized medicine and tissue engineering. The ability to create patient-specific models for drug testing, disease modeling, and personalized treatments provides a substantial market opportunity. As the technology advances, it can potentially eliminate the need for animal testing by offering more accurate human tissue models for research. This is particularly important for pharmaceutical companies, as it enables the development of more effective drugs with fewer side effects. Additionally, the growing shift toward regenerative medicine and organ transplantation opens doors for bioprinting technologies to create complex tissue structures for transplants, which could address the ongoing organ donor shortage.
Another promising opportunity lies in the collaboration between healthcare providers, research institutions, and biotechnology companies. With the increasing investments in research and development from both the public and private sectors, there is a clear path for the commercialization of 3D bioprinting solutions. Additionally, advancements in bioinks and printing techniques are paving the way for more complex and functional tissues, thereby expanding the scope of bioprinting applications in fields such as oncology, cardiovascular diseases, and neurological disorders. As healthcare providers seek innovative ways to deliver better outcomes, the adoption of 3D bioprinting as a tool for creating customized medical solutions is expected to increase significantly, fostering new market growth and opportunities for innovation.
Market Segmentation Analysis:
The U.S. 3D bioprinting market is segmented based on material, application, end-user, and technology, each contributing to the growth and expansion of the market.
By Material
The material segment is led by living cells, hydrogels, and extracellular matrices, all of which are integral to creating functional tissues and organs. Living cells are critical for replicating human tissues, while hydrogels provide a supportive environment for cell growth and extracellular matrices help mimic the natural biological scaffolding of tissues. Other materials include biocompatible polymers and composite materials, used for structural and functional support in bioprinting. These materials are essential in applications such as regenerative medicine and drug development.
By Application
The applications of 3D bioprinting span across medical, dental, biosensors, consumer/personal product testing, and bioinks. The medical sector remains the dominant application, with 3D bioprinting being used for tissue engineering, organ modeling, and drug testing. In the dental field, bioprinting is employed for creating customized implants and prosthetics. The use of bioprinting in biosensors and consumer products is growing, with companies leveraging the technology for product testing and development. Bioinks, a vital component for bioprinting, are also an emerging application as they enhance tissue and organ printing capabilities.
By End-User
End-users in the U.S. 3D bioprinting market include academic & research institutes, pharmaceutical and biotechnology companies, and hospitals. Academic institutions drive innovation through research, while pharmaceutical companies adopt bioprinting technologies for drug discovery and personalized treatments. Hospitals are exploring bioprinting for patient-specific treatments and organ modeling.
By Technology
The technology segment includes inkjet-based, magnetic levitation, syringe-based, and laser-based bioprinting. Inkjet-based technology is widely used due to its ability to print precise layers of materials, while syringe-based and laser-based technologies offer more control over the printing process. Magnetic levitation techniques are an emerging trend, offering the potential to create complex tissue structures without the need for scaffolding.
Segmentation:
By Material:
- Living Cells
- Hydrogels
- Extracellular Matrices
- Other Material
By Application:
- Medical
- Dental
- Biosensors
- Consumer/Personal Product Testing
- Bioinks
By End-User:
- Academic & Research Institute
- Pharmaceutical and Biotechnology Companies
- Hospitals
By Technology:
- Inkjet-based
- Magnetic Levitation
- Syringe-based
- Laser-based
- Others
Regional Analysis:
The U.S. 3D bioprinting market is primarily driven by strong technological advancements, substantial healthcare investments, and a robust research ecosystem. The regional landscape is characterized by distinct contributions from different states and institutions, which collectively shape the growth of the market.
Northeast Region
The Northeast region, particularly states like Massachusetts, New York, and Pennsylvania, holds a significant share of the U.S. 3D bioprinting market, accounting for approximately 35% of the total market share. This is primarily due to the presence of world-renowned academic institutions and research hubs such as Harvard University, MIT, and major pharmaceutical companies like Pfizer. The region’s focus on biotechnology and medical research, along with strong government funding, fosters the development of 3D bioprinting technologies, especially in the fields of tissue engineering, drug testing, and personalized medicine. Additionally, the concentration of venture capital investment in the Northeast accelerates the commercialization of bioprinting solutions.
West Coast Region
The West Coast, particularly California, Oregon, and Washington, is another major contributor to the U.S. 3D bioprinting market, accounting for approximately 30% of the market share. The region is home to a thriving biotechnology industry, driven by leading companies such as Organovo, which has pioneered 3D bioprinting in medical research. California’s extensive healthcare infrastructure and strong support for research and development in regenerative medicine make it a vital hub for 3D bioprinting innovation. The West Coast also benefits from collaboration between tech giants and bioprinting startups, integrating artificial intelligence (AI) and machine learning with bioprinting technologies.
Midwest and South Regions
The Midwest and South regions hold smaller but significant shares of the U.S. 3D bioprinting market, accounting for approximately 20% and 15%, respectively. The Midwest, with major medical centers like the Mayo Clinic in Minnesota, has strong growth potential in the field of medical applications, particularly in personalized medicine and organ modeling. The South, including Texas, Florida, and Georgia, sees steady growth driven by healthcare and biotechnology firms, as well as research institutions focusing on medical device manufacturing and tissue engineering. Additionally, Texas is home to several bioprinting startups, fueling regional innovation.
Key Player Analysis:
- Envisiontec, Inc
- Organovo
- Inventia Life Science Pty Ltd
- POIETIS
- VIVAX BIO, LLC
- ALLEVI
- Cyfuse Biomedical K.K.
- 3D Bioprinting Solutions
- CELLINK GLOBAL
- REGEMAT 3D S.L
Competitive Analysis:
The U.S. 3D bioprinting market is highly competitive, with several key players leading technological innovation and market adoption. Prominent companies like Organovo, 3D Systems, and Stratasys are at the forefront, offering advanced bioprinting platforms for medical research, drug development, and tissue engineering. Organovo is known for its pioneering work in creating functional human tissues, while 3D Systems and Stratasys have established themselves with versatile 3D printing solutions applicable across various industries, including healthcare. Additionally, startups such as BioBots and Allevi are gaining attention with their cost-effective and accessible 3D bioprinting solutions, enabling smaller research labs and academic institutions to adopt the technology. These companies are heavily investing in research and development to enhance the accuracy, scalability, and functionality of bioprinted tissues and organs. The competitive landscape is further shaped by partnerships, collaborations, and increasing venture capital funding, accelerating technological advancements and market growth.
Recent Developments:
- In March 2025, CELLINK, a leading US-based 3D bioprinting company and part of BICO Group, announced a strategic partnership with DKSH to expand access to its advanced bioprinting solutions in China. This collaboration leverages DKSH’s extensive sales and service network to strengthen CELLINK’s market presence and accelerate biomedical research in the region, reflecting the company’s ongoing commitment to global expansion and innovation in 3D bioprinting.
- In June 2024, Tethon 3D, a US developer specializing in ceramic and metal-polymer products, launched its first bioprinter, the Bison Bio DLP 3D bioprinter. Developed in collaboration with Carima, this new product features adjustable build sizes and compatibility with proprietary bioinks, positioning it to facilitate the creation of complex tissues and organs for biomedical research and personalized medicine. The Bison Bio aims to support advancements in healthcare by enabling more precise and efficient bioprinting processes.
Market Concentration & Characteristics:
The U.S. 3D bioprinting market is characterized by moderate concentration, with a few dominant players holding significant market shares while several emerging companies are driving innovation. Established leaders like Organovo, 3D Systems, and Stratasys hold a substantial portion of the market due to their advanced technologies, extensive patents, and strategic partnerships with academic institutions and research organizations. These companies focus on high-end, specialized bioprinting solutions for medical applications such as tissue engineering and regenerative medicine. At the same time, the market is becoming increasingly dynamic, with a growing number of startups such as Allevi and BioBots offering more affordable and accessible bioprinting solutions. This trend is expanding market access to smaller research labs and academic institutions, promoting greater diversity in product offerings. The market is characterized by ongoing technological advancements, regulatory uncertainties, and an increasing focus on collaborations and strategic alliances.
Report Coverage:
The research report offers an in-depth analysis based on Material, Application, End-User and Technology. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The U.S. 3D bioprinting market is expected to see continued strong growth, driven by advancements in bioprinting technologies and increasing healthcare applications.
- Personalized medicine will play a pivotal role, with 3D bioprinting enabling customized treatments for individual patients.
- The demand for regenerative medicine and organ transplantation will increase as bioprinting technologies improve tissue and organ creation capabilities.
- Investment in research and development by both private companies and government agencies will accelerate the pace of innovation.
- Collaborations between biotech firms, research institutions, and universities will foster breakthroughs in 3D bioprinting applications.
- The regulatory environment will gradually become clearer, enabling faster commercialization of bioprinted medical solutions.
- Cost reduction in bioprinting materials and equipment will make the technology more accessible to a broader range of medical professionals and researchers.
- Adoption of AI and machine learning in bioprinting processes will enhance precision and speed in tissue creation.
- Startups and smaller firms will drive competition, offering innovative and cost-effective solutions to expand market reach.
- Over the next decade, the 3D bioprinting market in the U.S. will become increasingly integrated into mainstream healthcare, especially in drug testing and personalized therapies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. 3D bioprinting Market?
What factors are driving the growth of the U.S. 3D bioprinting Market?
What are the key segments within the U.S. 3D bioprinting Market?
Who are the major players in the U.S. 3D bioprinting Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. 3D Bioprinting Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global U.S. 3D Bioprinting Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 437.36 million → 2032: USD 1,263.24 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. 3D Bioprinting Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. 3D Bioprinting Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. 3D Bioprinting Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 U.S. 3D Bioprinting Market Drivers
- 3.3 U.S. 3D Bioprinting Market Restraints & Challenges
- 3.4 U.S. 3D Bioprinting Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. 3D Bioprinting Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. 3D Bioprinting Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. 3D Bioprinting category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. 3D Bioprinting Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. U.S. 3D Bioprinting Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the U.S. 3D Bioprinting market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. 3D Bioprinting Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 U.S. 3D Bioprinting Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 U.S. 3D Bioprinting Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. 3D Bioprinting (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New U.S. 3D Bioprinting Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global U.S. 3D Bioprinting Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America U.S. 3D Bioprinting Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe U.S. 3D Bioprinting Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific U.S. 3D Bioprinting Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America U.S. 3D Bioprinting Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East U.S. 3D Bioprinting Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa U.S. 3D Bioprinting Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. U.S. 3D Bioprinting Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
