
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
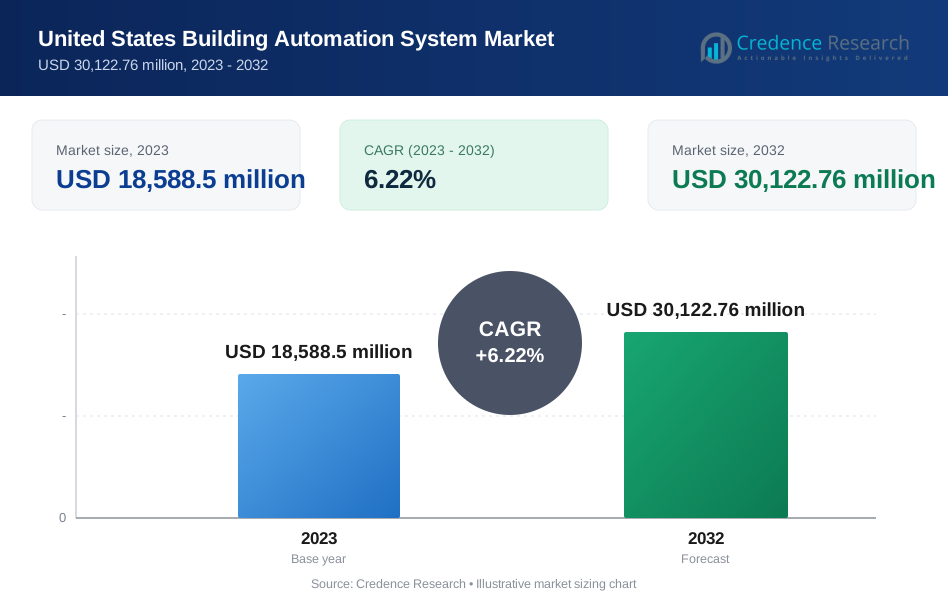
| United States Building Automation System Market Size 2023 | USD 18,588.5 Million |
| United States Building Automation System Market, CAGR | 6.22% |
| United States Building Automation System Market Size 2032 | USD 30,122.76 Million |
Market Overview
The United States Building Automation System market is projected to grow from USD 18,588.5 million in 2023 to an estimated USD 30,122.76 million by 2032, with a compound annual growth rate (CAGR) of 6.22% from 2024 to 2032. This significant growth reflects the increasing adoption of smart building technologies aimed at improving energy efficiency, enhancing security, and optimizing building operations. The expansion is driven by rising investments in infrastructure modernization and the increasing need for intelligent solutions to manage complex building systems more effectively.
Key drivers propelling the market include the growing emphasis on energy conservation and the demand for cost-effective, efficient building management solutions. Trends such as the integration of Internet of Things (IoT) technologies, advanced analytics, and artificial intelligence (AI) are transforming the landscape, making building automation systems more intelligent and responsive. The push for green buildings and sustainable construction practices further boosts the market, as automated systems play a crucial role in achieving energy efficiency and regulatory compliance.
Geographically, the market sees robust growth across various states, with significant contributions from regions like California, Texas, and New York, where large-scale commercial and residential projects are prevalent. Key players dominating the U.S. market include Honeywell International Inc., Johnson Controls International plc, Siemens AG, Schneider Electric SE, and United Technologies Corporation. These companies are continually innovating and expanding their product portfolios to cater to the evolving needs of the market, ensuring a competitive edge in this rapidly growing sector.
Market Drivers
Increasing Demand for Energy Efficiency
The growing emphasis on energy efficiency is a primary driver for the United States Building Automation System (BAS) market. For instance, with energy costs rising by an average of 3% per year, there is a substantial push from both government and private sectors to reduce energy consumption. Building automation systems are designed to optimize the use of energy in buildings by managing heating, ventilation, air conditioning (HVAC), lighting, and other systems more efficiently. These systems utilize sensors, controllers, and software to monitor and adjust energy usage in real-time, significantly reducing wastage. The implementation of BAS helps in achieving substantial energy savings, making buildings more sustainable and cost-effective to operate. Moreover, stringent energy regulations and policies at federal and state levels further propel the adoption of energy-efficient technologies, thereby boosting the market for building automation systems.
Advancements in IoT and AI Technologies
Technological advancements, particularly in the Internet of Things (IoT) and Artificial Intelligence (AI), are significantly driving the growth of the BAS market in the United States. For instance, a modern smart building can have over 5,000 IoT-connected devices. IoT enables the interconnectivity of various devices and systems within a building, allowing for seamless communication and data exchange. This interconnectedness allows building automation systems to gather and analyze vast amounts of data, leading to more informed decision-making and proactive management of building operations. AI, on the other hand, brings advanced analytics and machine learning capabilities to the table, enhancing the predictive maintenance and fault detection functionalities of BAS. These technologies collectively enable smarter, more responsive, and adaptive building management solutions that can predict and respond to occupants' needs and environmental changes, thereby improving overall operational efficiency and user comfort.
Rising Awareness and Adoption of Smart Building Solutions
The increasing awareness and adoption of smart building solutions are contributing significantly to the expansion of the BAS market. For instance, a survey showed that 70% of property owners and facility managers are considering implementing smart building solutions. Property owners and facility managers are becoming more cognizant of the benefits offered by building automation systems, such as improved operational efficiency, enhanced security, and better occupant comfort. Smart buildings, equipped with advanced BAS, can automatically adjust lighting, temperature, and other environmental factors based on occupancy and usage patterns, leading to improved energy efficiency and reduced operational costs. The growing trend towards smart cities and the integration of smart technologies in urban planning also play a crucial role in driving the demand for building automation systems. The shift towards smart buildings is further fueled by the competitive advantage they offer in terms of property value, tenant attraction, and regulatory compliance.
Government Initiatives and Incentives
Government initiatives and incentives aimed at promoting energy efficiency and sustainable building practices are major drivers of the BAS market in the United States. Federal and state governments offer various programs and incentives to encourage the adoption of energy-efficient technologies and practices. These include tax credits, rebates, grants, and other financial incentives for implementing building automation systems. Additionally, government regulations and standards, such as the Energy Policy Act and the Leadership in Energy and Environmental Design (LEED) certification, set stringent requirements for energy efficiency and sustainability in buildings. Compliance with these regulations often necessitates the integration of advanced BAS, driving market growth. Furthermore, government initiatives promoting smart city developments and infrastructure modernization projects also contribute to the increased adoption of building automation systems.
Market Trends
Integration of IoT and Smart Devices
One of the most prominent trends in the United States Building Automation System (BAS) market is the integration of Internet of Things (IoT) and smart devices. For instance, a modern smart building can have over 5,000 IoT-connected devices. Building systems are increasingly being interconnected through IoT, enabling seamless communication and data exchange. This integration allows for real-time monitoring and control of building functions, enhancing efficiency and responsiveness. Smart sensors and devices collect and transmit data, which is then analyzed to optimize building operations, reduce energy consumption, and improve occupant comfort.
Adoption of Artificial Intelligence and Machine Learning
The adoption of artificial intelligence (AI) and machine learning (ML) in BAS is transforming how buildings are managed. AI and ML algorithms can analyze vast amounts of data from various building systems to identify patterns and predict future performance. For example, AI-driven predictive maintenance can reduce downtime by up to 20% and extend the lifespan of equipment by up to 15%. Additionally, AI-driven analytics help in optimizing energy use by learning and adapting to the building’s operational patterns and occupant behaviors, leading to significant cost savings and enhanced sustainability.
Focus on Energy Efficiency and Sustainability
Energy efficiency and sustainability remain at the forefront of current trends in the BAS market. With increasing awareness of environmental issues and stringent regulations, there is a growing emphasis on creating energy-efficient buildings. For instance, a well-implemented BAS can reduce a building’s energy consumption by up to 30%. BAS solutions are designed to monitor and control energy usage, ensuring optimal performance of HVAC, lighting, and other systems. The trend towards green buildings and sustainable construction practices is driving the adoption of BAS, as these systems play a critical role in achieving energy efficiency and meeting regulatory requirements.
Rise of Smart Buildings and Smart Cities
The rise of smart buildings and smart cities is another significant trend impacting the BAS market. Smart buildings leverage advanced technologies such as IoT, AI, and cloud computing to enhance building operations, security, and occupant experience. These buildings are designed to be highly efficient, adaptive, and responsive to the needs of occupants. The trend towards smart cities, which integrate smart buildings into a larger urban ecosystem, further accelerates the adoption of BAS. In smart cities, buildings are interconnected and communicate with city infrastructure, enhancing overall urban efficiency and sustainability.
Increasing Use of Cloud-Based Solutions
Cloud-based solutions are gaining traction in the BAS market, offering greater flexibility, scalability, and accessibility. Cloud platforms enable centralized monitoring and control of multiple buildings from a single interface, facilitating efficient management of large building portfolios. These solutions also support remote access and real-time data analytics, allowing facility managers to make informed decisions and respond quickly to issues. The shift towards cloud-based BAS is driven by the need for cost-effective, scalable, and easily deployable solutions that can adapt to the dynamic requirements of modern buildings.
Enhanced Security and Cybersecurity Measures
As building systems become more interconnected and reliant on digital technologies, the importance of cybersecurity in BAS has increased significantly. Ensuring the security of BAS is crucial to protect against cyber threats and potential disruptions. Current trends include the implementation of robust cybersecurity measures, such as encryption, multi-factor authentication, and regular security updates, to safeguard building systems. Enhanced security features are also being integrated into BAS to protect physical assets and ensure the safety of occupants.
Emphasis on User Experience and Occupant Comfort
Improving user experience and occupant comfort is a growing trend in the BAS market. Modern BAS solutions are designed to create a comfortable and productive environment for occupants by automatically adjusting lighting, temperature, and ventilation based on real-time data and occupancy patterns. Advanced BAS also provide personalized control options, allowing occupants to customize their environment according to their preferences. This focus on occupant comfort not only enhances user satisfaction but also contributes to the overall efficiency and effectiveness of building operations.
Market Restraints and Challenges
High Initial Investment Costs
One of the primary restraints in the United States Building Automation System (BAS) market is the high initial investment required for installation and integration. Building automation systems involve significant upfront costs, including purchasing advanced equipment, installing hardware, and integrating software solutions. For many building owners and facility managers, especially those managing smaller or older buildings, these costs can be prohibitive. The financial burden is further compounded by the need for specialized labor to install and maintain these systems. Although the long-term savings and efficiency gains can be substantial, the initial capital expenditure remains a significant barrier to widespread adoption.
Complexity of Integration with Existing Infrastructure
Integrating BAS with existing building infrastructure presents another major challenge. Many buildings, especially older ones, have legacy systems that are not easily compatible with modern automation technologies. Retrofitting these buildings with new BAS can be complex and costly, requiring significant modifications to existing structures and systems. This complexity often leads to extended project timelines and increased costs, discouraging building owners from pursuing automation upgrades. Additionally, the lack of standardization in BAS technologies can complicate integration efforts, as different systems and devices may not seamlessly communicate with each other.
Cybersecurity Concerns
As BAS increasingly rely on interconnected devices and internet connectivity, cybersecurity has become a critical concern. The growing threat of cyberattacks poses significant risks to the integrity and functionality of building automation systems. Unauthorized access to BAS can lead to operational disruptions, data breaches, and potential physical harm to occupants. Ensuring robust cybersecurity measures involves continuous monitoring, regular updates, and the implementation of advanced security protocols, all of which add to the operational complexity and cost. The potential for cyber vulnerabilities can deter some organizations from fully embracing BAS technologies, fearing the associated risks and challenges.
Limited Skilled Workforce
The shortage of skilled professionals capable of designing, installing, and maintaining advanced BAS is another key restraint in the market. Building automation requires expertise in various disciplines, including information technology, engineering, and facility management. The current workforce lacks sufficient numbers of trained individuals with the necessary skills to support the growing demand for BAS implementation. This skill gap can lead to delays in project execution, increased labor costs, and potential issues with system performance and reliability. Training and developing a skilled workforce is essential to overcoming this challenge, but it requires time and investment from both the industry and educational institutions.
Regulatory and Compliance Challenges
Navigating the complex landscape of regulatory and compliance requirements is a significant challenge for the BAS market. Various federal, state, and local regulations govern building standards, energy efficiency, and safety protocols, which can vary widely. Compliance with these regulations often necessitates additional documentation, inspections, and modifications to BAS, increasing the administrative burden and costs for building owners. Keeping abreast of evolving regulatory requirements and ensuring that BAS installations meet all necessary standards can be a daunting task, particularly for smaller organizations with limited resources.
Market Segmentation Analysis
By Component
The hardware segment includes controllers, sensors, actuators, and other physical components essential for building automation systems. This segment holds a significant share of the market due to the necessity of physical devices to implement and manage automation functions. The demand for advanced hardware that offers greater precision and reliability is driving growth in this segment. The software segment comprises platforms and applications used to manage and control building automation systems. This segment is experiencing rapid growth due to advancements in software technologies, such as AI and machine learning, which enhance system capabilities. Cloud-based software solutions are particularly gaining traction for their scalability and remote management features.
By Application
HVAC control systems are crucial for maintaining optimal indoor climate conditions. This segment is a major contributor to the BAS market, driven by the need for energy-efficient heating, ventilation, and air conditioning solutions. Advanced HVAC systems improve occupant comfort and reduce energy consumption, making them a key focus area. Lighting control systems manage the use of artificial lighting based on occupancy and natural light availability. This segment is growing as businesses and homeowners seek to reduce energy costs and enhance lighting quality. Automated lighting systems are integral to smart building strategies and sustainability efforts. Electronic Security & Safety includes systems such as access control, surveillance, and fire safety. The increasing need for enhanced security and compliance with safety regulations drives the demand for sophisticated electronic security and safety systems. Integration with other BAS components further boosts market growth in this segment. BEMS are designed to monitor and manage a building's energy use. This segment is growing rapidly due to the emphasis on energy efficiency and sustainability. BEMS provide actionable insights to optimize energy consumption, making them essential for modern building management.
By Communication Technology
Wired communication technologies, such as Ethernet and BACnet, offer reliable and secure data transmission for building automation systems. This segment remains dominant due to its stability and resistance to interference, which is critical for essential building functions. Wireless technologies, including Wi-Fi, Zigbee, and Bluetooth, are increasingly popular due to their flexibility and ease of installation. This segment is expanding as the demand for retrofitting existing buildings with minimal disruption grows. Wireless solutions also facilitate the integration of IoT devices. Other segment includes emerging communication technologies that offer innovative solutions for building automation. Technologies like power line communication and proprietary protocols fall into this category, catering to specific needs and niche applications within the BAS market.
By End-user
The commercial segment, including offices, retail spaces, and educational institutions, is a major market driver. The demand for efficient building operations, reduced energy costs, and enhanced occupant comfort propels the adoption of BAS in commercial buildings. Industrial facilities use BAS to optimize production processes, ensure safety, and reduce energy consumption. This segment is growing as industries seek to improve operational efficiency and comply with stringent environmental regulations. The residential segment is witnessing significant growth due to the rising popularity of smart homes. Homeowners are increasingly adopting BAS for improved energy management, security, and convenience, driving market expansion in this segment.
By Sales Channel
Direct sales channels involve selling BAS directly to end-users through company sales teams. This channel is preferred for large-scale projects where tailored solutions and comprehensive support are required. Channel sales involve intermediaries such as distributors, integrators, and resellers. This channel is essential for reaching a broader customer base and providing localized support, especially for small and medium-sized installations.
Segments
Based on Component
- Hardware
- Software
Based on Application
- HVAC Control Systems
- Lighting Control Systems
- Electronic Security & Safety
- Building Energy Management Systems (BEMS)
Based on Communication Technology
- Wire
- Wireless
- Others
Based on End-user
- Commercial
- Industrial
- Residential
Based on Sales Channel
- Direct
- Channel
Based on Region
- Northeast
- Midwest
- South
- West
Regional Analysis
Northeast Region (25%):
The Northeast region, encompassing states like New York, New Jersey, and Massachusetts, holds a significant share of the United States Building Automation System (BAS) market, accounting for approximately 25% of the market. This region is characterized by a high density of commercial and institutional buildings, including office complexes, educational institutions, and healthcare facilities. The stringent energy efficiency regulations and the drive towards sustainable building practices in states like New York are major factors contributing to the adoption of BAS. The emphasis on reducing energy consumption and operational costs propels the demand for advanced building automation solutions in this region. Additionally, the presence of numerous historical buildings being retrofitted with modern BAS technologies further boosts the market.
South Region (30%):
The South region, comprising states such as Texas, Florida, and Georgia, holds a substantial share of approximately 30% of the BAS market. This region is experiencing rapid urbanization and significant growth in construction activities, both in residential and commercial sectors. The warm climate in the South necessitates efficient HVAC control systems, making BAS essential for managing energy consumption and maintaining indoor comfort. The rise of smart city initiatives and the construction of new commercial buildings and high-tech campuses in states like Texas drive the adoption of BAS. Additionally, the region's economic growth and investment in infrastructure projects further fuel market expansion.
Key players
- Honeywell International Inc.
- Johnson Controls International plc
- Siemens AG
- Schneider Electric SE
- United Technologies Corporation
- ABB Ltd.
- Emerson Electric Co.
- General Electric Company
- Legrand SA
- Cisco Systems, Inc.
Competitive Analysis
The United States Building Automation System market is highly competitive, with major players like Honeywell International Inc., Johnson Controls International plc, Siemens AG, and Schneider Electric SE leading the industry. These companies dominate the market by leveraging their extensive portfolios, strong brand recognition, and innovative technologies. They invest significantly in research and development to introduce advanced BAS solutions incorporating IoT, AI, and cloud computing. United Technologies Corporation and ABB Ltd. also maintain substantial market shares through their comprehensive automation solutions and global reach. Emerson Electric Co. and General Electric Company focus on industrial automation, enhancing their competitive edge. Legrand SA and Cisco Systems, Inc. contribute with their expertise in electrical and network infrastructure, respectively. The competitive landscape is marked by strategic partnerships, mergers, and acquisitions aimed at expanding product offerings and enhancing technological capabilities to meet the growing demand for smart building solutions.
Recent Developments
In September 2023, Johnson Controls, a global leader in intelligent, health-conscious, and eco-friendly buildings, launched its latest offering: OpenBlue Service. This service ensures the performance of security devices, aiming to enhance building safety, reduce risks, and maximize the value of security technology investments. OpenBlue Service integrates Johnson Controls' suite of interconnected solutions, allowing for the management and control of security devices from various manufacturers. It includes remote support services, expert insights, and a robust zero-trust cybersecurity system, providing a comprehensive solution for building security and efficiency.
In May 2023, Carrier announced the release of i-Vu Pro v8.5, the latest software for its i-Vu building automation system. This software introduces a staged download approach for controller firmware upgrades, improving serviceability for customers. Unlike traditional downloads that disrupt HVAC equipment operation throughout the process, the new staged method divides the download into distinct phases, minimizing downtime. This advancement ensures continuous operation of connected HVAC systems, enhancing customer experience and system reliability.
In March 2023, Honeywell introduced an innovative fire alarm system featuring UL-approved self-testing smoke detectors. These detectors can perform automatic testing, revolutionizing the installation, testing, and maintenance of fire and life safety systems. This breakthrough simplifies procedures, reduces manual testing requirements, and ensures consistent safety standards. Honeywell's self-testing smoke detectors enhance overall system reliability and provide a more efficient solution for fire safety management.
In March 2023, Siemens unveiled the Connect Box, an accessible and open IoT solution designed for managing small to medium-sized buildings. Part of the Siemens Xcelerator portfolio, the Connect Box offers a user-friendly method for monitoring building performance. It aims to improve energy efficiency by up to 30% and enhance indoor air quality. This solution is ideal for establishments such as schools, retail shops, apartments, and small offices, providing an effective and scalable option for building management.
Market Concentration and Characteristics
The United States Building Automation System (BAS) market is characterized by a moderate to high market concentration, with several key players such as Honeywell International Inc., Johnson Controls International plc, Siemens AG, and Schneider Electric SE dominating the industry. These leading companies leverage their extensive technological capabilities, robust product portfolios, and strong market presence to maintain a competitive edge. The market is defined by continuous innovation, driven by advancements in IoT, AI, and cloud computing, which enhance system integration, efficiency, and functionality. Additionally, the market exhibits a trend towards sustainability and energy efficiency, with increasing adoption of smart building solutions across commercial, industrial, and residential sectors. The competitive landscape is further shaped by strategic partnerships, mergers, and acquisitions, aiming to expand product offerings and technological expertise to meet the evolving demands of modern building management.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, Communication Technology, End-user, Sales Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The BAS market will see increased adoption of smart technologies, driven by advancements in IoT and AI, enhancing system interconnectivity and operational efficiency.
- Demand for energy management solutions will rise, as building owners seek to reduce energy consumption and comply with stringent energy efficiency regulations.
- Cloud-based BAS solutions will gain popularity due to their scalability, remote management capabilities, and cost-effectiveness, providing flexibility for diverse building management needs.
- The emphasis on cybersecurity will intensify, with more robust measures being integrated into BAS to protect against cyber threats and ensure system integrity.
- Smart city initiatives will drive BAS adoption, as urban planners and developers incorporate advanced automation systems into city infrastructure to improve overall urban efficiency and sustainability.
- Retrofit projects in older buildings will grow, as owners upgrade existing infrastructure with modern BAS to improve efficiency, reduce costs, and enhance occupant comfort.
- The focus on sustainability will lead to greater implementation of BAS in green buildings, aligning with global environmental goals and regulatory requirements.
- AI and machine learning technologies will advance, providing more predictive and adaptive BAS solutions that can proactively manage building systems and optimize performance.
- The residential sector will see increased BAS adoption, driven by the growing popularity of smart homes and the desire for enhanced security, energy efficiency, and convenience.
- Collaboration between BAS providers and technology companies will foster innovation, leading to the development of more integrated, user-friendly, and efficient building automation solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the United States Building Automation System (BAS) market?
What are the primary drivers fueling the BAS market growth in the United States?
Which regions contribute significantly to the growth of the BAS market in the United States?
Who are the major players in the United States BAS market?
What are the recent developments in the BAS industry?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 18,588.5 million → 2032: USD 30,122.76 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 United States Building Automation System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 United States Building Automation System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 United States Building Automation System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 United States Building Automation System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 United States Building Automation System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 United States Building Automation System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 United States Building Automation System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 United States Building Automation System Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 18,588.5 million → 2032: USD 30,122.76 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 United States Building Automation System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 United States Building Automation System Geographic Market Outlook, 2023-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 United States Building Automation System Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 United States Building Automation System Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
