
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
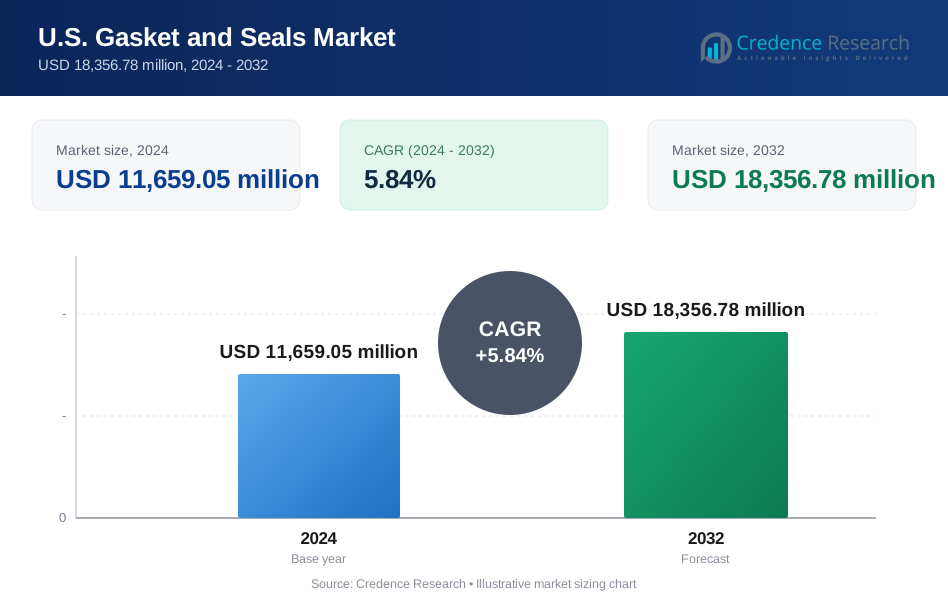
| U.S. Gasket and Seals Market Size 2024 | USD 11,659.05 million |
| U.S. Gasket and Seals Market, CAGR | 5.84% |
| U.S. Gasket and Seals Market Size 2032 | USD 18,356.78 million |
Market Overview
The U.S. Gasket and Seals Market is projected to grow from USD 11,659.05 million in 2024 to an estimated USD 18,356.78 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.84% from 2025 to 2032. This growth is attributed to the increasing demand for gaskets and seals across various end-use industries, including automotive, aerospace, and manufacturing.
Key drivers of the market include the rising demand for high-performance sealing solutions, stringent environmental regulations necessitating efficient sealing technologies, and the growth of end-user industries requiring reliable sealing products. Additionally, the trend towards automation and the development of advanced manufacturing processes are fueling the adoption of sophisticated gasket and seal solutions.
Geographically, the market is predominantly driven by regions with a strong industrial presence, including the Midwest and South, where manufacturing activities are concentrated. Key players such as SKF Group, Parker Hannifin Corporation, and Trelleborg AB are actively contributing to market growth through strategic partnerships, product innovations, and expanding their manufacturing capabilities within the U.S.
Market Insights
- The U.S. Gasket and Seals Market is projected to grow from USD 11,659.05 million in 2024 to USD 18,356.78 million by 2032, with a CAGR of 5.84% from 2025 to 2032.
- Increasing demand for high-performance sealing solutions across industries like automotive, aerospace, and manufacturing is fueling market growth.
- Innovations in sealing materials and smart sealing technologies are enhancing product performance and longevity, driving further market adoption.
- Stricter environmental and safety regulations are pushing industries to adopt more efficient and eco-friendly sealing solutions.
- Rising raw material costs and potential supply chain disruptions pose challenges for manufacturers in maintaining competitive pricing.
- The Midwest and South regions dominate the U.S. market, driven by strong automotive, aerospace, and energy sectors.
- Major companies such as SKF Group, Parker Hannifin, and Trelleborg AB are expanding their market presence through product innovations and strategic partnerships.
Market Drivers
Stringent Environmental and Safety Regulations
Environmental and safety concerns are becoming more stringent, particularly in industries such as oil and gas, automotive, and chemicals. As regulations become more rigorous, there is an increasing demand for gaskets and seals that meet these standards. For example, gaskets used in automotive and industrial applications must comply with the latest emission control standards, while those in the oil and gas sector must ensure leak prevention to avoid harmful environmental contamination. The growing need for sealing solutions that are capable of withstanding extreme environmental conditions, including high pressures, temperatures, and exposure to hazardous chemicals, is propelling the demand for advanced gaskets and seals. Additionally, there is a heightened focus on reducing waste and ensuring that products are environmentally friendly. As a result, manufacturers are increasingly turning to sustainable sealing solutions made from biodegradable or recyclable materials, which are expected to continue gaining traction in response to regulatory pressures. Moreover, the growing focus on sustainability within the manufacturing sector is promoting the development of gaskets and seals that help improve energy efficiency and reduce carbon footprints. This has become a critical consideration for industries working toward meeting environmental targets, driving the demand for sealing technologies that help achieve these goals.
Increase in Automation and Industry 4.0 Integration
The ongoing trend of automation in industrial processes and the rise of Industry 4.0 is significantly influencing the U.S. gasket and seals market. As more industries adopt automated systems, there is a growing need for sealing solutions that can operate efficiently in automated environments, ensuring system reliability and performance. Automation not only reduces the risk of human error but also enhances operational efficiency, which requires components like gaskets and seals to perform under more demanding conditions.Industry 4.0 technologies, including smart sensors, robotics, and data analytics, are transforming manufacturing and other industrial sectors. Seals and gaskets that can integrate with these technologies, offering real-time monitoring of conditions such as pressure, temperature, and chemical exposure, are increasingly in demand. This smart sealing capability provides businesses with insights that can lead to better maintenance schedules, fewer failures, and extended product lifecycles. Consequently, the integration of seals and gaskets with automation and digital technologies is driving the market as manufacturers seek to incorporate these solutions into their operations for improved performance and reliability.
Growing Demand Across End-Use Industries
The rising demand for gaskets and seals across diverse end-use industries is a major factor driving the U.S. gasket and seals market. The automotive sector plays a pivotal role in this growth, as modern vehicles increasingly require advanced sealing solutions for components like engines, fuel systems, and HVAC systems. For instance, the growing trend toward fuel-efficient vehicles has led to innovations in sealing technologies that enhance engine performance and prevent leaks. Similarly, the aerospace industry demands lightweight and high-temperature-resistant gaskets to improve fuel efficiency and reduce emissions. Other industries such as oil and gas, manufacturing, and power generation also rely heavily on gaskets and seals for critical equipment like pumps, valves, and machinery. These components are essential for ensuring operational safety and efficiency by minimizing leaks and maintaining system integrity. For instance, the oil and gas sector’s need for reliable sealing solutions in harsh environments has driven the adoption of advanced materials that can withstand extreme pressures and temperatures. As these industries continue to grow, particularly with a focus on sustainability and energy efficiency, the demand for high-performance sealing products is expected to accelerate further.
Technological Advancements and Innovation in Materials
Continuous innovation in materials and sealing technologies is another key driver of growth in the U.S. gasket and seals market. Traditional sealing solutions have evolved significantly to meet the demands of applications requiring resistance to high temperatures, pressures, and chemicals. For instance, advancements in material science have enabled the development of gaskets made from PTFE, elastomers, and composites that offer superior durability and reliability. These innovations extend the lifecycle of critical equipment while reducing maintenance costs. Additionally, emerging technologies such as 3D printing are revolutionizing gasket design by enabling manufacturers to produce highly customized solutions tailored to specific industry needs. For instance, 3D printing allows for intricate designs that optimize fluid flow or enhance system efficiency. Smart sealing solutions equipped with IoT capabilities are also gaining traction, providing real-time monitoring to predict maintenance needs and minimize downtime. These technological advancements not only improve operational efficiency but also align with industry trends toward sustainability by incorporating eco-friendly materials like biodegradable rubber. As industries increasingly adopthese innovative solutions, the market is poised for robust growth.
Market Trends
Shift Towards High-Performance Materials
A significant trend in the U.S. gasket and seals market is the shift toward high-performance materials, which are being increasingly used to meet the growing demands of modern industries. Traditional gasket and seal materials such as rubber and metals are being replaced or supplemented by advanced composites and engineered materials, including fluoropolymers and metal composites. These materials offer superior resistance to high temperatures, aggressive chemicals, and extreme pressures, making them ideal for industries such as oil and gas, automotive, aerospace, and chemical manufacturing. The growing demand for durability and longevity in sealing solutions is driving this trend. For instance, in the automotive sector, the use of high-performance seals helps meet the increasing pressure for fuel efficiency, as well as the need for components that can withstand higher temperatures and harsher operating conditions. In the aerospace industry, seals made from advanced composites are gaining popularity due to their light weight, excellent sealing properties, and resistance to extreme environmental conditions. This shift ensures lower maintenance costs and reduced downtime, which are crucial in sectors that rely heavily on continuous operations. As a result, manufacturers are increasingly investing in research and development to create new sealing solutions that can cater to the demanding needs of industrial applications.
Growth of Smart Seals and Integration with IoT
Another prominent trend in the U.S. gasket and seals market is the development and adoption of smart seals that integrate with the Internet of Things (IoT) and other digital technologies. These smart sealing solutions are equipped with sensors that enable real-time monitoring of various parameters such as pressure, temperature, and chemical exposure. This technology helps companies detect potential issues before they result in equipment failure, reducing the risk of leaks, improving reliability, and increasing operational efficiency. Smart seals are being increasingly used in critical applications such as in the oil and gas, aerospace, and chemical processing industries, where maintaining operational integrity is crucial. By integrating with digital systems, these seals offer the ability to monitor conditions remotely, thereby enabling predictive maintenance. For instance, companies like Trelleborg Sealing Solutions are developing smart seal technologies that can monitor performance in real-time, allowing for proactive maintenance strategies. This trend reflects the broader industrial shift towards more connected, intelligent, and efficient systems. As companies strive to enhance their operational performance, the demand for smart seals with integrated IoT capabilities is expected to continue growing.
Sustainability and Eco-Friendly Solutions
Sustainability is becoming a key focus in the U.S. gasket and seals market, as industries strive to reduce their environmental impact. There is a growing demand for eco-friendly sealing solutions that are made from biodegradable, recyclable, or non-toxic materials. This trend is particularly evident in sectors like automotive, packaging, and manufacturing, where there is an increasing push toward environmentally responsible products. The automotive industry, for example, is adopting more sustainable sealing materials to meet environmental regulations related to fuel efficiency and emissions. Gaskets and seals made from bio-based polymers, elastomers, and thermoplastics are becoming more popular as manufacturers seek to reduce their carbon footprint. Similarly, in the chemical and pharmaceutical industries, there is a demand for seals that not only perform well but are also compliant with stringent environmental and safety standards. This trend is also influenced by consumer preferences, as more companies are aligning their product offerings with environmental values. Manufacturers in the gasket and seals market are responding by investing in research and development of sustainable materials, including the use of recycled content and the development of seals that are easier to recycle or dispose of at the end of their life cycle. Furthermore, regulatory bodies are enforcing stricter environmental standards, which is compelling industries to choose sealing solutions that align with these regulations. As sustainability becomes a priority across industries, the demand for eco-friendly gaskets and seals is expected to continue to grow, driving innovation and new product development in the market.
Customization and Specialized Gasket Solutions
The demand for customized and specialized gasket solutions is another significant trend in the U.S. market. As industries become more diverse and applications more complex, there is an increasing need for sealing solutions that cater to specific operational conditions. Custom gaskets and seals are designed to meet the unique requirements of each application, such as sealing in extreme temperatures, harsh chemicals, or high-pressure environments. This trend is particularly noticeable in industries like aerospace, automotive, and energy, where the cost of equipment failure is high, and precision is crucial. Manufacturers are increasingly focusing on providing tailored sealing solutions that are designed to fit the specific needs of individual clients. For instance, seals used in the aerospace industry may require certifications for extreme temperatures and pressure conditions, while those used in the automotive sector may need to be lightweight yet durable for fuel-efficient vehicles. The growing need for specialized gasket solutions is driving advancements in manufacturing technologies, such as 3D printing and additive manufacturing. These technologies allow for the rapid production of custom seals with complex geometries and materials that are difficult to achieve using traditional manufacturing methods. As industries demand more precision and performance, the customization trend is expected to continue shaping the market.
Market Challenges
Rising Raw Material Costs and Supply Chain Disruptions
One of the key challenges facing the U.S. gasket and seals market is the rising cost of raw materials. The production of high-quality gaskets and seals often requires specialized materials such as elastomers, metals, and advanced composites, which have seen price increases in recent years due to global supply chain disruptions and inflation. The availability of raw materials is subject to fluctuations in international markets, and any supply chain disruptions can result in delays and higher production costs for gasket and seal manufacturers. For instance, data from industry surveys indicate that manufacturers have experienced significant volatility in raw material prices, particularly for rubber and metal components. These rising material costs can strain profit margins, especially for manufacturers that operate in highly competitive markets. Moreover, companies may face challenges in passing these cost increases onto customers due to price sensitivity, particularly in price-driven industries like automotive and manufacturing. The pressure to maintain competitive pricing while dealing with higher input costs may force manufacturers to adopt cost-cutting measures, which could affect product quality or innovation. Additionally, companies may need to invest in inventory management strategies to mitigate supply chain disruptions, further adding to operational complexities. For instance, government authority surveys have shown that a substantial number of gasket and seal manufacturers have reported increased lead times for raw materials and components, leading to production delays and inventory challenges. This has prompted many companies to reassess their supply chain strategies, with some opting for diversification of suppliers or exploring alternative materials. The ongoing global economic uncertainties and geopolitical tensions have further exacerbated these challenges, making it difficult for manufacturers to accurately forecast demand and plan production schedules. As a result, the industry has seen a trend towards increased collaboration between suppliers and manufacturers to enhance supply chain resilience and mitigate the impact of raw material cost fluctuations.
Meeting Stringent Regulatory Standards
Another significant challenge in the U.S. gasket and seals market is the need to comply with increasingly stringent environmental and safety regulations. As industries face growing pressure from both regulatory authorities and consumers to reduce their environmental footprint, gasket and seal manufacturers must ensure their products meet various safety, performance, and environmental standards. This includes compliance with regulations regarding emissions, waste reduction, and the use of non-toxic materials in applications such as automotive, chemical processing, and food manufacturing. Adhering to these regulations often requires substantial investment in research and development to create sealing solutions that are both efficient and environmentally friendly. Manufacturers must also stay updated with evolving regulations, which can vary significantly between industries and regions. Non-compliance could result in legal repercussions, reputational damage, or the need for costly product recalls, all of which can negatively impact the financial health of businesses operating in the gasket and seals market. This regulatory complexity adds a layer of operational difficulty and is a continual challenge for market players seeking to maintain product standards while meeting the demands of their customers and regulators.
Market Opportunities
Expansion of the Electric Vehicle (EV) Market
The growing adoption of electric vehicles (EVs) presents a significant market opportunity for the U.S. gasket and seals market. As the automotive industry shifts toward electric mobility, the demand for advanced sealing solutions is expected to rise. EVs require highly specialized gaskets and seals to address unique challenges such as sealing battery compartments, electric drive units, and high-voltage connectors. The need for enhanced sealing technologies that ensure the safety, durability, and energy efficiency of electric vehicles is opening new avenues for growth in the gasket and seals sector. Manufacturers can capitalize on this opportunity by developing customized sealing solutions that meet the stringent requirements of the EV market, including resistance to heat, vibration, and exposure to various chemicals used in batteries and electronic components.
Growth in Renewable Energy and Industrial Applications
Another key market opportunity lies in the growing demand for gasket and seal solutions in the renewable energy and industrial sectors. As industries increasingly focus on sustainability, the expansion of renewable energy sources such as wind, solar, and hydropower is driving the need for sealing solutions that can withstand extreme environmental conditions. Gaskets and seals are essential for ensuring the integrity of wind turbines, solar panels, and other renewable energy equipment. Additionally, with the increasing automation and industrial digitization (Industry 4.0), manufacturers require sealing solutions that offer superior performance in high-pressure, high-temperature, and chemically demanding environments. This trend provides opportunities for gasket and seal suppliers to develop products tailored to the evolving needs of these expanding industries.
Market Segmentation Analysis
By Product
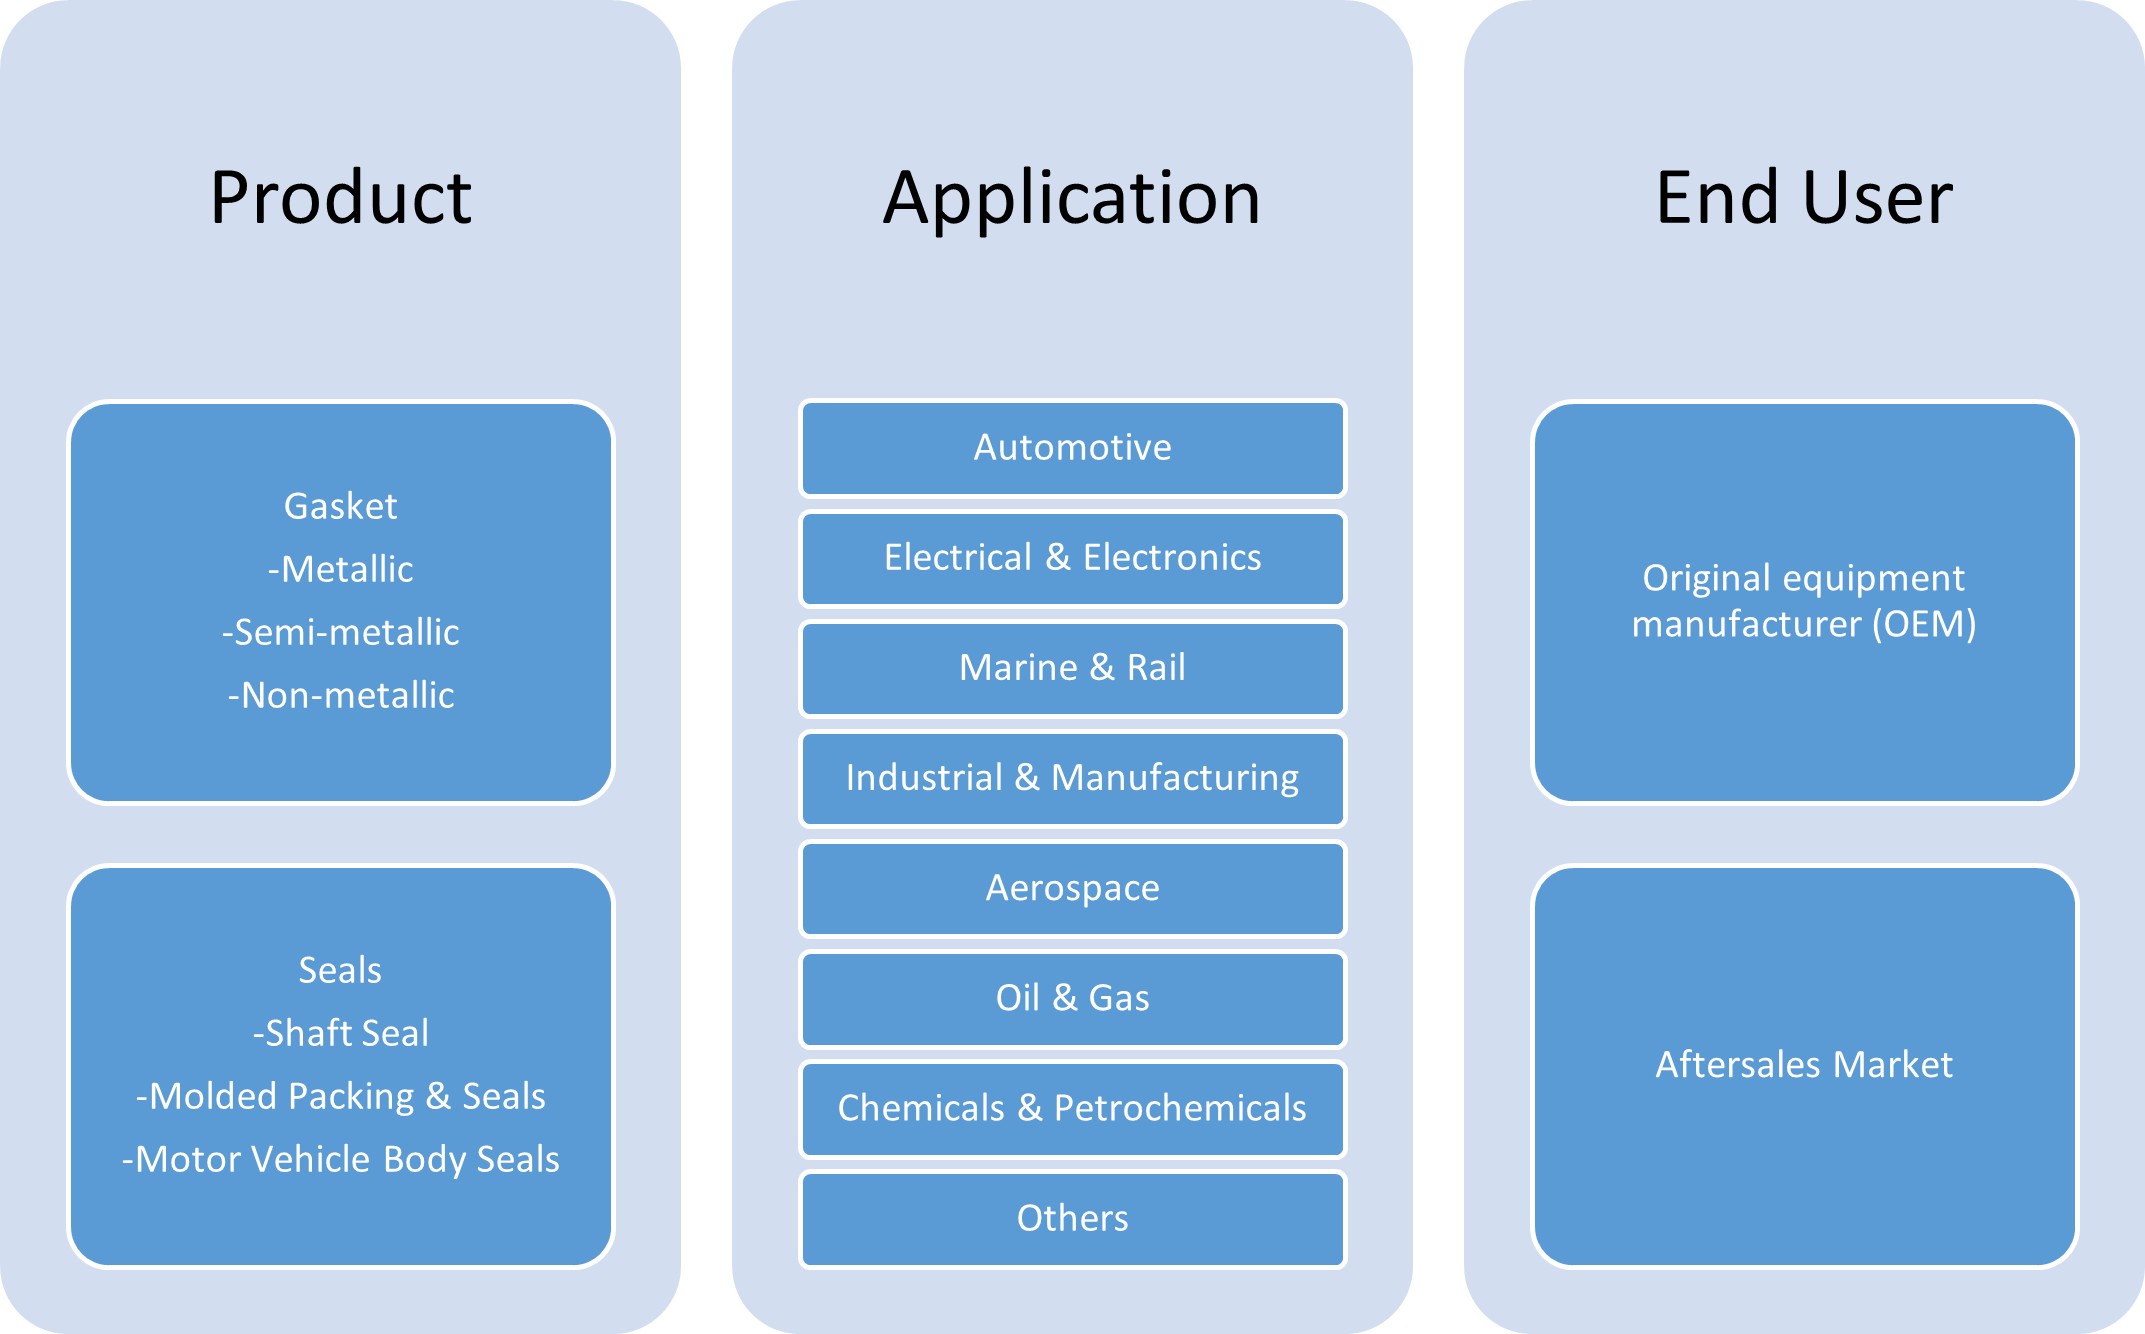
The U.S. gasket and seals market is primarily segmented into gaskets and seals, each further classified based on material types and applications. Gaskets include metallic, semi-metallic, and non-metallic variations. Metallic gaskets are designed for high-temperature and high-pressure environments such as automotive and aerospace industries, offering exceptional strength and chemical resistance. Semi-metallic gaskets combine both metallic and non-metallic materials, providing enhanced sealing capabilities for moderate pressure and temperature conditions, and are commonly used in industrial applications. Non-metallic gaskets, made from rubber, plastic, or elastomers, are preferred for applications requiring flexibility and resilience, such as automotive, chemical, and plumbing industries. Seals in the market are divided into shaft seals, molded packing & seals, and motor vehicle body seals. Shaft seals are crucial for preventing leaks and safeguarding machinery in rotating shafts, vital in automotive, manufacturing, and industrial applications. Molded packing & seals offer tight seals around joints, valves, and pipe connections, ensuring leak prevention in industrial and automotive applications. Motor vehicle body seals are used in automotive body components to prevent leaks, provide soundproofing, and enhance insulation, contributing to vehicle comfort and efficiency.
By Application
The gasket and seals market serves a wide range of industries, each requiring tailored sealing solutions to meet specific operational demands. In the automotive sector, gaskets and seals are essential for engines, fuel systems, and other critical components, driven by the increasing demand for durable and high-performance sealing solutions. In electrical and electronics, seals are used to protect against moisture, dust, and heat, with significant demand in consumer electronics and electric vehicles. Marine and rail applications require sealing solutions to prevent water ingress and maintain structural integrity in challenging environments like ships and trains. In the industrial and manufacturing sectors, seals and gaskets are necessary for machinery, valves, pumps, and compressors, particularly in oil and gas, chemicals, and food processing industries. The aerospace industry demands high-performance seals that can withstand extreme conditions such as high altitudes and temperature fluctuations. The oil and gas sector relies heavily on seals and gaskets for leak prevention and safety in equipment exposed to high pressures and hazardous chemicals. Chemical and petrochemical industries use seals to prevent harmful substance leakage and maintain the integrity of processing systems. The others category includes specialized industries like healthcare, where sealing solutions are vital in ensuring sterility and protection in medical devices.
Segments
Based on Product
- Gasket\
- Metallic
- Semi-metallic
- Non-metallic\
- Seals
- Shaft Seal\
- Molded Packing & Seals\
- Motor Vehicle Body Seal
Based on Application
- Automotive
- Electrical & Electronics
- Marine & Rail
- Industrial & Manufacturing
- Aerospace
- Oil & Gas
- Chemicals & Petrochemicals
- Others
Based on End User
- Original equipment manufacturer (OEM)
- Aftersales Market
Based on Region
- Midwest Region
- South Region
- West Region
- Northeast Region
Regional Analysis
Midwest Region (35%)
The Midwest holds the largest share of the U.S. gasket and seals market, accounting for approximately 35% of the total market. This is largely due to the region’s strong industrial base, particularly in automotive manufacturing, machinery production, and aerospace. Major manufacturing hubs like Michigan, Ohio, and Indiana play a pivotal role in the demand for gaskets and seals. The automotive industry in Detroit, as well as the aerospace sector in Ohio and Illinois, drive a substantial portion of gasket and seal usage. Additionally, the Midwest is home to a high concentration of oil and gas facilities, contributing to the demand for sealing solutions in both industrial and energy-related applications.
South Region (30%)
The South accounts for roughly 30% of the market share. This region has experienced significant industrial growth, especially in oil and gas, chemicals, and petrochemicals, particularly in Texas, Louisiana, and other Gulf Coast states. The demand for gaskets and seals in the energy sector, including oil refineries, pipelines, and offshore platforms, is a key factor driving market growth. Additionally, states like Georgia and Alabama are seeing an increase in automotive and manufacturing industries, further boosting the demand for sealing solutions in industrial and automotive applications.
Key players
- Flexitallic
- Garlock Sealing Technologies
- John Crane
- Dana Incorporated (Victor Reinz)
- APEX Sealing Solutions
Competitive Analysis
The U.S. gasket and seals market is highly competitive, with established players such as Flexitallic, Garlock Sealing Technologies, John Crane, Dana Incorporated (Victor Reinz), and APEX Sealing Solutions dominating the landscape. These companies offer a diverse range of sealing solutions that cater to multiple industries, including automotive, aerospace, oil and gas, and manufacturing. Flexitallic stands out for its innovative sealing technologies and strong presence in the industrial and energy sectors. Garlock Sealing Technologies is known for its advanced materials and seals, particularly in the chemical and petrochemical industries. John Crane offers high-performance sealing solutions for critical applications, with a focus on reliability and durability. Dana Incorporated (Victor Reinz) is a key player in the automotive sector, providing sealing solutions for engine components and other vehicle parts. Lastly, APEX Sealing Solutions differentiates itself with specialized sealing products that cater to niche markets such as pharmaceuticals and food processing. Overall, these players compete by offering tailored solutions, enhancing their R&D capabilities, and expanding their product portfolios to meet the evolving needs of customers across industries.
Recent Developments
- On February 12, 2025, SKF India Limited's Board of Directors approved the appointment of Ms. Surbhi Srivastava, Head of People Experience, to the Senior Management Team. Ms. Srivastava holds a Bachelor of Science from Fergusson College and an MBA from Symbiosis Institute of Business Management, Pune, with over 20 years of experience across various industries.
- In May 2024, Trelleborg announced plans to invest in a new production facility in Casablanca, Morocco, dedicated to aerospace sealing solutions. Construction commenced prior to January 2025, with operations expected to begin by the end of 2025.
- In November 2023, Freudenberg Sealing Technologies reported that sales of its Simriz perfluoroelastomeric (FFKM) compounds had more than doubled in North America over the preceding 24 months. This surge was attributed to the compounds' quality, performance, and availability during supply chain disruptions.
- On May 2, 2023, The Yokohama Rubber Co., Ltd. completed the acquisition of all outstanding shares of Trelleborg Wheel Systems Holding AB, expanding its presence in the off-highway tire sector.
Market Concentration and Characteristics
The U.S. gasket and seals market exhibits moderate market concentration, with a mix of large, established players and smaller, specialized companies. Major players like Flexitallic, Garlock Sealing Technologies, and John Crane dominate the market, leveraging their strong brand presence, extensive product portfolios, and advanced technological capabilities to maintain competitive advantages. However, the market also includes several smaller firms that cater to niche industries and offer customized sealing solutions. This competitive landscape is characterized by continuous innovation, with companies focusing on high-performance materials, smart sealing technologies, and sustainability. The demand for specialized, high-quality sealing products, particularly in sectors like automotive, aerospace, and oil and gas, drives market dynamics, while regulatory compliance and technological advancements further influence market characteristics.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The increasing adoption of electric vehicles is expected to drive significant demand for specialized gaskets and seals, particularly in battery compartments and electric drivetrains, creating new opportunities for market growth.
- Ongoing technological innovations, such as smart seals with IoT integration, will enhance the performance of sealing solutions, offering predictive maintenance and improved reliability across industries.
- The growing emphasis on sustainability will lead to higher demand for eco-friendly and recyclable sealing materials, pushing manufacturers to innovate in developing sustainable, high-performance products.
- With the rise of renewable energy sources like wind and solar, the need for gaskets and seals in energy equipment such as turbines and solar panels will significantly grow, fostering market opportunities.
- As industries continue to adopt automation and Industry 4.0 technologies, the demand for advanced sealing solutions capable of withstanding high pressure, temperature, and chemical exposure will rise.
- The aerospace and defense sectors will continue to demand high-performance sealing solutions for critical applications such as aircraft engines and fuel systems, contributing to market expansion.
- Stricter environmental regulations will drive the demand for high-quality sealing products that meet increasingly stringent safety and sustainability standards, especially in sectors like automotive and chemicals.
- The trend toward customization and specialized sealing solutions for industries such as medical devices, pharmaceuticals, and food processing will present substantial growth opportunities for manufacturers catering to niche markets.
- The oil and gas industry will continue to be a major contributor to the gasket and seals market, particularly for sealing solutions in exploration, extraction, and refining processes in harsh conditions.
- Regions like the South and West, driven by strong automotive, oil and gas, and renewable energy industries, will see increased demand for sealing solutions, contributing significantly to the overall market growth in the U.S.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the U.S. Gasket and Seals Market in 2023 and 2032?
What are the key drivers of the U.S. Gasket and Seals Market?
How do technological advancements impact the gasket and seals market?
Who are the key players in the U.S. Gasket and Seals Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Gasket and Seals Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global U.S. Gasket and Seals Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 11,659.05 million → 2032: USD 18,356.78 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Gasket and Seals Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Gasket and Seals Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Gasket and Seals Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 U.S. Gasket and Seals Market Drivers
- 3.3 U.S. Gasket and Seals Market Restraints & Challenges
- 3.4 U.S. Gasket and Seals Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Gasket and Seals Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Gasket and Seals Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Gasket and Seals category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Gasket and Seals Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. U.S. Gasket and Seals Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the U.S. Gasket and Seals market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Gasket and Seals Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 U.S. Gasket and Seals Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 U.S. Gasket and Seals Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Gasket and Seals (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New U.S. Gasket and Seals Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global U.S. Gasket and Seals Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America U.S. Gasket and Seals Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe U.S. Gasket and Seals Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific U.S. Gasket and Seals Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America U.S. Gasket and Seals Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East U.S. Gasket and Seals Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa U.S. Gasket and Seals Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. U.S. Gasket and Seals Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
