
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Mining Simulation Software Market Size 2023 | USD 728.94 million |
| U.S. Mining Simulation Software Market, CAGR | 8.7% |
| U.S. Mining Simulation Software Market Size 2032 | USD 1,544.92 million |
Market Overview:
U.S. Mining Simulation Software Market size was valued at USD 728.94 million in 2023 and is anticipated to reach USD 1,544.92 million by 2032, at a CAGR of 8.7% during the forecast period (2023-2032).
The U.S. mining simulation software market is experiencing significant growth, driven by several key factors. One of the primary drivers is the digital transformation within the mining industry, as companies increasingly turn to digital tools to enhance operational efficiency, reduce costs, and improve decision-making processes. The integration of automation and artificial intelligence (AI) into mining simulation software allows for more accurate modeling, real-time predictive capabilities, and scenario analysis. Additionally, the focus on safety and regulatory compliance has made simulation software indispensable. By providing a virtual environment for training and risk assessment, it helps mitigate potential hazards and ensures adherence to safety protocols. Furthermore, operational efficiency remains a central concern for mining companies, and simulation tools help identify inefficiencies, optimize resource allocation, and streamline processes, ultimately driving cost reductions and increasing productivity.
Regionally, the U.S. market is primarily concentrated in areas with high mining activity, including the Western U.S., Appalachian Region, and Alaska. States like Nevada, Arizona, and Utah, known for their significant gold and copper mining industries, are adopting simulation software to improve resource modeling and mine planning. The Appalachian region, which is heavily focused on coal mining, benefits from these tools to optimize extraction processes and ensure environmental compliance. Alaska, with its vast mineral resources, relies on simulation software for managing mining operations in challenging terrains. These regions underscore the growing importance of mining simulation software in enhancing safety, productivity, and environmental management within the industry.
Market Insights:
- The U.S. Mining Simulation Software Market was valued at USD 728.94 million in 2023 and is expected to grow to USD 1,544.92 million by 2032, reflecting a CAGR of 8.7% during the forecast period.
- The global mining simulation software market was valued at approximately USD 2.5 billion in 2023 and is projected to reach over USD 5.25 billion by 2032, reflecting a compound annual growth rate (CAGR) of 8.6% during the forecast period.
- The market's growth is fueled by the ongoing digital transformation within the mining industry, as companies adopt digital tools to improve operational efficiency and reduce costs.
- The integration of automation and artificial intelligence (AI) in simulation software enables more accurate modeling, real-time predictions, and optimized decision-making.
- Simulation software plays a crucial role in enhancing safety standards by providing virtual environments for training, risk assessment, and hazard mitigation in high-risk mining operations.
- Operational efficiency and cost reduction remain key priorities for mining companies, with simulation tools helping to optimize resource allocation, improve equipment management, and streamline production processes.
- Increasing environmental sustainability and regulatory compliance pressures are driving demand for mining simulation software to help companies minimize their environmental impact and ensure adherence to regulations.
- High initial investment costs and the complexity of integrating simulation software with existing systems are significant challenges, particularly for smaller mining companies with limited budgets.
Report Scope
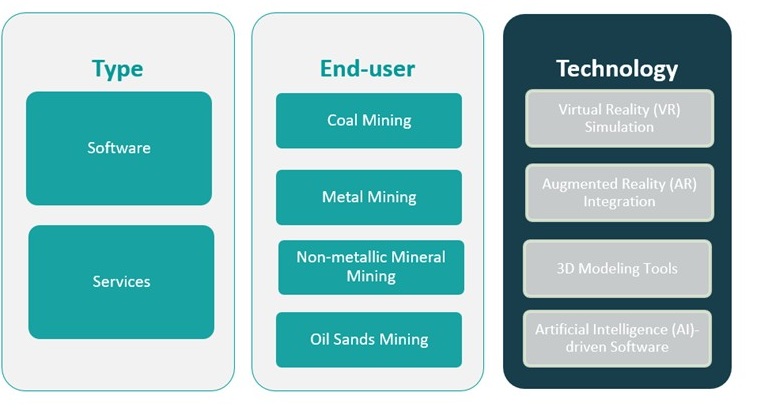
This report segments the U.S. Mining Simulation Software Market as follow
Market Drivers:
Technological Advancements in Automation and AI
The U.S. mining simulation software market is significantly driven by technological advancements in automation and artificial intelligence (AI). Mining companies are increasingly adopting AI and automation solutions to improve efficiency, optimize operations, and enhance productivity. AI-powered simulation software enables mining operators to model complex mining scenarios and predict outcomes more accurately. These capabilities help companies make data-driven decisions, improve resource management, and reduce operational risks. The integration of AI algorithms into simulation tools is also crucial for automating routine tasks and streamlining decision-making processes, allowing mining companies to allocate resources effectively and minimize human error. As technology continues to evolve, the role of AI in mining simulation software is expected to become even more integral, further driving market growth.
Enhancement of Safety Standards
The safety of workers in mining environments is another significant driver for the U.S. mining simulation software market. Mining operations inherently involve risks such as hazardous working conditions, equipment malfunctions, and environmental challenges. For instance, Freeport-McMoRan utilized drones and simulation technologies for blast pattern monitoring and highwall surveying, which has reduced employee exposure to traditional risks and improved safety outcomes. Simulation software provides a virtual platform for training workers, allowing them to experience and respond to high-risk situations in a controlled environment without the potential for harm. These tools enable mining companies to conduct comprehensive safety drills, improve employee preparedness, and mitigate workplace accidents. Furthermore, with increasing regulatory scrutiny in the mining sector, companies are turning to simulation software to ensure compliance with safety regulations and standards. As safety concerns remain a top priority, the demand for simulation software in the industry is poised to rise.
Operational Efficiency and Cost Reduction
Operational efficiency is a crucial focus for mining companies striving to maximize productivity and reduce costs. Mining simulation software plays a key role in optimizing resource allocation, improving the management of equipment, and enhancing production schedules. By simulating various operational scenarios, companies can identify inefficiencies, evaluate different strategies, and make informed decisions about their operations. Simulation tools also enable businesses to test different mining techniques and methods in a virtual environment before applying them in real-world conditions, which helps reduce costly mistakes and avoid downtime. For instance, predictive maintenance powered by AI analytics has allowed companies like Barrick Gold to significantly reduce unscheduled downtimes and extend equipment lifespan. As the mining industry continues to face pressure to lower operational expenses, the adoption of mining simulation software is expected to increase, offering companies the ability to streamline processes and achieve greater cost efficiency.
Regulatory Compliance and Environmental Management
The growing emphasis on environmental sustainability and regulatory compliance is also a key driver for the U.S. mining simulation software market. The mining industry is subject to strict environmental regulations aimed at minimizing its impact on ecosystems, air quality, and water resources. Mining simulation software allows companies to simulate and assess environmental risks associated with mining operations. By modeling environmental variables and assessing the potential impact of mining activities, simulation software helps organizations make informed decisions about their environmental management strategies. Additionally, these tools assist in ensuring compliance with environmental regulations by providing data and insights that can be used to improve sustainability practices. As regulations become increasingly stringent, the demand for simulation software to support compliance and environmental stewardship is expected to grow.
Market Trends:
Increased Adoption of Cloud-Based Simulation Software
A significant trend in the U.S. mining simulation software market is the growing adoption of cloud-based solutions. Traditionally, mining simulation software was installed on local systems, but the shift to cloud-based platforms offers numerous advantages, including improved accessibility, scalability, and cost efficiency. Cloud-based software enables mining companies to access simulation tools from any location, making it easier to collaborate across different teams and geographic regions. For instance, RPM Global offers cloud-enabled simulation solutions that support real-time data collection and analysis, enhancing decision-making and operational efficiency across mining sites. Additionally, cloud solutions provide better data storage and processing capabilities, allowing for the management of large datasets typical in mining operations. This trend aligns with the broader shift toward digital transformation in the mining industry, as cloud-based platforms streamline operations, reduce IT infrastructure costs, and offer more flexible, scalable solutions.
Integration of Virtual Reality (VR) and Augmented Reality (AR)
Another key trend in the U.S. mining simulation software market is the integration of virtual reality (VR) and augmented reality (AR) technologies. These immersive technologies are transforming the way mining simulation software is used, offering enhanced visualization capabilities that improve decision-making processes and operational training. VR and AR provide a more interactive experience, allowing users to simulate mining scenarios in a 3D virtual environment. For example, the University of Pretoria, in collaboration with Kumba Iron Ore, established a $1.3 million VR center equipped with advanced 3D stereoscopic theaters and immersive VR systems to train mining professionals in realistic scenarios. This immersive experience helps operators and engineers to better understand complex mining conditions, visualize the impact of different strategies, and improve overall safety. As VR and AR technologies become more advanced and affordable, their integration into mining simulation software is expected to become increasingly common, enabling more sophisticated simulations and training programs.
Rise in Collaboration with Technology Providers
The growing trend of collaboration between mining companies and technology providers is shaping the development of mining simulation software. Mining companies are partnering with software developers and technology providers to customize solutions that meet their specific operational needs. These partnerships often involve the integration of new technologies, such as AI, machine learning, and IoT, into mining simulation platforms. As a result, companies can access more tailored and advanced simulation capabilities, improving their ability to model complex scenarios and predict outcomes with greater accuracy. This collaboration between the mining sector and technology providers is expected to continue as the demand for more specialized, efficient, and high-performance simulation tools rises.
Focus on Sustainability and Green Mining Practices
A growing trend in the U.S. mining simulation software market is the increasing emphasis on sustainability and green mining practices. As environmental concerns become more prominent, mining companies are turning to simulation software to assess the environmental impact of their operations and identify ways to minimize resource depletion, energy consumption, and waste generation. Simulation tools are being used to optimize energy usage in mining processes, reduce carbon footprints, and improve the management of water resources. Additionally, with stricter environmental regulations being implemented, mining companies are using simulation software to ensure compliance and develop sustainable practices that align with both regulatory standards and corporate social responsibility goals. As sustainability becomes a critical focus for the industry, mining simulation software is evolving to support these green initiatives.
Market Challenges Analysis:
High Initial Investment Costs
One of the key restraints in the U.S. mining simulation software market is the high initial investment required for acquiring and implementing these advanced tools. Mining simulation software, particularly those incorporating artificial intelligence, machine learning, and virtual reality, can be expensive to license, deploy, and maintain. For smaller mining companies with limited budgets, the cost of these solutions may present a significant barrier to adoption. Additionally, there are ongoing costs related to system updates, training, and integration with existing operational systems. This financial burden can deter some companies from investing in mining simulation software, particularly if the return on investment is not immediately clear.
Complexity of Integration with Existing Systems
Another challenge facing the mining industry is the complexity of integrating simulation software with existing mining systems and infrastructure. Many mining companies rely on legacy systems for operations, and integrating modern simulation tools into these systems can be both time-consuming and costly. For example, mining companies using HAULSIM or K-MINE often face lengthy and complex integration processes when connecting new simulation software with legacy operational systems. Furthermore, the data required for accurate simulations is often stored in different formats across various platforms, which can make it difficult to achieve seamless data interoperability. Ensuring that the simulation software is compatible with a company's existing systems requires significant technical expertise and resources, presenting a considerable challenge for companies looking to adopt these technologies.
Data Quality and Availability
The effectiveness of mining simulation software depends heavily on the quality and availability of data. Accurate and comprehensive data is essential for creating reliable simulations and predicting mining outcomes. However, many mining companies struggle with inconsistent or incomplete data, particularly in regions where data collection practices may be less rigorous. Without high-quality data, the results of simulations may be inaccurate, leading to poor decision-making and suboptimal outcomes. This challenge highlights the importance of robust data management systems and the need for companies to invest in improving their data collection and storage processes.
Regulatory and Environmental Challenges
The mining industry is subject to stringent environmental regulations and compliance requirements. While simulation software can help companies meet regulatory standards, the rapidly changing landscape of environmental laws and regulations can create uncertainty for mining operators. Adapting simulation tools to comply with new regulations requires constant updates and adjustments, adding to the complexity and cost of using these software solutions. Additionally, navigating the environmental impact of mining operations remains a significant challenge, and while simulation software can aid in optimizing sustainable practices, it may not entirely address the growing demand for more environmentally responsible mining solutions.
Market Opportunities:
The U.S. mining simulation software market presents several promising opportunities, driven by the increasing demand for operational efficiency and safety in the mining industry. As mining companies strive to reduce operational costs, improve productivity, and optimize resource allocation, there is a significant opportunity for simulation software providers to cater to these needs. The ability to simulate various mining scenarios and predict outcomes with high accuracy allows companies to make informed decisions, minimize costly errors, and improve overall operational performance. As digital transformation continues to gain momentum in the mining industry, there is a growing market for advanced simulation tools, including AI-powered platforms, that can help operators optimize processes and achieve cost reductions.
Furthermore, the growing emphasis on sustainability and environmental responsibility in the mining sector opens new opportunities for mining simulation software developers. As environmental regulations become more stringent, companies are increasingly seeking ways to reduce their environmental impact. Simulation software offers the ability to model and assess the environmental effects of mining operations, helping companies optimize energy consumption, water usage, and waste management. With the demand for greener mining practices on the rise, there is significant potential for simulation software to assist companies in meeting regulatory requirements and adopting sustainable practices. The combination of cost optimization, safety improvements, and environmental management positions the U.S. mining simulation software market as a key growth area in the coming years.
Market Segmentation Analysis:
The U.S. mining simulation software market can be segmented based on type, end-user, and technology, each offering distinct opportunities for growth.
By Type Segment The market is primarily divided into software and services. The software segment includes simulation tools used for mine planning, resource management, and training, driving the demand for advanced systems that enhance operational efficiency and safety. The services segment covers consulting, training, and technical support, which are essential for helping mining companies effectively implement and integrate simulation solutions. As mining companies continue to adopt digital technologies, the demand for both software and services is expected to grow, with services playing a critical role in ensuring successful adoption and usage.
By End-User Segment The market's end-user segments include coal mining, metal mining, non-metallic mineral mining, and oil sands mining. Metal mining holds the largest share due to the high demand for simulation software to optimize the extraction and processing of valuable metals like gold, copper, and silver. Non-metallic mineral mining is also expanding as simulation tools help improve efficiency in extracting materials such as limestone and gypsum. Coal and oil sands mining are increasingly adopting simulation software for enhanced resource modeling and risk management in challenging operational environments.
By Technology Segment In terms of technology, virtual reality (VR) and augmented reality (AR) integration are emerging as key trends, providing immersive, real-time simulations for training and operational decision-making. 3D modeling tools and AI-driven software are increasingly popular for their ability to optimize mine design and predict outcomes. These advanced technologies enable more accurate, dynamic simulations, facilitating better decision-making and improving safety standards within the mining industry. As the technology landscape continues to evolve, AI-driven software and VR/AR integration are expected to drive significant growth in the sector.
Segmentation:
By Type Segment:
- Software
- Services
By End-User Segment:
- Coal Mining
- Metal Mining
- Non-metallic Mineral Mining
- Oil Sands Mining
By Technology Segment:
- Virtual Reality (VR) Simulation
- Augmented Reality (AR) Integration
- 3D Modeling Tools
- Artificial Intelligence (AI)-driven Software
Regional Analysis:
The U.S. mining simulation software market is experiencing substantial growth, with regional dynamics playing a critical role in shaping its overall expansion. The market is influenced by mining activities concentrated in specific regions, each with varying levels of adoption of simulation technologies. Key regions driving the growth of mining simulation software include the Western U.S., Appalachian Region, and Alaska, with each region representing unique demands and opportunities.
Western U.S.
The Western U.S. holds the largest market share in the U.S. mining simulation software market, accounting for approximately 40% of the total market. This region is home to some of the largest mining operations in the country, including those focused on gold, copper, and other precious metals. Nevada, Arizona, and Utah are particularly dominant in this segment, driving the demand for simulation software to improve resource modeling, mine planning, and operational efficiency. The region's significant mining presence coupled with ongoing technological adoption makes it the key market for advanced simulation tools.
Appalachian Region
The Appalachian region, which includes states such as West Virginia, Kentucky, and Pennsylvania, is another important market for mining simulation software. This region is primarily focused on coal mining, which represents a substantial portion of its mining activities. The demand for simulation software in this region is driven by the need to enhance safety, improve environmental management, and optimize extraction processes. The Appalachian region accounts for roughly 25% of the market share, as companies are increasingly adopting digital tools to mitigate risks and comply with stringent regulatory requirements related to coal mining operations.
Alaska
Alaska, with its vast untapped mineral resources, also presents a growing opportunity for mining simulation software adoption. The state has a smaller but rapidly expanding share of the U.S. market, accounting for around 15%. Alaska's mining sector, which primarily focuses on precious metals and base metals, faces unique challenges due to its remote location and harsh environmental conditions. Simulation software helps companies in Alaska optimize resource extraction, plan operations in challenging terrains, and reduce environmental impact, which are essential factors driving the market in the region.
Other Regions
Other regions, including the Midwest and Southern U.S., contribute to the remaining 20% of the market share. These areas focus on non-metallic mineral mining, such as limestone, and oil sands mining. Although smaller in scale compared to the Western and Appalachian regions, the demand for mining simulation software in these areas is steadily increasing, especially as companies aim to enhance productivity, safety, and compliance with environmental regulations.
Key Player Analysis:
- Dassault Systèmes
- Bentley Systems
- RPMGlobal
- Hexagon Mining
- Maptek
- Siemens AG
- VIST Group
- Autodesk
- Caterpillar
- BMT Group
Competitive Analysis:
The U.S. mining simulation software market is highly competitive, with several key players offering advanced solutions to meet the growing demand for operational efficiency, safety, and resource optimization. Leading companies in the market include Hexagon Mining, Dassault Systèmes, RPMGlobal, and Maptek, each offering a range of simulation tools designed to support mining operations across various stages, from planning and design to training and risk management. These companies focus on integrating cutting-edge technologies such as artificial intelligence, virtual reality, and 3D modeling to improve simulation accuracy and decision-making processes. Additionally, several smaller players are carving a niche by offering specialized solutions tailored to specific mining sectors, such as coal, metal, or non-metallic minerals. Competitive strategies include product innovation, strategic partnerships, and acquisitions to enhance technological capabilities and expand market presence. As mining companies continue to adopt digital technologies, the competition in this market is expected to intensify.
Recent Developments:
- On April 2, 2025, Hexagon completed the acquisition of the Geomagic software business from 3D Systems Corporation. This acquisition brings advanced 3D measurement, modeling, and reverse engineering capabilities to Hexagon’s portfolio, strengthening its offering across manufacturing, mining, and construction sectors. The Geomagic suite will now be integrated into Hexagon’s Manufacturing Intelligence division and supported for all existing hardware and software partners.
- In February 2025, Dassault Systèmes announced that its subsidiary, Centric Software, acquired Contentserv, an AI-powered Product Experience Management (PXM) solution provider, for €220 million. This acquisition strengthens Dassault Systèmes' digital transformation capabilities, especially in cloud-based product lifecycle management.
- In November 2024, Maptek announced early access for its new Maptek Vestrex ecosystem, a platform for automation and orchestration in mining operations. This suite includes the Maptek Data System, Compute Framework, and Orchestration Environment, providing integrated solutions for mine planning and scheduling-key for Asian mines seeking operational efficiency.
Market Concentration & Characteristics:
The U.S. mining simulation software market exhibits moderate to high concentration, with a few key players dominating the space. Leading companies such as Hexagon Mining, Dassault Systèmes, RPMGlobal, and Maptek hold a significant share due to their established presence, comprehensive product portfolios, and continuous innovation in simulation technologies. These companies leverage advanced tools, including artificial intelligence, virtual reality, and 3D modeling, to offer cutting-edge solutions that enhance operational efficiency, safety, and resource management. Despite the dominance of major players, the market also features a number of smaller firms offering specialized solutions tailored to specific mining sectors, such as coal, metal, or non-metallic mining. These smaller companies often focus on niche applications, providing customized solutions that meet the unique needs of regional or resource-specific markets. The market's characteristics reflect a strong focus on technological innovation, customer-centric solutions, and strategic partnerships aimed at expanding market share.
Report Coverage:
The research report offers an in-depth analysis based on Type Segment, End-User Segment and Technology Segment. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The U.S. mining simulation software market is expected to see continued growth due to rising demand for digital transformation in mining operations.
- Increased adoption of artificial intelligence and machine learning will enhance simulation accuracy and predictive capabilities.
- Virtual reality (VR) and augmented reality (AR) technologies will play a more significant role in immersive training and decision-making.
- Regulatory compliance pressures will drive the need for advanced simulation tools that ensure environmental and safety standards are met.
- Smaller mining companies will increasingly invest in simulation software as costs decrease and software becomes more accessible.
- Cloud-based simulation solutions will gain traction due to their scalability, cost-efficiency, and remote accessibility.
- Integration with Internet of Things (IoT) devices will enable real-time data collection and enhance the efficiency of mining simulations.
- The expansion of mining operations in remote areas will create opportunities for simulation software tailored to challenging environments.
- The growing focus on sustainability will drive the development of software that optimizes resource use and reduces environmental impact.
- Competition will intensify as new entrants innovate with niche applications for specific mining sectors, pushing established players to evolve.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements in Automation and AI
The integration of automation and artificial intelligence into mining simulation software enables more accurate modeling, real-time predictive analytics, and scenario analysis, allowing mining companies to optimize operations, reduce risks, and improve decision-making.
Enhancement of Safety Standards
Simulation software provides virtual environments for training and risk assessment, helping mining companies mitigate hazards, improve worker preparedness, and comply with increasingly stringent safety regulations.
Operational Efficiency and Cost Reduction
Mining simulation tools help companies identify inefficiencies, optimize resource allocation, and streamline processes, leading to significant cost savings and productivity improvements across mining operations.
Regulatory Compliance and Environmental Management
With growing environmental regulations, simulation software enables mining companies to model and assess environmental risks, optimize sustainability practices, and ensure compliance with federal and state requirements.
Adoption of Cloud-Based and Immersive Technologies
The shift toward cloud-based platforms and the integration of VR/AR technologies enhance accessibility, scalability, and immersive training capabilities, making advanced simulation tools more attractive and effective for mining companies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Mining Simulation Software Market?
What factors are driving the growth of the U.S. Mining Simulation Software Market?
What are some challenges faced by the U.S. Mining Simulation Software Market?
Who are the major players in the U.S. Mining Simulation Software Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Software
- 1.2.2 Services
- 1.3 By End-User
- 1.3.1 Coal Mining
- 1.3.2 Metal Mining
- 1.3.3 Non-metallic Mineral Mining
- 1.3.4 Oil Sands Mining
- 1.4 By Technology
- 1.4.1 Virtual Reality (VR) Simulation
- 1.4.2 Augmented Reality (AR) Integration
- 1.4.3 3D Modeling Tools
- 1.4.4 Artificial Intelligence (AI)-driven Software
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 728.94 million → 2032: USD 1,544.92 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Mining Simulation Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Mining Simulation Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 U.S. Mining Simulation Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 U.S. Mining Simulation Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Mining Simulation Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Mining Simulation Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Mining Simulation Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Mining Simulation Software Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 728.94 million → 2032: USD 1,544.92 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Mining Simulation Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Base-Year Market Share, 2023
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Software
- 12.3.6.2 Services
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Base-Year Market Share, 2023
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Coal Mining
- 12.4.6.2 Metal Mining
- 12.4.6.3 Non-metallic Mineral Mining
- 12.4.6.4 Oil Sands Mining
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Base-Year Market Share, 2023
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Virtual Reality (VR) Simulation
- 12.5.6.2 Augmented Reality (AR) Integration
- 12.5.6.3 3D Modeling Tools
- 12.5.6.4 Artificial Intelligence (AI)-driven Software
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Mining Simulation Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 U.S. Mining Simulation Software Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 U.S. Mining Simulation Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 U.S. Mining Simulation Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Hexagon Mining
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Dassault Systèmes
- 18.4 RPMGlobal
- 18.5 Maptek
- 18.6 Bentley Systems
- 18.7 Siemens AG
- 18.8 Autodesk
- 18.9 VIST Group
- 18.10 Caterpillar
- 18.11 BMT Group
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

