
Market Overview
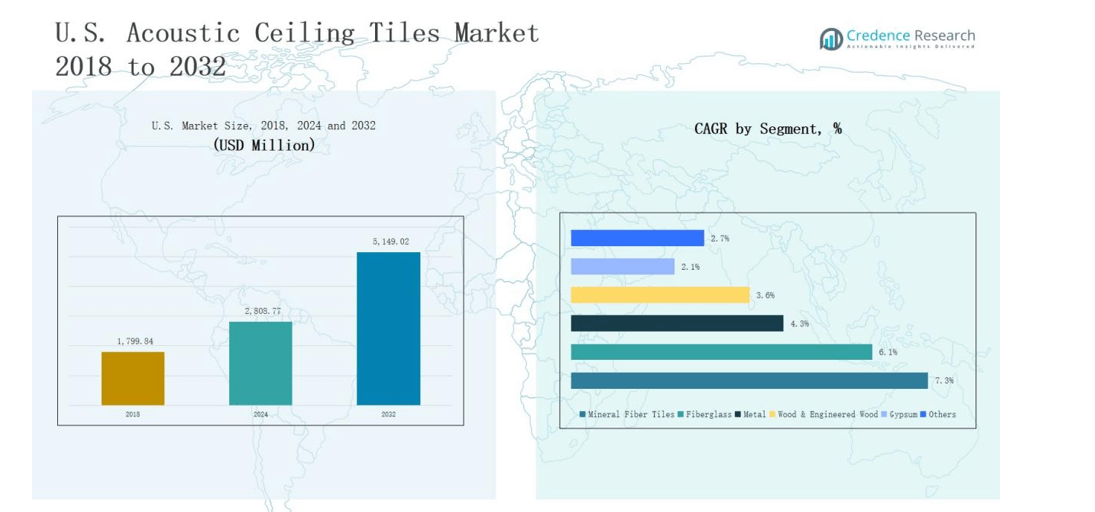
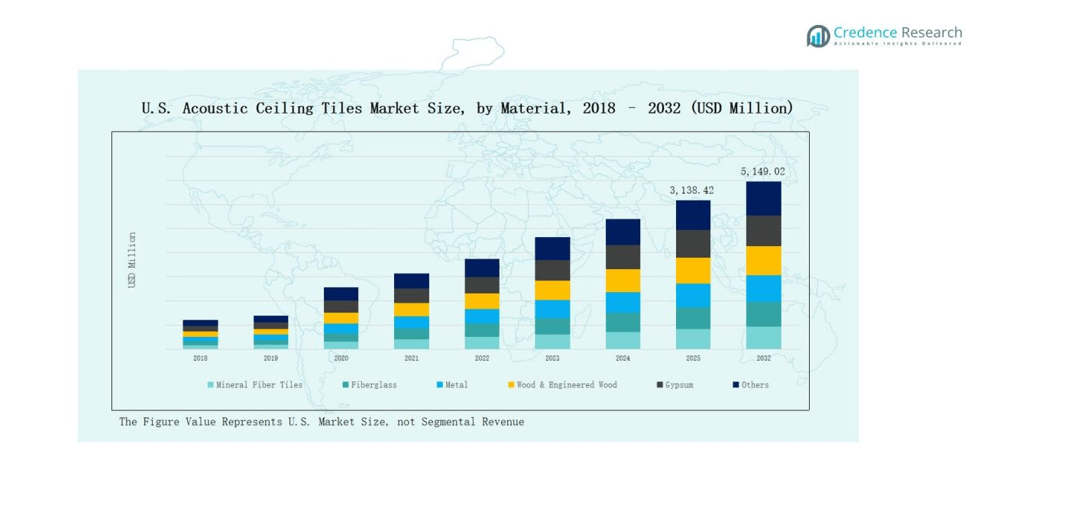
U.S. Acoustic Ceiling Tiles Market size was valued at USD 1,799.84 million in 2018, reached USD 2,808.77 million in 2024, and is anticipated to reach USD 5,149.02 million by 2032, growing at a CAGR of 7.33% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Acoustic Ceiling Tiles Market Size 2024 | USD 2,808.77 million |
| U.S. Acoustic Ceiling Tiles Market, CAGR | 7.33% |
| U.S. Acoustic Ceiling Tiles Market Size 2032 | USD 5,149.02 million |
The U.S. Acoustic Ceiling Tiles Market is shaped by leading companies such as Armstrong World Industries, USG Corporation, CertainTeed (Saint-Gobain), Rockfon, Hunter Douglas, SAS International, Ceilume, OWA Ceiling Systems Inc., Acoustical Surfaces, and Autex Acoustics. These players compete through product innovation, sustainable material development, and strategic partnerships with architects and contractors to strengthen their market presence. Armstrong World Industries and USG Corporation hold strong positions with extensive mineral fiber and fiberglass portfolios, while Rockfon and CertainTeed focus on premium solutions. The South region emerged as the leading market in 2024, commanding 31% share, driven by rapid urbanization, large-scale commercial projects, and expanding institutional infrastructure.
Market Insights
- The U.S. Acoustic Ceiling Tiles Market grew from USD 1,799.84 million in 2018 to USD 2,808.77 million in 2024 and is expected to reach USD 5,149.02 million by 2032.
- Mineral fiber tiles led with 41.2% share in 2024, supported by strong acoustic insulation, fire resistance, and cost efficiency, making them the preferred choice in institutional and commercial buildings.
- Suspended ceiling tiles dominated with 63.5% share in 2024, driven by flexibility, easy maintenance, and widespread use across offices, schools, and healthcare facilities nationwide.
- Building contractors accounted for 46.7% share in 2024, reflecting their pivotal role in material selection for new construction and renovation activities across commercial and residential sectors.
- The South region led with 31% share in 2024, supported by urbanization, large-scale projects in Texas and Florida, and growing adoption of premium designs in retail and hospitality.
Market Segment Insights
By Material
Mineral fiber tiles held the dominant share of 41.2% in the U.S. acoustic ceiling tiles market in 2024. Their strong acoustic insulation, cost-effectiveness, and fire-resistant properties drive adoption in commercial and institutional projects. Fiberglass follows due to lightweight construction and design flexibility, while metal and wood variants cater to premium aesthetics. Gypsum tiles gain traction in residential applications for durability. The “others” category includes composites addressing niche needs, but mineral fiber tiles remain the primary choice across diverse construction projects.
- For instance, Armstrong World Industries expanded its mineral fiber ceiling tile line with enhanced acoustical control solutions targeted at healthcare and education facilities.
By Installation Type
Suspended ceiling tiles accounted for 63.5% share in 2024, making them the leading installation type in the U.S. market. Their easy maintenance, flexibility for electrical and HVAC integration, and widespread use in offices, schools, and healthcare facilities drive this dominance. Surface-mounted ceiling tiles, though less common, gain use in small-scale renovations where suspended frameworks are not feasible. Demand for suspended designs continues to grow with large-scale commercial developments and retrofitting projects across urban regions.
- For instance, Armstrong World Industries introduced its Sustain portfolio of ceiling panels designed for schools and offices, emphasizing sustainable materials and integration with modern HVAC systems.
By End User
Building contractors dominated the market with a 46.7% share in 2024, reflecting their strong role in selecting cost-efficient and performance-driven materials for projects. Architects and interior designers follow closely, driving demand for premium finishes and sustainable materials in high-end commercial and residential projects. Facility managers represent a steady segment focused on replacement and maintenance. The “others” category includes DIY users and small-scale builders. Building contractors’ purchasing influence secures their leading position across new construction and renovation activities.
Market Overview
Rising Commercial Construction Projects
The U.S. market benefits from sustained demand in commercial construction, including office spaces, healthcare facilities, and educational institutions. Acoustic ceiling tiles are essential for sound absorption, compliance with building codes, and improved occupant comfort. Government infrastructure initiatives and private real estate investments reinforce this growth. The preference for efficient designs that balance aesthetics with functionality keeps mineral fiber and fiberglass tiles in high demand, cementing their role as the standard choice across high-volume commercial developments.
- For instance, USG’s Soft Fiber ceiling tiles provide NRC values close to 1.0 along with high ceiling attenuation, widely used in healthcare and educational buildings for privacy and noise reduction.
Focus on Energy Efficiency and Sustainability
Increasing focus on green building certifications such as LEED and WELL is boosting adoption of eco-friendly ceiling solutions. Acoustic ceiling tiles made from recycled content, low-emission materials, and sustainable composites meet regulatory standards while enhancing market appeal. Rising corporate sustainability targets and consumer awareness also drive demand for such products. Manufacturers respond with advanced offerings that combine acoustic performance with environmental responsibility, aligning with the U.S. construction industry’s shift toward sustainable and energy-efficient designs.
- For instance, Gyproc by Saint-Gobain provides gypsum boards and ceiling tiles certified under Green-Pro standards that align with corporate sustainability targets and regulatory requirements.
Urban Renovation and Retrofit Demand
Urbanization and the aging building stock across major U.S. cities create strong demand for renovation projects. Retrofitting ceilings with acoustic tiles provides cost-effective noise reduction and aesthetic improvements without extensive structural changes. Schools, offices, and healthcare facilities lead this trend, focusing on modernizing interiors while maintaining budgets. Facility managers and contractors favor suspended ceiling systems due to their adaptability and quick installation. This retrofit momentum drives steady growth, particularly in dense urban regions undergoing commercial and institutional upgrades.
Key Trends & Opportunities
Integration of Smart and Modular Designs
The U.S. market is witnessing rising demand for modular acoustic ceiling tiles that integrate lighting, sensors, and air filtration systems. These multifunctional ceilings address energy efficiency, aesthetics, and workplace wellness simultaneously. Manufacturers see opportunity in offering customizable designs that support flexible office layouts and smart building technologies. Modular innovations also appeal to facility managers seeking scalable solutions for renovations. This trend positions ceiling systems as integral to broader smart infrastructure development.
- For instance, Vibe by Vision offers smart acoustic ceiling tiles embedded with sensors that detect temperature and humidity, enabling building management systems to optimize acoustics and air quality automatically.
Premiumization and Aesthetic Appeal
An increasing opportunity lies in premium tiles offering superior aesthetics alongside acoustic performance. Metal and wood-based ceiling tiles are gaining traction in luxury offices, hospitality, and retail spaces where design is as critical as functionality. Architects and interior designers drive this demand by specifying high-end finishes to meet client expectations. The combination of durability, customization, and modern aesthetics provides manufacturers with lucrative opportunities to target niche but profitable market segments within the U.S. construction industry.
- For instance, CertainTeed expanded its Ecophon® Focus™ range, offering customizable premium ceiling tiles designed for both acoustics and visual appeal in high-end hospitality projects.
Key Challenges
High Installation and Maintenance Costs
The adoption of acoustic ceiling tiles in the U.S. faces restraint from high installation and ongoing maintenance costs. While suspended ceilings dominate due to their utility, they require significant labor and material investments. Small-scale projects and budget-sensitive institutions often hesitate to adopt premium ceiling solutions. Regular cleaning and replacement needs also increase lifecycle expenses. This cost barrier reduces adoption in low-budget renovations and residential projects, limiting market penetration beyond core commercial applications.
Competition from Alternative Solutions
Alternative soundproofing and interior design options, such as acoustic wall panels, spray-applied insulation, and drywall systems, challenge the growth of ceiling tiles. These substitutes often offer similar acoustic benefits at lower costs or with easier installation. Architects and contractors sometimes prefer these solutions in projects with limited ceiling height or structural constraints. As alternative materials evolve with better performance, the competitive pressure on acoustic ceiling tiles intensifies, requiring manufacturers to differentiate through innovation and value-added features.
Volatility in Raw Material Prices
Price fluctuations in raw materials, particularly mineral fiber, metal, and gypsum, create challenges for manufacturers in the U.S. acoustic ceiling tiles market. Supply chain disruptions, rising energy costs, and global trade uncertainties add to pricing volatility. Frequent adjustments in procurement and production costs affect profit margins, forcing companies to increase product prices. This volatility makes it difficult for contractors and distributors to plan budgets effectively, potentially slowing down adoption in cost-sensitive market segments.
Regional Analysis
Northeast
The Northeast accounted for 28% share of the U.S. Acoustic Ceiling Tiles Market in 2024. Strong demand arises from commercial real estate development in New York, Boston, and Philadelphia. Renovation of aging institutional buildings supports steady adoption of mineral fiber and fiberglass tiles. Architects emphasize sustainability standards, which drive demand for eco-friendly ceiling materials. The presence of large educational and healthcare institutions ensures long-term growth. It remains a leading market due to a balance of new construction and retrofit projects.
Midwest
The Midwest held 22% share of the market in 2024, supported by industrial hubs and expanding office spaces. Cities such as Chicago and Detroit record strong demand for suspended ceiling tiles. Facility managers in manufacturing-heavy states focus on cost-efficient acoustic solutions to enhance work environments. The regional construction sector emphasizes durable products, creating opportunities for gypsum and metal-based tiles. It continues to attract investments in commercial infrastructure. The market reflects a strong balance between affordability and performance.
South
The South led with 31% share of the U.S. Acoustic Ceiling Tiles Market in 2024. Rapid urbanization, population growth, and large-scale commercial projects in Texas, Florida, and Georgia fuel demand. Architects and contractors adopt premium wood and metal ceiling tiles in luxury retail and hospitality spaces. High demand in educational institutions further expands the use of mineral fiber tiles. The region also benefits from favorable construction activity driven by corporate relocations. It remains the fastest-growing contributor with both urban and suburban projects.
West
The West captured 19% share of the market in 2024, supported by California’s strong real estate and technology sectors. Demand for acoustic ceiling tiles is driven by modern office spaces, healthcare expansions, and sustainability mandates. Architects in the region prefer advanced fiberglass and modular tile systems to align with smart building practices. Premium designs hold traction in retail and entertainment projects. It benefits from eco-conscious construction trends and strict energy codes. The region continues to show growth through innovation-led adoption.
Market Segmentations:
By Material
- Mineral Fiber Tiles
- Fiberglass
- Metal
- Wood & Engineered Wood
- Gypsum
- Others
By Installation Type
- Suspended Ceiling Tiles
- Surface Mounted Ceiling Tiles
By End User
- Architects and Interior Designers
- Building Contractors
- Facility Managers
- Others
By Region
- Northeast
- Midwest
- South
- West
Competitive Landscape
The U.S. Acoustic Ceiling Tiles Market is highly competitive, characterized by the presence of global leaders and regional specialists. Key players such as Armstrong World Industries, USG Corporation, CertainTeed (Saint-Gobain), and Rockfon dominate with strong distribution networks, advanced product portfolios, and established relationships with architects and contractors. Their focus on mineral fiber and fiberglass tiles secures broad adoption in commercial and institutional projects. Companies like Hunter Douglas, SAS International, Ceilume, OWA Ceiling Systems Inc., and Autex Acoustics strengthen competition by offering premium wood, metal, and modular solutions targeting niche segments. The landscape reflects intense emphasis on innovation, with firms introducing sustainable, lightweight, and energy-efficient ceiling systems that align with evolving green building standards. Strategic mergers, partnerships, and product diversification remain central to market positioning. It continues to attract new entrants in design-driven and eco-friendly categories, further intensifying competition and shaping long-term growth opportunities across U.S. construction sectors.
Key Players
- Armstrong World Industries
- USG Corporation
- CertainTeed (Saint-Gobain)
- Rockfon
- Acoustical Surfaces
- Hunter Douglas
- SAS International
- Ceilume
- OWA Ceiling Systems Inc.
- Autex Acoustics
Recent Developments
- In September 2025, Armstrong World Industries acquired Geometrik, a maker of wood acoustical ceiling and wall systems.
- In August 2024, WAVE, the joint venture of Armstrong and Worthington, acquired the assets of Data Center Resources to expand modular aisle containment and ceiling solutions.
- In November 2023, Swedish brand BAUX introduced its Acoustic Pulp Bio Colour panels to the U.S. market.
Report Coverage
The research report offers an in-depth analysis based on Material, Installation Type, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for mineral fiber tiles will continue leading due to cost efficiency and acoustic strength.
- Fiberglass tiles will gain traction with rising preference for lightweight and flexible ceiling solutions.
- Premium wood and metal tiles will expand in luxury offices, retail, and hospitality projects.
- Renovation and retrofit projects in schools and hospitals will drive consistent replacement demand.
- Green building standards will push manufacturers to introduce eco-friendly and recyclable tile options.
- Smart modular ceiling systems integrating lighting and sensors will see wider adoption.
- Building contractors will remain the largest end-user group influencing material choice.
- Architects and designers will shape premium segment growth with emphasis on aesthetics.
- Facility managers will sustain steady demand through maintenance and upgrade cycles.
- Regional growth will remain strongest in the South, driven by large-scale commercial construction.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in Commercial Construction
The expansion of office spaces, healthcare facilities, and educational institutions across the U.S. is driving demand for acoustic ceiling tiles, which are essential for sound absorption, code compliance, and occupant comfort in these environments.
Urban Renovation and Retrofit Projects
Aging building stock and urbanization in major U.S. cities are fueling renovation and retrofit activities, where acoustic ceiling tiles offer a cost-effective solution for noise reduction and aesthetic upgrades without major structural changes.
Emphasis on Energy Efficiency and Sustainability
Increasing adoption of green building certifications like LEED and WELL is pushing demand for eco-friendly ceiling tiles made from recycled and low-emission materials, as both regulatory requirements and corporate sustainability goals become more stringent.
Integration of Smart and Modular Ceiling Systems
Rising interest in modular ceiling tiles that incorporate lighting, sensors, and air filtration is creating new opportunities, as these multifunctional systems support flexible office layouts and smart building technologies.
Premiumization and Aesthetic Appeal
Demand for high-end metal and wood ceiling tiles is growing in luxury offices, hospitality, and retail spaces, as architects and designers seek products that combine superior acoustics with modern aesthetics and customization options.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for U.S. Acoustic Ceiling Tiles Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the U.S. Acoustic Ceiling Tiles Market projected to grow between 2025 and 2032?
Which U.S. Acoustic Ceiling Tiles Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the U.S. Acoustic Ceiling Tiles Market?
Who are the leading companies in the U.S. Acoustic Ceiling Tiles Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Architects and Interior Designers
- 1.2.2 Building Contractors
- 1.2.3 Facility Managers
- 1.2.4 Others
- 1.3 By Material
- 1.3.1 Mineral Fiber Tiles
- 1.3.2 Fiberglass
- 1.3.3 Metal
- 1.3.4 Wood & Engineered Wood
- 1.3.5 Gypsum
- 1.3.6 Others
- 1.4 By Installation Type
- 1.4.1 Suspended Ceiling Tiles
- 1.4.2 Surface Mounted Ceiling Tiles
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,808.77 million → 2032: USD 5,149.02 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Acoustic Ceiling Tiles Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Acoustic Ceiling Tiles Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Acoustic Ceiling Tiles Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Acoustic Ceiling Tiles Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Acoustic Ceiling Tiles Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Acoustic Ceiling Tiles Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Acoustic Ceiling Tiles Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Acoustic Ceiling Tiles Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,808.77 million → 2032: USD 5,149.02 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Acoustic Ceiling Tiles Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Architects and Interior Designers
- 12.3.7.2 Building Contractors
- 12.3.7.3 Facility Managers
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Mineral Fiber Tiles
- 12.4.7.2 Fiberglass
- 12.4.7.3 Metal
- 12.4.7.4 Wood & Engineered Wood
- 12.4.7.5 Gypsum
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Installation Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Suspended Ceiling Tiles
- 12.5.7.2 Surface Mounted Ceiling Tiles
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Acoustic Ceiling Tiles End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 U.S. Acoustic Ceiling Tiles Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 U.S. Acoustic Ceiling Tiles Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 U.S. Acoustic Ceiling Tiles Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Armstrong World Industries
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 USG Corporation
- 18.4 CertainTeed (Saint-Gobain)
- 18.5 Rockfon
- 18.6 Hunter Douglas
- 18.7 SAS International
- 18.8 Ceilume
- 18.9 OWA Ceiling Systems Inc.
- 18.10 Acoustical Surfaces
- 18.11 Autex Acoustics
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

