
US Dental Care Market Overview:
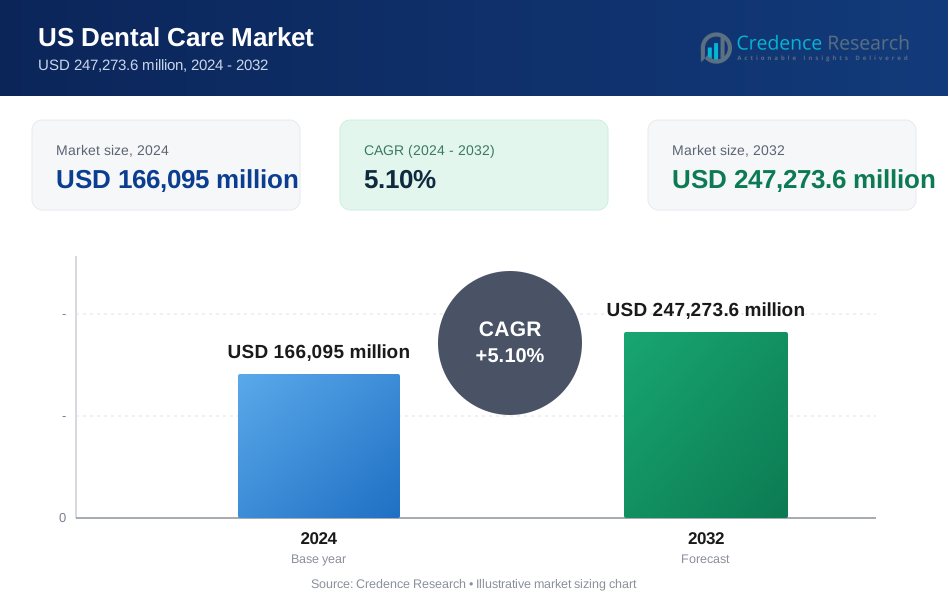
The US Dental Care Market size was valued at USD 166,095 million in 2024 and is anticipated to reach USD 247,273.6 million by 2032, growing at a CAGR of 5.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| US Dental Care Market Size 2024 | USD 166,095 million |
| US Dental Care Market, CAGR | 5.1% |
| US Dental Care Market Size 2032 | USD 247,273.6 million |
US Dental Care Market Insights
- The US Dental Care Market growth is driven by rising oral health awareness, increasing preventive dental visits, expanding dental insurance coverage, and higher demand from the aging population for restorative and periodontal care.
- The US Dental Care Market shows strong trends in digital dentistry adoption, teledentistry expansion, and growing demand for cosmetic procedures, while Diagnostic and Preventive Services led the service segment with a 34.6% share in 2024 and Preventive applications dominated with a 41.2% share in 2024.
- The US Dental Care Market analysis highlights leading DSOs such as Heartland Dental, Aspen Dental, Pacific Dental Services, Smile Brands, and Dental Care Alliance, which strengthen presence through clinic expansion, standardized protocols, technology integration, and partnerships.
- The US Dental Care Market faces restraints from high costs of advanced treatments and workforce shortages, while the South led regional demand with a 31.6% share in 2024, followed by the Northeast at 24.8%, Midwest at 22.3%, and West at 21.3%.

US Dental Care Market Segmentation Analysis:
By Services:
The US Dental Care Market by services is led by Diagnostic and Preventive Services, which accounted for 34.6% market share in 2024, driven by routine dental checkups, rising oral health awareness, and strong insurance coverage for preventive care. Regular examinations, X-rays, cleanings, and fluoride treatments support early detection of dental disorders, reducing long-term treatment costs. Growth is further supported by increasing annual dental visits, employer-sponsored dental plans, and preventive care recommendations by the American Dental Association. Cosmetic dentistry and orthodontic services are also expanding due to rising aesthetic preferences and demand for minimally invasive dental procedures.
- For instance, Henry Schein One, partnering with VideaHealth, integrates Dentrix Detect AI into practice software, cutting missed caries by 43% and errors by 15% for precise diagnostics on X-rays.
By Application:
The US Dental Care Market by application is dominated by the Preventive segment, which held a 41.2% market share in 2024, supported by a strong emphasis on oral disease prevention and cost-effective care delivery. Preventive services such as cleanings, sealants, and routine screenings are widely adopted across all age groups to avoid advanced dental conditions. Growth is reinforced by favorable reimbursement policies, school-based oral health programs, and increasing geriatric population requiring regular dental monitoring. Rising awareness of the link between oral health and systemic diseases further strengthens demand for preventive dental applications.
- For instance, Colgate's Bright Smiles, Bright Futures program delivers oral health education and screenings through classroom curricula reaching 4 million children across all 50 US states, alongside mobile dental vans providing services to 10 million children in rural and urban areas.
Key Growth Drivers
Rising Awareness of Oral Health and Preventive Care
Increasing awareness of oral health and its impact on overall well-being is a major growth driver in the US Dental Care Market. Government initiatives, professional dental associations, and digital health platforms have strengthened public understanding of preventive dental practices. Regular dental checkups, early diagnosis, and routine cleanings are increasingly viewed as essential healthcare services rather than optional visits. This behavioral shift drives higher utilization of diagnostic and preventive services, supports early treatment intervention, and reduces the long-term burden of complex dental procedures across diverse age groups.
- For instance, The Pew Charitable Trusts launched a dental campaign in 2007 that promoted school-based sealant programs, boosting sealant use among low-income children by about 70% from 1999-2004 to 2011-14 and preventing nearly 1 million cavities nationwide.
Expansion of Dental Insurance Coverage
The expansion of dental insurance coverage continues to support growth in the US Dental Care Market. Employer-sponsored dental plans, public insurance programs, and private dental policies have improved patient access to preventive and corrective dental services. Coverage for routine examinations, cleanings, and basic restorative treatments lowers out-of-pocket costs and encourages consistent dental visits. Improved reimbursement visibility also enables dental practices to invest in advanced equipment, expand service offerings, and improve patient outreach, supporting steady growth across clinical settings.
- For instance, Maryland's Medicaid program, effective January 2023, expanded adult benefits to include diagnostic, preventive, restorative, endodontic, periodontal, and oral surgery services for all enrollees, enhancing access to routine exams and cleanings previously limited.
Growing Aging Population and Chronic Dental Conditions
The growing aging population significantly contributes to sustained demand in the US Dental Care Market. Older adults exhibit higher incidences of periodontal disease, tooth loss, and oral complications linked to chronic health conditions. Increased life expectancy and improved access to healthcare have led to longer treatment cycles and ongoing dental care needs. This demographic trend drives demand for restorative, periodontal, and therapeutic services, prompting providers to develop specialized geriatric dental care programs and long-term treatment solutions.
Key Trends and Opportunities
Technological Advancements in Dental Procedures and Equipment
Technological advancements represent a major trend and opportunity in the US Dental Care Market. The adoption of digital dentistry solutions such as intraoral scanners, CAD/CAM systems, 3D imaging, and laser-based treatments improves diagnostic accuracy and procedural efficiency. These technologies enhance patient comfort and support minimally invasive care. Dental practices increasingly leverage advanced equipment to optimize workflows, reduce treatment time, and deliver precision-based care, creating opportunities for improved clinical outcomes and service differentiation.
- For instance, Dentsply Sirona's CEREC system with Primescan allows dentists to design, mill, and place crowns in a single appointment, streamlining workflows.
Rising Demand for Cosmetic and Aesthetic Dentistry
Growing consumer focus on aesthetics and self-confidence is creating strong opportunities in the US Dental Care Market. Demand for cosmetic procedures such as teeth whitening, veneers, aligners, and smile correction continues to increase, particularly among younger and working-age populations. Social media influence and rising disposable income further accelerate this trend. Dental clinics are expanding cosmetic service portfolios and integrating advanced materials to deliver natural-looking results, supporting higher patient engagement and revenue growth.
- For instance, Philips stated that its Zoom teeth whitening system has helped brighten over 10 million smiles worldwide, highlighting rising demand for in-office cosmetic treatments.
Key Challenges
High Cost of Advanced Dental Treatments
High treatment costs pose a significant challenge in the US Dental Care Market. Advanced dental procedures, including orthodontics, implants, and cosmetic treatments, often involve substantial out-of-pocket expenses due to limited insurance reimbursement. Rising equipment, material, and labor costs further increase service pricing. These financial barriers restrict access for cost-sensitive patients and may delay elective dental care, impacting treatment continuity and long-term oral health outcomes.
Shortage of Skilled Dental Professionals
The shortage of skilled dental professionals remains a critical challenge in the US Dental Care Market. An aging workforce, lengthy training requirements, and uneven geographic distribution of dentists contribute to access gaps, particularly in rural and underserved areas. Workforce constraints limit clinic expansion and increase operational pressures on existing practices. Addressing this challenge requires expanded dental education programs, workforce incentives, and broader adoption of teledentistry to improve service accessibility.
Regional Analysis
Northeast
The US Dental Care Market in the Northeast accounted for 24.8% market share in 2024, supported by high healthcare spending, strong dental insurance penetration, and a dense concentration of dental clinics and specialists. States such as New York, Massachusetts, and Pennsylvania benefit from advanced dental infrastructure and widespread adoption of preventive dental services. High awareness of oral hygiene, early disease diagnosis, and demand for cosmetic and orthodontic procedures further strengthen market performance. Academic dental institutions and continuous technological adoption also contribute to steady service utilization across both urban and suburban populations.
Midwest
The Midwest held 22.3% market share in 2024 in the US Dental Care Market, driven by a strong base of family dental practices and consistent demand for preventive and corrective dental services. States including Illinois, Ohio, and Michigan exhibit stable patient volumes supported by employer-sponsored dental insurance and public healthcare programs. The region shows high utilization of routine checkups, periodontal care, and restorative treatments. Growing awareness of oral health among aging populations and expanding access in suburban areas further support sustained growth across the Midwest dental care ecosystem.
South
The South dominated the US Dental Care Market with a 31.6% market share in 2024, supported by its large population base and expanding healthcare access. States such as Texas, Florida, and Georgia drive demand through increasing dental clinic networks, rising insurance enrollment, and growing geriatric and pediatric populations. Preventive and therapeutic dental services show strong adoption due to higher incidences of oral health conditions. Rapid urbanization, rising disposable income, and expanding private dental practices contribute to the region’s leadership in overall market revenue.
West
The West accounted for 21.3% market share in 2024 in the US Dental Care Market, driven by strong demand for advanced and cosmetic dental services. California and Washington lead regional growth through high adoption of digital dentistry, orthodontics, and aesthetic procedures. The region benefits from higher healthcare awareness, favorable reimbursement structures, and strong patient preference for preventive care. Technological innovation, growing use of aligners, and emphasis on minimally invasive treatments continue to support steady dental care demand across the western United States.
US Dental Care Market Segmentations:
By Services
- Cosmetic Dentistry
- Endodontic Procedures
- Periodontal Dentistry
- Orthodontic and Periodontic Services
- Diagnostic and Preventive Services
By Application
- Preventive
- Corrective
- Therapeutic
By Geography
- Northeast
- Midwest
- South
- West
Competitive Landscape
Competitive landscape analysis of the US Dental Care Market highlights the presence of major players such as Heartland Dental, Aspen Dental, Pacific Dental Services, Smile Brands, and Dental Care Alliance. The market is moderately fragmented, with large dental service organizations competing alongside independent clinics through extensive service portfolios and geographic reach. Key players focus on expanding clinic networks, enhancing patient experience, and integrating advanced dental technologies to improve clinical efficiency. Strategic acquisitions and partnerships remain central to strengthening regional presence and patient access. Companies are also investing in digital dentistry, standardized clinical protocols, and value-based care models to optimize outcomes. Strong emphasis on preventive, cosmetic, and restorative services enables providers to capture recurring patient visits. Competitive positioning is further shaped by branding, insurance collaborations, and adoption of teledentistry platforms to extend care delivery across urban and underserved regions.
Key Player Analysis
- Heartland Dental
- Aspen Dental
- Pacific Dental Services
- Smile Brands
- Dental Care Alliance
- Great Expressions Dental Centers
- Western Dental & Orthodontics
- Affordable Dentures & Implants
- Midwest Dental
- Kool Smiles
Recent Developments
- In September 2025, Archway Dental Partners partnered with Advanced Dentistry of Scarsdale and Advanced Dentistry of Chappaqua in New York, marking its entry into a second state with enhanced cosmetic offerings.
- In 2025, Patterson Companies completed its acquisition by Patient Square Capital, transitioning to private ownership to support strategic investments in dental products and services.
- In October 2025, Dentsply Sirona partnered with Pearl to deliver AI-assisted radiologic support for 2D X-rays, enhancing diagnostic capabilities for dental professionals.
Report Coverage
The research report offers an in-depth analysis based on Service, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The US Dental Care Market will continue to benefit from rising emphasis on preventive oral healthcare across all age groups.
- Increasing adoption of digital dentistry technologies will improve treatment precision and operational efficiency.
- Growing demand for cosmetic and aesthetic dental procedures will support higher patient engagement.
- Expansion of dental service organizations will enhance access to standardized and scalable dental care services.
- Technological integration such as artificial intelligence will strengthen diagnostics and personalized treatment planning.
- Rising geriatric population will sustain demand for restorative and periodontal dental services.
- Insurance coverage expansion will encourage more frequent dental visits and early-stage treatments.
- Teledentistry adoption will improve access to care in rural and underserved regions.
- Workforce optimization and expanded roles for dental hygienists will support service delivery capacity.
- Focus on patient-centric care models will improve long-term retention and overall treatment outcomes.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the US Dental Care Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the US Dental Care Market projected to grow between 2024 and 2032?
Which US Dental Care Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the US Dental Care Market?
Who are the leading companies in the US Dental Care Market?
Which region commanded the largest share of the US Dental Care Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 US Dental Care Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global US Dental Care Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 166,095 million → 2032: USD 247,273.6 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 US Dental Care Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. US Dental Care Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 US Dental Care Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 US Dental Care Market Drivers
- 3.3 US Dental Care Market Restraints & Challenges
- 3.4 US Dental Care Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 US Dental Care Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 US Dental Care Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, US Dental Care category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 US Dental Care Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. US Dental Care Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the US Dental Care market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 US Dental Care Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 US Dental Care Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 US Dental Care Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in US Dental Care (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New US Dental Care Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global US Dental Care Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America US Dental Care Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe US Dental Care Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific US Dental Care Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America US Dental Care Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East US Dental Care Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa US Dental Care Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. US Dental Care Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
