
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| U.S. Large Language Model Powered Tools Market Size 2023 | USD 395.41 million |
| U.S. Large Language Model Powered Tools Market, CAGR | 45.74% |
| U.S. Large Language Model Powered Tools Market Size 2032 | USD 11,728.53 million |
Market Overview
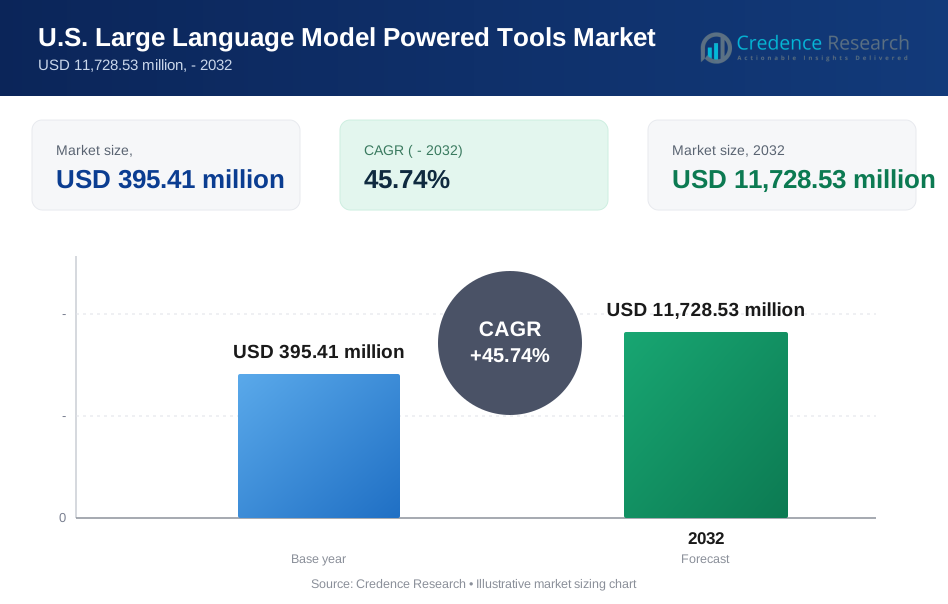
The U.S. Large Language Model Powered Tools Market is projected to grow from USD 395.41 million in 2023 to an estimated USD 11,728.53 million by 2032, with a compound annual growth rate (CAGR) of 45.74% from 2024 to 2032. The market’s expansion is driven by the increasing integration of advanced AI models into business processes and consumer applications.
The key market drivers include rapid advancements in artificial intelligence, increased investments in machine learning technologies, and the expanding use of natural language processing (NLP) solutions. Furthermore, businesses are seeking efficient ways to streamline operations, reduce operational costs, and enhance customer experiences, contributing to the demand for large language model-powered tools. As the adoption of cloud computing and AI technologies grows, so does the need for more scalable and efficient language models.
Geographically, the U.S. remains a dominant player in the Large Language Model Powered Tools Market, with high adoption rates across various sectors including technology, finance, and government. Leading players in this market include OpenAI, Google DeepMind, and Anthropic, who are at the forefront of developing and deploying state-of-the-art language models. These companies are driving innovation and setting new benchmarks for AI-powered tools.
Market Insights
- The market is projected to grow from USD 395.41 million in 2023 to USD 11,728.53 million by 2032, with a CAGR of 45.74% from 2024 to 2032.
- Rapid advancements in artificial intelligence and machine learning technologies are accelerating the adoption of large language models across industries.
- Growing demand for automation in sectors like customer service, healthcare, and education is fueling the adoption of AI-powered language tools.
- Data privacy and security concerns remain a challenge, particularly in highly regulated industries like healthcare and finance.
- Inherent biases in large language models can affect the accuracy and fairness of outcomes, presenting an obstacle to widespread adoption.
- California leads the market with a 40% market share, driven by its concentration of tech giants and AI research institutions.
- Texas and New York are also key regions, benefiting from tech growth, industrial demand, and innovation in AI applications.
Market Drivers
Rapid Advancements in Artificial Intelligence and Machine Learning
The ongoing evolution of artificial intelligence (AI) and machine learning (ML) stands as a primary driver fueling the growth of the U.S. Large Language Model Powered Tools Market. AI and ML technologies have made significant strides, particularly in natural language processing (NLP), a core component of large language models. These advancements have enabled machines to understand, process, and generate human language with high accuracy, making them increasingly useful across applications, from customer service chatbots to content generation tools. For instance, Google introduced BERT in 2018, a natural language processing model that understands context from the left and right sides of a word. Major players in the tech industry continuously refine their algorithms and expand the capabilities of language models. The market is witnessing an influx of innovative solutions that address the needs of businesses and consumers. This continuous innovation is expected to maintain the market's growth momentum, particularly as companies across sectors look for ways to leverage AI to enhance productivity, improve operational efficiency, and gain a competitive edge.
Increasing Demand for Automation in Business Operations
Another significant driver of market growth is the increasing demand for automation in business operations. In an increasingly digital and competitive business environment, companies seek ways to optimize processes, reduce manual efforts, and minimize human errors. Large language model-powered tools are uniquely positioned to address these needs by automating tasks such as customer support, content creation, data analysis, and even code generation. For instance, an AI-powered bot integrated with Shopify acted as a virtual shopping assistant and helped an electronics manufacturer achieve an 84% session engagement rate. AI-driven virtual assistants and chatbots can handle customer queries 24/7, providing efficient service while reducing the need for human intervention. In industries such as healthcare, finance, and retail, where the volume of data and customer interactions is high, the ability to automate routine tasks can significantly lower operational costs and improve overall service quality. As businesses realize the potential of these tools to streamline operations, the demand for language model-powered automation solutions is expected to rise, further driving market growth.
Growing Adoption of Cloud Computing and Scalable AI Solutions
The widespread adoption of cloud computing is another key factor accelerating the growth of the U.S. Large Language Model Powered Tools Market. The cloud offers scalability, flexibility, and cost-efficiency, enabling businesses to deploy large language models without the need for extensive on-premises infrastructure. Cloud service providers such as Amazon Web Services (AWS), Microsoft Azure, and Google Cloud have significantly expanded their AI and ML offerings, allowing companies of all sizes to access and implement large language models with minimal investment in hardware. For instance, cloud service providers offer AI-powered tools and frameworks that allow businesses to integrate AI into their applications and workflows seamlessly. Cloud-based solutions also enable seamless updates, scalability, and real-time performance, making them attractive for companies that need to process vast amounts of data or support large user bases. This accessibility has democratized the use of advanced language models, empowering small and medium-sized enterprises (SMEs) to leverage AI tools previously reserved for large organizations with significant resources. As cloud adoption continues to grow across industries, the demand for scalable and efficient AI-powered tools is expected to rise, propelling the market forward.
Expanding Applications Across Various Industry Verticals
The versatility of large language model-powered tools is a critical driver behind their increasing adoption across diverse industry verticals. These tools are not limited to just one sector; instead, they are finding use cases in a wide range of industries, including healthcare, finance, retail, legal, education, and more. For instance, H&M uses AI chatbots to help customers find products and offer size recommendations. In healthcare, AI-powered language models can assist in medical research, generate reports from clinical data, and support patient interaction through virtual health assistants. In finance, these models are used for fraud detection, risk analysis, and customer service automation. Legal professionals are leveraging AI to assist in document review, case analysis, and legal research, while in education, language models are being used to create personalized learning experiences and educational content. As businesses in these sectors increasingly realize the potential of large language models to improve efficiency, reduce costs, and drive innovation, the market for AI-powered tools will continue to expand. Moreover, as new applications emerge and technology matures, the scope of these tools' usage will likely broaden, presenting new opportunities for growth in the market.
Market Trends
Integration of Multimodal AI Capabilities
One of the prominent trends in the U.S. Large Language Model Powered Tools Market is the increasing integration of multimodal capabilities into language models. Multimodal AI refers to the ability of a system to process and generate content across multiple forms of data, such as text, images, videos, and audio. While traditional language models have primarily focused on text-based inputs and outputs, advancements are enabling models to understand and generate content that incorporates diverse types of media. This integration allows organizations to leverage AI for more dynamic applications, such as generating captions for videos, summarizing long-form content with relevant images, or even interpreting complex queries that involve both visual and textual information. For instance, OpenAI’s GPT-4 has demonstrated capabilities in understanding and generating multimodal content, setting a new benchmark for the industry. The growth of multimodal AI not only increases the scope of use cases but also enhances the accuracy and relevance of the responses provided by language models. As companies across various sectors—from e-commerce to entertainment—seek to provide richer user experiences, multimodal AI is becoming an essential component of the large language model-powered tools market.
Shift Towards Domain-Specific Language Models
Another significant trend in the U.S. Large Language Model Powered Tools Market is the shift toward domain-specific language models tailored to the needs of specific industries or business functions. While general-purpose language models, such as GPT-3, can be applied across a wide range of tasks, organizations are increasingly recognizing the value of models fine-tuned to address the unique language and requirements of specific sectors. This trend is particularly evident in industries such as healthcare, finance, law, and customer service, where domain-specific expertise is crucial. For example, healthcare organizations are developing AI models specifically trained on medical literature and clinical data to enhance diagnostics, research, and patient communication. In the financial sector, language models trained on financial data can assist with tasks such as sentiment analysis, fraud detection, and market predictions. Similarly, the legal industry is adopting specialized models for tasks such as contract review and legal research. By focusing on a narrower scope, domain-specific language models can improve accuracy, reduce the risk of misinterpretation, and provide deeper insights, leading to more efficient processes and better outcomes. The growing availability of industry-specific language models is creating new opportunities for market players and encouraging further investment in AI research and development.
Focus on Ethical AI and Regulation Compliance
Ethical AI practices and regulatory compliance are emerging as critical trends within the U.S. Large Language Model Powered Tools Market, driven by concerns about privacy, fairness, and transparency in AI systems. As large language models become more widely adopted, there is increasing scrutiny regarding their potential to perpetuate biases, generate harmful content, or infringe upon user privacy. To address these challenges, companies are focusing on developing and deploying AI models that adhere to ethical guidelines and regulatory frameworks. In the U.S., this has been particularly relevant with growing discussions around GDPR, CCPA, and other data protection regulations that mandate the responsible use of AI technologies. Additionally, organizations are implementing measures to mitigate biases in training datasets, ensuring that their language models do not favor certain groups or generate discriminatory content. Transparency has also become a key focus, with many companies working to make their AI systems more explainable and auditable. This trend is particularly important in sensitive sectors such as healthcare and finance, where the consequences of biased or inaccurate AI-driven decisions can have significant implications. As regulatory bodies continue to tighten regulations around AI usage, companies must navigate these complexities and adopt ethical AI practices, which is driving the development of more responsible and compliant large language model tools.
Increased Collaboration Between Tech Giants and Startups
The growing demand for advanced large language model-powered tools is fostering increased collaboration between established tech giants and innovative startups. Companies such as Google, Microsoft, and Amazon are actively partnering with smaller AI startups to accelerate the development and commercialization of cutting-edge language models. These collaborations are beneficial for both parties—large tech companies bring substantial resources, cloud infrastructure, and data, while startups contribute innovative approaches, niche expertise, and agility. For example, Microsoft’s partnership with OpenAI has resulted in the integration of GPT-3 into Microsoft products, such as Microsoft Word and Azure, while Google has collaborated with various AI-focused startups to improve its natural language processing capabilities. These partnerships also help drive industry standards and best practices, while enabling faster time-to-market for new products. Startups, in particular, are playing a critical role in pushing the boundaries of large language model applications, often focusing on specialized use cases and emerging sectors. As these collaborations continue to evolve, they are expected to further accelerate the development of next-generation AI technologies and expand the market for large language model-powered tools.
Market Challenges
Data Privacy and Security Concerns
One of the primary challenges facing the U.S. Large Language Model Powered Tools Market is the growing concern over data privacy and security. As these tools rely on vast amounts of data to train their models, the risk of data breaches, misuse of sensitive information, and potential violations of data protection laws such as GDPR and CCPA becomes a significant issue. In industries like healthcare, finance, and legal services, where customer data is highly sensitive, ensuring the confidentiality and security of the information processed by AI systems is paramount. The complexity of safeguarding data in AI applications arises from the need to strike a balance between collecting sufficient data for training large language models and adhering to privacy regulations. Additionally, the increasing number of cyberattacks targeting AI systems compounds the vulnerability of these tools. Organizations must implement robust data protection measures, such as encryption, access controls, and data anonymization, to mitigate these risks. Failure to address these challenges could result in regulatory fines, loss of customer trust, and reputational damage, posing significant obstacles to the broader adoption of large language model-powered tools.
Bias and Ethical Implications of AI Models
Another critical challenge in the U.S. Large Language Model Powered Tools Market is addressing the inherent biases present in many AI models. Large language models are trained on vast datasets sourced from the internet, which may contain biased or discriminatory language and information. As a result, these models can unintentionally generate outputs that reflect societal biases, such as gender, racial, or cultural biases, which can lead to ethical concerns. In applications like hiring, customer service, and content moderation, biased outputs can have far-reaching consequences, from reinforcing stereotypes to perpetuating unfair practices. Ensuring that AI systems are fair, transparent, and unbiased is a significant challenge that requires ongoing efforts to curate diverse training datasets, implement bias mitigation techniques, and establish ethical guidelines. Moreover, there is increasing pressure from regulators, stakeholders, and the public for companies to adopt responsible AI practices, making the need for unbiased, ethically sound models more urgent. The ability to create language models that are both highly accurate and free of bias remains a major challenge for companies in the market.
Market Opportunities
Expansion of AI Applications Across Industry Verticals
A significant market opportunity for the U.S. Large Language Model Powered Tools Market lies in the expansion of AI applications across diverse industry verticals. As businesses increasingly recognize the potential of language models to optimize operations, enhance customer experiences, and drive innovation, new use cases are emerging in sectors such as healthcare, finance, legal, retail, and education. In healthcare, for example, AI models can assist in medical research, patient communication, and clinical decision-making. In finance, language models are being used for sentiment analysis, fraud detection, and customer service automation. With industries exploring tailored AI solutions to address specific challenges, the demand for specialized large language models will continue to grow. As organizations across these sectors prioritize digital transformation and operational efficiency, large language model-powered tools represent a valuable opportunity to meet evolving market needs.
Advancements in Multimodal and Domain-Specific Models
The growing development of multimodal and domain-specific large language models presents another significant opportunity in the market. While general-purpose language models are versatile, there is increasing demand for models that are fine-tuned for specific tasks or industries. The ability to create domain-specific models that cater to healthcare, legal, and finance sectors allows companies to offer more accurate, efficient, and relevant solutions. Furthermore, as multimodal AI tools evolve, businesses have the opportunity to enhance user engagement by combining text, images, and video in more interactive and dynamic ways. The continued advancements in both multimodal and industry-specific AI models will open new market segments and unlock untapped opportunities for growth within the U.S. large language model-powered tools market.
Market Segmentation Analysis
By Type
Large Language Model (LLM) tools are categorized into three primary types based on their functionality and application. General Purpose LLM Tools are versatile solutions designed to handle a broad spectrum of tasks across industries. These tools are not specialized for any particular domain but instead cater to multiple applications such as text generation, question answering, and summarization. Their adaptability makes them highly sought-after across various sectors. Domain-Specific LLM Tools, on the other hand, are tailored for particular industries, including healthcare, finance, and legal services. These tools address the unique challenges of their respective fields by offering industry-specific solutions. For instance, in healthcare, LLMs can assist in processing medical records and providing clinical decision support. Lastly, Task-Specific LLM Tools are optimized for precise functions such as content generation, sentiment analysis, and language translation. These tools are designed to maximize efficiency and accuracy for their designated tasks, making them highly effective for businesses with specialized needs.
By Deployment Mode
LLM-powered tools are deployed through two main modes: on-premise and cloud-based solutions. On-premise deployment is favored by organizations that prioritize data security, control over infrastructure, and compliance with regulatory requirements. Large enterprises operating in highly regulated industries, such as banking and healthcare, often prefer this model due to the need for strict data governance and integration with internal systems. Conversely, cloud-based deployment is becoming increasingly popular due to its scalability, cost-effectiveness, and ease of access. Businesses can leverage cloud-hosted LLM tools without substantial upfront infrastructure investments. Cloud solutions also facilitate faster updates, seamless integration with other digital tools, and improved flexibility, making them ideal for companies looking to enhance operational efficiency and innovation.
Segments
Based on Type
- General Purpose LLMs Tools
- Domain-Specific LLMs Tools
- Task-Specific LLMs Tools
Based on Deployment Mode
- On-Premise
- Cloud
Based on Application
- Content Generation
- Customer Support
- Data Analysis and Insights
- Language Translation
- Education and Training
- Personalization
- Others
Based on Region
- California
- New York
- Texas
Regional Analysis
California (40%)
California, home to Silicon Valley, remains the dominant region in the U.S. Large Language Model Powered Tools Market, accounting for approximately 40% of the total market share. The state hosts some of the world’s leading tech companies, including Google, Apple, and Meta, alongside AI research institutions. These companies and their constant push for innovation have led to high investments in AI, particularly in natural language processing (NLP) and machine learning models. Additionally, California's strong startup ecosystem and venture capital backing contribute significantly to the growth of AI-driven solutions. The state is expected to maintain its leading position as it continues to serve as a global hub for technology and AI development
New York (20%)
New York ranks second, with 20% of the market share. As a major financial and business center, New York benefits from the growing need for AI tools in sectors such as finance, healthcare, and media. The financial sector, in particular, leverages large language models for applications like fraud detection, sentiment analysis, and market predictions. Moreover, New York's diverse industrial base fosters demand for AI-powered solutions in content generation, data analysis, and customer support. The region's strong focus on technological innovation and its proximity to global business networks make it a key player in the market.
Key players
- OpenAI, LLC
- Anthropic
- Stability AI
- Cohere
- Hugging Face
- Meta Platforms Inc.
- Amazon Web Services Inc.
- Salesforce, Inc.
- Hewlett Packard Enterprise Company
- NVIDIA Corporation
- Jasper AI Inc.
- Google LLC (Alphabet Inc.)
- Oracle Corporation
- IBM Corporation
Competitive Analysis
The U.S. Large Language Model Powered Tools Market is highly competitive, with several established players and emerging startups vying for market share. OpenAI, Google LLC, and Meta Platforms Inc. are at the forefront, leading the market with advanced AI models like GPT-3 and BERT, which are widely recognized for their versatile and powerful capabilities. NVIDIA Corporation provides critical hardware infrastructure that powers many of these large language models, positioning itself as an essential player in the AI ecosystem. Amazon Web Services and IBM Corporation are focusing on cloud-based AI solutions, capitalizing on the growing demand for scalable, cloud-deployed models. Meanwhile, Anthropic, Cohere, and Hugging Face are making strides in specialized AI, focusing on fine-tuning language models for specific industry applications. As the market grows, competition will intensify, with companies differentiating themselves based on model capabilities, scalability, and industry-specific solutions.
Recent Developments
- In January 2025 OpenAI expanded access to its large language models to all 17 of the Department of Energy’s National Laboratories.
- In June 2024, Anthropic released Claude 3.5 Sonnet, the first release of the new Claude 3.5 model family, outperforming GPT-4o in coding and text reasoning, while maintaining a larger context window at a lower cos.
- In January 2024, Stability AI released Stable LM 2, including 12B (12 billion parameters) and 1.6B (1.6 billion parameters) models.
Market Concentration and Characteristics
The U.S. Large Language Model Powered Tools Market is characterized by a moderately concentrated competitive landscape, with a mix of established technology giants and emerging startups. Major players like OpenAI, Google LLC, Meta Platforms Inc., and Amazon Web Services Inc. dominate the market, leveraging their advanced AI research, vast computational resources, and large-scale cloud platforms to deliver robust and scalable language model solutions. At the same time, companies such as Anthropic, Cohere, and Hugging Face are carving out a niche by focusing on specialized, domain-specific models and innovations in natural language processing. While the market is still maturing, the rapid pace of technological advancements and the increasing demand for AI-driven automation across industries is driving both competition and collaboration, fostering continuous innovation. As such, the market remains dynamic with significant potential for growth, particularly for companies that can offer tailored, efficient, and scalable language model solutions.
Report Coverage
The research report offers an in-depth analysis based on Type, Deployment Mode, Application, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to experience sustained growth, with the increasing adoption of AI tools across industries driving demand. By 2032, the market is projected to expand significantly, reaching an estimated USD 11,728.53 million.
- The development of domain-specific large language models will accelerate, addressing unique needs in sectors like healthcare, finance, and legal. This trend will enhance the accuracy and relevance of AI-powered tools in specialized applications.
- Businesses will increasingly adopt large language models to streamline operations and improve decision-making. Automation in areas like customer service, data analysis, and content generation will be key to improving productivity.
- AI tools will evolve to integrate multimodal capabilities, combining text, images, and videos to create more dynamic and interactive user experiences. This will broaden the scope of applications and enhance tool versatility.
- As regulatory frameworks evolve, companies will focus more on ensuring their AI models are ethical, transparent, and free of bias. This will be essential for ensuring consumer trust and regulatory compliance.
- Cloud deployments of large language models will dominate, providing businesses with scalable, cost-effective solutions. The flexibility and ease of integration offered by cloud services will drive widespread adoption.
- Partnerships between large tech companies and startups will foster innovation, leading to the development of more advanced AI models and quicker time-to-market for new tools. This collaboration will help propel the market forward.
- Personalization will become a key application of language models, enabling businesses to offer tailored content, recommendations, and services. The need for more customized user experiences will increase demand for AI-powered solutions.
- As AI becomes more integrated into everyday business functions, ensuring responsible AI practices will be crucial. This includes transparent decision-making processes and ensuring that AI models are aligned with societal values.
- With growing demand, the market will see more entrants and increased competition. This will lead to fragmentation, with companies differentiating themselves through specialized models, technological innovation, and value-added services.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the U.S. Large Language Model Powered Tools Market in 2023 and 2032?
What are the key drivers of the U.S. Large Language Model Powered Tools Market?
What industries are contributing to the growth of the market?
What are the benefits of using large language model-powered tools?
Who are the key players in the U.S. Large Language Model Powered Tools Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Large Language Model Powered Tools Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global U.S. Large Language Model Powered Tools Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 395.41 million → 2032: USD 11,728.53 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Large Language Model Powered Tools Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Large Language Model Powered Tools Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Large Language Model Powered Tools Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 U.S. Large Language Model Powered Tools Market Drivers
- 3.3 U.S. Large Language Model Powered Tools Market Restraints & Challenges
- 3.4 U.S. Large Language Model Powered Tools Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Large Language Model Powered Tools Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Large Language Model Powered Tools Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Large Language Model Powered Tools category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Large Language Model Powered Tools Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. U.S. Large Language Model Powered Tools Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the U.S. Large Language Model Powered Tools market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Large Language Model Powered Tools Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 U.S. Large Language Model Powered Tools Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 U.S. Large Language Model Powered Tools Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Large Language Model Powered Tools (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New U.S. Large Language Model Powered Tools Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global U.S. Large Language Model Powered Tools Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America U.S. Large Language Model Powered Tools Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe U.S. Large Language Model Powered Tools Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific U.S. Large Language Model Powered Tools Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America U.S. Large Language Model Powered Tools Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East U.S. Large Language Model Powered Tools Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa U.S. Large Language Model Powered Tools Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. U.S. Large Language Model Powered Tools Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
