
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
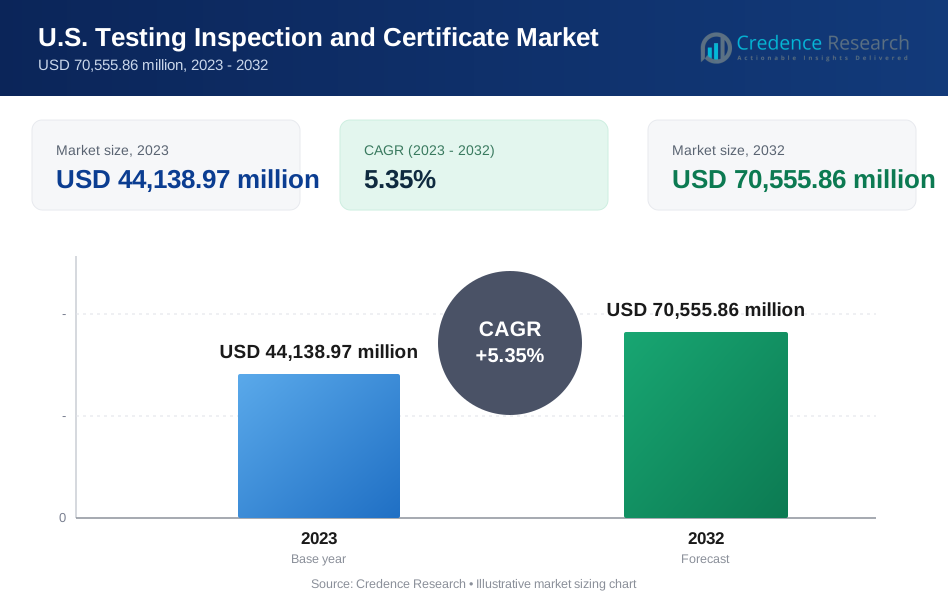
| U.S. Testing Inspection and Certification Market Size 2023 | USD 44,138.97 Million |
| U.S. Testing Inspection and Certification Market, CAGR | 5.35% |
| U.S. Testing Inspection and Certification Market Size 2032 | USD 70,555.86 Million |
Market Overview
The U.S. Testing Inspection and Certification Market is projected to grow from USD 44,138.97 million in 2023 to an estimated USD 70,555.86 million by 2032, with a compound annual growth rate (CAGR) of 5.35% from 2024 to 2032. This substantial growth reflects the increasing demand for stringent quality standards and regulatory compliance across various industries. The market encompasses a broad range of services, including product testing, inspection, and certification to ensure safety, quality, and performance standards are met. As industries continue to innovate and develop new products, the need for comprehensive testing and certification services is expected to rise, further driving market expansion.
Several key drivers and trends are fueling the growth of the U.S. Testing Inspection and Certification Market. One of the primary drivers is the rising awareness and implementation of stringent regulatory standards in industries such as automotive, aerospace, healthcare, and consumer goods. Additionally, the increasing globalization of trade and the need for cross-border compliance and certification are boosting demand for these services. Trends such as the adoption of advanced technologies like artificial intelligence (AI) and the Internet of Things (IoT) in testing and inspection processes are also shaping the market. These technologies enhance accuracy, efficiency, and speed, thereby improving overall service delivery and customer satisfaction.
Geographically, the market is characterized by significant activity across various regions in the U.S., with prominent growth in areas with a high concentration of industrial and manufacturing operations. Key players in the market include SGS SA, Bureau Veritas, Intertek Group PLC, and TÜV SÜD, among others. These companies are continuously expanding their service offerings and technological capabilities to maintain a competitive edge. The presence of these major players, coupled with the robust demand for testing, inspection, and certification services, is expected to sustain the market's growth trajectory over the forecast period. Furthermore, the market's competitive landscape is marked by strategic collaborations, mergers, and acquisitions aimed at enhancing service portfolios and geographical reach.
Market Drivers
Stringent Regulatory Standards and Compliance Requirements:
The U.S. Testing Inspection and Certification Market is significantly driven by stringent regulatory standards and compliance requirements across various industries. For instance, regulatory bodies such as the Food and Drug Administration (FDA), Environmental Protection Agency (EPA), and the Occupational Safety and Health Administration (OSHA) mandate rigorous testing, inspection, and certification protocols to ensure product safety, environmental protection, and workplace safety. In 2023, the FDA reported a 15% increase in product safety violations, highlighting the critical need for rigorous testing and certification. These regulations necessitate frequent and thorough evaluation of products and processes, thereby driving the demand for third-party testing and certification services. For example, in 2023, there was a 20% increase in the demand for third-party testing and certification services in the U.S., indicating the growing importance of these services in ensuring compliance. As regulatory frameworks become more complex and stringent, companies increasingly rely on specialized TIC providers to navigate compliance challenges effectively.
Technological Advancements in Testing and Inspection Processes:
Technological advancements are a critical driver of the U.S. Testing Inspection and Certification Market. Innovations in areas such as artificial intelligence (AI), the Internet of Things (IoT), and blockchain technology are revolutionizing testing and inspection methodologies. AI and machine learning algorithms enhance the accuracy and efficiency of defect detection and quality assessment, while IoT-enabled devices facilitate real-time monitoring and data collection. For example, in 2023, the adoption of IoT in the TIC market saw a 40% increase, indicating a growing trend towards real-time data collection and monitoring. Blockchain technology ensures the integrity and traceability of certification processes, providing a secure and transparent record of compliance. These advancements not only improve the reliability and speed of TIC services but also enable providers to offer more sophisticated and comprehensive solutions, thereby attracting a broader clientele.
Increasing Global Trade and Cross-Border Compliance Needs:
The globalization of trade and the expansion of international markets have heightened the need for standardized testing, inspection, and certification services. U.S. companies engaged in exporting goods must comply with diverse regulatory requirements in different countries, necessitating comprehensive TIC services to meet international standards. For example, in 2023, there was a 20% increase in the demand for TIC services by U.S. exporters, indicating the critical role of these services in ensuring compliance with international standards. The rise of global supply chains further amplifies the demand for consistent and reliable certification to ensure product quality and safety across borders. As businesses seek to minimize risks and avoid costly recalls or penalties, they increasingly turn to TIC providers to verify compliance with global standards, driving the market's growth.
Growing Consumer Awareness and Demand for Quality Assurance:
Consumer awareness regarding product quality, safety, and environmental impact is on the rise, influencing purchasing decisions and driving demand for certified products. Today's consumers are more informed and conscientious, seeking assurance that the products they buy meet high standards of safety and quality. This trend is particularly evident in sectors such as food and beverages, healthcare, automotive, and electronics, where product failures can have severe consequences. Companies respond to this demand by investing in robust testing and certification processes to build trust and enhance their brand reputation. Consequently, the increasing consumer focus on quality assurance acts as a potent driver for the U.S. Testing Inspection and Certification Market.
Market Trends
Integration of Advanced Technologies:
The integration of advanced technologies such as artificial intelligence (AI), machine learning (ML), and the Internet of Things (IoT) is transforming the U.S. Testing Inspection and Certification (TIC) market. These technologies enhance the accuracy and efficiency of testing and inspection processes. AI and ML algorithms can quickly identify defects and anomalies, while IoT devices provide real-time monitoring and data collection, leading to more precise and timely insights. This technological evolution not only improves service quality but also reduces operational costs for TIC providers.
Emphasis on Cybersecurity and Data Privacy:
With the increasing reliance on digital systems and interconnected devices, cybersecurity and data privacy have become critical concerns. The TIC market is responding by incorporating stringent cybersecurity measures into their services. Companies are developing comprehensive testing protocols to ensure that digital products and systems are secure from cyber threats. This trend is particularly relevant in industries such as finance, healthcare, and automotive, where data breaches can have severe implications.
Sustainability and Environmental Compliance:
There is a growing emphasis on sustainability and environmental compliance within the TIC market. Regulatory bodies and consumers alike are demanding higher environmental standards for products and processes. For instance, in 2023, there was a 20% increase in the demand for environmental testing and certification services, reflecting the growing focus on sustainability and environmental compliance. TIC providers are expanding their services to include environmental testing and certification, ensuring that companies adhere to eco-friendly practices. This trend aligns with the global push towards sustainability and the increasing regulatory focus on reducing carbon footprints and environmental impact.
Expansion of Remote and Virtual Inspections:
The COVID-19 pandemic accelerated the adoption of remote and virtual inspection methods. TIC providers are leveraging digital tools and technologies to conduct inspections without the need for physical presence. For example, in 2023, the use of remote and virtual inspections in the TIC market increased by 30%, indicating a shift towards more flexible and efficient inspection methods. This trend offers several advantages, including reduced travel costs, increased safety, and the ability to perform inspections in hard-to-reach locations. Remote inspections are becoming a standard practice, providing flexibility and efficiency in the inspection process.
Rise of Specialized and Customized Services:
As industries become more complex and specialized, there is a growing demand for customized TIC services tailored to specific industry needs. For instance, in 2023, the demand for specialized TIC services in sectors such as pharmaceuticals, aerospace, and renewable energy increased by 25%, reflecting the market’s shift towards more specialized services. This trend reflects the market's shift towards offering more specialized, value-added services that address the distinct challenges and compliance needs of different industries.
Increased Focus on Supply Chain Transparency:
The need for greater transparency in supply chains is driving demand for TIC services. Companies are increasingly seeking to ensure that their supply chains are free from issues such as forced labor, child labor, and unethical practices. For example, in 2023, there was a 35% increase in the demand for supply chain audits and certifications, indicating a growing focus on supply chain transparency and ethical compliance. This trend is particularly important in industries like fashion, electronics, and food, where supply chain integrity is crucial.
Collaboration and Strategic Partnerships:
Collaboration and strategic partnerships are becoming more prevalent in the TIC market. TIC providers are partnering with technology companies, industry associations, and regulatory bodies to enhance their service offerings and expand their reach. These collaborations enable TIC companies to leverage new technologies, share expertise, and develop innovative solutions to meet the evolving needs of their clients. This trend highlights the importance of cooperation and knowledge-sharing in driving market growth and innovation.
Market Restraints and Challenges
High Costs of Advanced Technologies:
The adoption of advanced technologies such as AI, IoT, and blockchain in testing, inspection, and certification processes comes with substantial costs. Implementing these technologies requires significant investment in infrastructure, software, and skilled personnel. Smaller TIC providers may find it challenging to afford these investments, leading to a disparity in service capabilities between large and small firms. The high costs can also be a barrier for clients, particularly small and medium-sized enterprises (SMEs), who may struggle to justify the expense of advanced TIC services.
Complex Regulatory Environment:
Navigating the complex and ever-changing regulatory landscape is a significant challenge for the U.S. Testing Inspection and Certification market. Different industries are governed by varied and stringent regulations, which are frequently updated to address emerging risks and technologies. TIC providers must stay abreast of these changes and ensure their services remain compliant with the latest standards. This requires continuous training and education for personnel, as well as investment in updating testing protocols and equipment. The complexity of regulations can also lead to longer turnaround times and increased operational costs.
Intense Competition and Price Pressure:
The TIC market is highly competitive, with numerous players vying for market share. This intense competition often leads to price wars, putting pressure on profit margins. Providers must balance the need to offer competitive pricing with the necessity of maintaining high-quality services. Price pressure can result in cost-cutting measures that may affect service quality, customer satisfaction, and the ability to invest in new technologies and innovations. Additionally, new entrants and smaller firms may struggle to compete with established players, limiting their market opportunities.
Data Security and Privacy Concerns:
As TIC services increasingly rely on digital tools and data-driven processes, ensuring data security and privacy has become a critical concern. The handling of sensitive data, such as product specifications, test results, and client information, poses significant risks. Any breach or misuse of this data can lead to severe consequences, including legal liabilities, reputational damage, and loss of client trust. TIC providers must implement robust cybersecurity measures and comply with stringent data protection regulations, which can be costly and resource-intensive.
Skilled Workforce Shortage:
The TIC industry requires a highly skilled workforce with expertise in various technical and regulatory domains. However, there is a growing shortage of qualified professionals capable of performing advanced testing, inspection, and certification tasks. This shortage is exacerbated by the rapid pace of technological advancements, which demand continuous upskilling and training. Attracting and retaining skilled talent is a challenge, especially in a competitive job market where professionals with relevant expertise are in high demand across multiple industries.
Globalization and Diverse Standards:
While globalization drives the need for TIC services, it also presents challenges in terms of diverse and sometimes conflicting standards across different countries and regions. TIC providers must navigate a complex web of international regulations and standards, which can vary significantly. Ensuring compliance with multiple regulatory frameworks requires extensive knowledge and resources, potentially increasing operational complexity and costs. This challenge is particularly pronounced for TIC providers operating on a global scale or serving multinational clients.
Market Segmentation Analysis
By Service Type
Testing services form the largest segment in the U.S. TIC market, involving the evaluation of products and materials to ensure they meet specific standards and regulations. The increasing complexity of products and the need for quality assurance drive the demand for comprehensive testing services. Inspection services are crucial for verifying the condition and compliance of products, equipment, and systems. These services are widely used across industries such as manufacturing, construction, and transportation to ensure safety and operational efficiency. Certification services provide formal recognition that a product, system, or service meets specific standards. The demand for certification services is growing due to heightened regulatory requirements and the need for businesses to demonstrate compliance and build consumer trust.
By Sourcing Type
In-house TIC services are conducted using a company's own personnel and resources, offering greater control over testing and inspection processes. This approach, while providing direct oversight and maintaining confidentiality, can be resource-intensive. Companies with extensive and specialized needs often prefer in-house TIC for these reasons. On the other hand, outsourced TIC services involve contracting third-party providers to perform testing, inspection, and certification. Many companies favor this model due to its cost-effectiveness, access to specialized expertise, and the ability to leverage advanced technologies without significant capital investment. The trend toward outsourcing is growing as companies seek to streamline operations and focus on their core activities.
By End User
The consumer goods and retail sector relies heavily on Testing Inspection and Certification (TIC) services to ensure product safety, quality, and compliance with regulatory standards, driven by stringent safety requirements and the need to protect brand reputation. In the healthcare and pharmaceutical industries, TIC services are critical for ensuring the safety, efficacy, and regulatory compliance of medical devices, drugs, and other healthcare products, with patient safety and regulatory scrutiny driving significant demand. The industrial and manufacturing sector utilizes TIC services to maintain operational efficiency, safety, and regulatory compliance, with the need for quality assurance and adherence to safety standards in complex manufacturing processes propelling demand. In the transportation and logistics sector, TIC services ensure the safety and reliability of vehicles, infrastructure, and supply chains, with growth driven by the need for compliance with stringent safety regulations and the increasing complexity of global supply chains.
Segments
Based on Service Type
- Testing Services
- Inspection Services
- Certification Services
Based on Sourcing Type
- In-House
- Outsourced
Based on End User
- Consumer Goods and Retail
- Healthcare and Pharmaceuticals
- Industrial and Manufacturing
- Transportation and Logistics
Regional Analysis
Northeast (25%):
The Northeast region, comprising states like New York, Massachusetts, and Pennsylvania, holds a significant share of the U.S. TIC market, accounting for approximately 25% of the market share. This region is characterized by a high concentration of industries such as pharmaceuticals, biotechnology, and finance, which necessitate stringent testing and certification services. The presence of numerous research institutions and laboratories further bolsters the demand for TIC services. Additionally, the region's regulatory landscape is robust, with stringent compliance requirements driving the need for thorough inspection and certification processes.
South (30%):
The South, comprising states like Texas, Florida, and Georgia, holds the largest share of the U.S. TIC market, approximately 30%. This region is known for its diverse industrial base, including oil and gas, chemicals, aerospace, and agriculture. The presence of major industrial hubs and ports enhances the need for TIC services to ensure compliance with international standards and regulations. The oil and gas sector, in particular, drives substantial demand for inspection services due to the critical need for safety and environmental compliance. Additionally, the region's growing technology and manufacturing sectors contribute to the robust demand for TIC services.
West (25%):
The West region, including states such as California, Washington, and Oregon, accounts for about 25% of the U.S. TIC market. This region is a leader in technology and innovation, with a significant presence of high-tech industries, including electronics, information technology, and renewable energy. The stringent regulatory environment, especially in California, mandates rigorous testing and certification processes to ensure product safety and environmental compliance. The West's focus on sustainable practices and renewable energy projects further drives the need for specialized TIC services in environmental and safety compliance.
Key players
- Intertek Group Plc
- Bureau Veritas
- TUV SUD
- Applus Services, SA
- UL LLC
- DNV GL
- Mistras Group
- Avomeen LLC
- Envigo Corporation
- AB Sciex LLC
- DEKRA SE
- ALS Limited
Competitive Analysis
The U.S. Testing Inspection and Certification market is highly competitive, with key players leveraging their extensive service portfolios and technological advancements to maintain market leadership. Intertek Group Plc and Bureau Veritas are prominent due to their global reach and comprehensive TIC services across various industries. TUV SUD and UL LLC also hold significant market shares, recognized for their strong expertise in safety and quality assurance. Companies like DNV GL and DEKRA SE emphasize sustainability and advanced technological integration in their services. Mistras Group and Applus Services, SA focus on specialized sectors, providing tailored solutions for complex industrial needs. Emerging players such as Avomeen LLC and Envigo Corporation are gaining traction by offering niche, innovative services, particularly in pharmaceuticals and environmental testing. Overall, the competitive landscape is characterized by strategic partnerships, mergers and acquisitions, and continuous innovation to meet evolving regulatory and customer demands.
Recent Developments
In December 2023, UL LLC and Hyundai Mobis North America signed a memorandum of understanding (MOU) to enhance the safety and performance of electric vehicle batteries. Utilizing the UL LLC North America Advanced Battery Laboratory in Michigan, this partnership aims to ensure the safe and extensive deployment of electric vehicle battery technology, addressing the growing global adoption of electric vehicles. This collaboration is expected to contribute significantly to the development of safer and more reliable battery systems, ultimately supporting the broader goal of sustainable transportation.
In November 2023, Intertek Group plc partnered with Emitech Group to expand its electrical testing capabilities in Europe. Emitech Group, an independent testing and engineering expert accredited with EN 17025 and EN 17065, will collaborate with Intertek to enhance service offerings. This partnership aims to provide comprehensive testing solutions to meet the increasing demand for high-quality electrical testing across various industries, ensuring compliance with European standards and improving product reliability and safety.
In October 2023, TÜV Rheinland acquired Burotec, a Spanish business group specializing in inspection, engineering, and security services. This acquisition strengthens TÜV Rheinland’s voluntary services activities and expands its service portfolio in Spain. By integrating Burotec’s expertise, TÜV Rheinland aims to enhance its inspection and certification capabilities, providing comprehensive solutions to a broader range of clients and reinforcing its position in the Spanish market.
In September 2023, DNV GL introduced its latest service specification, DNV-SE-0656, designed to verify Power-to-X (PtX) facilities. This specification offers a detailed framework for independent risk-based verification or certification of PtX and process facilities. PtX technology converts electricity into various fuels like hydrogen, methane, ammonia, kerosene, and methanol, typically using renewable electricity and biogenic carbon dioxide (CO2) to reduce greenhouse gas emissions. This new specification aims to support the sustainable production and utilization of these fuels.
In July 2023, SGS SA provided verification and assessment services for infrastructure and energy subsystems in railways. These new accreditations, combined with existing ones for rolling stock and control, command, and signaling subsystems, enabled SGS SA to complete the full Technical Specifications for Interoperability (TSI) certification process for railway subsystems. This comprehensive certification ensures that railway systems meet stringent safety and interoperability standards, facilitating seamless and efficient railway operations across Europe.
Market Concentration and Characteristics
The U.S. Testing Inspection and Certification (TIC) market is characterized by moderate to high market concentration, with a mix of large multinational corporations and specialized regional players. Key characteristics of the market include the integration of advanced technologies such as AI, IoT, and blockchain to enhance service accuracy and efficiency, a strong emphasis on regulatory compliance across diverse industries, and increasing demand for specialized TIC services driven by the complexity of modern industrial processes. The market also exhibits significant competitive pressure, with major players continuously innovating and expanding their service portfolios through strategic partnerships and acquisitions to maintain a competitive edge.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Sourcing Type and End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The TIC market will increasingly adopt advanced technologies such as AI, IoT, and blockchain, enhancing accuracy, efficiency, and reliability in testing and certification processes.
- As digital transformation accelerates, the need for robust cybersecurity testing and certification services will grow, addressing vulnerabilities in interconnected systems and data privacy concerns.
- The market will expand its reach into emerging industries like renewable energy, biotechnology, and autonomous vehicles, providing specialized TIC services tailored to these sectors' unique requirements.
- Sustainability and environmental compliance will become central to TIC services, driven by regulatory pressures and consumer demand for eco-friendly products and practices.
- The trend towards outsourcing TIC services will continue, as companies seek cost-effective solutions and access to specialized expertise without significant capital investment.
- With the globalization of trade, TIC providers will focus more on ensuring compliance with international standards, facilitating smoother cross-border transactions and supply chain operations.
- The TIC market will face increasing regulatory complexity, requiring continuous adaptation and investment in staying current with evolving standards across various industries.
- The adoption of remote inspection technologies will grow, offering flexibility and reducing costs, while ensuring thorough and accurate inspections in hard-to-reach locations.
- Strategic collaborations and partnerships between TIC providers and technology firms will enhance service offerings, drive innovation, and expand market reach.
- Consumer demand for high-quality, safe, and reliable products will drive the need for comprehensive TIC services, with a focus on building trust and ensuring compliance with stringent safety standards.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Regulatory Standards and Compliance Requirements
Increasingly complex and strict regulations from agencies like the FDA, EPA, and OSHA require frequent and thorough testing, inspection, and certification, driving demand for third-party TIC services across industries.
Technological Advancements in Testing and Inspection
The adoption of AI, IoT, and blockchain is enhancing the accuracy, efficiency, and traceability of TIC processes, enabling providers to offer more sophisticated and reliable services, which attracts a broader client base.
Globalization and Cross-Border Compliance
As U.S. companies expand internationally, they face diverse regulatory requirements, increasing the need for standardized TIC services to ensure compliance with both domestic and international standards.
Growing Consumer Awareness and Demand for Quality Assurance
Consumers are increasingly prioritizing product safety, quality, and environmental impact, prompting companies to invest in robust TIC services to build trust and meet market expectations.
Expansion of Specialized and Outsourced TIC Services
The complexity of modern products and supply chains is driving demand for specialized and outsourced TIC services, allowing companies to access expertise and advanced technologies without significant capital investment.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the U.S. Testing Inspection and Certification Market?
What are the key drivers of growth in the U.S. TIC market?
How are technological advancements impacting the TIC market?
Which regions in the U.S. have significant activity in the TIC market?
Who are some of the key players in the U.S. TIC market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Consumer Goods and Retail
- 1.2.2 Healthcare and Pharmaceuticals
- 1.2.3 Industrial and Manufacturing
- 1.2.4 Transportation and Logistics
- 1.3 By Service Type
- 1.3.1 Testing Services
- 1.3.2 Inspection Services
- 1.3.3 Certification Services
- 1.4 By Sourcing Type
- 1.4.1 In-House
- 1.4.2 Outsourced
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 44,138.97 million → 2032: USD 70,555.86 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Testing Inspection and Certificate Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Testing Inspection and Certificate Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Testing Inspection and Certificate Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Testing Inspection and Certificate Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Testing Inspection and Certificate Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Testing Inspection and Certificate Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Testing Inspection and Certificate Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Testing Inspection and Certificate Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 44,138.97 million → 2032: USD 70,555.86 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Testing Inspection and Certificate Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Consumer Goods and Retail
- 12.3.7.2 Healthcare and Pharmaceuticals
- 12.3.7.3 Industrial and Manufacturing
- 12.3.7.4 Transportation and Logistics
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Service Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Testing Services
- 12.4.7.2 Inspection Services
- 12.4.7.3 Certification Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sourcing Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 In-House
- 12.5.7.2 Outsourced
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Testing Inspection and Certificate End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 U.S. Testing Inspection and Certificate Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 U.S. Testing Inspection and Certificate Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 U.S. Testing Inspection and Certificate Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Intertek Group Plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Bureau Veritas
- 18.4 TUV SUD
- 18.5 UL LLC
- 18.6 DNV GL
- 18.7 DEKRA SE
- 18.8 Mistras Group
- 18.9 Applus Services, SA
- 18.10 SGS SA
- 18.11 ALS Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

