
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| USA and Canada Molded Fiber Pulp Packaging Market Size 2024 | USD 8600 million |
| USA and Canada Molded Fiber Pulp Packaging Market, CAGR | 5.6% |
| USA and Canada Molded Fiber Pulp Packaging Market Size 2032 | USD 13298.71 million |
Market Overview:
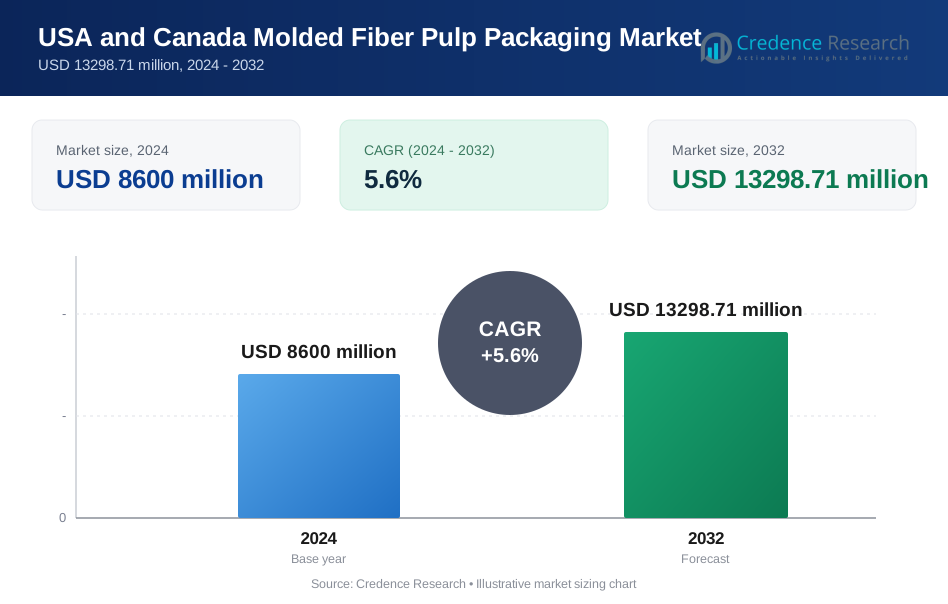
The USA and Canada Molded Fiber Pulp Packaging Market is projected to grow from USD 8600 million in 2024 to an estimated USD 13298.71 million by 2032, with a compound annual growth rate (CAGR) of 5.6% from 2024 to 2032.
Market drivers include heightened awareness of environmental sustainability and stricter regulatory measures to curb plastic waste. The rise of e-commerce has also boosted demand for protective yet sustainable packaging solutions, as molded fiber pulp offers versatility and durability for a variety of products. In addition, consumers increasingly prefer eco-friendly products, driving businesses to adopt biodegradable and recyclable packaging options. Technological advancements in molded fiber manufacturing, such as improvements in automation and customization, are enhancing product quality and production efficiency, further bolstering market adoption. These factors collectively position molded fiber pulp packaging as a key solution for reducing the environmental footprint of packaging materials.
Regionally, the United States dominates the market, accounting for approximately 75% of the market share. This dominance is attributed to robust industrial activity, extensive e-commerce networks, and strong consumer demand for sustainable solutions. Key states like California, New York, and Texas lead adoption due to stringent environmental policies and a strong preference for green products. Meanwhile, Canada accounts for 25% of the market, experiencing steady growth driven by government initiatives promoting environmental sustainability and increasing demand for eco-friendly packaging in the food and beverage sector. Together, the USA and Canada represent a dynamic market landscape, marked by innovation, regulatory compliance, and growing consumer preference for sustainable packaging solutions.
Market Insights:
- The USA and Canada molded fiber pulp packaging market is projected to grow significantly, driven by increasing demand for sustainable packaging solutions as environmental concerns and regulatory measures intensify.
- Heightened awareness around the environmental impact of single-use plastics has positioned molded fiber packaging as an eco-friendly alternative, particularly in food, beverage, and e-commerce sectors.
- The rapid expansion of e-commerce in both countries has fueled the need for durable, protective, and lightweight packaging, aligning with consumer expectations for eco-conscious products.
- Technological advancements, including automation and material innovations, have improved production efficiency, customization capabilities, and scalability, expanding the applications of molded fiber packaging.
- Regulatory frameworks in the USA, such as state-level bans on plastics, and Canada’s federal initiatives for a zero-plastic waste goal, are catalyzing market adoption and driving innovation in biodegradable and recyclable solutions.
- Challenges such as high production costs, raw material fluctuations, and quality issues in high-moisture environments persist, yet advancements in coatings and performance-enhancing materials are mitigating these limitations.
- The USA leads the market with 70% share, driven by robust industrial infrastructure and consumer demand, while Canada, holding 30%, shows rapid growth through strong government support and eco-conscious consumer trends. Both regions complement each other in driving market expansion and sustainability initiatives.
Market Drivers:
Rising Demand for Sustainable Packaging Solutions:
The increasing global emphasis on sustainability is a significant driver for the USA and Canada molded fiber pulp packaging market. With heightened awareness of environmental degradation caused by single-use plastics, consumers and industries alike are shifting toward biodegradable and recyclable materials. Molded fiber pulp packaging, being derived from renewable resources such as recycled paper and natural fibers, offers an eco-friendly alternative to conventional plastic-based packaging. For instance, 60% of consumers are willing to pay more for sustainable packaging. This trend aligns with growing consumer expectations for businesses to adopt sustainable practices, driving demand across various sectors, including food and beverage, consumer goods, and electronics.
Stringent Government Regulations and Policies:
Government regulations targeting the reduction of plastic waste are a critical factor influencing market growth. Policies such as bans on single-use plastics, extended producer responsibility programs, and incentives for sustainable packaging adoption have accelerated the transition to environmentally friendly solutions. In the USA, state-level initiatives, particularly in regions like California and New York, encourage businesses to switch to biodegradable materials. For example, California's Plastic Pollution Prevention and Packaging Producer Responsibility Act mandates that all packaging be recyclable or compostable by 2032. Similarly, Canada’s nationwide commitment to achieving zero plastic waste by 2030 has created a favorable regulatory environment for the adoption of molded fiber pulp packaging. These measures are compelling manufacturers to innovate and prioritize eco-friendly packaging solutions.
Growth in E-commerce and Retail Sectors:
The rapid expansion of e-commerce and retail sectors in the USA and Canada has further propelled demand for molded fiber pulp packaging. Online retail platforms require protective, lightweight, and sustainable packaging to ensure safe product delivery while minimizing environmental impact. Molded fiber pulp packaging meets these criteria, offering exceptional cushioning properties and durability. The rise in direct-to-consumer shipping models and subscription-based services has amplified the need for eco-conscious packaging options that cater to environmentally aware consumers. This trend has positioned molded fiber as a preferred choice for businesses seeking to enhance their sustainability profiles.
Technological Advancements and Customization Capabilities:
Innovations in manufacturing processes and material technologies are enhancing the adoption of molded fiber pulp packaging. Automation and advancements in production techniques have improved the quality, efficiency, and scalability of molded fiber solutions, making them competitive with traditional materials. Additionally, customization capabilities, such as tailored designs and branding options, enable businesses to align packaging with their unique requirements. These technological advancements have expanded the application range of molded fiber packaging, from protective trays for electronics to aesthetically appealing food containers, further driving its market penetration in the USA and Canada.
Market Trends:
Integration of Advanced Manufacturing Techniques:
The USA and Canada molded fiber pulp packaging market is witnessing a surge in advanced manufacturing technologies, enhancing efficiency and expanding product versatility. Automation and robotics are increasingly integrated into production lines, enabling faster turnaround times and improved precision in molding intricate designs. Moreover, innovations in material engineering, such as the use of water-resistant coatings and additives, are enhancing the functionality of molded fiber packaging, making it suitable for applications requiring moisture resistance. These advancements are broadening the scope of adoption across sectors like electronics, food delivery, and healthcare.
Expansion of Sustainable Packaging Initiatives in Retail:
Retail and e-commerce sectors in the USA and Canada are increasingly incorporating sustainable molded fiber packaging to meet growing consumer demand for eco-friendly products. Major retailers are adopting molded fiber for its lightweight and biodegradable properties, aligning with their corporate sustainability goals. Brands are leveraging molded fiber as a marketing tool, emphasizing environmentally friendly packaging as a value proposition to attract eco-conscious consumers. The shift toward minimalistic packaging designs, coupled with efforts to reduce carbon footprints, has positioned molded fiber as a key component of sustainable retail strategies.
Emergence of High-Performance Molded Fiber Solutions:
High-performance molded fiber packaging, designed for durability and superior protective capabilities, is gaining traction in the USA and Canada. These solutions are particularly relevant for sectors requiring robust and precise packaging, such as electronics and industrial goods. The ability to mold customized inserts and trays for fragile or complex-shaped products has driven the adoption of molded fiber in high-value industries. For instance, Kemira's advanced chemical additives enhance the durability and strength of molded fiber packaging, making it suitable for demanding applications. Companies are investing in research and development to enhance material strength and flexibility, expanding molded fiber's utility in challenging applications and displacing traditional materials like foam and plastic.
Proliferation of Food Service Applications:
The food service industry is emerging as a prominent driver of molded fiber pulp packaging adoption in the USA and Canada. With the rise of takeout, food delivery, and quick-service restaurants, there is a growing need for sustainable and functional packaging. Molded fiber solutions, including clamshell containers, plates, and trays, are widely used for their ability to maintain food integrity while minimizing environmental impact. The introduction of compostable and microwave-safe options has further cemented molded fiber's role in addressing evolving consumer preferences for convenience and sustainability in food packaging.
Market Challenges Analysis:
High Production Costs and Limited Scalability:
The production of molded fiber pulp packaging often incurs higher costs compared to conventional plastic alternatives. This is primarily due to the need for specialized machinery, higher energy consumption, and the cost of raw materials, particularly recycled fiber. For instance, the cost of recycled paper, a common raw material, ranges from $50 to $150 per ton, whereas traditional plastics can cost between $800 and $1200 per ton. Small and medium-sized enterprises (SMEs) in the USA and Canada may find it financially challenging to transition to molded fiber packaging due to limited scalability and the capital investment required for advanced manufacturing technologies.
Quality and Performance Limitations:
Despite advancements, molded fiber packaging faces challenges in meeting performance requirements for certain applications. Its susceptibility to moisture and humidity can limit its utility in sectors like frozen food and electronics, where enhanced durability and resistance are critical. While coatings and additives are being developed to address these issues, their integration often adds to production costs, creating a trade-off between performance and affordability. Achieving consistent quality in molded fiber products, particularly for complex designs, remains another technical hurdle.
Regulatory Compliance and Certification Complexities:
Adhering to stringent environmental and safety regulations can pose challenges for manufacturers in the USA and Canada. Certification processes for compostability, recyclability, and food safety standards require rigorous testing and documentation, adding to operational complexities and costs. Variations in regulatory frameworks between states and provinces further complicate compliance, especially for companies operating across borders. Meeting these diverse requirements while maintaining cost-effectiveness is a persistent challenge for industry players.
Supply Chain Constraints and Raw Material Availability:
The availability and quality of raw materials, particularly post-consumer recycled paper and virgin pulp, can be inconsistent. Supply chain disruptions, driven by factors such as global trade restrictions or local shortages, affect the production capacity and pricing of molded fiber packaging. Additionally, fluctuations in raw material costs impact profitability and create pricing uncertainties for customers. These constraints make it difficult for manufacturers to maintain stable production and competitive pricing, limiting market expansion.
Market Opportunities:
The USA and Canada molded fiber pulp packaging market presents significant growth opportunities, driven by increasing consumer and regulatory demand for sustainable packaging solutions. With heightened awareness about the environmental impact of plastic waste, industries such as food and beverage, electronics, and healthcare are transitioning toward eco-friendly alternatives. Molded fiber pulp packaging, recognized for its biodegradability and recyclability, aligns with the sustainability goals of businesses and governments. The rising adoption of e-commerce, which requires durable yet eco-conscious packaging for shipping, further amplifies demand. Innovations in molded fiber technology, such as improved water and grease resistance coatings, are expanding its applicability, making it a viable choice for more sectors. Businesses that invest in advanced manufacturing processes and customized solutions stand to capitalize on these trends, addressing the growing preference for sustainable consumer goods.
Regionally, opportunities lie in addressing the unique needs of both the USA and Canada markets. In the United States, the market benefits from a large consumer base and strong corporate sustainability commitments, with major industries seeking to replace plastic packaging to meet environmental regulations and consumer expectations. In Canada, government-led initiatives promoting circular economies and bans on single-use plastics provide fertile ground for growth. Furthermore, the development of localized supply chains to minimize carbon footprints and reduce transportation costs presents another opportunity. Companies that align with evolving regulations and offer scalable, cost-effective solutions tailored to specific industries are well-positioned to drive growth and gain competitive advantage in this dynamic market.
Market Segmentation Analysis:
The USA and Canada molded fiber pulp packaging market is segmented by molded pulp type, product type, application, and end use, reflecting its diverse applications and increasing demand for sustainable solutions.
By molded pulp type, the market includes thick wall, transfer molded, thermoformed fiber, and processed pulp categories. Thermoformed fiber is a key driver due to its smooth finish and suitability for premium packaging, while transfer molded pulp is widely used for protective applications in consumer durables.
By product type, the market offers a variety of options such as trays, drink carriers, boxes, end caps, plates, bowls, cups, and clamshell containers. Drink carriers are further categorized by capacity, including 2 cups, 4 cups, and up to 8 cups or more, catering to diverse needs in the food and beverage industry.
By application, molded fiber pulp packaging serves primary and secondary packaging needs, as well as specialized uses like edge protectors. Primary packaging remains dominant due to the growing demand for eco-friendly solutions in food and consumer goods.
By end use, the market spans consumer durables (mobile phones, TVs, laptops), food and beverage packaging (egg cartons, wine carriers, fruit trays), cosmetics, food services, healthcare, automotive, and logistics. The food and beverage segment leads, driven by applications like egg packaging (ranging from 4 to 30+ eggs) and wine packaging (375 ml to 3+ liters). Emerging applications in healthcare and automotive further expand market opportunities, while other niche uses like flower and candle packaging contribute to its versatility.
Segmentation:
By Molded Pulp Type:
- Thick Wall
- Transfer Molded
- Thermoformed Fiber
- Processed Pulp
By Product Type:
- Trays
- Drink Carriers
- Boxes
- End Caps
- Plates
- Bowls
- Cups
- Clamshell Containers
By Application:
- Primary Packaging
- Secondary Packaging
- Edge Protectors
By End Use:
- Consumer Durables
- Food & Beverage
- Cosmetics
- Food Services
- Healthcare
- Automotive
- Logistics
- Others (Candles, Flower Packaging)
By Country:
- USA
- Canada
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
The USA and Canada molded fiber pulp packaging market exhibits distinct regional dynamics, driven by differences in regulatory landscapes, industrial activity, and consumer preferences. Together, these regions form a robust market, each contributing unique opportunities and challenges.
The United States dominates the market, accounting for approximately 70% of the total share. This leadership is underpinned by the country’s large consumer base, advanced manufacturing infrastructure, and strong corporate commitments to sustainability. The food and beverage industry, particularly in metropolitan areas such as New York, Los Angeles, and Chicago, plays a pivotal role in driving demand for molded fiber pulp packaging, as businesses seek sustainable alternatives to plastic. E-commerce has also surged in the United States, further amplifying the need for protective yet eco-friendly packaging solutions. Regulatory pressures, including state-level bans on single-use plastics and mandates for recycled content, are compelling industries to adopt molded fiber packaging. The United States also benefits from significant investment in innovation, with companies exploring advanced coatings and customized designs to cater to diverse applications.
Canada accounts for the remaining 30% of the market and is experiencing rapid growth. The country’s emphasis on environmental conservation, coupled with federal bans on single-use plastics, has created a fertile ground for molded fiber packaging solutions. Key provinces such as Ontario, British Columbia, and Quebec are leading demand, supported by a strong focus on circular economies and government-backed initiatives promoting sustainability. The foodservice industry in Canada is a notable driver, with restaurants and fast-food chains increasingly adopting molded fiber containers and trays to align with eco-conscious consumer preferences. Additionally, Canada’s smaller yet growing e-commerce sector is contributing to the market, as businesses prioritize environmentally responsible shipping materials.
Cross-border trade between the USA and Canada further strengthens the regional market, as companies leverage integrated supply chains to optimize production and distribution. Both countries share a commitment to sustainability, with industries increasingly adopting molded fiber solutions to meet regulatory requirements and consumer expectations. Together, the USA and Canada present a dynamic and evolving market for molded fiber pulp packaging, characterized by innovation, regulatory support, and increasing consumer demand for environmentally friendly solutions. As the market continues to expand, both regions are expected to play complementary roles in driving sustainable packaging adoption.
Key Player Analysis:
- Atlantic Pulp
- Cascades Inc.
- Earth Recycle International S. de R. L. de C. V.
- EnviroPAK Corporation
- FiberCel Packaging LLC
- Footprint
- Hartmann Canada Inc.
- Henry Molded Products, Inc.
- Huhtamaki Oyj
- IB Packaging
- Interbrands Packaging
- Keiding Inc
- MFT-CKF Inc
- Michelsen Packaging Company
- Multipap Industries
- OrCon Industries Corporation
- Pacific Pulp Molding, Inc.
- Pactiv LLC
- ProtoPak Engineering Corporation
- Western Pulp Products Company
- YFY Jupiter
Competitive Analysis:
The USA and Canada molded fiber pulp packaging market is characterized by moderate competition, with key players focusing on innovation, sustainability, and customization to capture market share. Leading companies such as Huhtamaki, UFP Technologies, and Pactiv Evergreen dominate the space, leveraging their extensive production capabilities and advanced technologies to meet diverse customer needs. These players invest significantly in research and development to improve product performance, including water and grease resistance, while maintaining eco-friendly attributes. Smaller and regional firms also contribute to market dynamics by offering niche solutions tailored to local demands, particularly in the foodservice and agricultural sectors. The competitive landscape is further shaped by rising demand for sustainable packaging, driving companies to adopt recycled materials and biodegradable coatings. Strategic partnerships, acquisitions, and geographical expansions are common as firms seek to strengthen their market presence. As sustainability regulations tighten, competition is expected to intensify, fostering further innovation and collaboration.
Recent Developments:
- In September 2024, ANDRITZ and PulPac joined forces in a strategic partnership to advance the alternative packaging market. By integrating PulPac's Dry Molded Fiber technology with ANDRITZ's expertise in turnkey pulp mills and web-forming processes, the collaboration aims to deliver complete production lines for recyclable products such as coffee lids and food trays.
- In June 2024, Innofibre, a Quebec-based industrial innovation center, unveiled groundbreaking research demonstrating that recycled food and beverage cartons can be used to create high-quality molded pulp packaging. The study revealed that recycled carton fiber pulp matches the properties of virgin kraft pulp and offers superior strength compared to traditional products made from old newspaper.
- In February 2024, Pregis, in partnership with Exxon Mobil, introduced a sustainable foam packaging solution made from certified circular polyethylene resin. This innovative product leverages advanced recycling technology to support plastic reduction goals while maintaining high performance in protective packaging.
- In November 2022, at its facility in Nules, Spain, Huhtamaki Oyj increased its capacity for packaging made of paper. The company increased its capacity in response to the growing demand for packaging made of recyclable and paper-based materials in place of plastic.
Market Concentration & Characteristics:
The USA and Canada molded fiber pulp packaging market exhibits a moderately concentrated structure, with a mix of dominant multinational players and regional manufacturers. Large companies such as Huhtamaki and UFP Technologies hold significant market shares due to their advanced production capabilities, extensive distribution networks, and strong focus on innovation. These firms leverage economies of scale and technological advancements to maintain a competitive edge. Regional and local players also contribute to market diversity by addressing niche demands, such as custom packaging solutions for foodservice and agriculture industries. The market is characterized by its focus on sustainability, with a growing shift toward recycled and biodegradable materials to meet regulatory requirements and consumer preferences. The balance between large-scale efficiency and regional specialization creates a dynamic and evolving competitive environment. Companies increasingly prioritize R&D investments, partnerships, and sustainable practices to strengthen their positions, catering to the rising demand for eco-friendly and cost-effective packaging solutions.
Report Coverage:
The research report offers an in-depth analysis based on By Molded Pulp Type, By Product Type, By Application and By End Use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The USA and Canada molded fiber pulp packaging market is projected to witness steady growth, driven by increasing demand for sustainable and biodegradable packaging solutions.
- Rising environmental awareness and regulatory policies targeting plastic reduction are expected to propel adoption across industries.
- The food and beverage sector will remain a key growth driver, with heightened demand for eco-friendly packaging for takeaway meals and fresh produce.
- Advancements in manufacturing technologies, including automation and precision molding, are anticipated to enhance production efficiency and product quality.
- Customization and design innovations will cater to the unique needs of end-users, particularly in consumer electronics and healthcare sectors.
- Investments in recycled and renewable raw materials are expected to lower costs and support circular economy initiatives.
- E-commerce growth in the USA and Canada will drive demand for protective and sustainable packaging solutions for shipping and logistics.
- Regional manufacturers will benefit from increasing government incentives promoting green technologies and local production.
- Cross-industry collaborations and partnerships will accelerate innovation and expand market reach for molded fiber packaging solutions.
- The growing preference for lightweight, durable, and compostable packaging will solidify the market’s position as a leading solution in the transition to sustainable packaging.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the molded fiber pulp packaging market in the USA and Canada?
What are the primary drivers of this market's growth?
Which region dominates the market, and why?
What challenges does the market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 USA and Canada Molded Fiber Pulp Packaging Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global USA and Canada Molded Fiber Pulp Packaging Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8600 million → 2032: USD 13298.71 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 USA and Canada Molded Fiber Pulp Packaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. USA and Canada Molded Fiber Pulp Packaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 USA and Canada Molded Fiber Pulp Packaging Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 USA and Canada Molded Fiber Pulp Packaging Market Drivers
- 3.3 USA and Canada Molded Fiber Pulp Packaging Market Restraints & Challenges
- 3.4 USA and Canada Molded Fiber Pulp Packaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 USA and Canada Molded Fiber Pulp Packaging Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 USA and Canada Molded Fiber Pulp Packaging Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, USA and Canada Molded Fiber Pulp Packaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 USA and Canada Molded Fiber Pulp Packaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. USA and Canada Molded Fiber Pulp Packaging Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the USA and Canada Molded Fiber Pulp Packaging market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 USA and Canada Molded Fiber Pulp Packaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 USA and Canada Molded Fiber Pulp Packaging Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 USA and Canada Molded Fiber Pulp Packaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in USA and Canada Molded Fiber Pulp Packaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New USA and Canada Molded Fiber Pulp Packaging Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global USA and Canada Molded Fiber Pulp Packaging Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America USA and Canada Molded Fiber Pulp Packaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe USA and Canada Molded Fiber Pulp Packaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific USA and Canada Molded Fiber Pulp Packaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America USA and Canada Molded Fiber Pulp Packaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East USA and Canada Molded Fiber Pulp Packaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa USA and Canada Molded Fiber Pulp Packaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. USA and Canada Molded Fiber Pulp Packaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
