
Market Overview:
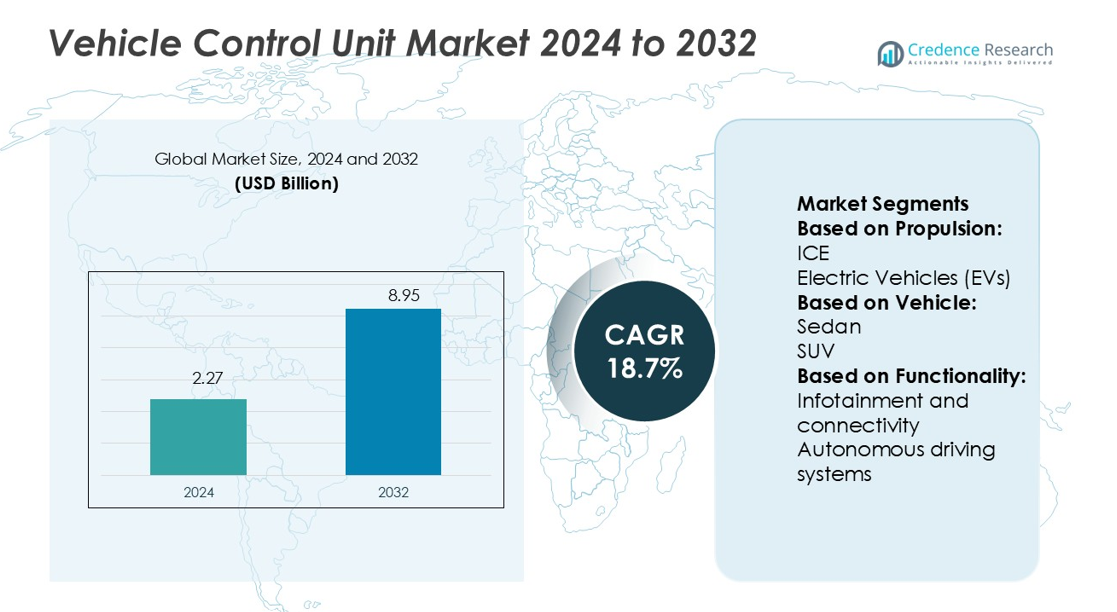
Vehicle Control Unit Market size was valued USD 2.27 billion in 2024 and is anticipated to reach USD 8.95 billion by 2032, at a CAGR of 18.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Vehicle Control Unit Market Size 2024 | USD 2.27 billion |
| Vehicle Control Unit Market, CAGR | 18.7% |
| Vehicle Control Unit Market Size 2032 | USD 8.95 billion |
The Vehicle Control Unit market is shaped by top players including ZF Friedrichshafen AG, Dorleco, Infineon, Continental AG, ASI Robots, NXP Semiconductors, Robert Bosch, Denso, Delphi Technologies, and STMicroelectronics. These companies drive innovation through advanced powertrain control, semiconductor integration, ADAS development, and connectivity solutions. Strong focus on software-defined platforms, autonomous driving support, and energy-efficient designs strengthens their competitive positions. Asia-Pacific leads the global market with a 34% share, supported by large-scale automotive production, rapid adoption of electric vehicles, and government-backed initiatives for smart mobility, positioning the region as the primary growth hub for vehicle control unit deployment.
Market Insights
- The Vehicle Control Unit Market size was USD 2.27 billion in 2024 and will reach USD 8.95 billion by 2032 at a CAGR of 18.7%.
- Rising demand for electric vehicles and ADAS integration acts as a major driver, supported by government regulations and emission reduction goals.
- The market shows strong trends in software-defined vehicle architectures, battery management system integration, and autonomous driving technologies.
- Competition remains intense as key players like ZF Friedrichshafen AG, Robert Bosch, Continental AG, Infineon, and others focus on innovation in semiconductors, connectivity, and powertrain control.
- Asia-Pacific leads with 34% share, followed by North America at 32% and Europe at 29%, with passenger vehicles holding the dominant segment share driven by adoption of advanced safety and connectivity features.
Market Segmentation Analysis:
By Propulsion
In the Vehicle Control Unit (VCU) market, Internal Combustion Engine (ICE) vehicles hold the dominant share of 58%. Their leadership is driven by the wide global fleet of ICE-powered cars and the presence of mature infrastructure supporting conventional fuels. The market is sustained by strong demand in developing regions where fuel-based mobility continues to dominate. Increasing adoption of control systems for emission management and efficiency optimization further supports this segment. Electric vehicles (EVs) are rapidly gaining momentum due to battery innovation and government incentives, while Fuel Cell Electric Vehicles (FCEVs) remain niche but steadily developing.
- For instance, Electric Vehicle Control Unit (EVCU) switching frequency above 20 kHz is desirable, as it falls outside the range of human hearing, minimizing audible noise from the powertrain. PWM frequencies are commonly in this range for power electronics in EVs.
By Vehicle
Passenger vehicles lead this segment with a 61% share, supported by high ownership rates and continuous demand for sedans, SUVs, and hatchbacks. SUVs contribute significantly due to their global popularity, offering more advanced control units for safety, infotainment, and connectivity features. Commercial vehicles also represent strong adoption of VCUs, particularly in light commercial vehicles (LCVs) where fleet electrification and logistics expansion create opportunities. Medium and heavy commercial vehicles (MCVs and HCVs) increasingly use control units for powertrain management and fuel efficiency. Off-highway vehicles are an emerging niche as automation and precision control grow in agriculture and construction machinery.
- For instance, Infineon’s AURIX TC29xT microcontroller runs at 300 MHz, includes 8 MB flash memory and meets ASIL-D safety requirements, aimed at handling powertrain and body control tasks in passenger, commercial, and off-highway vehicles.
By Functionality
Powertrain control dominates with a 47% share, reflecting its role as the core application of vehicle control units. The segment benefits from growing demand for efficient torque control, fuel optimization, and emission reduction. Battery management system (BMS) integration follows closely, aligned with the rise of electric vehicles requiring efficient battery performance and safety. Advanced driver assistance systems (ADAS) adoption is accelerating, driven by regulatory mandates and consumer preference for enhanced safety. Infotainment and connectivity expand alongside consumer demand for digital driving experiences, while autonomous driving systems, though emerging, attract heavy investments from automakers. Other functions, such as climate and chassis control, also support diversification.
Market Overview
Rising Adoption of Electric Vehicles (EVs)
The rapid expansion of electric vehicles drives strong demand for advanced vehicle control units. VCUs integrate battery management systems, motor control, and energy optimization, making them vital for EV efficiency and safety. Governments worldwide provide incentives and infrastructure support, further accelerating EV adoption. Automakers invest heavily in electrification strategies, boosting deployment of high-performance VCUs. With increasing focus on sustainability and emission reduction, this driver ensures long-term growth for the VCU market, particularly in regions with ambitious carbon neutrality targets and regulatory pressure on ICE vehicles.
- For instance, Continental’s thermal management systems maintain battery temperatures between 20 °C and 40 °C using specialized coolant, refrigerant, and oil lines to prevent range loss and thermal runaway.
Integration of Advanced Driver Assistance Systems (ADAS)
The widespread adoption of ADAS technologies creates significant demand for sophisticated VCUs. These systems manage functions such as adaptive cruise control, lane-keeping assistance, and collision avoidance, requiring real-time data processing and precision control. Regulatory requirements for safety features in passenger and commercial vehicles further accelerate ADAS integration. Automakers increasingly prioritize driver safety and convenience, making VCUs central to enabling these intelligent functionalities. As consumer preference shifts toward safer vehicles, ADAS-enabled VCUs are becoming essential, strengthening their role in both developed and emerging automotive markets.
- For instance, the steering robot actuator in ASI’s kit delivers 60 N·m peak torque at 500°/sec, and maintains 15 N·m continuous torque at 1000°/sec for precise lane keeping and collision avoidance manoeuvres.
Increasing Demand for Connected and Autonomous Vehicles
The growing trend toward connected and autonomous driving reinforces VCU adoption. VCUs enable seamless integration of infotainment, connectivity, and autonomous driving systems, ensuring real-time communication and vehicle intelligence. Rising consumer interest in in-vehicle connectivity and smart mobility solutions supports this growth. Automakers and technology firms collaborate to enhance autonomous functionalities, requiring highly reliable VCUs to manage complex operations. With 5G networks expanding and vehicle-to-everything (V2X) technologies advancing, this driver is set to accelerate market expansion, positioning VCUs as a backbone of future mobility ecosystems worldwide.
Key Trends & Opportunities
Advancements in Software-Defined Vehicles
The shift toward software-defined vehicles creates new opportunities for VCU providers. Modern VCUs rely on software updates to enhance performance, security, and functionality, reducing dependency on hardware changes. Automakers leverage over-the-air (OTA) updates to introduce new features and optimize vehicle efficiency. This trend improves lifecycle value and strengthens customer engagement. Companies developing scalable, software-centric VCU platforms can capitalize on recurring revenue opportunities. As the industry embraces digital transformation, software-defined architectures position VCUs as central hubs for innovation, offering a sustainable competitive advantage in the evolving automotive landscape.
- For instance, NXP’s CoreRide platform integrates the S32N55 processor as central compute, paired with four S32K344 MCUs as zone controllers, allowing safe, isolated execution of multiple vehicle functions on a single system.
Expansion of Commercial Fleet Electrification
Electrification of commercial fleets presents a significant growth opportunity for VCU manufacturers. Logistics companies increasingly adopt electric light commercial vehicles (LCVs) and heavy-duty trucks to reduce operating costs and meet emission regulations. These vehicles require robust VCUs for battery management, load optimization, and predictive maintenance. Governments provide subsidies and charging infrastructure support to accelerate adoption. The demand for reliable fleet management solutions enhances the role of VCUs in ensuring efficiency and uptime. This trend supports higher volume deployment of advanced control systems across logistics, public transport, and last-mile delivery networks.
- For instance, Bosch manufactures an e-axle for commercial vehicles up to 7.5 metric tons that operates at 800 volts and employs silicon carbide inverter technology to shorten charging cycles in urban delivery routes.
Key Challenges
High Development and Integration Costs
Developing advanced vehicle control units involves significant costs related to design, software development, and testing. Automakers face challenges in balancing performance with affordability, particularly in price-sensitive markets. Integration of complex functionalities such as ADAS, BMS, and autonomous systems increases engineering requirements and time-to-market. Suppliers must continuously invest in R&D to remain competitive, adding financial strain. These high costs often limit adoption among smaller manufacturers. As vehicles become increasingly sophisticated, managing development expenses while maintaining profitability remains a critical challenge for industry stakeholders.
Cybersecurity and Data Privacy Risks
The rise of connected and autonomous vehicles increases exposure to cybersecurity threats. VCUs, as central control systems, handle sensitive vehicle data and communication with external networks, making them potential targets for cyberattacks. Breaches can compromise passenger safety, vehicle performance, and consumer trust. Regulatory bodies impose strict standards for data security, further pressuring manufacturers to implement robust protection measures. Ensuring real-time threat detection, encryption, and secure software updates is complex and costly. Addressing cybersecurity risks effectively is a key challenge that determines long-term adoption and trust in VCUs.
Regional Analysis
North America
North America leads the Vehicle Control Unit market with a 32% share, supported by advanced automotive manufacturing, strong adoption of electric vehicles, and regulatory emphasis on safety features. The United States dominates the regional market, driven by high demand for ADAS-enabled passenger vehicles and growing investments in autonomous vehicle testing. Canada follows with rising EV adoption, supported by government subsidies and charging infrastructure. The presence of leading technology firms and automakers ensures innovation in connectivity and software-defined VCUs. Strong regulatory frameworks on emissions and safety standards further drive continuous integration of advanced control systems across vehicle categories.
Europe
Europe accounts for 29% of the Vehicle Control Unit market, driven by stringent emission regulations and a strong push toward electrification. Germany leads the region with its advanced automotive ecosystem and investments in autonomous vehicle technologies. France, Italy, and the UK also contribute significantly through EV adoption and safety feature mandates. Automakers in the region integrate VCUs extensively in passenger and commercial vehicles to meet carbon reduction targets. The European Union’s policies promoting ADAS and connected vehicle technologies strengthen market growth. The shift toward software-defined and electrified mobility positions Europe as a major hub for VCU innovation.
Asia-Pacific
Asia-Pacific holds the largest regional share at 34%, led by China, Japan, and South Korea. China dominates the region with rapid EV adoption, strong government support, and the world’s largest automotive production base. Japan drives innovation in hybrid and fuel cell vehicles, while South Korea invests in advanced mobility solutions and connected car technologies. India also emerges with growing demand for cost-effective VCUs in passenger and commercial vehicles. Regional players benefit from economies of scale, high production capacities, and expanding technology integration. Asia-Pacific remains the fastest-growing region, supported by strong domestic demand and global export opportunities.
Latin America
Latin America accounts for 3% of the Vehicle Control Unit market, with Brazil and Mexico leading adoption. Brazil drives demand through rising passenger vehicle sales and integration of ADAS features in mid-range cars. Mexico benefits from strong automotive manufacturing hubs supplying global markets, which accelerates the use of VCUs in both passenger and light commercial vehicles. Government incentives for electric mobility remain limited, but urbanization and fleet modernization initiatives create opportunities. Despite infrastructure challenges, the region shows steady growth potential as automakers expand product portfolios and incorporate digital connectivity and safety features into mainstream vehicles.
Middle East & Africa
The Middle East and Africa represent 2% of the Vehicle Control Unit market, supported by emerging adoption in the UAE, Saudi Arabia, and South Africa. The Middle East focuses on smart mobility projects, with the UAE investing heavily in connected and autonomous vehicle pilots. Saudi Arabia’s Vision 2030 drives modernization in transportation, creating demand for advanced control units. Africa remains in early adoption stages due to limited infrastructure, though urbanization and gradual electrification initiatives in South Africa provide growth avenues. High costs and lack of EV charging networks pose challenges, but long-term opportunities exist through government-led modernization strategies.
Market Segmentations:
By Propulsion:
- ICE
- Electric Vehicles (EVs)
By Vehicle:
- Sedan
- SUV
By Functionality:
- Infotainment and connectivity
- Autonomous driving systems
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The competitive landscape of the Vehicle Control Unit market ZF Friedrichshafen AG, Dorleco, Infineon, Continental AG, ASI Robots, NXP Semiconductors, Robert Bosch, Denso, Delphi Technologies, and STMicroelectronics. The Vehicle Control Unit market is defined by rapid technological advancements, increasing electrification, and the integration of intelligent systems. Companies focus heavily on developing software-defined architectures, semiconductor solutions, and AI-enabled platforms to enhance vehicle efficiency, safety, and connectivity. Strategic collaborations between automakers and technology providers strengthen innovation pipelines, particularly in areas such as ADAS, autonomous driving, and battery management systems. Intense competition drives continuous investment in R&D to deliver scalable and cost-effective solutions while meeting stringent regulatory standards. The market remains highly dynamic, with differentiation increasingly centered on software capabilities, cybersecurity resilience, and long-term system reliability.
Key Player Analysis
- ZF Friedrichshafen AG
- Dorleco
- Infineon
- Continental AG
- ASI Robots
- NXP Semiconductors
- Robert Bosch
- Denso
- Delphi Technologies
- STMicroelectronics
Recent Developments
- In January 2025, Zonar unveiled the Zonar LD Telematics Control Unit (TCU), which enhances the intelligence and security of fleet operators regarding their vehicles. TCU would install more quickly, work with more vehicles, and offer better diagnostics, including towing detection and cold start tracking.
- In November 2024, Marelli launched the VEC_480, an advanced AI-powered Electronic Control Unit (ECU) intended for use in motorsport for advanced engine and vehicle management. Some key developments include a specialized NPU which implements 26 TOPS with a rate of 26 tera operations per second.
- In September 2024, Cummins Inc. announced their partnership with Bosch Global Software and KPIT to release their Eclipse CANought, an open-source project and telematics platform in commercial vehicles.
- In September 2024, Dongfeng Motor and Huawei made a joint investment into the Dongfeng Intelligent Vehicle Control Center, cementing a strategic alliance aimed at refining automotive intelligence technologies and systems automation
Report Coverage
The research report offers an in-depth analysis based on Propulsion, Vehicle, Functionality and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with rising adoption of electric and hybrid vehicles.
- Software-defined vehicle architectures will increase reliance on advanced control units.
- ADAS and autonomous driving systems will drive greater integration of VCUs.
- Battery management systems will become a core focus with growing EV penetration.
- Connected car technologies will strengthen demand for secure and scalable VCUs.
- Semiconductor innovations will enhance processing power and energy efficiency of VCUs.
- Regulatory mandates on safety and emissions will accelerate adoption across all vehicle categories.
- Commercial fleet electrification will create strong opportunities for advanced VCU deployment.
- Cybersecurity solutions will play a critical role in ensuring safe vehicle communication.
- Strategic collaborations between automakers and technology firms will shape competitive growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption of Electric Vehicles (EVs)
The rapid expansion of electric vehicles is driving strong demand for advanced vehicle control units, which are essential for integrating battery management, motor control, and energy optimization. Government incentives and automaker investments in electrification further accelerate VCU deployment, especially in regions with ambitious emission reduction targets.
Integration of Advanced Driver Assistance Systems (ADAS)
The widespread adoption of ADAS technologies, such as adaptive cruise control and lane-keeping assistance, requires sophisticated VCUs for real-time data processing and precision control. Regulatory mandates for safety features and consumer preference for safer vehicles are making ADAS-enabled VCUs essential across both passenger and commercial vehicles.
Increasing Demand for Connected and Autonomous Vehicles
The trend toward connected and autonomous vehicles is reinforcing the need for VCUs that can manage infotainment, connectivity, and autonomous driving systems. Expansion of 5G and V2X technologies, along with consumer interest in smart mobility, positions VCUs as the backbone of future vehicle intelligence.
Advancements in Software-Defined Vehicles
The shift to software-defined vehicle architectures allows for over-the-air updates and scalable feature enhancements, increasing the value and lifecycle of VCUs. Automakers and suppliers focusing on software-centric platforms can capitalize on recurring revenue and improved customer engagement.
Expansion of Commercial Fleet Electrification
The electrification of commercial fleets, driven by logistics companies seeking lower operating costs and regulatory compliance, is boosting demand for robust VCUs. These units are critical for battery management, load optimization, and predictive maintenance in electric light commercial vehicles and heavy-duty trucks.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Vehicle Control Unit Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Vehicle Control Unit Market projected to grow between 2025 and 2032?
Which Vehicle Control Unit Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Vehicle Control Unit Market?
Who are the leading companies in the Vehicle Control Unit Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Vehicle
- 1.2.1 Passenger Vehicles
- 1.2.2 Commercial Vehicles
- 1.2.3 Off-Highway Vehicles
- 1.3 By Propulsion
- 1.3.1 Internal Combustion Engine (ICE)
- 1.3.2 Electric Vehicles (EVs)
- 1.3.3 Fuel Cell Electric Vehicles (FCEVs)
- 1.4 By Functionality
- 1.4.1 Powertrain Control
- 1.4.2 Battery Management System (BMS)
- 1.4.3 Advanced Driver Assistance Systems (ADAS)
- 1.4.4 Infotainment and Connectivity
- 1.4.5 Autonomous Driving Systems
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.27 billion → 2032: USD 8.95 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Vehicle Control Unit Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Vehicle Control Unit Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Vehicle Control Unit Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Vehicle Control Unit Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Vehicle Control Unit Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Vehicle Control Unit Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Vehicle Control Unit Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Vehicle Control Unit Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.27 billion → 2032: USD 8.95 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Vehicle Control Unit Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Vehicle - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Passenger Vehicles
- 12.3.7.2 Commercial Vehicles
- 12.3.7.3 Off-Highway Vehicles
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Propulsion - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Internal Combustion Engine (ICE)
- 12.4.7.2 Electric Vehicles (EVs)
- 12.4.7.3 Fuel Cell Electric Vehicles (FCEVs)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Functionality - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Powertrain Control
- 12.5.7.2 Battery Management System (BMS)
- 12.5.7.3 Advanced Driver Assistance Systems (ADAS)
- 12.5.7.4 Infotainment and Connectivity
- 12.5.7.5 Autonomous Driving Systems
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Vehicle Control Unit Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Vehicle Control Unit Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Vehicle Control Unit Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 ZF Friedrichshafen AG
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Dorleco
- 17.4 Infineon
- 17.5 Continental AG
- 17.6 ASI Robots
- 17.7 NXP Semiconductors
- 17.8 Robert Bosch
- 17.9 Denso
- 17.10 Delphi Technologies
- 17.11 STMicroelectronics
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

