
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
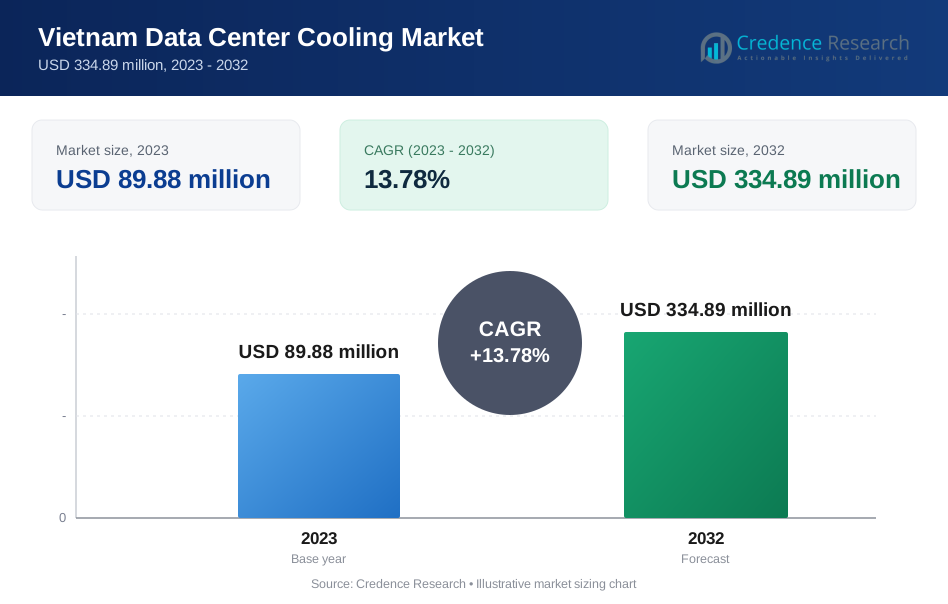
| Vietnam Data Center Cooling Market Size 2023 | USD 89.88 Million |
| Vietnam Data Center Cooling Market, CAGR | 13.78% |
| Vietnam Data Center Cooling Market Size 2032 | USD 334.89 Million |
Market Overview
The Vietnam Data Center Cooling Market is projected to grow from USD 89.88 million in 2023 to an estimated USD 334.89 million by 2032, with a compound annual growth rate (CAGR) of 13.78% from 2024 to 2032. This significant growth is driven by the increasing demand for data storage and processing capabilities as the country advances its digital infrastructure.
The primary drivers of the Vietnam Data Center Cooling market include the growing adoption of cloud services, the surge in internet penetration, and the increasing focus on energy efficiency within data centers. Additionally, advancements in cooling technologies, such as liquid cooling and free cooling, are gaining traction, further supporting market growth. The trend toward green data centers is also encouraging the adoption of innovative cooling solutions that reduce energy consumption and operational costs.
Geographically, the market is concentrated in major urban centers such as Ho Chi Minh City and Hanoi, where the demand for data centers is the highest. Key players in the Vietnam Data Center Cooling market include Schneider Electric, Vertiv Group Corp., Delta Electronics, and STULZ GmbH, among others. These companies are focusing on expanding their product portfolios and strengthening their presence in Vietnam through strategic partnerships and investments to meet the growing demand for advanced cooling solutions in data centers.
Market Drivers
Rising Demand for Data Centers Due to Increased Digitalization and Cloud Adoption
The rapid digital transformation occurring across various sectors in Vietnam is a major driver for the data center cooling market. As businesses and government agencies increasingly rely on digital platforms for their operations, the need for robust and scalable data centers has become paramount. This shift is further accelerated by the adoption of cloud computing, which enables organizations to store and manage vast amounts of data more efficiently. For instance, Telecom Vietnam has integrated Google Cloud into its hybrid multi-cloud strategy as part of its overarching cloud-first approach. The growth of e-commerce, online services, and the digital economy as a whole has led to an exponential increase in data generation, necessitating the expansion of data centers across the country. As these facilities expand, the demand for efficient and effective cooling solutions rises, as they are crucial to maintaining optimal operating conditions and ensuring the reliability of data center operations. This surge in demand for data centers, coupled with the need to prevent overheating and downtime, directly fuels the growth of the data center cooling market in Vietnam.
Focus on Energy Efficiency and Sustainable Cooling Solutions
Energy efficiency has become a critical consideration for data center operators in Vietnam, driven by both economic and environmental concerns. As data centers are among the most energy-intensive facilities, the cost of electricity for cooling can constitute a significant portion of operational expenses. This has led to a growing emphasis on implementing energy-efficient cooling technologies that can reduce power consumption and lower operational costs. Moreover, there is an increasing focus on sustainability, as businesses and governments are becoming more aware of their carbon footprints and the environmental impact of their operations. For instance, Edge Centres opened its edge data center in Ho Chi Minh City, Vietnam, which operates on solar energy. Innovations such as free cooling, which leverages the ambient temperature to cool data centers, and liquid cooling, which is more efficient than traditional air-based cooling systems, are gaining popularity. These technologies not only offer cost savings but also contribute to achieving sustainability goals by reducing greenhouse gas emissions. The push for energy-efficient and eco-friendly cooling solutions is, therefore, a key driver of the Vietnam data center cooling market.
Government Initiatives and Support for Digital Infrastructure Development
The Vietnamese government's strong commitment to developing the country's digital infrastructure is a significant driver of the data center cooling market. Recognizing the importance of digitalization in driving economic growth and competitiveness, the government has launched various initiatives to enhance the country's IT infrastructure. These initiatives include policies to attract foreign investment in the ICT sector, development of smart cities, and the establishment of technology parks. For instance, the government has rolled out incentives and tax breaks to attract foreign investment in high-tech industries, including data center development. Additionally, the government's focus on fostering a favorable environment for the growth of the digital economy has led to the implementation of supportive regulations and incentives for data center development. These efforts have resulted in increased investments in data centers, both from domestic and international players, thereby boosting the demand for advanced cooling solutions. Furthermore, the government's push for energy-efficient and sustainable practices aligns with the growing trend of adopting green technologies in data centers, further propelling the market for innovative cooling systems.
Technological Advancements and the Emergence of New Cooling Technologies
The Vietnam data center cooling market is witnessing significant growth due to the continuous technological advancements in cooling solutions. As the complexity and scale of data centers increase, traditional cooling methods are often inadequate to meet the demands of modern facilities. This has spurred the development and adoption of new cooling technologies that offer enhanced efficiency, reliability, and scalability. Innovations such as liquid cooling, which involves the use of liquids to transfer heat away from data center components, and immersion cooling, where servers are submerged in a thermally conductive liquid, are gaining traction. These technologies provide superior cooling performance compared to conventional air-based systems and are particularly effective in high-density data center environments. Moreover, the integration of artificial intelligence (AI) and machine learning (ML) in cooling systems allows for more precise control and optimization of cooling processes, further improving energy efficiency and reducing operational costs. The emergence of these advanced cooling solutions, coupled with the growing need for high-performance data centers, is a major driver of the market in Vietnam. As more data centers adopt these cutting-edge technologies, the demand for specialized cooling systems is expected to rise significantly.
Market Trends
Shift Towards Sustainable and Energy-Efficient Cooling Solutions
The Vietnam data center cooling market is experiencing a significant shift towards sustainable and energy-efficient cooling solutions. As data centers expand to meet growing digitalization demands, managing energy consumption has become critical. Data centers are known for their high energy usage, particularly for cooling, which accounts for a substantial portion of operational costs. In response, there is increasing adoption of advanced cooling technologies that reduce energy consumption while maintaining optimal temperatures. Liquid cooling and free cooling are gaining traction due to their energy-saving potential compared to traditional air-based systems. For instance, the Vietnam National University in Ho Chi Minh City implemented a liquid cooling system, resulting in a significant reduction in cooling energy consumption. Similarly, FPT Corporation, a leading IT company in Vietnam, has adopted free cooling technologies in its data centers, leveraging the country's cooler northern climate to reduce reliance on mechanical cooling systems. This trend is driven by cost considerations and the growing focus on sustainability, aligning with global and local environmental regulations.
Growing Adoption of Modular Data Center Cooling Systems
The Vietnam data center cooling market is witnessing a growing adoption of modular cooling systems. Modular data centers, offering scalability and flexibility, are becoming increasingly popular as businesses seek to rapidly deploy data center capacity. Modular cooling systems complement these data centers by providing efficient and customizable solutions that can be scaled based on specific needs. For instance, CMC Telecom, a major telecommunications company in Vietnam, has implemented modular cooling systems in its Tier III data center in Tan Thuan, Ho Chi Minh City. These systems allow for quick deployment and reduced installation time compared to traditional setups. The Vietnam Posts and Telecommunications Group (VNPT) has also embraced modular cooling in its new data center facilities, enabling them to optimize cooling performance while minimizing energy use. This trend towards modular data center cooling reflects the broader shift towards agile and flexible data center infrastructures in Vietnam, enabling businesses to respond effectively to market demands while managing operational costs and energy consumption efficiently.
Market Restraints and Challenges
High Initial Investment and Operational Costs
One of the primary restraints in the Vietnam data center cooling market is the high initial investment required for the installation of advanced cooling systems. Implementing cutting-edge cooling technologies such as liquid cooling, immersion cooling, or modular cooling systems involves significant capital expenditure, which can be a substantial barrier for small and medium-sized enterprises (SMEs) and new market entrants. For instance, a survey by the Vietnam Chamber of Commerce and Industry found that over 60% of SMEs cited high costs as the main obstacle to adopting new technologies. Additionally, the operational costs associated with running and maintaining these sophisticated systems can be prohibitive, particularly in the context of rising electricity prices. Data from Vietnam Electricity (EVN) shows that industrial electricity rates have increased steadily over the past five years. Energy consumption for cooling represents a significant portion of a data center's operational expenses, and even with energy-efficient systems, the costs can be considerable. This financial burden may deter some organizations from adopting the latest cooling technologies, potentially slowing the overall growth of the market.
Technical and Infrastructure Challenges
The Vietnam data center cooling market also faces several technical and infrastructure challenges that can hinder its growth. One major challenge is the limited availability of skilled professionals with the expertise required to design, implement, and maintain advanced cooling systems. According to a report by the Ministry of Information and Communications, there is a significant shortage of IT professionals in Vietnam, with demand outpacing supply by a factor of 4 to 1. The technical complexity of modern cooling solutions demands a deep understanding of both IT infrastructure and HVAC systems, which can be difficult to source locally. Additionally, Vietnam's infrastructure development, while progressing, still faces limitations, particularly in rural or less developed areas where power supply and grid reliability may not be optimal. Data from the World Bank indicates that Vietnam's electrification rate is high at 99%, but power outages and voltage fluctuations remain concerns in some regions. These infrastructure constraints can pose significant challenges for the deployment and operation of data centers, particularly in maintaining consistent and reliable cooling. Moreover, the country's tropical climate, characterized by high temperatures and humidity, adds to the difficulty of achieving efficient cooling.
Market Segmentation Analysis
By Component
The Vietnam data center cooling market is segmented by component into solutions and services. The solutions segment includes a variety of cooling technologies such as air conditioners, precision air conditioners, chillers, and air handling units, which are essential for maintaining optimal temperatures in data centers. For instance, a survey conducted by the Vietnam Data Center Association found that air conditioning systems account for the largest share of cooling solutions deployed in Vietnamese data centers. The services segment encompasses installation and deployment, support and consulting, and maintenance services. According to a report by the Ministry of Information and Communications, the demand for specialized cooling services has grown significantly as data centers become more complex and energy-intensive.
By Application
By application, the market is segmented into Telecom & IT, Retail & BFSI, Healthcare, Energy, and Others. The Telecom & IT sector dominates the market due to the rapid digitalization and growth of cloud computing in Vietnam. For example, a study by the Vietnam Internet Association revealed that the number of data centers operated by telecom companies has doubled in the past five years. The Retail & BFSI sectors also contribute significantly, with increasing reliance on data centers for online transactions and data management. A survey by the State Bank of Vietnam indicated that over half of the country's banks have invested in dedicated data center facilities with advanced cooling systems. The healthcare and energy sectors are emerging segments, driven by the rising adoption of digital technologies and the need for secure, reliable data centers to manage critical information and operations.
Segments
Based on Component
- Solution
- Services
Based on Application
- Telecom & IT
- Retail & BFSI
- Healthcare
- Energy
- Others
Based on Solution
- Air Conditioners
- Precision Air Conditioners
- Chillers
- Air Handling Units
- Others
Based on Containment
- Raised Floor with Containment
- Hot Aisle Containment (HAC)
- Cold Aisle Containment (CAC)
- Raised Floor without Containment
Based on Services
- Installation & Deployment
- Support & Consulting
- Maintenance Services
Based on Cooling Type
- Raised Floor
- Non-Raised Floors
Based on Structure
- Rack-based Cooling
- Row-based Cooling
- Room-based Cooling
Based on Region
- Urban
- Rural
Regional Analysis
Ho Chi Minh City (40%):
Ho Chi Minh City is the largest market for data center cooling solutions in Vietnam, accounting for approximately 40% of the total market share. The city's status as Vietnam's economic powerhouse attracts numerous multinational corporations, financial institutions, and technology companies, driving demand for robust data center infrastructure. For instance, a recent survey by the Ho Chi Minh City Department of Information and Communications found that over 70% of large enterprises in the city have invested in or plan to invest in data center facilities within the next two years. The rapid growth of digital services and e-commerce in the region has further accelerated the need for advanced cooling solutions. The city's high-tech parks and IT zones, such as the Saigon Hi-Tech Park, have become hubs for data center development, contributing to the strong demand for cooling technologies.
Hanoi (30%):
Hanoi, the capital of Vietnam, holds the second-largest market share, representing around 30% of the total market. The city's position as the political and administrative center of the country drives demand from government agencies, financial institutions, and large corporations. For instance, a government report on digital infrastructure development indicated that Hanoi has seen a 25% year-on-year increase in data center investments over the past three years. The city's digital transformation initiatives have led to the establishment of several technology parks and innovation hubs, such as the Hoa Lac Hi-Tech Park, which houses multiple data centers. A recent survey conducted by the Hanoi Department of Information and Technology revealed that over 60% of businesses in the city consider data center cooling solutions a critical investment for their IT infrastructure expansion plans.
Key players
- Stulz GmbH
- Mitsubishi Electric Corporation
- Schneider Electric SE
- Huawei Technologies Co., Ltd.
- Johnson Controls International PLC (York International)
- Airedale International Air Conditioning Ltd.
- Rittal GMBH & Co. KG
- Daikin Industries Ltd.
- Munters Group AB
Competitive Analysis
The Vietnam data center cooling market is highly competitive, with both global and regional players striving for market dominance. Key players such as Schneider Electric SE, Huawei Technologies Co., Ltd., and Mitsubishi Electric Corporation lead the market with their wide range of innovative cooling solutions and strong presence in the global data center infrastructure sector. These companies benefit from their well-established distribution networks and advanced technological capabilities, which allow them to cater to large-scale data centers in urban areas. Companies like Stulz GmbH, Rittal GMBH & Co. KG, and Airedale International Air Conditioning Ltd. are known for their specialized solutions, focusing on precision cooling and energy-efficient systems. Meanwhile, Johnson Controls (York International) and Daikin Industries Ltd. leverage their expertise in HVAC systems to offer reliable cooling solutions. The market also sees rising competition from niche players such as Munters Group AB, which focuses on sustainable cooling technologies.
Recent Developments
- In May 2022, Stulz announced the launch of the CyberCoolFree Cooling Booster, a new free cooling module for data centers and industrial applications. While not specific to Vietnam, this product is likely available in the Vietnamese market.
- In May 2024, Mitsubishi Electric announced the launch of heat-related total solutions for manufacturers, building owners, and heat-supply operators. This includes heat pump chillers and other cooling equipment that could be applicable to data centers in Vietnam.
- In February 2024, Huawei launched its SmartDC solution for large-scale data centers at MWC Barcelona. This solution incorporates integrated power supply, prefabrication, and distributed cooling to build reliable, simplified, and sustainable computing infrastructure. While not specific to Vietnam, this solution is likely to be available in the Vietnamese market.
- In 2024, Airedale by Modine introduced new cloud-based monitoring and diagnostics platforms for mission-critical HVAC plants and multiple site HVAC systems. This development could potentially benefit data center cooling operations in Vietnam.
Market Concentration and Characteristics
The Vietnam Data Center Cooling market is moderately concentrated, with a mix of global leaders and specialized regional players competing for market share. Major international companies like Schneider Electric SE, Huawei Technologies Co., Ltd., and Mitsubishi Electric Corporation hold significant influence due to their extensive portfolios and advanced technologies. These companies benefit from economies of scale, strong R&D capabilities, and established partnerships with local enterprises. At the same time, specialized players such as Stulz GmbH and Airedale International Air Conditioning Ltd. provide niche solutions focusing on precision cooling and energy efficiency, appealing to data centers with specific requirements. The market is characterized by increasing demand for sustainable and energy-efficient solutions, driven by rising digitalization, cloud adoption, and Vietnam's push toward greener technologies. This trend encourages both large and smaller players to innovate and differentiate their offerings, maintaining a competitive yet growing market environment.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, Solution, Containment, Services, Cooling Type, Structure and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Vietnam data center cooling market is expected to witness robust growth, projected to reach USD 334.89 million by 2032, driven by increased digitalization and data center expansion.
- As energy costs rise, data center operators will increasingly adopt energy-efficient cooling technologies, such as liquid cooling and free cooling, to reduce operational expenses.
- The trend toward green data centers will continue to drive demand for cooling solutions that minimize energy consumption and lower carbon footprints, aligning with global sustainability goals.
- Ongoing innovation in cooling technologies, including AI-based climate control and immersion cooling, will further enhance the efficiency and precision of data center cooling solutions in Vietnam.
- Growing investment in cloud services, data storage, and IT infrastructure will lead to higher demand for scalable and reliable cooling systems to support data center expansion.
- The rise of modular data centers, which offer flexible and scalable cooling solutions, is expected to boost the demand for modular cooling systems, particularly in smaller and mid-sized facilities.
- Vietnam's government initiatives to promote digitalization and smart city development will fuel further investment in data centers, driving the need for advanced cooling solutions.
- The proliferation of edge computing will increase the demand for cooling solutions tailored to smaller, decentralized data centers, especially in rural and underdeveloped regions.
- As data center cooling systems become more complex, the need for maintenance, support, and consulting services will grow, ensuring optimal performance and reducing downtime.
- The market will see intensified competition as both global and regional players continue to innovate and expand their presence in Vietnam, pushing the development of more advanced and cost-effective cooling technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Vietnam Data Center Cooling market in 2023 and 2032?
What are the key drivers of growth in the Vietnam Data Center Cooling market?
Which sectors are driving demand for data center cooling solutions in Vietnam?
What cooling technologies are gaining popularity in Vietnam?
How is the Vietnamese government supporting the data center cooling market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Vietnam Data Center Cooling Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Vietnam Data Center Cooling Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 89.88 million → 2032: USD 334.89 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Vietnam Data Center Cooling Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Vietnam Data Center Cooling Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Vietnam Data Center Cooling Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Vietnam Data Center Cooling Market Drivers
- 3.3 Vietnam Data Center Cooling Market Restraints & Challenges
- 3.4 Vietnam Data Center Cooling Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Vietnam Data Center Cooling Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Vietnam Data Center Cooling Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Vietnam Data Center Cooling category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Vietnam Data Center Cooling Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Vietnam Data Center Cooling Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Vietnam Data Center Cooling market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Vietnam Data Center Cooling Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Vietnam Data Center Cooling Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Vietnam Data Center Cooling Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Vietnam Data Center Cooling (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Vietnam Data Center Cooling Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Vietnam Data Center Cooling Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Vietnam Data Center Cooling Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Vietnam Data Center Cooling Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Vietnam Data Center Cooling Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Vietnam Data Center Cooling Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Vietnam Data Center Cooling Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Vietnam Data Center Cooling Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Vietnam Data Center Cooling Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
