
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Vinyl acetate monomer (VAM) market Size 2023 | USD 9,355.5 million |
| Vinyl acetate monomer (VAM) market, CAGR | 5.80% |
| Vinyl acetate monomer (VAM) market Size 2032 | USD 14,687.65 million |
Market Overview:
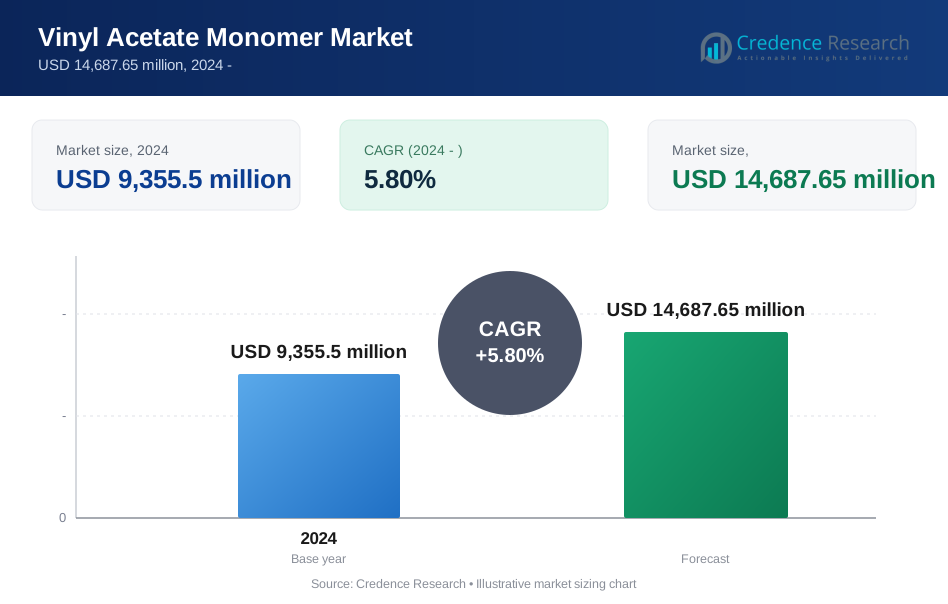
The global vinyl acetate monomer (VAM) market is projected to grow from USD 9,355.5 million in 2024 to approximately USD 14,687.65 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.80%. Vinyl acetate monomer is a key intermediate chemical used in producing polymers and resins, such as polyvinyl acetate (PVA) and polyvinyl alcohol (PVOH), essential for various applications. VAM plays a critical role in the production of adhesives, paints and coatings, textiles, and packaging materials. With rising demand from key industries, particularly construction, automotive, and packaging, the VAM market is set to experience steady growth over the forecast period.
The market growth is driven by increasing demand from the adhesives and coatings industry, as VAM-based adhesives provide strong bonding and durability. Additionally, VAM is integral to the production of water-based paints and coatings, which are preferred due to their lower environmental impact compared to solvent-based alternatives. The packaging sector also contributes to the rising demand for VAM, as polyvinyl acetate adhesives are extensively used in flexible packaging materials. Furthermore, the growing emphasis on energy-efficient buildings and infrastructure is driving demand for VAM-based construction materials, such as paints, coatings, and adhesives. Technological advancements in VAM production processes have also led to improved yield and cost efficiency, further supporting market expansion.
Regionally, the Asia-Pacific region holds the largest share of the vinyl acetate monomer market, driven by strong industrial activity in countries like China, India, and Japan. China, in particular, is a major consumer of VAM due to its vast manufacturing sector and high demand from the construction and automotive industries. North America follows closely, with a well-established market for adhesives and coatings, particularly in the U.S. In Europe, the market is supported by the region’s automotive and packaging industries, with countries like Germany and France as key contributors. Emerging markets in Latin America and the Middle East & Africa are also expected to witness growth, spurred by rising construction activity and industrial expansion, providing new opportunities for VAM applications across various sectors.
Market Drivers:
Rising Demand from the Adhesives and Sealants Industry:
The demand for vinyl acetate monomer (VAM) in the adhesives and sealants industry is substantial, primarily due to VAM’s excellent binding properties. Polyvinyl acetate (PVA), a derivative of VAM, is widely used in adhesives for woodworking, packaging, and construction applications because of its strong adhesion and water resistance. For instance, the Adhesive and Sealant Council notes that adhesives formulated with PVA offer superior bonding for wood and paper products, making them indispensable in the packaging and furniture sectors. The construction industry’s growing need for durable and reliable adhesives further drives demand, as VAM-based adhesives help to improve structural integrity in both residential and commercial buildings.
Expansion of the Paints and Coatings Sector:
Vinyl acetate monomer is a critical raw material in the production of water-based paints and coatings, which are gaining popularity for their low volatile organic compound (VOC) emissions and environmental benefits. For instance, According to the European Coatings Journal, water-based coatings account for over 60% of the global coatings market due to their minimal environmental impact. As governments worldwide implement stricter environmental regulations, demand for eco-friendly paints and coatings continues to rise. VAM’s role in producing these coatings has solidified its importance in the industry, particularly in markets focused on reducing VOC emissions, such as North America and Europe.
Growth in the Packaging Industry:
The packaging industry’s expansion, fueled by increased e-commerce activity and demand for consumer goods, is a key driver of VAM demand. Polyvinyl acetate (PVA) adhesives are integral to flexible packaging materials, providing durable and secure bonding for a range of packaging applications. For example, according to the Flexible Packaging Association, flexible packaging is the second-largest packaging segment in the United States, driven by food and beverage products that require durable, lightweight, and cost-effective packaging solutions. As consumer goods companies prioritize sustainable and high-performance packaging, the demand for VAM-based adhesives in this sector is expected to grow.
Increased Use in Solar Power and Energy-Efficient Applications:
The rise of renewable energy sources, especially solar power, is boosting the use of VAM in solar panel encapsulation materials. Ethylene-vinyl acetate (EVA), a key component in solar panel encapsulation, enhances durability and ensures reliable performance over time. For instance, the International Energy Agency (IEA) reported a 22% increase in global solar capacity in 2022, underscoring the need for materials that improve panel longevity. Furthermore, as energy-efficient building practices become more common, VAM-based products in insulation and weatherproof coatings are increasingly essential, aligning with global efforts to reduce energy consumption in residential and commercial buildings.
Market Trends:
Shift Towards Bio-Based Vinyl Acetate Monomer:
As industries strive for sustainability, there is an increasing trend towards the development and use of bio-based vinyl acetate monomer (VAM). Bio-based VAM is derived from renewable resources, which reduces dependency on petroleum-based raw materials and minimizes environmental impact. For instance, companies such as BASF are investing in research to develop VAM derived from bioethanol, aligning with the demand for eco-friendly raw materials. This trend reflects the broader shift across chemical industries to transition towards greener, renewable resources in response to both consumer demand and regulatory pressure for sustainable products.
Increased Focus on Production Efficiency and Cost Optimization:
To meet the growing demand and manage production costs, VAM manufacturers are investing in advanced technologies that improve production efficiency. Innovations such as catalytic processes and reactor designs that increase VAM yield are being adopted to optimize production. For example, Dow Chemical has explored catalytic systems that enhance efficiency, reduce waste, and minimize energy consumption in VAM production. This focus on production optimization is particularly important in regions like Asia-Pacific, where industrial output is high, and manufacturers aim to maximize resource efficiency to remain competitive.
Expansion of Application in the Textile and Footwear Industries:
Vinyl acetate monomer is gaining traction in the textile and footwear industries for producing polyvinyl alcohol (PVOH), which is used in water-soluble films, sizing agents, and adhesives. In the textile industry, PVOH improves fabric durability and provides a soft finish. For instance, The Japanese Ministry of Economy, Trade, and Industry reports that PVOH-based films are increasingly popular for their biodegradability and ease of use. In the footwear industry, PVOH applications are favored for their excellent bonding properties, contributing to more durable, high-performance footwear products. This trend underscores VAM’s versatility and the growing demand for performance-enhancing materials across a range of consumer goods.
Rising Investment in VAM Production Capacity in Asia-Pacific:
Asia-Pacific is witnessing significant investments in VAM production capacity due to the region’s strong manufacturing base and rising demand from end-use industries. Major producers, such as Celanese and Sinopec, are expanding facilities in countries like China and India to meet the increasing demand for VAM in adhesives, coatings, and packaging. The Chinese Ministry of Industry and Information Technology has reported rising demand for industrial chemicals, including VAM, driven by rapid urbanization and industrialization. This regional focus on capacity expansion not only strengthens local supply chains but also positions Asia-Pacific as a leading VAM production hub for the global market.
Market Challenges Analysis:
Volatility in Raw Material Prices:
The vinyl acetate monomer (VAM) market is highly susceptible to fluctuations in raw material costs, particularly ethylene and acetic acid, which are derived from crude oil. Variations in crude oil prices due to geopolitical tensions, supply chain disruptions, and production changes can significantly impact the cost structure of VAM. For instance, the U.S. Energy Information Administration (EIA) has reported frequent fluctuations in crude oil prices, causing instability for petrochemical industries reliant on these resources. Manufacturers face the challenge of maintaining profit margins while managing the unpredictability of raw material costs.
Environmental and Health Concerns:
VAM production involves handling hazardous chemicals that pose environmental and health risks, leading to stringent regulatory scrutiny. Regulatory agencies, such as the U.S. Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA), enforce strict regulations on the handling, transportation, and disposal of chemicals involved in VAM production. These regulations increase compliance costs for manufacturers and can slow down production processes. Additionally, the presence of volatile organic compounds (VOCs) in VAM applications, such as adhesives and coatings, raises concerns about air quality, which further influences the regulatory landscape.
Competition from Alternative Materials:
The VAM market faces competition from alternative materials, particularly in the adhesives and coatings sectors, where alternatives such as polyurethane and acrylic-based adhesives are becoming more popular. These alternatives offer performance benefits, such as enhanced durability and lower VOC emissions, appealing to industries focused on sustainability. The growing adoption of these alternatives in regions like North America and Europe could limit VAM’s market share, as manufacturers seek materials that align with environmental goals.
Capacity Constraints and Production Limitations:
Expanding VAM production capacity requires significant capital investment and infrastructure, presenting a challenge for smaller manufacturers. Additionally, any disruption in production facilities, such as those caused by maintenance shutdowns or natural disasters, can impact supply availability, particularly in regions with limited capacity. This situation can lead to supply constraints that elevate prices and create supply chain challenges, particularly for end users reliant on consistent VAM availability for manufacturing processes.
Market Segmentation Analysis:
By Type
The vinyl acetate monomer (VAM) market is segmented by type into polyvinyl acetate (PVA), polyvinyl alcohol (PVOH), and ethylene-vinyl acetate (EVA). Polyvinyl acetate, primarily used in adhesives and coatings, is one of the largest segments due to its strong bonding properties and versatility. Polyvinyl alcohol, valued for its water solubility and film-forming capabilities, is widely used in textiles, packaging, and specialty films. Ethylene-vinyl acetate, known for its flexibility and resilience, is popular in the production of footwear, solar encapsulation materials, and various industrial applications. Each type caters to different industry needs, supporting VAM’s broad utility across sectors.
By Technology
In terms of technology, the market includes suspension polymerization, emulsion polymerization, and bulk polymerization. Suspension polymerization is commonly used for VAM products with higher purity requirements, often in coatings and adhesives. Emulsion polymerization, which produces fine particles ideal for paints and coatings, is widely used due to its cost efficiency and environmental advantages, such as lower VOC emissions. Bulk polymerization, suitable for producing thermoplastics and adhesives, allows for faster production rates, aligning with the needs of industries requiring large volumes of VAM-based products. Advancements in these technologies continue to enhance product efficiency and performance across applications.
By End User The main end users of VAM are the construction, automotive, packaging, and textile industries. The construction sector is the largest consumer, utilizing VAM-based adhesives, coatings, and paints for durable and moisture-resistant applications. The automotive industry relies on EVA for lightweight, impact-resistant materials, while the packaging sector benefits from PVOH and PVA for flexible packaging solutions. The textile industry uses PVOH for fabric finishes and treatments, enhancing durability and ease of care. This segmentation underscores VAM’s critical role in supporting a diverse range of industrial applications.
Segmentations:
- By Purity:
- 99% & Above
- <99%
- By Application:
- Polyvinyl Alcohol
- Polyvinyl Acetate
- Ethylene Vinyl Acetate
- Ethylene Vinyl Alcohol
- By End-use Industry:
- Packaging
- Construction
- Textiles
- Cosmetics
- By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis:
Asia-Pacific Asia-Pacific holds the largest share of the vinyl acetate monomer (VAM) market, accounting for approximately 40% of the global demand. This dominance is driven by high industrial activity in countries like China, India, Japan, and South Korea. China, in particular, is a major producer and consumer of VAM, owing to its expansive manufacturing sector and significant demand from the construction and automotive industries. The country’s rapid urbanization and industrialization have led to a sustained need for VAM-based adhesives, coatings, and packaging materials. India, with its fast-growing packaging and construction sectors, is also contributing significantly to regional growth. In Japan and South Korea, VAM is primarily used in the production of high-performance adhesives and advanced materials for the automotive and electronics industries. This strong industrial base positions Asia-Pacific as a vital hub for VAM production and consumption, driving continuous investment in production capacity expansion to meet the rising demand.
North America North America represents around 25% of the global VAM market share, supported by robust demand in the United States and Canada. In the U.S., the construction industry is a major consumer of VAM, utilizing it in paints, coatings, and adhesives due to its durability and moisture resistance. The U.S. automotive industry also relies on ethylene-vinyl acetate (EVA) for lightweight, impact-resistant components, which contribute to improved fuel efficiency. Canada is seeing increased demand for eco-friendly, VAM-based products as it continues to prioritize sustainable building practices. North America’s market growth is further fueled by the increasing adoption of water-based coatings and adhesives, which utilize VAM due to their low VOC emissions. Additionally, the region’s stringent environmental regulations encourage companies to invest in more sustainable VAM technologies, driving product innovation and growth in the sector.
Europe Europe accounts for approximately 20% of the global VAM market, with strong demand from the automotive, packaging, and construction industries. Key markets include Germany, France, and the United Kingdom, where there is a high demand for adhesives and coatings that align with the European Union’s strict environmental standards. The automotive sector in Europe, which is heavily focused on sustainability, increasingly uses EVA in applications requiring lightweight, durable materials. Moreover, Europe’s packaging industry utilizes VAM-based polyvinyl acetate (PVA) adhesives for flexible and eco-friendly packaging solutions. The region’s regulatory framework supports market growth by encouraging low-emission, water-based alternatives, positioning Europe as a leader in the adoption of environmentally friendly VAM applications.
Latin America, the Middle East & Africa Latin America, the Middle East, and Africa, collectively represents about 15% of the VAM market. While these regions have smaller market shares, they are gradually expanding due to rising industrial and infrastructure investments. In Latin America, countries like Brazil and Mexico are seeing increased demand for VAM in construction and automotive applications, spurred by urbanization and growth in consumer goods. In the Middle East and Africa, construction and packaging sectors are the primary drivers of VAM demand, with governments prioritizing infrastructure development and economic diversification. As these regions continue to invest in industrialization and urban development, the demand for VAM is expected to grow, providing new opportunities for market expansion beyond the traditional industrial centers.
Key Player Analysis:
- Celanese Corporation
- Dow Chemical Company
- Kuraray Co., Ltd.
- LyondellBasell Industries N.V.
- SIPCHEM (Saudi International Petrochemical Company)
- Dairen Chemical Corporation
- Wacker Chemie AG
- Sinopec Corp.
- Lotte Chemical Corporation
- Arkema S.A.
Competitive Analysis:
The vinyl acetate monomer (VAM) market is highly competitive, with major players such as Celanese Corporation, Dow Chemical Company, and Kuraray Co., Ltd. holding significant shares due to their advanced production capabilities and strong global distribution networks. These companies lead by leveraging extensive R&D investments to improve production efficiency and develop innovative products, such as bio-based VAM, to meet rising demand for sustainable alternatives. Furthermore, many key players are expanding their manufacturing facilities, particularly in Asia-Pacific, to cater to the growing industrial sectors in China and India. Competitive pressures are also driven by regulatory demands, as firms strive to produce low-emission and environmentally friendly products that align with stringent regional standards in North America and Europe. Smaller players and new entrants face challenges in establishing themselves due to the capital-intensive nature of VAM production and the dominance of established firms with well-established customer bases and supplier relationships.
Recent Developments:
- In 2023, Dow entered a partnership with New Energy Blue to produce bio-based ethylene from agricultural residues, marking the first agreement of its kind in North America. This partnership aims to reduce carbon emissions by using renewable resources to create ethylene, which can be integrated into VAM production. This initiative supports Dow's goal to expand its use of sustainable feedstocks and reduce reliance on fossil fuels.
- Announced in early 2024, Dow's Path2Zero initiative is a multi-billion-dollar investment aimed at decarbonizing its production processes. The project includes plans for circular hydrogen and carbon capture facilities, which will help Dow lower its overall carbon footprint. The project will be instrumental in developing cleaner production methods for its VAM and other materials.
- Dow is also increasing its propylene glycol capacity at its facility in Map Ta Phut, Thailand, expected to be fully operational by 2024. This expansion is part of Dow's broader strategy to meet rising demand in Asia-Pacific for high-performance materials across multiple sectors, including packaging and construction. Enhanced capacity will allow Dow to support the regional growth of VAM and other essential chemical products.
- In 2022, Dow announced advancements in its portfolio by focusing on products with lower carbon footprints, including sustainable VAM derivatives. This aligns with their commitment to addressing climate change through innovation and producing materials that meet stringent environmental standards, particularly in high-growth markets like infrastructure and consumer goods.
Market Concentration & Characteristics:
The vinyl acetate monomer (VAM) market is moderately concentrated, dominated by key players such as Dow Chemical Company, Celanese Corporation, and Kuraray Co., Ltd., which collectively hold significant market shares due to their extensive production capacities, robust R&D investments, and global distribution networks. These companies leverage economies of scale and advanced production technologies to maintain competitive advantages, particularly in regions like Asia-Pacific and North America, where demand from construction, automotive, and packaging industries is high. The market is characterized by high capital requirements, as VAM production involves complex processes and significant environmental compliance measures, which present barriers to entry for smaller players. Additionally, the market is driven by sustainability trends, with major producers investing in bio-based and low-emission VAM products to align with global regulatory standards and rising consumer demand for eco-friendly materials. The competitive landscape reflects a focus on innovation, strategic partnerships, and capacity expansion to meet global demand.
Report Coverage:
The research report offers an in-depth analysis based on Purity, Application, End-use Industry, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The vinyl acetate monomer (VAM) market is expected to expand as demand rises for adhesives, coatings, and sealants in the construction and packaging industries, driven by rapid infrastructure development globally.
- Growing interest in sustainable products will push manufacturers to develop bio-based VAM and adopt production processes that reduce carbon emissions.
- The Asia-Pacific region, particularly China and India, is likely to see substantial growth due to its strong industrial base.
- Investments in production capacity expansions by key players, such as Dow and Celanese, will enhance supply capabilities to meet increasing regional and global demand.
- Advancements in polymer technology will drive the use of VAM in solar encapsulation and other renewable energy applications.
- The North American market is expected to grow, supported by stringent environmental regulations that favor low-VOC water-based paints and coatings.
- Rising e-commerce activity and consumer demand for sustainable, flexible packaging solutions will boost VAM demand for packaging adhesives.
- The shift towards energy-efficient and lightweight materials in the automotive sector will increase VAM usage in ethylene-vinyl acetate (EVA) applications for vehicle components.
- Strategic partnerships and collaborations among key industry players will focus on innovation, ensuring VAM products meet the evolving needs of high-growth end markets.
- Overall, the market will emphasize sustainable development, operational efficiency, and diversified applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Vinyl Acetate Monomer Market?
What factors are driving the growth of the Vinyl Acetate Monomer market?
What are some challenges faced by the Vinyl Acetate Monomer market?
Who are the major players in the Vinyl Acetate Monomer Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Vinyl Acetate Monomer Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Vinyl Acetate Monomer Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 9,355.5 million → forecast year: USD 14,687.65 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Vinyl Acetate Monomer Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Vinyl Acetate Monomer Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Vinyl Acetate Monomer Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Vinyl Acetate Monomer Market Drivers
- 3.3 Vinyl Acetate Monomer Market Restraints & Challenges
- 3.4 Vinyl Acetate Monomer Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Vinyl Acetate Monomer Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Vinyl Acetate Monomer Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Vinyl Acetate Monomer category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Vinyl Acetate Monomer Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Vinyl Acetate Monomer Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Vinyl Acetate Monomer market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Vinyl Acetate Monomer Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Vinyl Acetate Monomer Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Vinyl Acetate Monomer Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Vinyl Acetate Monomer (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Vinyl Acetate Monomer Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Vinyl Acetate Monomer Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Vinyl Acetate Monomer Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Vinyl Acetate Monomer Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Vinyl Acetate Monomer Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Vinyl Acetate Monomer Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Vinyl Acetate Monomer Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Vinyl Acetate Monomer Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Vinyl Acetate Monomer Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
