
Market Overview:
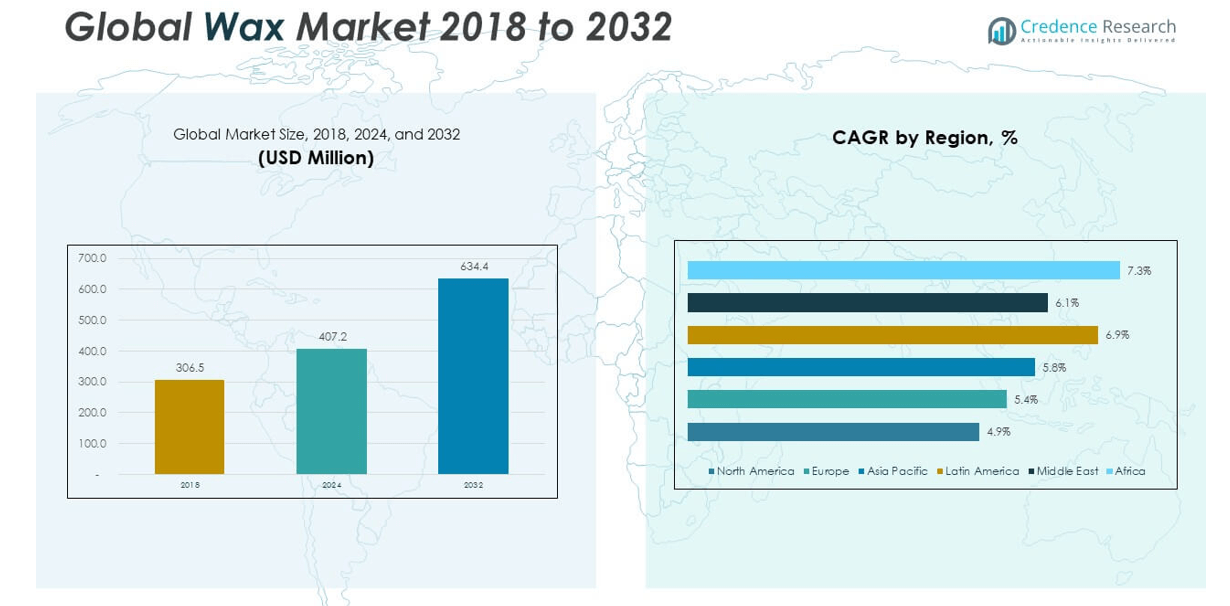
The Global Wax Market size was valued at USD 7,475.49 million in 2018 to USD 9,595.46 million in 2024 and is anticipated to reach USD 13,324.48 million by 2032, at a CAGR of 4.16% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wax Market Size 2024 | USD 9,595.46 million |
| Wax Market, CAGR | 4.16% |
| Wax Market Size 2032 | USD 13,324.48 million |
The wax market is propelled by expanding applications across industries, driven by evolving consumer preferences and technological trends. In packaging, wax enhances product durability and barrier performance, spurred by booming e‑commerce and fresh‑produce coatings. The cosmetics sector increasingly adopts waxes for structure and skin feel in lipsticks, creams, and haircare, aligning with rising clean‑label and sustainable demands. Candle makers continue to fuel volume growth with scented and decorative products, particularly in mature markets seeking home fragrance and ambience. Meanwhile, technical waxes like synthetic and Fischer‑Tropsch grades are gaining ground in adhesives, coatings, and inks due to superior melting range, cohesion, and water resistance, especially in logistics and printing. Innovations in solvent‑free extraction and gas‑to‑liquids production are improving yields and supply reliability. Regulatory shifts in Europe targeting PAHs and single‑use plastics are accelerating the adoption of bio‑based natural waxes. Additionally, extraction advances and strategic offtake agreements are securing long‑chain plant wax supplies, meeting demand from cosmetics and edible coatings. Collectively, these cross‑industry drivers create a landscape where high‑volume commodity grades sustain scale and specialty segments deliver premium margins, fueling steady market expansion.
Regionally, Asia‑Pacific dominates the wax market, with China, India, and ASEAN leading due to integrated refining, large consumer goods production, and rapid growth in e‑commerce and personal care sectors. China anchors demand in candles, packaging, and cosmetics, while India’s beekeeping base offers strong growth potential for beeswax and natural types. ASEAN’s parcel volumes drive demand for high‑performance hot‑melt adhesive waxes. Europe holds the second-largest share and is shifting toward plant‑based and food-grade waxes, influenced by regulatory pressures and a mature cosmetics industry. Germany and the UK serve as major hubs for pharmaceutical and coating-grade waxes. North America follows, benefiting from shale‑derived ethane feedstock that supports competitive synthetic wax exports, with the U.S. leading in packaging and industrial applications. Emerging regions include Latin America and the Middle East & Africa, where infrastructure development and rising consumer goods manufacturing are gradually increasing wax consumption, though they remain behind established markets in scale.
Market Insights:
- The Global Wax Market was valued at USD 7,475.49 million in 2018 and is projected to reach USD 13,324.48 million by 2032, growing at a CAGR of 4.16%.
- E-commerce growth and demand for sustainable packaging solutions are driving wax applications in corrugated coatings and hot melt adhesives.
- Cosmetics and personal care industries are boosting demand for specialty and natural waxes like beeswax and carnauba due to clean-label preferences.
- Scented and decorative candle production remains a high-volume application, supported by lifestyle trends and seasonal demand in North America and Europe.
- Technical waxes, including Fischer-Tropsch types, are gaining traction in coatings, inks, and concrete curing, driven by infrastructure growth in Asia and the Middle East.
- Fluctuating petroleum feedstock supply and shifting refinery practices are limiting paraffin wax availability, creating pricing and supply challenges.
- Asia-Pacific leads the market due to strong refining capacity and consumer manufacturing, while Europe shifts to plant-based waxes and North America excels in synthetic exports.
Market Drivers:
Expansion of Packaging and E-commerce Industries Driving Wax Demand for Protective Coatings:
The rapid growth of e-commerce and the packaging sector is a major driver for the Global Wax Market. Manufacturers use wax coatings to enhance water resistance, abrasion protection, and printability of corrugated boxes and paper-based packaging. Demand for protective wax applications continues to rise with increased shipments of perishables, electronics, and fragile items. Wax-based hot melt adhesives also support efficient, tamper-proof packaging solutions. The packaging industry’s shift toward sustainable materials sustains demand for natural and biodegradable wax alternatives. It is reinforcing its relevance by enabling both functionality and eco-compliance.
- For instance, Smurfit Kappa supplied McCormack Family Farms with a water-resistant, biodegradable coating for its cardboard produce trays, replacing wax-lined and PET-coated alternatives and enabling fully recyclable and moisture-resistant packaging. The coating, developed at Smurfit Kappa’s Markham Vale site, allowed McCormack Family Farms to place orders for two lines after sample testing, demonstrating a concrete operational shift toward sustainable solutions in the packaging supply chain.
Cosmetics and Personal Care Sector Fueling Demand for Specialty and Natural Waxes:
The Global Wax Market benefits significantly from the cosmetics and personal care industry. Waxes are key ingredients in lipsticks, balms, mascaras, lotions, and hair products, where they provide structure, gloss, and texture. Growing consumer preference for clean-label and vegan cosmetics boosts demand for natural waxes such as beeswax, carnauba, and rice bran wax. Manufacturers adopt waxes for their emollient properties and ability to stabilize emulsions. Innovation in plant-derived wax blends supports broader formulation compatibility. It meets evolving formulation needs while ensuring sensory quality and product performance.
- For instance, L'Oréal launched a line of natural and organic skincare products featuring beeswax as a key ingredient. This strategic launch responded to consumer demand for clean-label cosmetics and exemplified industry adoption of specialty waxes for structure and formulation stability in a global cosmetics portfolio.
Growth in Candle Manufacturing Supported by Lifestyle and Cultural Preferences:
The candle industry remains a high-volume consumer in the Global Wax Market, particularly in North America and Europe. Demand for scented and decorative candles continues to grow with changing lifestyle preferences, wellness trends, and interior aesthetics. Seasonal festivals, religious practices, and gifting traditions sustain year-round consumption. Manufacturers invest in paraffin alternatives such as soy and palm wax to align with sustainability and health priorities. Fragrance load compatibility and burn characteristics remain key formulation drivers. It continues to meet consumer preferences for both utility and ambiance.
Industrial and Construction Applications Driving Technical Wax Utilization:
Industrial applications in coatings, rubber, and construction materials drive the use of Fischer-Tropsch and synthetic waxes. These grades offer superior hardness, thermal resistance, and lubrication properties. Wax is used in concrete curing compounds, polishes, inks, and cable insulation to improve product performance. The growth of infrastructure projects in Asia and the Middle East supports volume expansion. Regulatory compliance and product longevity further support wax use in industrial-grade formulations. It enables technical enhancements across diverse downstream sectors.
Market Trends:
Transition Toward Bio-Based and Renewable Wax Alternatives Across End-Use Industries:
The Global Wax Market is witnessing a clear trend toward renewable and bio-based wax solutions. Manufacturers are developing plant-sourced waxes that offer similar properties to paraffin while reducing carbon footprint. Consumer-facing industries such as cosmetics, food coatings, and packaging are leading adopters of natural alternatives. Feedstocks like soy, coconut, sunflower, and rice bran are increasingly used in wax extraction. Environmental regulations in Europe and demand for sustainable labeling drive this transition. It fosters a shift in sourcing strategy among wax producers.
- For instance, Cargill has expanded its portfolio to include bio-waxes produced from renewable sources, supporting applications in both food packaging and cosmetics. The company has reported substantial increases in bio-wax demand, emphasizing its role as a supplier of sustainable wax alternatives for major global brands.
Advancements in Gas-to-Liquids and Coal-to-Liquids Technologies Improving Wax Supply Security:
Technological improvements in GTL and CTL processes are transforming the supply base of synthetic waxes. Companies are expanding their capabilities to produce high-purity waxes using these methods, reducing reliance on petroleum-based feedstocks. These waxes offer excellent consistency and are ideal for precision applications such as cosmetics and pharmaceuticals. Emerging economies with access to natural gas or coal reserves are entering the production space. The diversification of supply chains supports price stability and availability. It strengthens the resilience of the synthetic wax segment.
- For instance, Shell Middle Distillate Synthesis (Shell MDS) in Malaysia launched the world’s first commercial-scale Gas-to-Liquids (GTL) synthetic microcrystalline wax in 2024. The plant’s automation allows microcrystalline wax production at commercial scale, with high purity suitable for premium applications such as cosmetics, adhesives, and pharmaceuticals. This development follows six years of research and concept-to-market execution in technological partnership with European manufacturers.
Smart Candle Innovations and Fragrance Integration Reshaping Consumer Products:
Smart candle technology is gaining momentum in premium lifestyle markets. Manufacturers integrate LED lighting, remote controls, and fragrance diffusion into candle designs, enhancing user experience. Fragrance encapsulation and release control technologies are also advancing. These innovations increase the perceived value of wax-based home decor and relaxation products. Smart candles appeal to consumers seeking customization, safety, and functionality. It reflects the convergence of technology and tradition in wax product development.
Rising Popularity of Wax-Based Food Coatings in Organic and Specialty Products:
Food coatings made from wax are gaining attention in the organic and premium produce market. Wax forms a protective barrier on fruits, vegetables, and confectionery items, extending shelf life without synthetic additives. Health-conscious consumers are driving demand for non-GMO and edible-grade wax coatings. Waxed cheese coatings, chocolate glazes, and fruit shine treatments exemplify this trend. Producers favor natural waxes for their safety and visual enhancement qualities. It supports clean-label packaging and food preservation strategies.
Market Challenges Analysis:
Volatile Raw Material Prices and Declining Petroleum Wax Supply Disrupt Production Economics:
The Global Wax Market faces pressure from fluctuating crude oil prices and declining paraffin wax availability. Refiners are shifting toward hydrocracking and alternative fuel configurations, which reduce wax yield. This trend tightens supply and raises costs for key end-use sectors such as packaging, candles, and rubber processing. Producers struggle to maintain consistent pricing and profit margins amid unstable input costs. The reliance on petroleum-derived feedstocks exposes the market to geopolitical tensions and trade disruptions. It must adjust procurement and manufacturing strategies to navigate this structural supply constraint.
Regulatory Compliance and Environmental Restrictions Create Complexity for Manufacturers:
Wax manufacturers must comply with a growing body of environmental and safety regulations across major markets. The Global Wax Market faces scrutiny over volatile organic compounds (VOCs), polycyclic aromatic hydrocarbons (PAHs), and fossil-based additives. These regulations are particularly stringent in the European Union and North America. Compliance requires reformulation, new certifications, and investment in cleaner technologies, which increase production costs and time-to-market. Smaller producers often face operational burdens in keeping up with evolving compliance demands. It must accelerate innovation and sustainability alignment to remain competitive in regulated regions.
Market Opportunities:
Rising Preference for Sustainable Products Creating Strong Demand for Bio-Based Waxes:
Growing environmental awareness and regulatory shifts are creating new opportunities for bio-based and renewable wax alternatives. Consumers and industries are actively seeking sustainable ingredients, pushing manufacturers to explore plant-derived waxes such as soy, carnauba, and sunflower. The Global Wax Market can leverage this shift by developing formulations that align with clean-label and non-toxic standards. Demand is increasing across cosmetics, food coatings, and pharmaceuticals for waxes that meet safety, biodegradability, and performance requirements. Investment in green chemistry and sustainable extraction processes enhances supply chain resilience. It can strengthen market position by offering eco-conscious solutions at competitive scale.
Expanding Infrastructure and Industrial Activities in Emerging Economies Stimulating Technical Wax Use:
Rapid urban development and industrialization in emerging regions present strong opportunities for technical wax applications. Markets in Asia, Latin America, and Africa are witnessing growing demand for construction materials, insulation, and packaging, all of which benefit from high-performance wax solutions. The Global Wax Market can expand by supplying Fischer-Tropsch and synthetic waxes tailored to regional needs. Government investment in infrastructure and logistics supports sustained consumption in coatings, adhesives, and concrete additives. Localized production and supply partnerships can reduce costs and enhance competitiveness. It can gain long-term advantage by aligning product offerings with large-scale industrial growth.
Market Segmentation Analysis:
By Type
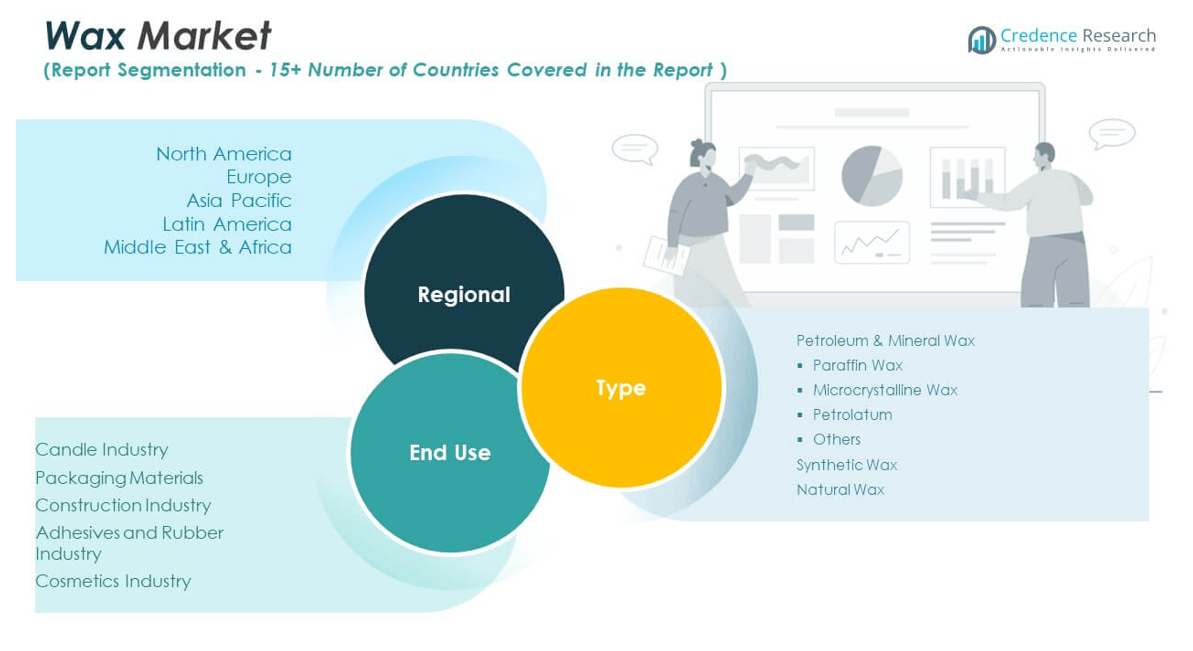
The Global Wax Market is segmented into Petroleum & Mineral Wax, Synthetic Wax, and Natural Wax. Petroleum & Mineral Wax holds the largest share, with Paraffin Wax widely used in candles, packaging, and industrial coatings due to its cost efficiency and availability. Microcrystalline Wax is preferred in cosmetics and pharmaceuticals for its elasticity and adhesive properties, while Petrolatum plays a key role in personal care formulations. The "Others" category, including slack and scale wax, supports industrial applications such as lubrication and rust prevention. Synthetic Wax is gaining momentum, particularly in high-performance adhesives, inks, and polishes, due to its purity and controlled composition. Natural Wax, including beeswax, carnauba, and soy-based waxes, is growing in demand across food, personal care, and candle segments driven by regulatory and environmental considerations.
- For instance, paraffin wax is extensively applied in the packaging sector to coat corrugated boxes, enhancing water resistance and box durability. Fully refined paraffin wax is used in waxed paper and corrugated box applications to provide a moisture-resistant and durable barrier for food packaging and perishables, directly impacting product shelf-life and safety in transit.
By End Use
The Candle Industry represents the largest end-use sector in the Global Wax Market, supported by strong consumer demand for home ambiance and ceremonial use. Packaging Materials form a key segment, with waxes improving moisture resistance, seal strength, and print adhesion. The Construction Industry utilizes wax in concrete curing, insulation, and surface protection to extend material performance. Adhesives and Rubber Industry use waxes for viscosity control, tack modification, and process stability. The Cosmetics Industry continues to expand wax usage in skincare, lip care, and decorative cosmetics where texture and structure are critical. It addresses diverse performance and compliance needs across these applications.
- For instance, Paraffin, microcrystalline, and plant-based waxes are utilized at scale in the candle industry, especially in Asia-Pacific and North America, to meet substantial demand for home, decorative, and ceremonial candles.
Segmentation:
BY TYPE SEGMENT
- Petroleum & Mineral Wax
- Paraffin Wax
- Microcrystalline Wax
- Petrolatum
- Others
- Synthetic Wax
- Natural Wax
BY END USE SEGMENT
- Candle Industry
- Packaging Materials
- Construction Industry
- Adhesives and Rubber Industry
- Cosmetics Industry
BY REGION
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Wax Market size was valued at USD 1,402.40 million in 2018 to USD 1,718.68 million in 2024 and is anticipated to reach USD 2,235.85 million by 2032, at a CAGR of 3.3% during the forecast period. The Global Wax Market in North America benefits from advanced manufacturing capabilities and consistent demand across packaging, cosmetics, and candle applications. The region leads in synthetic wax production due to shale-derived feedstock advantages. The U.S. drives consumption, particularly in industrial coatings and decorative candles. Regulatory focus on cleaner alternatives supports investment in bio-based waxes and GTL technologies. Demand for premium candles and wellness-related products is steady. It maintains a strong regional presence by balancing cost-effective petroleum wax with high-value specialty grades.
Europe
The Europe Wax Market size was valued at USD 2,048.28 million in 2018 to USD 2,571.58 million in 2024 and is anticipated to reach USD 3,464.36 million by 2032, at a CAGR of 3.8% during the forecast period. The Global Wax Market in Europe is shaped by strict environmental regulations and a high preference for sustainable products. Demand is concentrated in cosmetics, pharmaceuticals, and packaging industries, with strong activity in Germany, France, and the UK. Europe is transitioning from paraffin to plant-based waxes in response to regulatory pressures on fossil-based materials. Innovation in biodegradable and food-grade waxes drives product development. Producers focus on clean-label certifications and low-emission processes. It aligns closely with sustainability trends while serving mature consumer segments.
Asia Pacific
The Asia Pacific Wax Market size was valued at USD 2,591.75 million in 2018 to USD 3,413.52 million in 2024 and is anticipated to reach USD 4,900.74 million by 2032, at a CAGR of 4.6% during the forecast period. The Global Wax Market holds the largest share in Asia Pacific due to strong refining infrastructure and expanding consumer product manufacturing. China dominates regional demand across packaging, candle production, and personal care. India shows high growth potential in beeswax and natural waxes due to its agricultural base. The rise of e-commerce and cold-chain logistics fuels hot melt adhesive usage. Local producers focus on both commodity and specialty wax segments. It continues to expand with industrial output and growing middle-class consumption.
Latin America
The Latin America Wax Market size was valued at USD 747.55 million in 2018 to USD 1,028.22 million in 2024 and is anticipated to reach USD 1,554.97 million by 2032, at a CAGR of 5.3% during the forecast period. The Global Wax Market in Latin America is driven by growth in packaging, construction, and personal care sectors. Brazil and Mexico lead regional demand due to rising urbanization and increased industrial production. Imports meet much of the wax requirement, with a gradual push toward local value-added processing. Natural waxes gain popularity in cosmetics and food sectors. Regulatory adoption of sustainability standards is slower than in developed markets. It leverages untapped demand by aligning supply chains with local manufacturing needs.
Middle East
The Middle East Wax Market size was valued at USD 289.30 million in 2018 to USD 377.51 million in 2024 and is anticipated to reach USD 535.64 million by 2032, at a CAGR of 4.4% during the forecast period. The Global Wax Market in the Middle East is supported by industrial expansion and infrastructure development. Countries like Saudi Arabia and the UAE are investing in petrochemical complexes, supporting regional wax availability. Demand for construction-grade waxes used in concrete additives and insulation continues to grow. Candle consumption is also rising, influenced by tourism and hospitality. Producers benefit from cost advantages tied to energy and feedstock access. It targets industrial and building sectors for sustained growth.
Africa
The Africa Wax Market size was valued at USD 396.20 million in 2018 to USD 485.94 million in 2024 and is anticipated to reach USD 632.91 million by 2032, at a CAGR of 3.3% during the forecast period. The Global Wax Market in Africa remains at an early stage but shows steady progress in packaging, agriculture, and personal care. Demand for wax-coated packaging and candles is increasing with population growth and improving income levels. South Africa and Egypt are key demand centers, supported by retail and light manufacturing. Imports dominate the market, though there is growing interest in local production. Sustainability concerns are emerging, creating potential for natural wax applications. It presents long-term opportunity through strategic regional partnerships and technology transfer.
Key Player Analysis:
- BASF SE
- Bogdany Petrol Ltd.
- China National Petroleum Corporation
- Clariant
- Darent Wax Company Ltd
- Exxon Mobil Corporation
- Frank B. Ross Co., Inc.
- H&R Group
- HCI Wax
- Other Key Players
Competitive Analysis:
The Global Wax Market features a moderately consolidated competitive landscape with the presence of major multinational and regional players. Key companies focus on expanding product portfolios, investing in sustainable wax alternatives, and securing feedstock reliability to strengthen market position. Strategic partnerships, capacity expansions, and R&D in bio-based and synthetic waxes remain central to growth. Leading players such as BASF SE, ExxonMobil Corporation, and China National Petroleum Corporation maintain strong supply chains and global distribution networks. The market also includes niche producers catering to specialty applications in cosmetics, pharmaceuticals, and food. It experiences competition based on product quality, pricing, environmental compliance, and technical specifications. Innovation in plant-based waxes, Fischer-Tropsch waxes, and solvent-free processes is shaping the industry’s direction. It continues to evolve through technological integration, sustainability commitments, and diversified application development across regions.
Recent Developments:
- In April 2025, BASF SE unveiled new natural-based innovations for the personal care sector at in-cosmetics Global in Amsterdam. Among the launches were Lamesoft® OP Plus, a wax-based, readily biodegradable opacifier dispersion, and Verdessence® Maize, a natural styling polymer. These introductions are designed to support sustainable beauty product formulations and serve as biodegradable alternatives to traditional synthetic ingredients.
- In January 2025, Clariant expanded its partnership with TER Chemicals to broaden the distribution of its comprehensive lubricant and specialty product portfolio to Central and Eastern Europe. This strategic extension enhances Clariant's reach in providing innovative wax solutions and lubricant additives across multiple new geographic markets within the region.
- In 2025, Darent Wax Company Ltd remains an influential supplier and developer of over 1,500 specialized wax compounds, particularly emphasizing custom formulations for various industries including beauty, aerospace, and agriculture. While their latest product launches are not specified this year, the company is recognized for continuous product-driven and customer-focused innovations.
Market Concentration & Characteristics:
The Global Wax Market demonstrates moderate market concentration, with a mix of large integrated oil companies, chemical manufacturers, and specialized wax producers. It is characterized by steady demand across traditional and emerging applications, including candles, packaging, cosmetics, and industrial processes. The market relies heavily on petroleum-derived waxes, though synthetic and natural alternatives are gaining traction due to sustainability regulations. Supply dynamics are influenced by refinery configurations, feedstock availability, and regional production capacities. It shows strong vertical integration among leading players, ensuring control over raw material sourcing and distribution. The market favors product customization, consistent quality, and regulatory compliance, particularly in high-margin end uses. It balances commodity-scale production with growing demand for value-added specialty grades.
Report Coverage:
The research report offers an in-depth analysis based on type and end use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing demand for bio-based waxes will accelerate innovation in plant-derived and renewable formulations.
- Expanding e-commerce will boost consumption of wax-coated packaging and hot-melt adhesives.
- Increased use of waxes in cosmetics and personal care will drive demand for specialty and natural grades.
- Infrastructure growth in emerging economies will strengthen industrial wax applications in construction and coatings.
- Advancements in GTL and FT technologies will enhance synthetic wax production and quality.
- Regulatory shifts will push producers to invest in clean-label, food-safe, and low-emission wax alternatives.
- Candle market growth, driven by lifestyle and wellness trends, will support stable paraffin and soy wax demand.
- Integration of wax in food preservation and edible coatings will expand market reach in the food industry.
- Strategic partnerships and capacity expansion will improve global supply chain resilience.
- Digitalization and process automation will increase efficiency in wax production and quality control.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Packaging and E-commerce Industries
The rapid growth of e-commerce and the packaging sector is driving demand for wax coatings and hot-melt adhesives, which enhance water resistance, durability, and printability of packaging materials. This trend is reinforced by the shift toward sustainable and recyclable packaging solutions, increasing the relevance of both petroleum and bio-based waxes.
Cosmetics and Personal Care Sector Growth
Rising consumer preference for clean-label, vegan, and natural cosmetics is boosting demand for specialty and natural waxes such as beeswax and carnauba. Waxes are essential for providing structure, gloss, and emollient properties in a wide range of personal care products.
Growth in Candle Manufacturing
Lifestyle trends, wellness movements, and cultural practices are sustaining high-volume demand for scented and decorative candles, especially in North America and Europe. Manufacturers are also investing in paraffin alternatives like soy and palm wax to meet sustainability and health priorities.
Industrial and Construction Applications
Infrastructure development and industrialization, particularly in Asia and the Middle East, are increasing the use of technical waxes such as Fischer-Tropsch and synthetic grades in coatings, adhesives, concrete curing, and insulation. These applications benefit from waxes' superior hardness, thermal resistance, and lubrication properties.
Transition Toward Bio-Based and Renewable Waxes
Environmental regulations and consumer demand for sustainable products are accelerating the adoption of plant-based and biodegradable waxes across food, packaging, and cosmetics industries. This shift is driving innovation in extraction processes and expanding the market for renewable wax alternatives.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Wax Market?
What factors are driving the growth of the Global Wax Market?
What are some challenges faced by the Global Wax Market?
Who are the major players in the Global Wax Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Petroleum & Mineral Wax
- 1.2.2 Synthetic Wax
- 1.2.3 Natural Wax
- 1.3 By End Use
- 1.3.1 Candle Industry
- 1.3.2 Packaging Materials
- 1.3.3 Construction Industry
- 1.3.4 Adhesives and Rubber Industry
- 1.3.5 Cosmetics Industry
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 9,595.46 million → 2032: USD 13,324.48 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wax Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wax Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Wax Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Wax Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wax Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wax Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wax Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wax Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 9,595.46 million → 2032: USD 13,324.48 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wax Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Petroleum & Mineral Wax
- 12.3.7.2 Synthetic Wax
- 12.3.7.3 Natural Wax
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Candle Industry
- 12.4.7.2 Packaging Materials
- 12.4.7.3 Construction Industry
- 12.4.7.4 Adhesives and Rubber Industry
- 12.4.7.5 Cosmetics Industry
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wax End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Wax Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Wax Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Wax Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Exxon Mobil Corporation
- 18.4 China National Petroleum Corporation
- 18.5 Clariant
- 18.6 Darent Wax Company Ltd
- 18.7 H&R Group
- 18.8 Bogdany Petrol Ltd.
- 18.9 Frank B. Ross Co., Inc.
- 18.10 HCI Wax
- 18.11 Shell
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

