
Market Overview
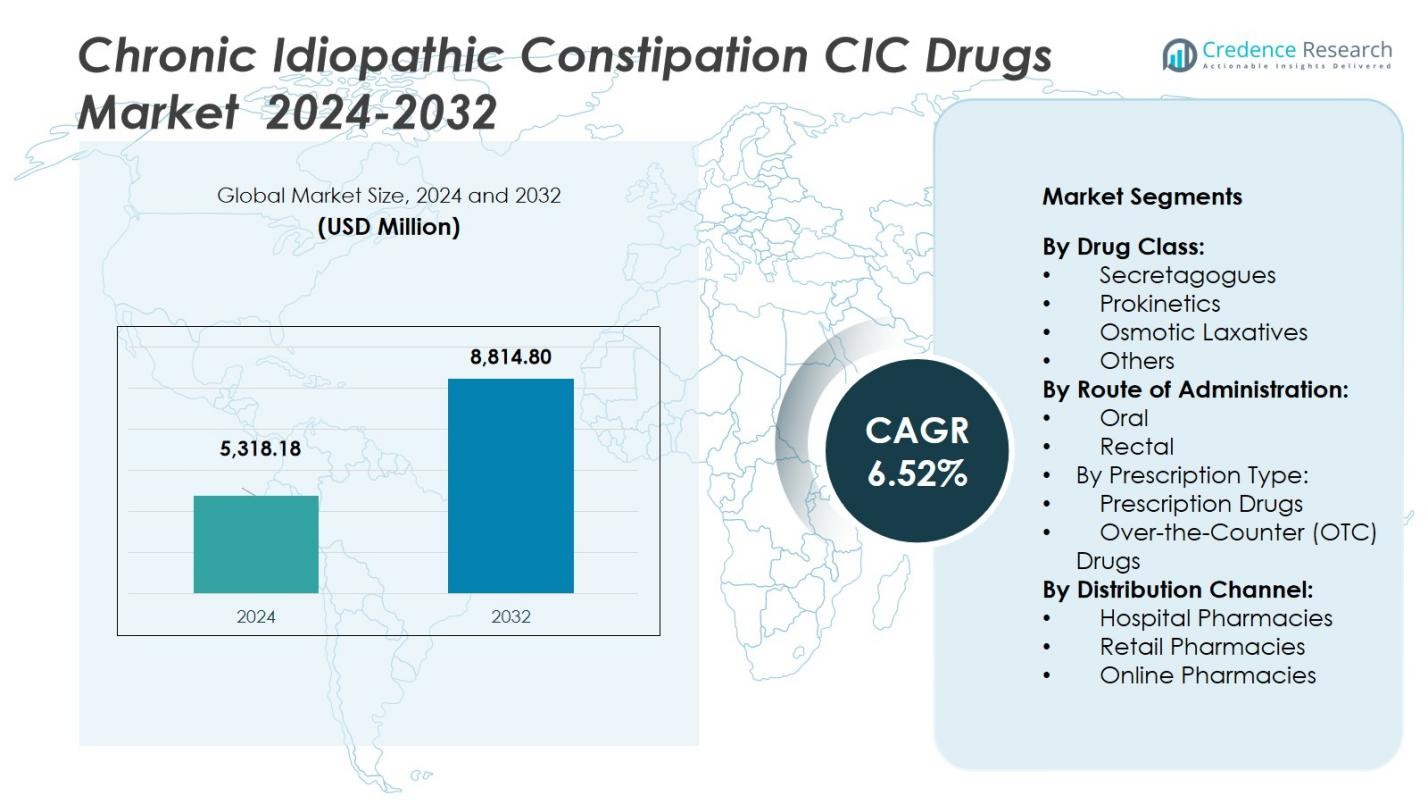
The Chronic Idiopathic Constipation (CIC) Drugs Market size was valued at USD 5,318.18 million in 2024 and is anticipated to reach USD 8,814.80 million by 2032, growing at a CAGR of 6.52% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Chronic Idiopathic Constipation (CIC) Drugs Market Size 2024 | USD 5,318.18 Million |
| Chronic Idiopathic Constipation (CIC) Drugs Market, CAGR | 6.52% |
| Chronic Idiopathic Constipation (CIC) Drugs Market Size 2032 | USD 8,814.80 Million |
The Chronic Idiopathic Constipation (CIC) Drugs Market is led by prominent companies such as Actavis Generics, Chugai Pharmaceutical Co., Ltd., Ferring International Center, S.A., Synergy Pharmaceuticals, Pfizer Inc., GlaxoSmithKline plc, F. Hoffmann-La Roche AG, Sanofi S.A., Bayer AG, and Salix Pharmaceuticals, Inc. These key players are driving the market through continuous innovation in drug formulations, strategic collaborations, and geographic expansion. North America dominates the market with a 41% share, driven by a high prevalence of CIC, strong healthcare infrastructure, and significant adoption of prescription treatments. Europe follows with a 28% share, while Asia Pacific holds a 21% share, benefiting from growing healthcare access and rising awareness of CIC treatments. Latin America and the Middle East & Africa represent smaller shares, contributing to incremental growth as healthcare systems improve in these regions.
Market Insights
- The market for Chronic Idiopathic Constipation (CIC) drugs was valued at USD 5,318.18 million in 2024 and is projected to reach USD 8,814.80 million by 2032 with a CAGR of 6.52% during the forecast period.
- Rising incidence of CIC driven by ageing populations, sedentary lifestyles and dietary habits continues to expand the addressable patient base and drives demand for effective therapies.
- A growing shift toward novel mechanisms (such as secretagogues capturing 46% share in the drug‑class segment) and oral administration (84% route share) underscores strong innovation and patient convenience trends.
- Firms face restraint from high costs of prescription drugs and under‑diagnosis in emerging regions, which limits uptake and broad market access.
- Regionally, North America commands a 41% share, Europe holds 28%, Asia Pacific accounts for 21%, Latin America about 6% and Middle East & Africa around 4%, with mature markets dominating and developing regions offering expansion potential.
Market Segmentation Analysis:
By Drug Class
In the drug‑class segmentation of the Chronic Idiopathic Constipation (CIC) drugs market, the Secretagogues sub‑segment holds the dominant share at 46 %. These agents (e.g., chloride‑channel activators and guanylate cyclase‑C agonists) lead due to their demonstrated efficacy in boosting intestinal fluid secretion and improving bowel movement frequency. Key growth drivers include rising diagnosis rates of CIC, increased physician adoption of novel mechanisms for refractory patients, and strong reimbursement support for specialty therapies. Prokinetics, osmotic laxatives and other classes support the broader market but trail behind secretagogues in share.
- For instance, Plecanatide, initially developed by Synergy Pharmaceuticals and marketed under the brand name Trulance, demonstrated durable responder rates of around 20% in its pivotal chronic idiopathic constipation (CIC) trials, which was significantly higher than the placebo rate of approximately 10-13%.
By Route of Administration
Within the route‑of‑administration segmentation, the Oral sub‑segment commands a leading share of 84 %, reflecting its prevalence in the CIC drugs market. Oral formulations deliver convenience, patient adherence and suitability for chronic management, making them the preferred mode of administration. Factors driving this dominance include broader availability of oral dosage forms, minimal invasiveness compared to rectal options, and strong pipeline activity in oral secretagogue and prokinetic agents. Rectal formulations remain niche, often reserved for acute relief or specific patient cohorts unable to tolerate oral administration.
- For instance, the drug Lubiprostone (approved in capsule form) is indicated for chronic idiopathic constipation and must be taken orally at 24 µg twice daily with food and water.
By Prescription Type
In the segmentation by prescription type, Prescription Drugs represent the overwhelmingly dominant sub‐segment, accounting for 70% of the market share. Prescription treatments are favored owing to their higher efficacy, more rigorous regulatory approval, and use in moderate to severe CIC cases. The growth drivers here include increasing unmet medical needs among patients unresponsive to over‐the‐counter (OTC) laxatives, greater physician awareness of prescription treatment opportunities, and expanding indications across adult and geriatric populations. OTC drugs continue to grow as self‐medication trends rise, but they remain secondary to prescription therapies in the global CIC drugs market, holding around 30% of the market share.
Key Growth Drivers
Rising Prevalence of Chronic Idiopathic Constipation
The increasing prevalence of Chronic Idiopathic Constipation (CIC) is a major growth driver in the CIC drugs market. Factors such as aging populations, lifestyle changes, and dietary habits contribute to the higher incidence of CIC. As healthcare providers improve diagnostic capabilities, more patients are being identified and treated. The rise in prevalence, especially among older adults, expands the addressable market for CIC drugs, prompting greater demand for effective treatments. Increased patient awareness and better access to healthcare are accelerating market growth.
- For instance, the National Institute of Diabetes and Digestive and Kidney Diseases (NIDDK) reports that about 16% of the U.S. adult population experiences chronic constipation, with the prevalence rising significantly in individuals aged 60 and older.
Advancements in Drug Formulations
Continuous innovation in drug formulations is propelling the CIC drugs market. Newer treatments, such as secretagogues and prokinetics, offer improved efficacy and fewer side effects compared to traditional treatments. These advancements are making medications more effective for patients, particularly those with refractory cases of CIC who previously had limited treatment options. The development of oral formulations that are easier to administer and better tolerated by patients is further boosting market growth. As pharmaceutical companies invest in R&D, the pipeline of innovative CIC drugs remains robust.
- For instance, Lubiprostone (Amitiza), a treatment for CIC, was found to significantly improve bowel movement frequency and alleviate abdominal discomfort, offering a better alternative to stimulant laxatives.
Increasing Adoption of Prescription Treatments
The growing adoption of prescription drugs is significantly contributing to the expansion of the CIC drugs market. Prescription medications are preferred by healthcare providers for managing moderate to severe cases of CIC due to their higher efficacy and targeted action. The shift from over-the-counter (OTC) to prescription drugs is a key trend driven by the increasing recognition of CIC as a chronic condition requiring specialized care. Prescription medications not only offer better symptom control but also address the underlying causes of CIC, which enhances patient quality of life and adherence.
Key Trends & Opportunities
Shift Towards Personalized Medicine
A notable trend in the CIC drugs market is the shift towards personalized medicine. Healthcare providers are increasingly tailoring treatments based on individual patient needs, genetics, and response to previous therapies. This trend allows for more effective treatment regimens and better outcomes for patients suffering from CIC. Companies that develop targeted therapies and diagnostic tools to identify the most suitable treatments are poised to capitalize on this opportunity. Personalized medicine could significantly enhance the precision and efficacy of CIC drugs, offering new avenues for market expansion.
- For instance, imatinib, developed for chronic myeloid leukemia, targets the BCR-ABL fusion gene present in over 95% of cases, exemplifying precision therapy that inhibits the cancer-driving protein effectively.
Growing Market for Over-the-Counter (OTC) Solutions
The demand for Over-the-Counter (OTC) drugs in the CIC market presents a significant opportunity. As patients increasingly seek self-care options for managing milder forms of CIC, OTC products such as osmotic laxatives are gaining traction. The convenience and accessibility of OTC solutions are key factors contributing to their popularity, particularly in regions with high healthcare accessibility. With expanding consumer awareness about CIC and its management, OTC solutions are expected to see increased market penetration, providing a growth opportunity for both existing and new players in the CIC drugs market.
- For instance, the brand MiraLAX (polyethylene glycol 3350) is positioned as the “#1 doctor‑recommended OTC laxative” in the U.S. and is formulated as a 17 g powder dose for daily use.
Key Challenges
High Cost of Prescription Drugs
One of the major challenges in the CIC drugs market is the high cost associated with prescription medications. Despite the effectiveness of newer treatments, the price point remains a barrier for many patients, particularly in low-income regions or among those without comprehensive insurance coverage. The cost of treatment can limit access to vital drugs, thereby hindering broader adoption. As a result, healthcare systems may need to address pricing strategies, reimbursement policies, and support programs to ensure that all patients can benefit from available therapies.
Lack of Awareness and Diagnosis in Emerging Markets
In emerging markets, the lack of awareness and underdiagnosis of Chronic Idiopathic Constipation (CIC) presents a significant challenge. Many patients in these regions are either unaware of their condition or delay seeking treatment, resulting in an underreporting of CIC cases. This gap in diagnosis limits the market potential for CIC drugs, as many individuals remain untreated or self-medicate without professional guidance. Overcoming this challenge requires increased awareness campaigns, education for both healthcare providers and patients, and improved healthcare infrastructure in emerging regions to facilitate earlier diagnosis and treatment.
Regional Analysis
North America
The North America region holds a 41% share of the global Chronic Idiopathic Constipation (CIC) Drugs market, driven by a high prevalence of CIC and strong adoption of prescription therapies. Healthcare systems in the U.S. and Canada emphasise chronic gastrointestinal treatment, with advanced diagnostics and specialist gastroenterology services fostering greater uptake of novel secretagogue and prokinetic drugs. Robust reimbursement frameworks and presence of major pharmaceutical players further reinforce regional leadership. Given the established market infrastructure, North America is expected to maintain its dominance through 2032.
Europe
Europe holds a 28% share in the global CIC Drugs market, supported by established public‑health systems and clinical guidelines for gastrointestinal disorders. Countries such as Germany, the United Kingdom, France and Italy are leading in terms of prescriptions for moderate to severe CIC cases. Inflation of geriatric populations, rising awareness of functional bowel disorders and increasing physician prescribing of advanced agents contribute to growth. While access varies regionally, the overall infrastructure and regulatory environment position Europe as a strong secondary region in the CIC Drugs market.
Asia Pacific
The Asia Pacific region accounts for a 21% share of the global CIC Drugs market. Market growth is propelled by rising healthcare expenditures, expanding access to prescription therapies and increasing awareness of CIC among adult and elderly populations in China, India, Japan and Southeast Asia. A growing middle‑class population, improving gastroenterology infrastructure and wider rollout of advanced formulations are key drivers. Although per‑capita spending remains lower than Western markets, rapid growth potential positions Asia Pacific as a significant expansion zone through the forecast period.
Latin America
Latin America represents a 6% share of the global CIC Drugs market, reflecting emerging adoption of prescription therapies and improving access to specialist care. Brazil and Mexico remain key markets as healthcare penetration improves and awareness of CIC grows. However, market growth is moderated by reimbursement challenges, lower treatment penetration and reliance on over‑the‑counter laxatives for milder symptoms. Through enhanced physician education, expanded distribution networks and generics entry, Latin America offers incremental growth potential for CIC drug manufacturers.
Middle East & Africa
The Middle East & Africa region holds a 4% share in the global CIC Drugs market. Regional growth stems from increasing investments in specialty clinics, expanding healthcare infrastructure in Gulf Cooperation Council (GCC) countries and rising awareness of chronic gastrointestinal conditions. However, limited diagnostic capacity, variable reimbursement frameworks and access disparities in rural areas constrain uptake. As telemedicine expands and pharmaceutical distribution strengthens, the region’s share is expected to rise, albeit from a small base relative to mature markets.
Market Segmentations:
By Drug Class:
- Secretagogues
- Prokinetics
- Osmotic Laxatives
- Others
By Route of Administration:
- Oral
- Rectal
By Prescription Type:
- Prescription Drugs
- Over-the-Counter (OTC) Drugs
By Distribution Channel:
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape or analysis of the Chronic Idiopathic Constipation (CIC) Drugs Market reveals a moderately concentrated yet evolving field, with major key players including Actavis Generics, Chugai Pharmaceutical Co., Ltd., Ferring International Center, S.A., Synergy Pharmaceuticals, Pfizer Inc., GlaxoSmithKline plc, F. Hoffmann‑La Roche AG, Sanofi S.A., Bayer AG and Salix Pharmaceuticals, Inc.. These leaders compete across innovation, therapeutic coverage, geographic reach and distribution strength. They deploy diversified strategies including product pipeline investments in secretagogue and prokinetic therapies, strategic alliances or acquisitions to bolster existing portfolios, and geographic expansion into emerging markets. Additionally, generics players and OTC alternatives steadily exert pressure on pricing and market access, compelling legacy manufacturers to differentiate through novel mechanisms of action, patient‑support programs and lifecycle management. Competition also accelerates in regions such as Asia‑Pacific and Latin America where localized regulatory and reimbursement trends affect market dynamics.
Key Player Analysis
- The Chugai Pharmaceutical Co., Ltd (Japan)
- Bayer AG (Germany)
- Salix Pharmaceuticals, Inc. (US)
- F. Hoffmann‑La Roche AG (Switzerland)
- GlaxoSmithKline plc (UK)
- Actavis Generics (US)
- Pfizer Inc. (US)
- Ferring International Center, S.A. (Switzerland)
- Sanofi S.A. (France)
- Synergy Pharmaceuticals (US)
Recent Developments
- In August 2025, Dr. Reddy’s Laboratories launched Linaclotide under the brand name “Colozo®” in India, indicated for adult CIC – marking its entry in the Indian market.
- In July 2025, Camber Pharmaceuticals launched Prucalopride Tablets (1 mg & 2 mg) in the U.S. under its portfolio for adult CIC treatment.
- In June 2025, Lupin Limited received U.S. FDA approval for its generic version of Prucalopride Tablets (1 mg & 2 mg) indicated for the treatment of CIC in adults.
Report Coverage
The research report offers an in-depth analysis based on Drug Class, Roue of Administration, Proscription Type, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Growth in geriatric populations will expand the patient pool for CIC drugs as age‑related gastrointestinal motility issues become more prevalent.
- Rising adoption of novel mechanism therapies such as GC‑C agonists and 5‑HT₄ receptor agonists will drive demand for more effective CIC treatment options.
- Expansion into emerging markets with improving healthcare access and growing awareness of CIC will open new revenue streams for key players.
- Increased reimbursement support and favourable regulatory approvals for prescription CIC therapies will improve market penetration and patient uptake.
- Growth in digital health tools and remote monitoring will support earlier diagnosis and treatment adherence in CIC management.
- Shift toward orally administered therapies will satisfy patient preference, boost compliance, and reinforce market growth for CIC drugs.
- Greater collaboration between pharmaceutical companies and gastroenterology specialists will accelerate clinical trial pipelines and new treatment launches for CIC.
- Increased competition from generics and biosimilars will pressure branded CIC drugs to differentiate via patient‑support services and value‑based pricing.
- Broader adoption of OTC treatments in milder CIC cases will complement prescription drug growth, expanding overall market size and segment diversity.
- Growing emphasis on personalized medicine and biomarker‑driven therapy selection will enhance treatment outcomes and foster niche‑segment development within the CIC drugs market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Chronic Idiopathic Constipation CIC Drugs Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Chronic Idiopathic Constipation CIC Drugs Market projected to grow between 2025 and 2032?
Which Chronic Idiopathic Constipation CIC Drugs Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Chronic Idiopathic Constipation CIC Drugs Market?
Who are the leading companies in the Chronic Idiopathic Constipation CIC Drugs Market?
Which region commanded the largest share of the Chronic Idiopathic Constipation CIC Drugs Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Chronic Idiopathic Constipation (CIC) Drugs Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Chronic Idiopathic Constipation (CIC) Drugs Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,318.18 million → 2032: USD 8,814.80 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Chronic Idiopathic Constipation (CIC) Drugs Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Chronic Idiopathic Constipation (CIC) Drugs Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Chronic Idiopathic Constipation (CIC) Drugs Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Chronic Idiopathic Constipation (CIC) Drugs Market Drivers
- 3.3 Chronic Idiopathic Constipation (CIC) Drugs Market Restraints & Challenges
- 3.4 Chronic Idiopathic Constipation (CIC) Drugs Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Chronic Idiopathic Constipation (CIC) Drugs Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Chronic Idiopathic Constipation (CIC) Drugs Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Chronic Idiopathic Constipation (CIC) Drugs category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Chronic Idiopathic Constipation (CIC) Drugs Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Chronic Idiopathic Constipation (CIC) Drugs Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Chronic Idiopathic Constipation (CIC) Drugs market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Chronic Idiopathic Constipation (CIC) Drugs Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Chronic Idiopathic Constipation (CIC) Drugs Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Chronic Idiopathic Constipation (CIC) Drugs Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Chronic Idiopathic Constipation (CIC) Drugs (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Chronic Idiopathic Constipation (CIC) Drugs Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Chronic Idiopathic Constipation (CIC) Drugs Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Chronic Idiopathic Constipation (CIC) Drugs Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Chronic Idiopathic Constipation (CIC) Drugs Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Chronic Idiopathic Constipation (CIC) Drugs Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Chronic Idiopathic Constipation (CIC) Drugs Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Chronic Idiopathic Constipation (CIC) Drugs Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Chronic Idiopathic Constipation (CIC) Drugs Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Chronic Idiopathic Constipation (CIC) Drugs Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
