
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Marine Actuators and Valves Market Size 2024 | USD 3,113 million |
| Marine Actuators and Valves Market, CAGR | 5.6% |
| Marine Actuators and Valves Market Size 2032 | USD 5083.4 million |
Market Overview:
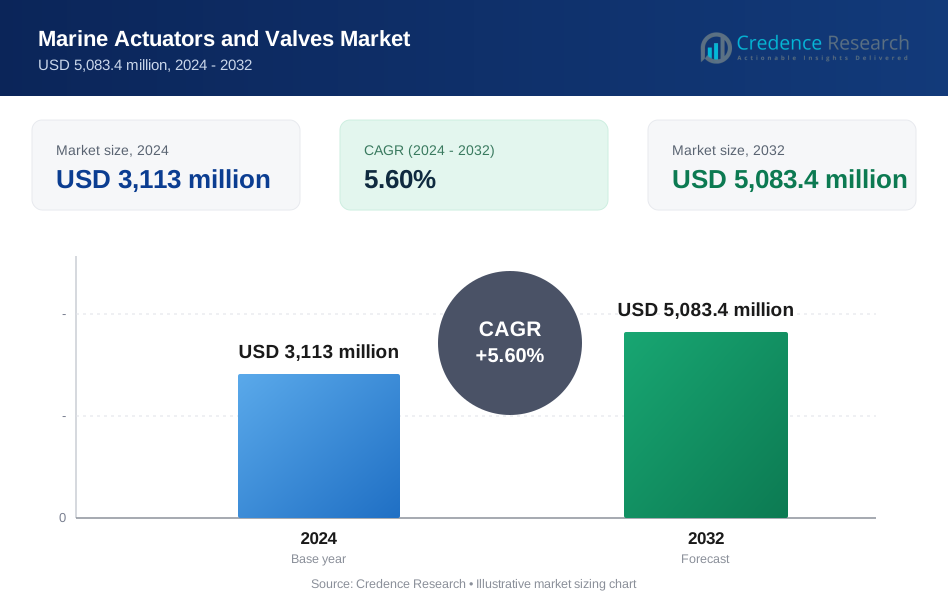
Marine Actuators and Valves Market size was valued at USD 3,113 million in 2024 and is anticipated to reach USD 5083.4 million by 2032, at a CAGR of 5.6% during the forecast period (2024-2032).
Several factors propel market expansion. Rising global maritime commerce drives demand for efficient fluid control systems that optimize propulsion, ballast regulation, and cargo handling. Offshore energy exploration projects intensify the need for robust hydraulic and electric solutions capable of enduring harsh marine environments. Defense modernization programs allocate substantial budgets to upgrade naval fleets with high-pressure valve systems certified for reliability and safety. At the same time, tightening environmental and safety regulations incentivize the adoption of smart, leak-resistant valve technologies that minimize emissions and operational risks. The industry also embraces digitalization trends-such as IoT-enabled remote monitoring and predictive maintenance-which enhance uptime and reduce lifecycle costs across maritime assets. Manufacturers are expanding aftermarket service offerings to include modular actuator designs that simplify field repairs and minimize vessel downtime. Advances in materials science and protective coatings further improve actuator and valve longevity under corrosive saltwater conditions.
The Asia Pacific region leads global revenue share, propelled by expanding shipbuilding capacities and offshore energy initiatives in key markets. North America follows, underpinned by advanced shipyards, rigorous safety frameworks, and rapid adoption of automated control systems across commercial and defense vessels. Europe maintains a strong presence, supported by fleet renewal programs, stringent environmental mandates, and significant investments in intelligent valve technologies for cruise liners and cargo ships. Emerging markets in Latin America, the Middle East, and Africa are also gaining traction as governments invest in port infrastructure and offshore operations, opening new growth avenues through the forecast period. Strategic collaborations between regional shipbuilders and global equipment suppliers foster technology transfer and localize supply chains to meet specific operational requirements. Shifting trade routes and emerging shipping corridors are driving demand for tailored actuator and valve configurations across diverse marine environments.
Market Insights:
- Marine Actuators and Valves Market size reached USD 3,113 million in 2024 and will climb to USD 5,083.4 million by 2032 at a 5.6% CAGR.
- Global maritime commerce drives demand for efficient fluid control systems that optimize propulsion, ballast regulation, and cargo handling.
- Offshore energy exploration intensifies need for robust hydraulic and electric solutions capable of enduring extreme marine environments.
- Defense modernization programs allocate substantial budgets to procure high-pressure valve systems certified for reliability and safety.
- Tightening environmental and safety regulations incentivize adoption of smart, leak-resistant valve technologies that minimize emissions and operational risks.
- IoT-enabled remote monitoring and predictive maintenance enhance uptime and reduce lifecycle costs across maritime assets.
- Manufacturers expand aftermarket service offerings with modular actuator designs and leverage advances in materials science to improve longevity under corrosive saltwater conditions.
Market Drivers:
Surge in Global Maritime Commerce Stimulates Equipment Demand
The Marine Actuators and Valves Market benefits from higher shipments across major sea routes. It supports vessel propulsion, ballast control, and cargo handling systems with precise fluid regulation. Higher container volumes compel ship operators to upgrade actuation modules. Naval and commercial fleets specify valves that ensure consistent performance under pressure. It integrates seamlessly with onboard automation platforms. Equipment suppliers report higher orders from shipyards and retrofit providers.
Expansion of Offshore Energy Ventures Drives Demand for Robust Systems
The Marine Actuators and Valves Market secures contracts from offshore drilling platforms. It equips subsea production trees and riser control units with high-torque actuators. Deepwater exploration imposes strict reliability standards for valves. Operators require equipment that resists corrosion and withstands extreme pressure. It uses advanced sealing technologies to extend maintenance cycles. Field teams favor modular designs that simplify component replacement.
- For instance, Hunt Valve Company was awarded purchase orders totaling $96 million to supply valves for the construction of 12 Virginia-class and five Columbia-class submarines, demonstrating the demand for robust valve systems in challenging marine environments.
Defense Fleet Upgrades Mandate High-Performance Valve Solutions
The Marine Actuators and Valves Market wins defense awards for next generation vessels. It provides fail-safe valve units for critical ballast and weapon control systems. Military standards require certification for shock, vibration, and temperature extremes. It passes rigorous qualification tests before final integration. Naval architects specify actuators with redundant control channels. It boosts mission readiness by reducing operational failures.
- For instance, Fairbanks Morse Defense’s Hunt Valve was selected to deliver essential ship service ball valves and forged high-pressure system valves for 12 new Virginia-class and five Columbia-class submarines under a $96 million contract with the U.S. Navy.
Regulatory Mandates and Digital Solutions Enhance System Reliability
The Marine Actuators and Valves Market adapts to environmental mandates on emissions control. It supplies valves designed to prevent hydraulic fluid leaks and reduce contamination risk. Class societies require equipment that satisfies fresh water flushing standards. It integrates sensors that feed real-time performance feedback into management systems. Operators leverage remote diagnostics to schedule maintenance interventions. It lowers total cost of ownership through predictive alert mechanisms.
Market Trends:
Integration of Digital Technologies Enhances Predictive Maintenance and Operational Efficiency
Marine Actuators and Valves Market leverages IoT-enabled sensors to deliver real-time performance metrics. It supports remote monitoring platforms that notify engineers about deviation in valve pressure or actuator torque. OEMs develop cloud-based dashboards that consolidate diagnostic data across fleets of marine vessels. Service providers employ advanced machine-learning algorithms to predict component failure before downtime occurs. Shipbuilding firms integrate digital twins for scenario analysis and lifecycle planning. Suppliers optimize supply chains by verifying spare part provenance and authenticity. End-users report a measurable drop in unplanned outages and maintenance expenditures.
- For instance, Blackhall Engineering’s Valvemetrix® system provides 24/7 real-time monitoring and immediate alerts for condition changes, enabling proactive maintenance and preventing costly breakdowns for water companies and dam operators.
Shift Toward Environmentally Sustainable Materials and Leak-Prevention Systems Balances Regulatory Demands
Within the Marine Actuators and Valves Market, regulatory bodies impose stricter standards for underwater emissions and spill prevention to protect marine ecosystems. Manufacturers replace traditional rubber seals with fluoropolymer alternatives that resist corrosion and produce negligible microplastics. It drives investment in electric actuators that eliminate hydraulic fluid leaks and reduce maintenance hazards. Class societies introduce certification pathways for explosion-proof valve assemblies and green vessels. R&D teams partner with composite suppliers to develop lightweight components that lower fuel consumption. Operators adopt fail-safe valve designs that self-seal upon power loss and minimize environmental risk. Industry stakeholders publish case studies that highlight compliant retrofit solutions and accelerate market adoption.
- For instance, IMI Critical Engineering’s Retrofit3D solution delivered a custom 6-inch valve trim to an offshore oil & gas facility within 12 weeks, enabling the reuse of the existing valve body and actuator while solving operational issues without full valve replacement.
Market Challenges Analysis:
Volatility in Raw Material Costs Undermines Pricing Stability
Marine Actuators and Valves Market faces pressure from variable prices for steel alloys and specialty polymers. It forces OEMs to adjust contract terms frequently to preserve margins. Supply chain disruptions elevate shipping costs and extend lead times. Tier-1 suppliers encounter difficulty securing long-term agreements at fixed prices. End-users demand more transparent procurement processes to limit budget overruns. Manufacturers adopt cost-control measures and explore alternative sourcing strategies. Many stakeholders cite unpredictable input costs as a top barrier to consistent profitability.
Complex Certification Requirements Delay Product Launch Cycles
Marine Actuators and Valves Market must navigate stringent marine safety standards enforced by multiple class societies worldwide. Manufacturers complete exhaustive testing protocols and submit extensive documentation. Certification bodies update rules frequently to incorporate new safety and environmental mandates. Engineering teams allocate significant resources to meet compliance deadlines. Delayed approvals prolong time to revenue and raise development budgets. Customers demand clarity on qualification status prior to purchase commitments. Protracted validation stages hamper innovation and stretch project timelines.
- For instance, Bosch Rexroth’s Subsea Valve Actuator was certified by DNV GL for application in safety systems with requirements up to Safety Integrity Level 3, and is designed for maintenance-free operation for 25 years.
Market Opportunities:
Expansion of Autonomous Vessel Fleet Drives Demand for Intelligent Control Solutions
Marine Actuators and Valves Market can capture new revenue streams through integration of smart control modules aboard autonomous ships. It aligns with shipyards that invest in remote navigation systems and require robust valve automation. OEMs collaborate with navigation platform providers to embed predictive diagnostics hardware. Compliance with cybersecurity standards offers scope to differentiate product lines. Manufacturers partner with software firms for firmware upgrade pathways. Operators seek vendor support for system interoperability and lifecycle management. Research institutes join forces with industry to develop next-generation actuator designs.
Development of Hybrid Propulsion Systems Opens Opportunities in Green Retrofits
Marine Actuators and Valves Market finds growth prospects in retrofit projects for vessels that adopt electric and fuel-cell propulsion. It suits fleet owners that target emission limits set by international bodies. Suppliers offer modular valve assemblies compatible with hydrogen bunkering infrastructure. Retrofit specialists recommend actuator kits that reduce hydraulic leak risk and maintenance downtime. Collaboration with engine builders yields custom valve solutions compliant with new vessel classification rules. Financial incentives for clean-maritime projects increase retrofit volume. Stakeholders secure early-mover advantage through certified retrofit offerings.
Market Segmentation Analysis:
By Application
Marine Actuators and Valves Market divides into propulsion control, ballast regulation, cargo handling and safety shutdown systems. It delivers precise torque and pressure management across these applications. Propulsion control actuators receive the largest demand due to emphasis on fuel efficiency. Ballast regulation valves gain traction from stricter stability requirements. Cargo handling systems require robust electric actuation for container terminals. Safety shutdown actuators undergo rigorous certification to comply with maritime safety standards. Providers tailor products to each function to enhance operational reliability.
- For instance, Habonim’s CompAct spring return actuator is specifically designed for LNG emergency shutdown systems, featuring a unique four-piston design that enables shutdown speeds up to 10 times faster than standard actuators in high-torque applications.
By End-User
Marine Actuators and Valves Market segments include commercial shipping, offshore energy, defense and port operations. It supplies container carriers, bulk carriers and LNG vessels in the commercial sector. Offshore energy producers require subsea actuators for drilling platforms and FPSOs. Defense navies specify shock-resistant valves and redundant control modules. Port operators adopt electric actuators for dockside cranes and lock systems. Vendor support agreements cover maintenance and training for end-users in each category. OEMs issue product updates to meet operational requirements in every sector.
- For instance, Emerson Electric launched the Fisher easy-Drive 200R Electric Actuator in January 2024, designed for use with butterfly and ball valves, offering accurate process control and remote diagnostics for marine applications.
Segmentations:
By Application
- Propulsion Control
- Ballast Regulation
- Cargo Handling
- Safety Shutdown Systems
By End-User
- Commercial Shipping
- Offshore Energy
- Defense Navies
- Port Operations
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America Focuses on Naval Modernization and High-Performance Retrofit Demand
North America holds 29% of the global Marine Actuators and Valves Market revenue. It benefits from strong government spending on naval fleet modernization and offshore energy infrastructure. OEMs maintain long-term agreements with defense contractors and shipyards to supply high-performance actuators and corrosion-resistant valves. Electric valve technologies are gaining traction across U.S. commercial ports due to their safety and reliability advantages. Canada supports green retrofitting initiatives through public-private partnerships. Service providers operate regional hubs to ensure rapid part availability and reduce vessel downtime. Marine operators in both countries emphasize lifecycle cost efficiency and remote monitoring capabilities.
Europe Leverages Policy-Driven Demand for Sustainable Marine Systems
Europe contributes 26% to the Marine Actuators and Valves Market. It prioritizes emissions compliance and lifecycle efficiency through integration of smart and electric actuators. Shipowners invest in environmentally certified retrofits to align with EU maritime directives and decarbonization targets. Manufacturers based in Germany, the Netherlands, and Scandinavia lead in the production of compact, high-efficiency valve systems. Offshore wind expansion across the North Sea drives demand for subsea valve actuators with real-time monitoring features. Regional classification bodies support fast-tracked certification for green propulsion technologies. European R&D clusters continue to pioneer hybrid systems for future-ready fleets.
Asia Pacific Leads Global Growth through Large-Scale Shipbuilding and Digital Integration
Asia Pacific commands 45% of the global Marine Actuators and Valves Market revenue. It leads global shipbuilding through large-scale commercial and LNG vessel production. Governments across the region support advanced automation and fuel-efficient technologies in newbuilds. China integrates IoT-based actuators in smart ports to improve control system reliability and asset tracking. South Korean shipbuilders partner with technology providers to standardize predictive maintenance platforms. Vietnam and India emerge as key production centers for cost-effective actuator components. Local demand remains high for scalable, digital-ready valve solutions across commercial, defense, and offshore sectors.
Key Player Analysis:
- Rotork Plc
- Flowserve Corporation
- IMI plc
- AVK Group
- Tyco International Ltd.
- Cameron International Corporation
- Honeywell International, Inc.
- Emerson Electric Co.
- Bürkert Fluid Control Systems
- Alfa Laval AB
- Watts Water Technologies
- KITZ Corporation
Competitive Analysis:
Leading suppliers such as Emerson Electric, Flowserve, Curtiss-Wright and Parker Hannifin compete on technology leadership, service coverage and regulatory certification. Marine Actuators and Valves Market features consolidation through mergers and targeted alliances that broaden product portfolios and global footprint. It compels manufacturers to innovate hydraulic and electric actuator designs and enhance aftermarket services. Service network depth and rapid response capabilities differentiate players in high-demand regions. Regulatory compliance expertise shapes procurement decisions, and firms invest in local testing centers to expedite approvals. Price competitiveness drives tier-2 suppliers to specialize in modular valve assemblies for niche applications. Digital platform providers partner with OEMs to integrate remote diagnostics and predictive maintenance tools. Smaller vendors retain market share through tailored solutions for specific vessel classes and operational profiles. Competitive pressure encourages continuous R&D investment and strategic expansion into new maritime corridors.
Recent Developments:
- In February 2025, Emerson announced a strategic partnership with Zitara to integrate advanced battery management solutions into Emerson’s Ovation automation platform, enhancing energy storage management for utility customers.
- In May 2025, Emerson launched AspenTech v15, featuring expanded industrial AI capabilities, generative AI for facility layouts, and new sustainability features to accelerate decarbonization and resource efficiency.
- In March 2025, Rotork announced the acquisition of Noah Actuation, a South Korean electric actuator manufacturer, for £44 million.
Market Concentration & Characteristics:
Marine Actuators and Valves Market displays a moderate concentration where leading global and regional suppliers command a significant portion of industry revenue. It features a competitive landscape in which major original equipment manufacturers leverage technical expertise and extensive service coverage to secure large-scale contracts. High certification costs and capital requirements create substantial barriers for new entrants. Smaller firms gain traction in specialized segments through tailored solutions and swift field support. It demands robust global service networks and local testing facilities to uphold compliance and performance standards. Production centers cluster in Asia Pacific, Europe and North America. Strategic alliances and mergers drive incremental product enhancements and expand geographic reach.
Report Coverage:
The research report offers an in-depth analysis based on Application, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Industry players invest in AI-driven diagnostics to enable predictive maintenance and minimize unplanned downtimes.
- Suppliers collaborate with shipyards to develop modular actuator platforms that simplify installation and customization.
- Regulatory mandates will push adoption of leak-resistant valve systems designed for zero-emission vessel corridors.
- Integration with vessel automation suites will accelerate through standardized communication protocols and cybersecurity frameworks.
- Material innovations such as composite alloys will extend component life and reduce corrosion in harsh marine environments.
- Retrofit programs will drive demand for electric actuators in aging fleets seeking energy-efficient solutions.
- Collaboration between OEMs and software firms will yield cloud-based service models that enhance remote performance monitoring.
- Regional supply chains will diversify to reduce dependency on single-source suppliers and improve resilience.
- Training initiatives will expand to equip maintenance teams with skills for advanced smart actuator technologies.
- Strategic partnerships between technology vendors and classification societies will streamline certification pathways and shorten delivery cycles.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size and forecast of the Marine Actuators and Valves Market?
What factors drive market expansion?
How does digitalization affect the market?
What role do aftermarket services play?
Who are the major players in this market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Marine Actuators and Valves Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Marine Actuators and Valves Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,113 million → 2032: USD 5,083.4 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Marine Actuators and Valves Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Marine Actuators and Valves Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Marine Actuators and Valves Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Marine Actuators and Valves Market Drivers
- 3.3 Marine Actuators and Valves Market Restraints & Challenges
- 3.4 Marine Actuators and Valves Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Marine Actuators and Valves Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Marine Actuators and Valves Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Marine Actuators and Valves category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Marine Actuators and Valves Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Marine Actuators and Valves Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Marine Actuators and Valves market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Marine Actuators and Valves Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Marine Actuators and Valves Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Marine Actuators and Valves Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Marine Actuators and Valves (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Marine Actuators and Valves Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Marine Actuators and Valves Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Marine Actuators and Valves Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Marine Actuators and Valves Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Marine Actuators and Valves Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Marine Actuators and Valves Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Marine Actuators and Valves Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Marine Actuators and Valves Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Marine Actuators and Valves Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
