
Market Overview
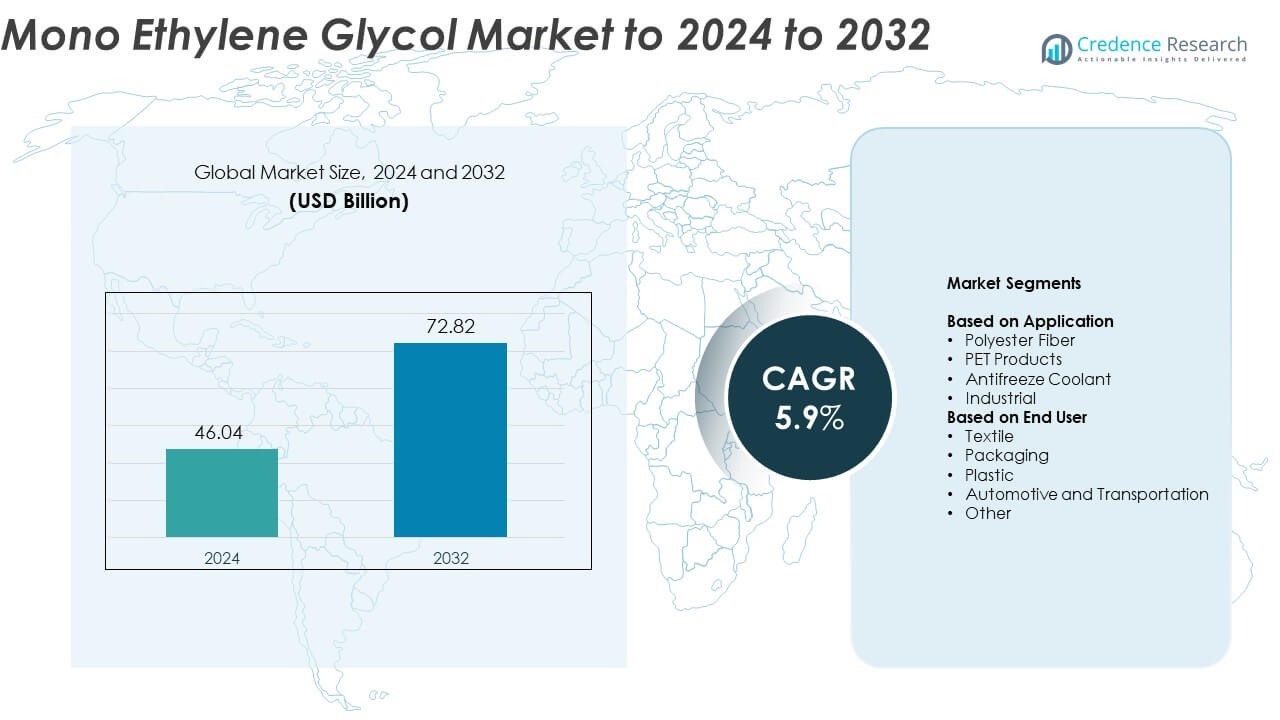
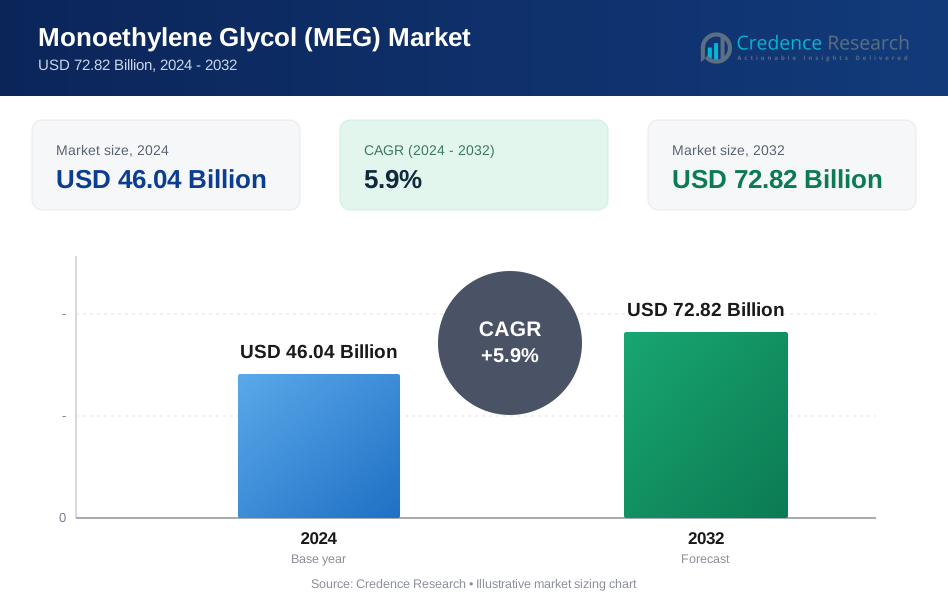
Mono Ethylene Glycol market size was valued at USD 46.04 Billion in 2024 and is anticipated to reach USD 72.82 Billion by 2032, at a CAGR of 5.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Monoethylene Glycol (MEG) Market Size 2024 | USD 46.04 Billion |
| Monoethylene Glycol (MEG) Market, CAGR | 5.9% |
| Monoethylene Glycol (MEG) Market Size 2032 | USD 72.82 Billion |
The mono ethylene glycol market is led by major players such as Exxon Mobil Corporation, Dow, Royal Dutch Shell PLC, Mitsubishi Chemical Corporation, China Petroleum & Chemical Corporation, LyondellBasell Industries Holdings BV, NAN YA PLASTICS CORPORATION, Petro Rabigh, ME, India Glycols Limited, and UPM. These companies dominate through integrated petrochemical operations, technological innovation, and global supply networks. Asia-Pacific remains the leading region, accounting for about 41.6% share in 2024, driven by its strong textile, packaging, and automotive sectors. North America follows with around 27.8% share, supported by advanced chemical production infrastructure and sustained PET demand.
Market Insights
- The mono ethylene glycol market was valued at USD 46.04 Billion in 2024 and is projected to reach USD 72.82 Billion by 2032, growing at a CAGR of 5.9%. • Increasing demand for polyester fiber in textiles and PET packaging applications remains the key growth driver, supported by industrial expansion in emerging economies. • The market is witnessing trends toward bio-based MEG production and advanced catalytic technologies aimed at improving efficiency and sustainability. • Competitive dynamics are shaped by global producers focusing on capacity expansion, vertical integration, and adoption of greener manufacturing processes. • Asia-Pacific dominates with 41.6% market share, followed by North America at 27.8% and Europe at 22.5%, while the polyester fiber segment holds the largest share at 53.7%, driven by growing demand from the textile industry.
Market Segmentation Analysis:
By Application
The polyester fiber segment dominates the mono ethylene glycol market, accounting for around 53.7% share in 2024. Its leadership is driven by the extensive use of MEG as a key raw material in polyester fiber manufacturing, which is widely applied in textiles, apparel, and home furnishings. The strong growth of the apparel industry and increasing demand for synthetic fibers across Asia-Pacific further strengthen this segment. Rising consumption of polyester fiber in industrial and technical textiles, coupled with expanding production capacities in China and India, continues to propel the demand for mono ethylene glycol.
- For instance, Reliance Industries has polyester fiber and yarn capacity of 2.5 million tons per year
By End User
The textile segment leads the mono ethylene glycol market with approximately 39.2% share in 2024. This dominance is fueled by the extensive application of MEG in producing polyester-based yarns and fabrics used across clothing, upholstery, and industrial materials. The surge in fast fashion trends, coupled with growing exports of synthetic textiles from emerging economies, drives significant consumption. Increasing investments in textile manufacturing and the shift toward durable, cost-effective polyester blends further reinforce the segment’s growth trajectory in the global mono ethylene glycol market.
- For instance, Hengli reports polymerization capacity of 6 million tons and fabric output over 4 billion meters annually.
Key Growth Drivers
Rising Demand for Polyester-Based Textiles
The growing global demand for polyester fibers in clothing, home furnishings, and industrial fabrics is a primary driver for the mono ethylene glycol market. MEG serves as a crucial feedstock in polyester fiber and PET resin production, making it indispensable to the textile industry. Rapid urbanization, expanding middle-class populations, and increasing fashion consumption in emerging economies such as China and India are amplifying this demand. The shift toward cost-effective synthetic fibers over natural materials continues to sustain long-term growth.
- For instance, Toray Advanced Materials Korea Inc. increased its annual production capacity for TORELINA™ polyphenylene sulfide (PPS) resin by 5,000 metric tons at its Gunsan plant, with operations starting from November 2024 (slightly ahead of the originally planned December 2024 completion date).
Expansion of PET Packaging Applications
The widespread use of PET products across food, beverage, and personal care packaging sectors significantly boosts MEG consumption. Growing awareness of lightweight and recyclable packaging materials enhances the adoption of PET bottles and containers. With rising global beverage consumption and the expansion of e-commerce, PET demand is increasing steadily. Technological advancements in PET recycling and sustainable packaging solutions further reinforce the long-term potential for MEG in the packaging industry.
- For instance, Indorama recycled over 26 billion PET bottles in 2024, contributing to a total of more than 150 billion bottles recycled from 2011 to August 2025.
Industrial and Automotive Growth
Expanding automotive and industrial activities worldwide have accelerated the demand for MEG-based antifreeze coolants and lubricants. MEG’s excellent thermal properties and ability to prevent freezing make it vital for engine performance and equipment maintenance. Increasing vehicle ownership and infrastructure development in developing countries support higher MEG usage. Additionally, industrial applications, including resins, solvents, and chemical intermediates, contribute to consistent market expansion across various sectors.
Key Trends & Opportunities
Shift Toward Bio-Based Mono Ethylene Glycol
The growing emphasis on sustainability and carbon footprint reduction is driving investment in bio-based MEG production. Companies are adopting renewable feedstocks such as bioethanol or sugarcane to produce eco-friendly alternatives to conventional petrochemical-derived MEG. This shift aligns with global environmental goals and consumer preference for green materials. As regulatory pressure intensifies on fossil-based products, bio-MEG offers significant opportunities for innovation and competitive differentiation.
- For instance, Avantium’s plant-based MEG demo unit in Delfzijl has about 10 tons per-year capacity.
Technological Advancements in Production Processes
Continuous improvement in MEG production efficiency through catalytic oxidation and advanced separation techniques is shaping market dynamics. New process designs reduce energy consumption, minimize by-products, and enhance yield quality. Integrated manufacturing setups combining MEG with other glycols or PET operations offer cost optimization and sustainability benefits. Such technological advancements strengthen supply reliability and support manufacturers in maintaining competitiveness under fluctuating raw material costs.
- For instance, Shell's OMEGA process technology is used in several plants and enables operators to produce up to 1.95 tons of mono-ethylene glycol (MEG) per ton of ethylene consumed, which is more efficient than conventional processes that produce between 1.53 and 1.70 tons of MEG per ton of ethylene.
Key Challenges
Volatility in Crude Oil Prices
Fluctuations in crude oil and ethylene prices directly impact MEG production costs, creating market uncertainty. As MEG is derived from ethylene obtained from petroleum feedstocks, any shift in oil markets influences its profit margins. Geopolitical tensions, supply disruptions, and changing refinery output levels add to the volatility. These cost fluctuations challenge producers to maintain stable pricing structures and secure long-term supply contracts with end users.
Environmental and Regulatory Pressures
The mono ethylene glycol industry faces growing environmental scrutiny due to its petrochemical origin and potential ecological risks during production and disposal. Stricter emission norms and sustainability mandates compel manufacturers to adopt greener technologies and cleaner production methods. Compliance with environmental regulations increases capital expenditure and operational complexity. The transition toward sustainable manufacturing practices remains challenging, particularly for smaller producers with limited technological resources.
Regional Analysis
North America
North America holds around 27.8% share of the mono ethylene glycol market in 2024, driven by strong demand from the packaging, automotive, and textile sectors. The United States leads the region due to its extensive PET production and established chemical manufacturing infrastructure. Growth in sustainable packaging and expanding use of antifreeze coolants in the automotive industry further support market expansion. Rising investments in bio-based MEG production and recycling facilities enhance regional competitiveness. The presence of major producers and advanced refining capabilities ensures a stable supply chain across key industrial applications.
Europe
Europe accounts for nearly 22.5% share of the mono ethylene glycol market in 2024, supported by rising demand for PET-based packaging and polyester fibers. The region benefits from strict environmental regulations that encourage sustainable MEG production and recycling initiatives. Countries such as Germany, France, and the United Kingdom are leading adopters of energy-efficient and low-emission manufacturing technologies. The growing electric vehicle industry increases the use of MEG-based coolants, while the textile and industrial sectors remain key consumers. Circular economy initiatives are fostering innovation in bio-derived MEG alternatives across Europe.
Asia-Pacific
Asia-Pacific dominates the mono ethylene glycol market, accounting for about 41.6% share in 2024. China and India are major production and consumption hubs due to their vast textile, packaging, and automotive industries. Rapid urbanization, industrial expansion, and the growing preference for polyester fibers drive substantial demand across the region. Expanding PET bottle manufacturing and increasing investments in sustainable production facilities strengthen Asia-Pacific’s leadership. Government initiatives supporting industrial growth and large-scale chemical capacity expansions continue to position the region as a global MEG production powerhouse.
Latin America
Latin America captures around 4.6% share of the global mono ethylene glycol market in 2024. Brazil and Mexico serve as major growth centers due to rising demand for PET packaging and automotive coolants. Increasing industrialization and urban population are fueling consumption in the textile and packaging sectors. Expanding regional trade and supportive government policies encourage foreign investments in chemical manufacturing. Although the market remains smaller than Asia-Pacific and North America, infrastructure development and emerging bio-MEG projects offer long-term growth potential for Latin American producers.
Middle East & Africa
The Middle East & Africa region holds approximately 3.5% share of the mono ethylene glycol market in 2024, driven by abundant petrochemical feedstock availability. Saudi Arabia, Qatar, and the United Arab Emirates are major producers, leveraging large-scale ethylene and glycol plants to serve global markets. The region’s strategic exports to Asia and Europe enhance its market position. Growing infrastructure and automotive development in African nations are also contributing to steady consumption growth. Continued investments in refining and downstream integration strengthen the region’s competitive edge in MEG production.
Market Segmentations:
By Application
- Polyester Fiber
- PET Products
- Antifreeze Coolant
- Industrial
By End User
- Textile
- Packaging
- Plastic
- Automotive and Transportation
- Other
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The mono ethylene glycol market features prominent players such as Exxon Mobil Corporation (US), Dow (US), Royal Dutch Shell PLC, Mitsubishi Chemical Corporation, China Petroleum & Chemical Corporation, LyondellBasell Industries Holdings BV, NAN YA PLASTICS CORPORATION, Petro Rabigh (Saudi Arabia), ME (UAE), India Glycols Limited (India), and UPM. The competitive landscape is characterized by integrated production capacities, strategic joint ventures, and continuous process optimization to enhance cost efficiency. Companies are increasingly investing in sustainable manufacturing technologies and exploring bio-based MEG production to meet tightening environmental regulations. Expansion of PET and polyester fiber industries across Asia-Pacific drives capacity additions and long-term supply contracts. Market participants focus on technological advancements, improved feedstock utilization, and global supply chain optimization to maintain competitiveness. Strategic partnerships with packaging and textile manufacturers, along with innovations in recycling and green chemistry, continue to shape market positioning and strengthen sustainability-driven growth across key regions.
Key Player Analysis
- Exxon Mobil Corporation (US)
- Dow (US)
- Royal Dutch Shell PLC
- Mitsubishi Chemical Corporation
- China Petroleum & Chemical Corporation
- LyondellBasell Industries Holdings BV
- NAN YA PLASTICS CORPORATION
- Petro Rabigh (Saudi Arabia)
- ME (UAE)
- India Glycols Limited (India)
- UPM
Recent Developments
- In 2025, Shell Chemicals expanded its Monoethylene Glycol (MEG) production capacity in Asia to meet rising demand from industrialization and the growth of products like PET for packaging.
- In 2025, LyondellBasell commissioned a new MEG production line in Texas, USA. This facility expansion aims to enhance domestic supply for polyester and antifreeze applications, targeting growing demand from the textile and automotive sectors.
- In 2025, UPM continued to develop and introduce bio-based MEG materials from sustainable sources.
Report Coverage
The research report offers an in-depth analysis based on Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Rising demand for polyester fibers will continue to drive MEG consumption globally.
- Growing adoption of PET packaging in food and beverage industries will sustain market expansion.
- Increasing investments in bio-based MEG production will enhance sustainability and reduce dependency on fossil feedstocks.
- Rapid industrialization and automotive growth in Asia-Pacific will strengthen regional dominance.
- Technological advancements in catalytic and energy-efficient processes will improve production efficiency.
- Expanding textile manufacturing in emerging economies will create new opportunities for MEG suppliers.
- Strong focus on recycling and circular economy models will influence market strategies.
- Integration of MEG production with refinery and petrochemical complexes will improve cost competitiveness.
- Environmental and regulatory compliance will drive innovation in greener manufacturing practices.
- Strategic mergers and capacity expansions among global producers will shape long-term market dynamics.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Mono Ethylene Glycol Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Mono Ethylene Glycol Market projected to grow between 2025 and 2032?
Which Mono Ethylene Glycol Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Mono Ethylene Glycol Market?
Who are the leading companies in the Mono Ethylene Glycol Market?
Which region commanded the largest share of the Mono Ethylene Glycol Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Monoethylene Glycol (MEG) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Monoethylene Glycol (MEG) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 46.04 Billion → 2032: USD 72.82 Billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Monoethylene Glycol (MEG) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Monoethylene Glycol (MEG) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Monoethylene Glycol (MEG) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Monoethylene Glycol (MEG) Market Drivers
- 3.3 Monoethylene Glycol (MEG) Market Restraints & Challenges
- 3.4 Monoethylene Glycol (MEG) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Monoethylene Glycol (MEG) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Monoethylene Glycol (MEG) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Monoethylene Glycol (MEG) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Monoethylene Glycol (MEG) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Monoethylene Glycol (MEG) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Monoethylene Glycol (MEG) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Monoethylene Glycol (MEG) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Monoethylene Glycol (MEG) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Monoethylene Glycol (MEG) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Monoethylene Glycol (MEG) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Monoethylene Glycol (MEG) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Monoethylene Glycol (MEG) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Monoethylene Glycol (MEG) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Monoethylene Glycol (MEG) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Monoethylene Glycol (MEG) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Monoethylene Glycol (MEG) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Monoethylene Glycol (MEG) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Monoethylene Glycol (MEG) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Monoethylene Glycol (MEG) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
