
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| 3D Bioprinting Market Size 2023 | USD 1,500.00 Million |
| 3D Bioprinting Market, CAGR | 12.4% |
| 3D Bioprinting Market Size 2032 | USD 4,295.25 Million |
Market Overview:
Global 3D Bioprinting Market size was valued at USD 1,500.00 million in 2023 and is anticipated to reach USD 4,295.25 million by 2032, at a CAGR of 12.4% during the forecast period (2023-2032).
The growth of the global 3D bioprinting market is fueled by several key drivers. One of the primary factors is the increasing demand for alternative solutions to address the global organ transplant shortage. 3D bioprinting offers the potential to create functional tissues and organs, which could help bridge the gap between the supply and demand for donor organs. Technological advancements also play a crucial role, as improvements in bioprinting technologies, including the development of advanced bioinks, enhanced printing precision, and faster processing speeds, expand the capabilities of 3D bioprinting for clinical applications. Additionally, significant investments in research and development by both public and private sectors are accelerating innovation in this field, driving further advancements in bioprinting applications. The growing focus on regenerative medicine, is also increasing the adoption of 3D bioprinting technologies.
The 3D bioprinting market exhibits significant regional variation in growth and adoption. North America leads the global market, driven by a well-established healthcare infrastructure, substantial research and development investments, and a strong presence of key market players. The United States, in particular, is at the forefront of 3D bioprinting innovation and application, contributing significantly to the market’s dominance. The Asia-Pacific region, however, is experiencing the fastest growth, with countries like China, Japan, and India making considerable strides in 3D bioprinting. This is largely due to the region’s large patient base, increased healthcare investments, and lower operational costs, making it an attractive location for clinical trials and research. Europe, while not as dominant as North America, is steadily expanding in the bioprinting sector, with countries such as Germany and the UK leading the way in adopting these technologies for medical purposes. In contrast, regions like Latin America and the Middle East & Africa are still in the early stages of adoption.
Market Insights:
- The global 3D bioprinting market was valued at USD 1,500.00 million in 2023 and is projected to reach USD 4,295.25 million by 2032, growing at a CAGR of 12.4% during the forecast period (2023-2032).
- The increasing demand for alternative solutions to address the global organ transplant shortage is a major driver, as 3D bioprinting can create functional tissues and organs to bridge the gap between supply and demand.
- Technological advancements, including improved bioinks, enhanced printing precision, and faster processing speeds, are expanding the capabilities of 3D bioprinting for more complex and functional tissues.
- The growing focus on regenerative medicine and personalized healthcare is boosting the adoption of 3D bioprinting, as it allows the creation of patient-specific tissues for more effective treatments.
- Increased investments in research and development from both public and private sectors are accelerating technological innovations and making 3D bioprinting more accessible and affordable.
- High costs associated with bioprinting technology, including expensive equipment and bioinks, present a significant barrier to widespread adoption, particularly in developing countries or smaller healthcare facilities.
- The lack of clear regulatory guidelines and the technical limitations in replicating complex organs for transplantation are key challenges, slowing the commercialization and broader adoption of bioprinting technologies.
Market Drivers:
Increasing Demand for Organ Transplants
One of the primary drivers for the growth of the global 3D bioprinting market is the growing demand for organ transplants. The global shortage of available donor organs has led to significant challenges in meeting the transplantation needs of patients. Traditional organ transplant procedures often face long waiting lists, and many patients do not survive while waiting for a suitable donor organ. 3D bioprinting offers a promising solution by enabling the creation of functional tissues and even organs that can potentially be used for transplantation. The ability to print complex tissues with the patient’s own cells reduces the risk of rejection, thus offering an innovative solution to address the transplant gap. This demand for alternatives in organ transplantation is expected to significantly boost the adoption of 3D bioprinting technologies in the healthcare sector.
Technological Advancements in Bioprinting
Advancements in bioprinting technology are another critical factor driving the market. In recent years, bioprinting has seen substantial improvements in printing precision, the development of bioinks, and the speed at which printing can occur. These technological breakthroughs are enabling the production of more complex and functional tissues, paving the way for applications in regenerative medicine. For instance, Organovo Holdings has pioneered the use of 3D bioprinted human liver tissue for therapeutic research and drug profiling, and is collaborating with healthcare providers to advance clinical applications of bioprinted tissue implants. The continuous improvement in the quality of bioprinted tissues allows for better scalability in clinical settings, where the demand for personalized treatments is growing. With the integration of automation, artificial intelligence, and better material formulations, 3D bioprinting is advancing at a pace that allows it to address a wide range of medical applications, from creating skin tissues for burn victims to printing cartilage for joint repair. The technological strides in this field are driving its rapid adoption across various sectors.
Regenerative Medicine and Personalized Healthcare
The increasing focus on regenerative medicine and personalized healthcare is another significant driver for the 3D bioprinting market. Regenerative medicine aims to restore or replace damaged tissues and organs using a patient’s own cells, and bioprinting provides a viable method for creating customized, functional tissues tailored to individual needs. For instance, TeVido Biodevices uses 3D printing for reconstructive surgeries in breast cancer survivors, applying patients’ own melanocytes to reduce rejection risk and offering customized solutions for skin regeneration and wound healing. As patients and healthcare providers seek more effective and personalized treatment options, 3D bioprinting technologies are becoming an essential part of the healthcare ecosystem. The ability to create patient-specific tissues can improve recovery outcomes and reduce the likelihood of rejection in transplantation procedures. Additionally, personalized medicine is gaining momentum, with patients expecting tailored solutions for their medical conditions. The rise of personalized healthcare and regenerative treatments is significantly driving the demand for 3D bioprinting in clinical practices.
Research and Development Investments
Research and development (R&D) investments are another key factor propelling the global 3D bioprinting market. Both public and private sectors are increasingly funding R&D activities aimed at improving bioprinting capabilities and exploring new applications for this technology. These investments are not only helping to accelerate technological advancements but also making 3D bioprinting more accessible and affordable for healthcare providers. Institutions and companies worldwide are working on enhancing the functionality of bioprinted tissues and developing new bioinks, printing techniques, and post-processing methods to meet the growing demands of the healthcare sector. The increase in R&D spending is accelerating the adoption of 3D bioprinting across various industries, from pharmaceutical research to clinical treatments. The ongoing investments are expected to lead to breakthroughs that will further expand the potential applications of bioprinting, thereby driving market growth in the years to come.
Market Trends:
Rising Adoption in Drug Development and Testing
A key trend in the global 3D bioprinting market is the increasing adoption of bioprinting technologies in drug development and testing. Traditional methods of drug testing involve animal models or cell cultures, but these techniques have limitations in mimicking the complexity of human tissues. 3D bioprinting, however, allows researchers to create more accurate tissue models that better simulate human organs. This capability is particularly valuable in the pharmaceutical industry, where the demand for more reliable and cost-effective testing solutions is growing. Bioprinted tissues are being used to evaluate the efficacy and safety of new drug candidates, potentially reducing the need for animal testing and enabling faster, more accurate results in the drug development process. This trend is expected to drive further innovation in the use of bioprinting for personalized medicine and targeted treatments.
Integration of Artificial Intelligence and Machine Learning
Another prominent trend shaping the 3D bioprinting market is the integration of artificial intelligence (AI) and machine learning (ML) technologies. For example, the National University of Singapore (NUS) has developed a workflow that combines 3D bioprinting with AI to fabricate personalized gingival (gum) tissue grafts. These technologies are being utilized to optimize the bioprinting process, enabling more precise and efficient production of complex tissues and organs. AI algorithms are being employed to analyze large datasets, improve printing accuracy, and predict the outcomes of bioprinted tissue functionality. Machine learning models help identify patterns in tissue growth and healing, offering deeper insights into bioprinted tissues' performance in clinical applications. By combining AI and ML with 3D bioprinting, researchers can enhance the quality and scalability of bioprinted products, accelerating their integration into real-world medical applications and clinical trials.
Focus on Customization and Patient-Specific Solutions
Customization and patient-specific solutions are gaining significant attention in the 3D bioprinting market. The ability to create personalized medical treatments that are tailored to an individual’s genetic makeup, disease progression, or physical condition is a key factor driving the demand for bioprinting. Companies are increasingly focusing on bioprinting tissues and organs that match the unique characteristics of each patient. This trend is evident in applications such as 3D-printed prosthetics, implants, and tissue scaffolds. As the technology improves, the potential for creating highly specialized, patient-specific medical solutions will continue to expand, offering more effective treatment options and reducing complications associated with traditional one-size-fits-all approaches in healthcare.
Expansion of Bioprinting Applications Beyond Healthcare
While the healthcare sector remains the primary focus of the 3D bioprinting market, there is growing interest in applying bioprinting technologies to other industries. The food industry, for example, is exploring the use of bioprinting for creating lab-grown meat and other sustainable food products. The ability to print tissues and even entire meals using plant-based or cultured cells is being hailed as a potential solution to global food security challenges. Similarly, the fashion industry is investigating the use of bioprinting for creating eco-friendly, sustainable clothing items using biologically sourced materials. For instance, companies like Bolt Threads and Modern Meadow are also engineering sustainable materials such as Microsilk™ and biofabricated leather, offering eco-friendly alternatives to traditional textiles. This broadening of bioprinting applications beyond healthcare demonstrates the versatility of the technology and its potential to impact multiple industries, paving the way for new innovations and market opportunities in the coming years.
Market Challenges Analysis:
High Costs of Technology
One of the major restraints in the global 3D bioprinting market is the high initial cost associated with the technology. Bioprinting machines and related equipment are expensive, and their installation and maintenance costs can be prohibitive for smaller organizations and research institutions. Additionally, the bioinks required for 3D bioprinting are often costly, further increasing the financial burden on businesses and researchers looking to adopt this technology. For instance, UPM Biomedicals offers GrowInk™, a hydrogel-based bioink, which is promoted for its customizability but still represents a significant cost for repeated or large-scale use. The high costs associated with bioprinting limit its widespread adoption, particularly in developing countries or smaller healthcare facilities with limited budgets. This financial barrier hinders the ability of many organizations to fully explore the potential of 3D bioprinting technologies.
Regulatory Challenges
The regulatory landscape surrounding 3D bioprinting remains underdeveloped, posing a significant challenge for the market. As 3D bioprinting technologies are increasingly used in healthcare applications such as organ printing, regulatory bodies are faced with the task of ensuring the safety, efficacy, and ethical considerations surrounding the use of bioprinted tissues and organs. The lack of established regulations and clear guidelines for approval processes creates uncertainty for manufacturers, which can delay the commercialization and widespread adoption of bioprinting technologies. Additionally, regulatory complexities may vary by region, further complicating the approval process for companies seeking to enter new markets.
Technical Limitations in Bioprinted Tissue Complexity
Despite significant advancements in 3D bioprinting, the complexity of bioprinted tissues and organs remains a challenge. Current bioprinting technologies are still limited in their ability to accurately replicate the full functionality and complexity of human organs. While 3D bioprinting has shown success in printing simple tissues, creating highly functional, vascularized, and fully operational organs is still a work in progress. These technical limitations hinder the development of viable bioprinted organs for transplantation, slowing the overall progress of the market. Overcoming these challenges requires continued research and innovation, which may take years to achieve.
Market Opportunities:
The global 3D bioprinting market presents numerous growth opportunities, particularly in the healthcare sector. As the demand for personalized medicine and patient-specific treatments continues to rise, 3D bioprinting offers the potential to revolutionize the way medical treatments are designed and delivered. The ability to print tissues and organs tailored to individual patients' needs could significantly improve the success rates of treatments, reduce the risk of organ rejection, and enhance overall patient outcomes. Additionally, the increasing focus on regenerative medicine further amplifies the market opportunity, with bioprinting enabling the creation of complex tissues that can be used to repair or replace damaged organs. These advancements are opening new avenues for market players to explore, especially as the technology evolves to meet clinical demands for functional and personalized solutions.
Another key opportunity lies in the pharmaceutical industry, where 3D bioprinting is transforming drug testing and development. By creating more accurate models of human tissues, bioprinting is helping pharmaceutical companies conduct more reliable preclinical trials, potentially reducing the need for animal testing and speeding up drug approval processes. This could lead to more efficient drug development cycles, lower costs, and improved drug efficacy. Moreover, as bioprinting technology continues to improve, its applications are likely to expand into other industries such as food production, fashion, and environmental sustainability. These developments position 3D bioprinting as a versatile technology with significant growth potential across multiple sectors, offering ample opportunities for innovation and market expansion.
Market Segmentation Analysis:
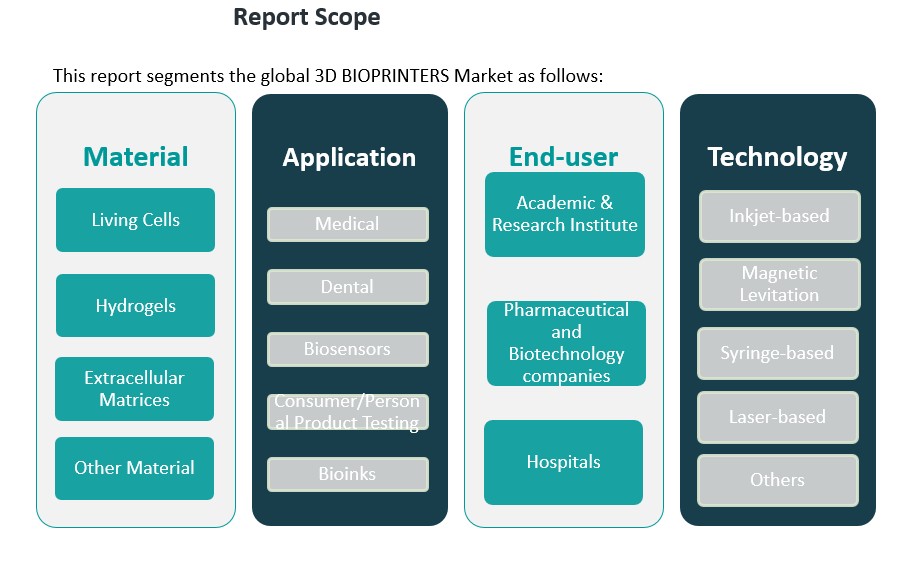
The global 3D bioprinting market is segmented into various categories, each contributing uniquely to its growth and application in healthcare and research.
By Material, the market is primarily driven by the demand for functional and biocompatible substances. Living cells are the most commonly used material, crucial for tissue engineering and organ printing. Hydrogels are gaining traction for their ability to mimic the natural extracellular matrix, providing an ideal environment for cell growth. Extracellular matrices are also important for creating complex tissues, while other materials, such as synthetic polymers, are used in specific applications like medical devices and implants.
By Application, the medical sector dominates, as bioprinting is increasingly used for developing tissues and organs for transplantation, as well as drug testing and development. The dental segment is expanding, with bioprinting applications in prosthetics and tissue regeneration. Biosensors are emerging as a key application area, where bioprinted tissues can be used for real-time disease monitoring. Consumer/personal product testing is also growing, where 3D bioprinted models simulate human skin for cosmetic testing. The growing demand for bioinks is propelling advancements in material formulations.
By End-User, academic and research institutes are the largest consumers, utilizing bioprinting for scientific exploration. Pharmaceutical and biotechnology companies follow, leveraging the technology for drug development and personalized medicine. Hospitals are adopting bioprinting for customized treatments and surgical planning.
By Technology, inkjet-based bioprinting is widely used due to its precision and versatility. Magnetic levitation is gaining attention for its ability to print high-resolution structures. Syringe-based and laser-based technologies continue to evolve, while other technologies cater to niche applications. Each technology contributes to different aspects of tissue complexity and functional accuracy.
Segmentation:
By Material:
- Living Cells
- Hydrogels
- Extracellular Matrices
- Other Material
By Application:
- Medical
- Dental
- Biosensors
- Consumer/Personal Product Testing
- Bioinks
By End-User:
- Academic & Research Institute
- Pharmaceutical and Biotechnology Companies
- Hospitals
By Technology:
- Inkjet-based
- Magnetic Levitation
- Syringe-based
- Laser-based
- Others
Regional Analysis:
The global 3D bioprinting market is experiencing diverse growth patterns across different regions, driven by varying levels of technological adoption, healthcare infrastructure, and investment in research and development. Key regions include North America, Europe, Asia-Pacific, and the rest of the world, each contributing uniquely to the market's expansion.
North America: Market Leader
North America holds the largest market share in the global 3D bioprinting market, accounting for over 40% of the total market revenue. The United States, in particular, plays a central role in this dominance, thanks to its advanced healthcare infrastructure, significant investments in research and development, and strong presence of key market players such as Organovo and EnvisionTEC. Additionally, government initiatives and favorable regulatory environments for bioprinting research further bolster the region’s leadership position. North America also benefits from the rapid commercialization of 3D bioprinting technologies, especially in medical applications like organ printing, regenerative medicine, and drug development. The region's strong focus on innovation in personalized medicine and its well-established network of research institutions provide a solid foundation for sustained market growth.
Europe: Steady Growth and Innovation
Europe holds a significant share of the global market, contributing around 30% to the overall market size. Countries such as Germany, the United Kingdom, and France are leading the way in 3D bioprinting adoption, driven by substantial government funding for bioprinting research and increasing collaborations between academic institutions and private industry. Europe's emphasis on improving healthcare access and personalized treatments, along with its well-established regulatory frameworks, supports the growing use of 3D bioprinting technologies in medical applications. The market is also expanding due to rising healthcare expenditures and the increasing demand for advanced therapies, particularly in regenerative medicine and tissue engineering.
Asia-Pacific: Fastest Growing Market
The Asia-Pacific region is the fastest-growing market for 3D bioprinting. The region's market share is currently around 20%, but it is steadily increasing due to rapid advancements in healthcare infrastructure, government initiatives supporting technological innovation, and lower operational costs. China, Japan, and India are the major players in the region, with substantial investments in bioprinting research and development. Additionally, the large patient pool in countries like India, along with an increasing focus on personalized healthcare, provides ample growth opportunities for 3D bioprinting applications, particularly in drug testing and regenerative medicine. The region's favorable environment for medical innovation is also expected to drive continued adoption of 3D bioprinting technologies.
Rest of the World: Emerging Opportunities
The rest of the world, including regions such as Latin America, the Middle East, and Africa, holds a smaller market share but presents significant growth potential. Market penetration in these regions is currently low, but increasing healthcare investments, expanding access to advanced medical technologies, and growing collaborations with international companies are expected to drive future growth. In Latin America, Brazil is a key player in the bioprinting sector, while the Middle East is witnessing increased interest from countries like Saudi Arabia and the UAE, who are investing heavily in healthcare infrastructure. As these regions continue to invest in healthcare innovation and expand research initiatives, the 3D bioprinting market will see steady growth in the coming years.
Key Player Analysis:
- EnvisionTEC, Inc.
- Organovo
- Inventia Life Science Pty Ltd
- POIETIS
- VIVAX BIO, LLC
- ALLEVI
- Cyfuse Biomedical K.K.
- 3D Bioprinting Solutions
- CELLINK GLOBAL
- REGEMAT 3D S.L.
Competitive Analysis:
The global 3D bioprinting market is highly competitive, with numerous players ranging from established companies to emerging startups. Leading companies such as Organovo, EnvisionTEC, and Stratasys dominate the market by offering advanced bioprinting solutions and establishing a strong presence in research and commercial applications. These key players focus on continuous innovation, with a particular emphasis on enhancing the functionality and precision of bioprinting technologies for use in tissue engineering, regenerative medicine, and drug testing. Smaller companies and startups, such as CELLINK and RegenHU, are also gaining traction by developing specialized bioinks and user-friendly bioprinting platforms tailored to specific market needs. Strategic partnerships, collaborations, and acquisitions are common, as companies seek to expand their technology portfolios and increase market share. As the demand for personalized healthcare and drug development grows, competition in the market will intensify, pushing players to advance their technological capabilities and broaden their service offerings.
Recent Developments:
- In 2025, Cyfuse Biomedical K.K., a Japanese company, unveiled a pilot program for bioprinted nerve repair grafts. Cyfuse's unique scaffold-free tissue fabrication process, which utilizes robotic assembly of spheroids into complex 3D shapes, is accelerating advancements in regenerative medicine, particularly in the commercialization of tissue patches for clinical use and applications in regenerative orthopedics and neurology.
- In June 2024, Ronawk, a company specializing in advanced tissue mimetic technologies, partnered with B9Creations to mass-produce 3D bioprinted hydrogels using Ronawk's Bio-Blocks. This collaboration focuses on producing tissue constructs that closely mimic the natural architecture and function of human and animal tissues, offering a more physiologically relevant environment for cell growth compared to traditional methods. The partnership is expected to enhance the scalability and reproducibility of tissue engineering for research and clinical use.
- In April 2023, CollPlant Biotechnologies Ltd., based in Israel, entered into a significant collaboration with Stratasys, a leading U.S.-based 3D printing company, to develop advanced solutions for bio-fabricating human tissues and organs. This partnership leverages Stratasys' P3 technology-based bioprinter and CollPlant's recombinant human collagen (rh-Collagen)-based bioinks, aiming to accelerate the creation of functional, transplantable tissues and organs for medical applications.
Market Concentration & Characteristics:
The global 3D bioprinting market is moderately concentrated, with a few dominant players holding significant market share, while a growing number of emerging companies are contributing to innovation and market expansion. Major players such as Organovo, Stratasys, and CELLINK lead the market, focusing on advanced bioprinting technologies, particularly in tissue engineering, regenerative medicine, and pharmaceutical applications. These companies invest heavily in research and development to enhance the functionality and precision of their bioprinting solutions. The market is characterized by high levels of innovation, as companies continually improve their product offerings to meet the increasing demand for personalized healthcare, drug testing, and organ printing. Additionally, strategic partnerships and collaborations are common, as companies aim to expand their technological capabilities and strengthen their market presence. While the market remains competitive, the rapid pace of technological advancements presents significant opportunities for new entrants and smaller players to make an impact.
Report Coverage:
The research report offers an in-depth analysis based on Material, Application, End-User and Technology. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The global 3D bioprinting market is expected to continue growing at a strong CAGR, driven by technological advancements in bioprinting techniques and materials.
- Increased demand for personalized medicine will fuel the adoption of patient-specific bioprinted tissues and organs.
- The pharmaceutical industry will increasingly use 3D bioprinting for drug development and testing, reducing the need for animal models.
- Continued innovations in bioinks will enable the printing of more complex and functional tissues, enhancing clinical applications.
- Collaboration between academic institutions, healthcare providers, and industry leaders will accelerate the commercialization of bioprinting technologies.
- Regulatory bodies will develop clearer guidelines, easing the approval process and encouraging wider adoption of bioprinted medical solutions.
- Bioprinting applications will expand beyond healthcare into sectors such as food production and sustainable fashion.
- Emerging markets, particularly in Asia-Pacific and Latin America, will drive new growth opportunities as healthcare infrastructure improves.
- The focus on organ transplantation will intensify, pushing for advances in the creation of fully functional, vascularized organs.
- The integration of AI and machine learning with 3D bioprinting will streamline production and improve the accuracy of bioprinted tissues.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Demand for Organ Transplants
The persistent global shortage of donor organs is driving the adoption of 3D bioprinting, as it enables the creation of functional tissues and organs that can potentially be used for transplantation, reducing waiting times and improving patient outcomes.
Technological Advancements in Bioprinting
Continuous improvements in bioprinting precision, bioink formulations, and processing speeds are expanding the range and complexity of tissues that can be produced, making 3D bioprinting more viable for clinical and research applications.
Growth in Regenerative Medicine and Personalized Healthcare
The shift toward regenerative medicine and personalized treatments is boosting demand for 3D bioprinting, as it allows for the creation of patient-specific tissues and organs, improving treatment efficacy and reducing the risk of rejection.
Rising Investments in Research and Development
Significant funding from both public and private sectors is accelerating innovation in 3D bioprinting, leading to new applications, improved accessibility, and reduced costs, which in turn drives broader market adoption.
Expansion of Bioprinting Applications in Drug Development
Pharmaceutical companies are increasingly using 3D bioprinted tissues for drug testing and development, as these models better mimic human physiology than traditional methods, enabling more accurate and efficient drug discovery processes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global 3D bioprinting Market?
What factors are driving the growth of the Global 3D bioprinting Market?
What are the key segments within the Global 3D bioprinting Market?
What are some challenges faced by the Global 3D bioprinting Market?
Who are the major players in the Global 3D bioprinting Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Academic & Research Institute
- 1.2.2 Pharmaceutical and Biotechnology Companies
- 1.2.3 Hospitals
- 1.3 By Material
- 1.3.1 Living Cells
- 1.3.2 Hydrogels
- 1.3.3 Extracellular Matrices
- 1.3.4 Other Material
- 1.4 By Technology
- 1.4.1 Inkjet-based
- 1.4.2 Magnetic Levitation
- 1.4.3 Syringe-based
- 1.4.4 Laser-based
- 1.4.5 Others
- 1.5 By Application
- 1.5.1 Medical
- 1.5.2 Dental
- 1.5.3 Biosensors
- 1.5.4 Consumer/Personal Product Testing
- 1.5.5 Bioinks
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 1,500.00 million → 2032: USD 4,295.25 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global 3D Bioprinting Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global 3D Bioprinting Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global 3D Bioprinting Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global 3D Bioprinting Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global 3D Bioprinting Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global 3D Bioprinting Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global 3D Bioprinting Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global 3D Bioprinting Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 1,500.00 million → 2032: USD 4,295.25 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global 3D Bioprinting Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Academic & Research Institute
- 12.3.7.2 Pharmaceutical and Biotechnology Companies
- 12.3.7.3 Hospitals
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Living Cells
- 12.4.7.2 Hydrogels
- 12.4.7.3 Extracellular Matrices
- 12.4.7.4 Other Material
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Inkjet-based
- 12.5.7.2 Magnetic Levitation
- 12.5.7.3 Syringe-based
- 12.5.7.4 Laser-based
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Medical
- 12.6.7.2 Dental
- 12.6.7.3 Biosensors
- 12.6.7.4 Consumer/Personal Product Testing
- 12.6.7.5 Bioinks
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global 3D Bioprinting End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global 3D Bioprinting Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global 3D Bioprinting Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global 3D Bioprinting Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Organovo
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 EnvisionTEC, Inc.
- 18.4 CELLINK GLOBAL
- 18.5 Stratasys
- 18.6 Inventia Life Science Pty Ltd
- 18.7 POIETIS
- 18.8 VIVAX BIO, LLC
- 18.9 Cyfuse Biomedical K.K.
- 18.10 3D Bioprinting Solutions
- 18.11 REGEMAT 3D S.L.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

