
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| 3D NAND Flash Memory Market Size 2024 | USD 28,427.00 Million |
| 3D NAND Flash Memory Market, CAGR | 18.10% |
| 3D NAND Flash Memory Market Size 2032 | USD 107,579.67 Million |
Market Overview
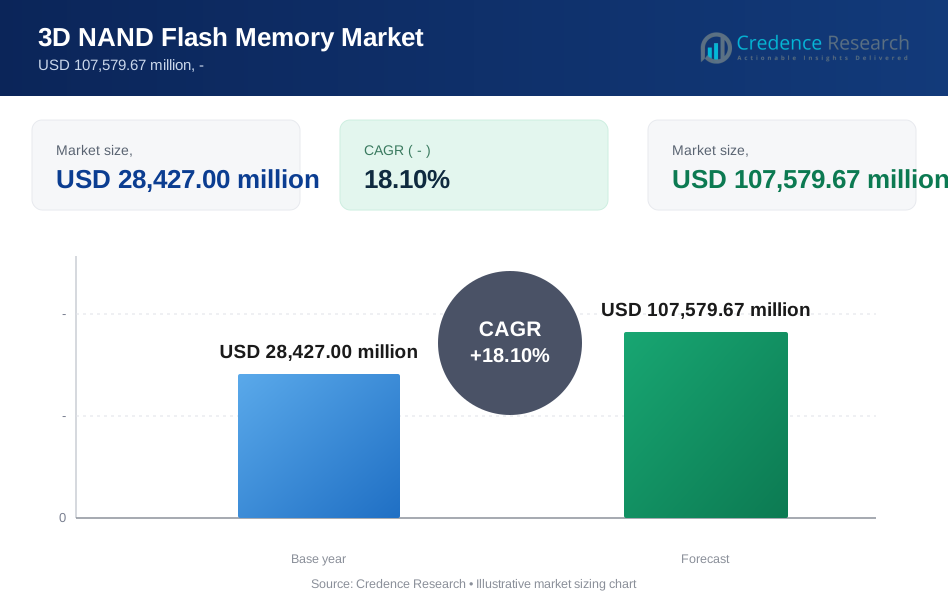
The 3D NAND Flash Memory market is projected to grow from USD 28,427.00 million in 2024 to USD 107,579.67 million by 2032, reflecting a compound annual growth rate (CAGR) of 18.10%.
The 3D NAND Flash Memory market is experiencing robust growth driven by escalating demand for higher storage capacities in consumer electronics and data centers. Innovations in technology that enable more storage layers without increasing physical size are key to meeting the expanding data storage requirements of modern devices and cloud services. Additionally, the integration of 3D NAND technology in smartphones, laptops, and solid-state drives (SSDs) is propelling market expansion. These trends, coupled with the declining costs of NAND Flash production, are set to further enhance market penetration and the adoption of high-capacity, efficient storage solutions.
The 3D NAND Flash Memory market is geographically segmented with Asia-Pacific leading the charge, home to key players such as Samsung Electronics, SK Hynix, and Kioxia Corporation, which dominate due to their advanced manufacturing capabilities and substantial R&D investments. North America follows, with significant contributions from Intel Corporation and Micron Technology, driven by robust technological infrastructure and high demand across consumer electronics and data centers. These regions not only host major manufacturing hubs but also lead in technological innovations, making them pivotal to the global expansion and evolution of the 3D NAND flash memory industry.
Market Drivers
Rising Storage Requirements in Consumer Electronics
The demand for higher storage capacities in consumer electronics like smartphones and laptops is intensifying. For instance, the rising storage requirements in consumer electronics are evident in the fact that consumers are increasingly demanding faster products with more storage and better cameras. Smartphones equipped with high-resolution cameras and data-intensive applications necessitate larger storage spaces, driving the adoption of 3D NAND technology. Similarly, the trend towards slimmer and more compact tablets and laptops has fostered the replacement of traditional hard disk drives (HDDs) with solid-state drives (SSDs) that utilize 3D NAND for enhanced storage efficiency and device miniaturization.
Expanding Data Needs in Data Centers and Cloud Computing
Data centers supporting cloud computing services are undergoing rapid expansion, requiring vast amounts of high-density storage. 3D NAND flash memory meets this need with its capability to offer large storage capacities while maintaining fast read and write speeds essential for handling data-intensive applications. For instance, according to a survey by the Securities and Exchange Board of India, the registered investor base at the National Stock Exchange has grown significantly, indicating increased data storage needs. This technology's superior performance is crucial for optimizing data processing and accessibility in cloud environments, making it a foundational component of modern data infrastructure.
Integration of 3D NAND in IoT and Automotive Industries
In the realm of the Internet of Things (IoT), 3D NAND flash memory plays a pivotal role by providing local storage solutions necessary for data collection and processing in devices like smart home appliances and wearables. Additionally, the shift towards edge computing requires reliable storage that can handle extensive data generation on-site, which 3D NAND facilitates effectively. In the automotive sector, advanced infotainment systems and the development of autonomous vehicles demand high-capacity, high-performance storage solutions to manage intricate algorithms and extensive sensor data, areas where 3D NAND excels.
Technological Innovations and Cost Efficiency
Technological advancements continue to propel the 3D NAND market forward. Manufacturers are increasing the number of layers in 3D NAND chips, enhancing storage density and reducing the cost per gigabyte. This layer stacking technique, coupled with improvements in controller technology and firmware, boosts both performance and reliability. Furthermore, economies of scale achieved in the production of 3D NAND have led to reduced manufacturing costs, increasing its affordability and accessibility across a broad range of applications.
Market Trends
Rapid Technological Evolution and Expanding Applications in Storage
The 3D NAND Flash Memory market is characterized by rapid technological advancements, particularly in layer stacking techniques. For instance, a survey by the Semiconductor Industry Association found that manufacturers are progressively increasing the number of layers in 3D NAND chips, with some companies reporting chips with over 200 layers in development. Manufacturers are progressively increasing the number of layers in 3D NAND chips, which enhances storage density and reduces the cost per gigabyte significantly. Simultaneously, advances in controller technology and firmware optimization are improving the performance and reliability of 3D NAND, making it more suitable for a wide range of applications. These continuous improvements are essential for keeping pace with the increasing demands for data storage capacity and speed in various tech sectors. There is a noticeable shift towards Universal Flash Storage (UFS) and NVMe SSDs across several platforms. UFS is becoming the preferred storage standard for mobile devices like smartphones and tablets due to its superior performance and efficiency over traditional eMMC solutions. Additionally, UFS is making significant inroads in embedded systems, including IoT devices and automotive infotainment systems, where fast and reliable storage solutions are crucial. Similarly, the adoption of NVMe SSDs is escalating in data centers and enterprise applications, driven by their low latency and high throughput capabilities, which are essential for handling high-performance workloads efficiently.
Competitive Landscape and Sustainability Focus
The 3D NAND market is witnessing intense competition among major semiconductor manufacturers like Samsung, Intel, Micron, SK Hynix, and Toshiba. This competition is fostering innovation but also creating price pressures that could impact the profitability of these firms. In response to environmental concerns, there is also a growing focus on developing more energy-efficient 3D NAND technologies. Efforts to enhance the recyclability and reusability of NAND components are underway, aiming to minimize the environmental impact of electronic waste. The demand for 3D NAND is also being propelled by emerging applications in AI and machine learning, which require robust, high-capacity storage solutions to manage large datasets effectively. Additionally, augmented reality (AR) and virtual reality (VR) technologies are pushing the boundaries for storage, as these platforms require extensive capacities to process and store immersive content. These applications highlight the dynamic nature of the 3D NAND market and underscore the ongoing need for innovation in storage technology to meet the evolving demands of modern digital applications.
Market Challenges Analysis
Production Challenges and Cost Pressures in 3D NAND Manufacturing
The production of 3D NAND flash memory involves sophisticated manufacturing processes that become increasingly complex as the number of layers in memory cells rises. This complexity can lead to significant yield issues, where higher layer counts exacerbate the challenges of maintaining production efficiency and quality. Managing defects in these intricate multi-layer structures demands advanced technology and precision, which can significantly influence the overall product quality and output rates. These manufacturing complexities not only affect supply but also escalate production costs, impacting the economic scale of operations in the highly competitive memory market. The 3D NAND market is characterized by fierce price competition among leading players, which puts considerable pressure on profitability. This environment compels companies to continuously innovate and improve their products, necessitating substantial investments in research and development. These financial pressures are compounded by the high cost of pioneering new technologies and scaling up production capabilities to meet global demand. Moreover, the ongoing need to advance the technology while reducing costs presents a dual challenge, as firms strive to balance innovation with financial sustainability.
Technological and Supply Chain Vulnerabilities
As 3D NAND technology approaches the physical limits of scaling how many layers can be feasibly stacked manufacturers face potential constraints on future growth and performance enhancements. For instance, industry surveys have revealed that manufacturers are increasingly concerned about the technical feasibility of continually increasing layer counts. Although recent advancements have significantly improved the endurance and reliability of 3D NAND, ongoing challenges with long-term data retention and operational durability remain. Concurrently, emerging memory technologies like resistive random access memory (RRAM) and phase-change memory (PCM) pose competitive threats, offering alternative solutions that could disrupt the market dominance of 3D NAND in certain applications. The global nature of the semiconductor supply chain exposes 3D NAND manufacturing to geopolitical tensions, natural disasters, and logistic disruptions, which can severely impact the availability of critical raw materials and manufacturing capacity. Additionally, the concentration of manufacturing facilities in specific geographic areas increases vulnerability to regional disruptions. Environmental concerns also play a significant role, as the energy-intensive production of 3D NAND and subsequent waste generation call for enhanced sustainability measures. Companies are increasingly investing in greener technologies and practices to mitigate environmental impacts and align with global sustainability goals, adding another layer of complexity to the operational strategies of 3D NAND manufacturers.
Market Segmentation Analysis:
By Product:
In the 3D NAND flash memory market, segmentation by type includes single-level cells (SLC), multi-level cells (MLC), and triple-level cells (TLC). SLCs, known for their high durability and fast performance, are predominantly used in industrial and high-performance applications where reliability is crucial. MLCs, which store more data per cell than SLCs, strike a balance between cost, performance, and endurance, making them suitable for consumer electronics and business applications. TLCs, which store three bits per cell, offer even greater capacity and cost efficiency but at the expense of lower endurance and slower write speeds, catering primarily to large-scale consumer storage solutions. This diversity allows manufacturers to target a broad range of applications, adjusting the technology to meet specific reliability and cost requirements.
By Application:
The application segments for 3D NAND flash memory encompass cameras, laptops and personal computers, smartphones and tablets, among others. In cameras, 3D NAND is essential for storing high-resolution images and video content. For laptops and personal computers, this memory type enhances the performance and reliability of SSDs, crucial for both consumer and business users. Smartphones and tablets, which require substantial memory within compact designs, benefit significantly from 3D NAND's ability to provide increased storage capacity without compromising the device's size or battery life. Other emerging applications include gaming consoles and wearable devices, where enhanced storage capabilities are increasingly necessary. This segmentation reflects the versatility of 3D NAND technology and its growing integration across diverse technological platforms.
Segments:
Based on Type:
- Single-level cells (SLC)
- Multi-level cells (MLC)
- Triple-level cells (TLC)
Based on Application:
- Cameras
- Laptops and Personal Computers
- Smartphones and Tablets
- Others
Based on End-user:
- Automotive
- Consumer Electronics
- Enterprise
- Healthcare
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Asia-Pacific
The Asia-Pacific region is a powerhouse in the 3D NAND flash memory market, commanding a significant share with over 40% of the global market. This dominance is driven by the presence of major semiconductor manufacturing hubs in countries like South Korea, China, and Taiwan, where leading companies such as Samsung and SK Hynix are headquartered. The region benefits from advanced manufacturing capabilities, significant investments in R&D, and strong governmental support for semiconductor industries. Additionally, the rising demand for consumer electronics and mobile devices in populous countries like India and China fuels the regional market's growth, leveraging cost-effective manufacturing and a growing tech-savvy consumer base.
North America
In North America, particularly the United States, the 3D NAND flash memory market holds approximately 25% of the global market share. This region's market is characterized by high adoption rates of advanced technology solutions in consumer electronics, enterprise storage, and automotive applications. For instance, the rise in space constraints on the semiconductor wafer and high performance & low latency of 3D NAND flash memory are driving the growth of the market. The presence of major technology firms, such as Intel and Micron, drives innovation and development within the sector, focusing on enhancing data storage solutions with higher capacity and reliability. North America's strong infrastructure for research and technological advancement supports the rapid integration of 3D NAND in next-generation consumer and industrial products. Moreover, the increasing focus on data centers and cloud services in the U.S. continues to drive demand for high-performance storage solutions, making it a critical market for 3D NAND technology developers.
Key Player Analysis
- SK Hynix
- Micron Technology
- Intel Corporation
- Samsung Electronics
- Western Digital Corporation
- Kioxia Corporation (formerly Toshiba Memory Corporation)
- SanDisk (a division of Western Digital)
- YMTC (Yangtze Memory Technologies Co., Ltd.)
- Nanya Technology Corporation
- Powerchip Technology Corporation
- Intel-Micron Flash Technologies (IMFT)
- XMC (Xiamen Xinxin Semiconductor Manufacturing Corporation)
- Macronix International
- Transcend Information
- ADATA Technology
- Phison Electronics Corporation
- Silicon Motion Technology Corporation
- Netlist, Inc.
- SK Hynix System IC, Inc.
- GigaDevice Semiconductor (Beijing) Inc.
Competitive Analysis
The competitive landscape of the 3D NAND Flash Memory market is characterized by intense rivalry among major players. Samsung Electronics, SK Hynix, and Micron Technology lead with advanced manufacturing technologies and substantial R&D investments, maintaining their dominance through innovation and production efficiency. The major players compete by investing in research and development to enhance their product offerings, focusing on improving performance, density, and reliability. They also engage in strategic partnerships and acquisitions to expand their market presence and capabilities. Pricing strategies and manufacturing efficiencies are crucial factors influencing the competitive dynamics. Additionally, innovation in production technologies, such as advanced layering techniques, plays a significant role in maintaining market leadership and responding to evolving consumer and industry demands.
Recent Developments
- In April 2024, Samsung Electronics Co., based in South Korea, launched mass production of its latest 286-layer NAND chips, increasing storage capacity by 50%. Samples were shipped to tech giants like Google and Apple, targeting AI data centers and smartphones.
- In August 2023, SK Hynix, based in South Korea, revealed its groundbreaking 321-layer 3D NAND flash technology at the Flash Memory Summit. The innovation boasted a storage capacity of 1Tbit per silicon die, marking a significant advancement in storage density and performance over its predecessor.
- In March 2023, Western Digital and Kioxia Corporation announced their sixth-generation, 162-layer 3D flash memory technology.
- In April 2024, Japan-based Kioxia announced its plan to mass-produce 3D NAND memory with over 1,000 layers by 2031. Hidefumi Miyajima, the company’s CTO, discussed the technical challenges and solutions for achieving this during a lecture at the 71st Applied Physics Society Spring Meeting at Tokyo City University.
- In December 2023, SK Hynix, headquartered in South Korea, actively recruited Richard Pasto, a senior lead engineer from Intel, to bolster its research & development capabilities. Pasto, with 28 years of experience, joined other Intel experts like Rezaul Haque and Erika Shiple, who had joined in June and November 2023, respectively.
Market Concentration & Characteristics
The 3D NAND Flash Memory market is characterized by moderate to high market concentration, with a few major players dominating the sector. This concentration results from significant capital requirements and advanced technological expertise needed for production and innovation. Leading companies leverage their extensive research and development capabilities to maintain competitive advantages, driving advancements in storage density, performance, and cost efficiency. The market features rapid technological evolution, with ongoing improvements in layer stacking and performance enhancements shaping industry trends. Despite the concentration, new entrants are emerging, driven by advancements in manufacturing technology and the demand for specialized applications. This dynamic landscape fosters intense competition and continuous innovation, balancing the market’s concentration with opportunities for growth and technological breakthroughs. Overall, the 3D NAND Flash Memory market exhibits characteristics of both consolidation and competitive expansion, reflecting its evolving and high-tech nature.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-user and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The 3D NAND Flash Memory market is expected to experience substantial growth due to increasing demand for high-performance storage solutions across various sectors.
- Advances in layer stacking technology will drive higher storage densities and reduce costs per gigabyte, enhancing overall market appeal.
- The shift towards Universal Flash Storage (UFS) in mobile devices will further boost demand for 3D NAND Flash, providing faster data transfer speeds and improved performance.
- The growing adoption of NVMe SSDs will propel the market, particularly in data centers and enterprise applications, due to their low latency and high throughput.
- Technological innovations and improved controller technology will continue to enhance the performance and reliability of 3D NAND Flash Memory.
- Competition among major semiconductor manufacturers will lead to continued advancements and price adjustments, impacting market dynamics.
- Emerging applications in AI, machine learning, and AR/VR will drive demand for high-capacity and high-performance storage solutions.
- The focus on sustainability will lead to the development of more energy-efficient and recyclable 3D NAND technologies.
- Supply chain disruptions and geopolitical tensions may affect the availability of raw materials and manufacturing capacities.
- Continued research and development efforts will address technological limitations and scalability challenges, ensuring long-term market growth and innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the 3D NAND Flash Memory Market?
What factors are driving the growth of the 3D NAND Flash Memory market?
Which regions are leading in the 3D NAND Flash Memory market?
What are the major applications of 3D NAND Flash Memory?
What are the key challenges faced by the 3D NAND Flash Memory market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 3D NAND Flash Memory Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global 3D NAND Flash Memory Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 28,427.00 million → forecast year: USD 107,579.67 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 3D NAND Flash Memory Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. 3D NAND Flash Memory Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 3D NAND Flash Memory Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 3D NAND Flash Memory Market Drivers
- 3.3 3D NAND Flash Memory Market Restraints & Challenges
- 3.4 3D NAND Flash Memory Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 3D NAND Flash Memory Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 3D NAND Flash Memory Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, 3D NAND Flash Memory category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 3D NAND Flash Memory Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. 3D NAND Flash Memory Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the 3D NAND Flash Memory market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 3D NAND Flash Memory Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 3D NAND Flash Memory Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 3D NAND Flash Memory Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in 3D NAND Flash Memory (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New 3D NAND Flash Memory Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global 3D NAND Flash Memory Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America 3D NAND Flash Memory Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe 3D NAND Flash Memory Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific 3D NAND Flash Memory Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America 3D NAND Flash Memory Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East 3D NAND Flash Memory Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa 3D NAND Flash Memory Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. 3D NAND Flash Memory Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
