
Acetaminophen demand moves from opioid combos to plain doses
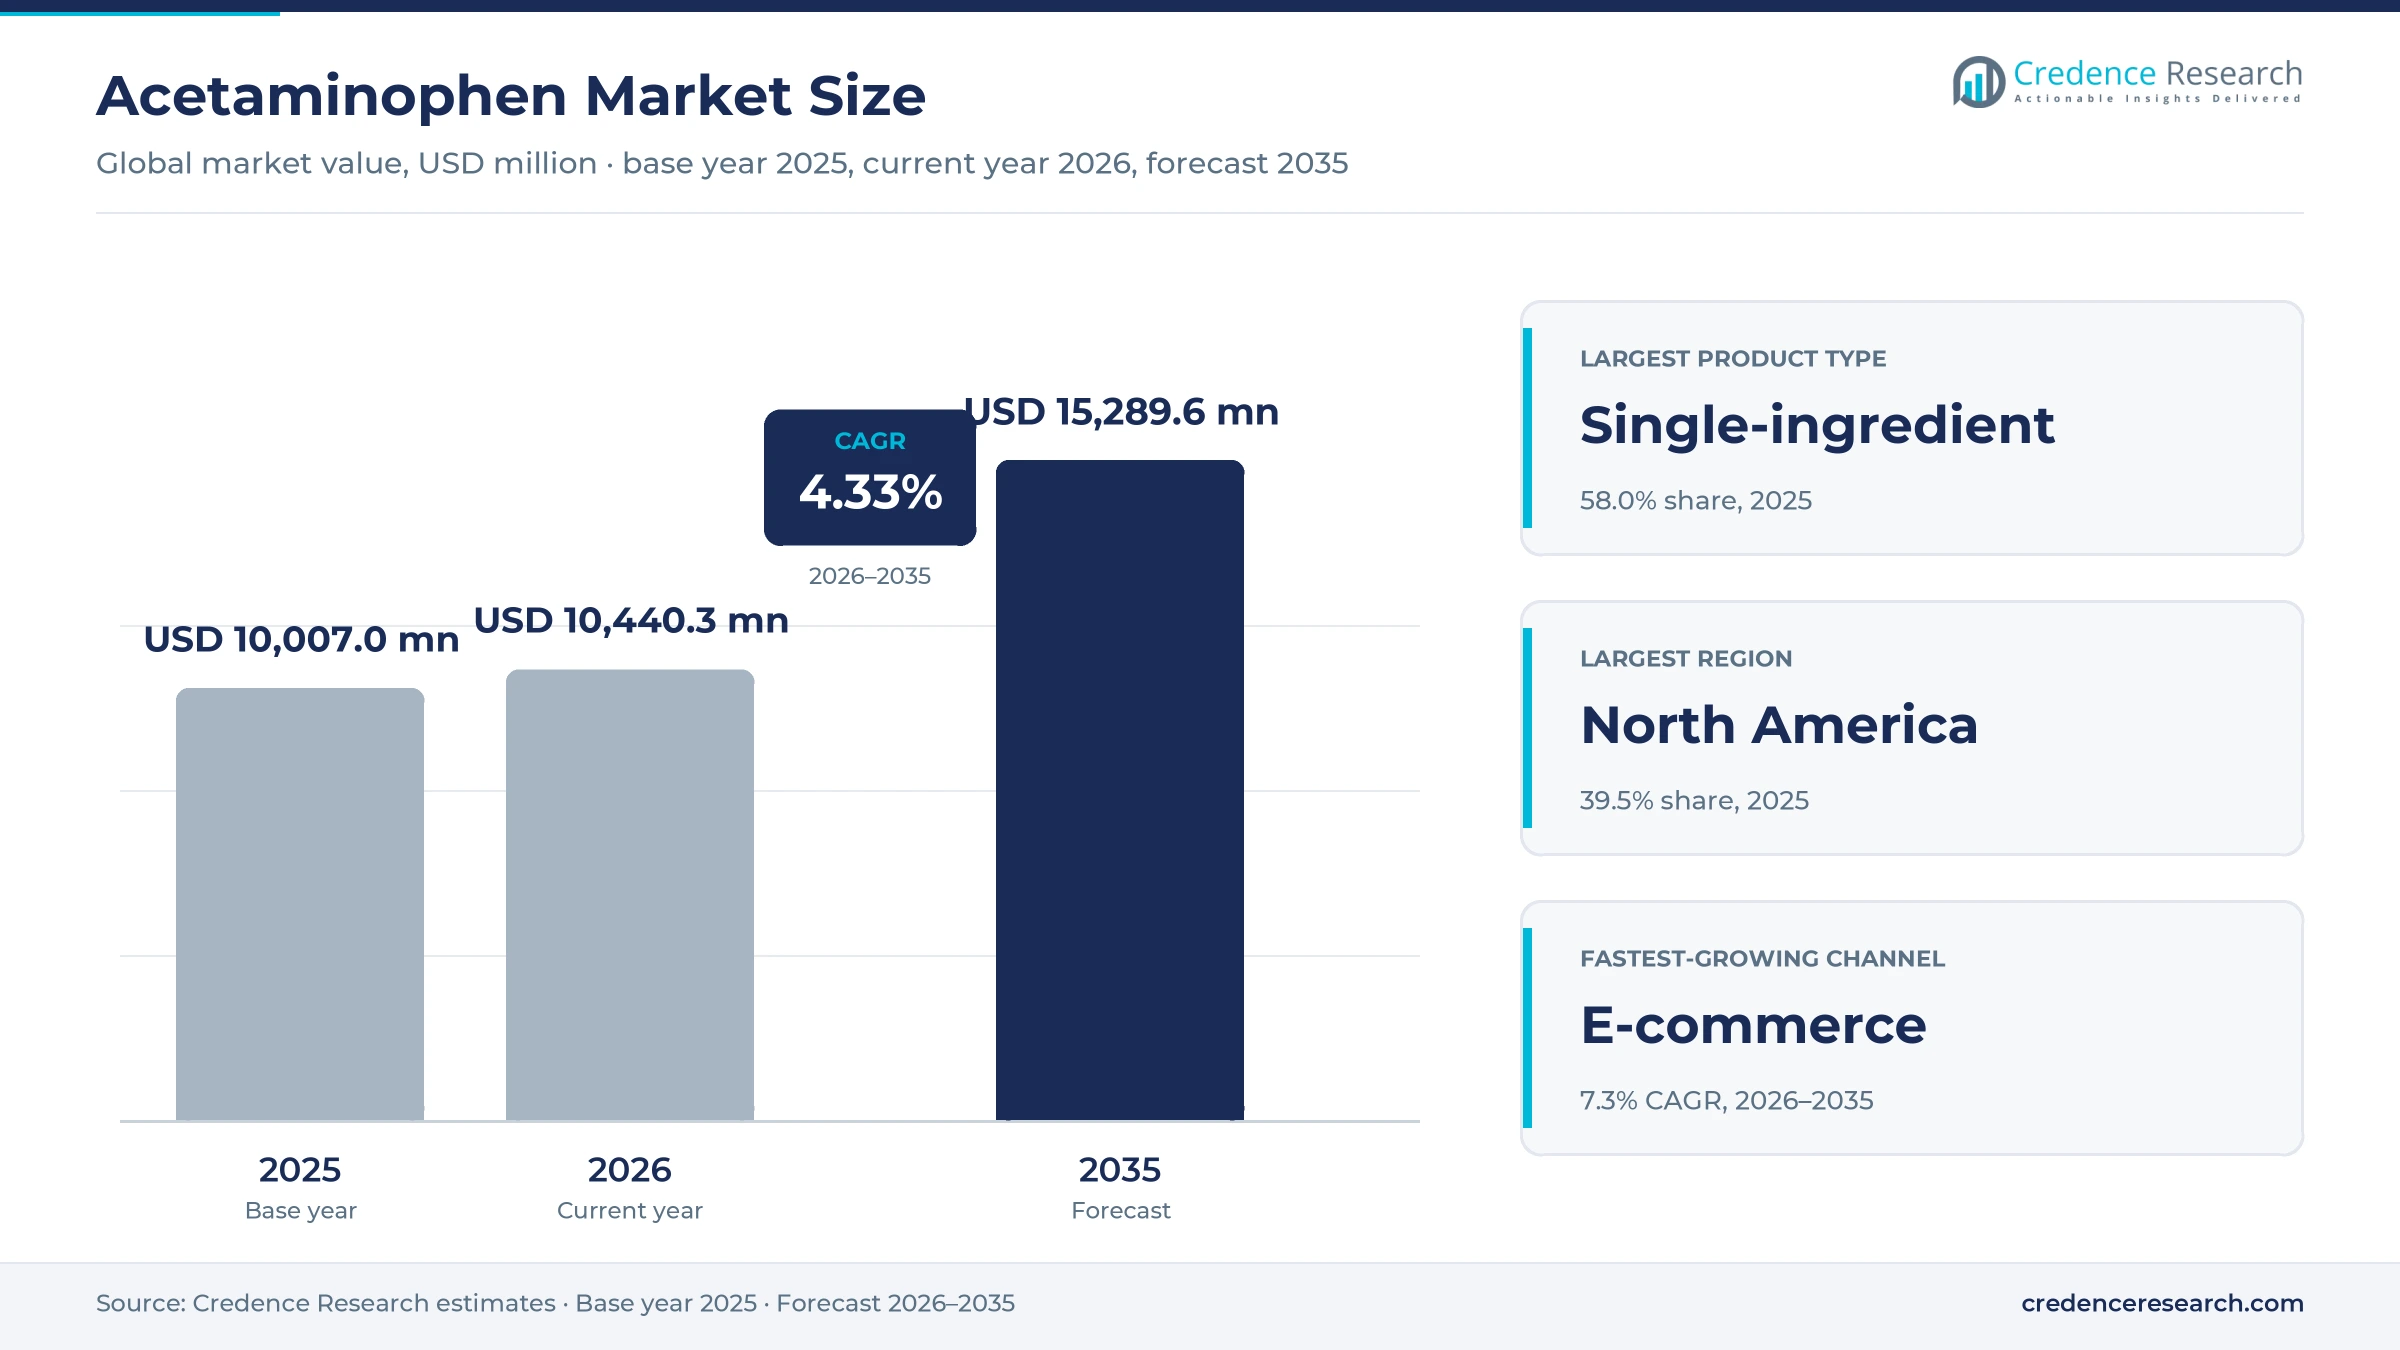
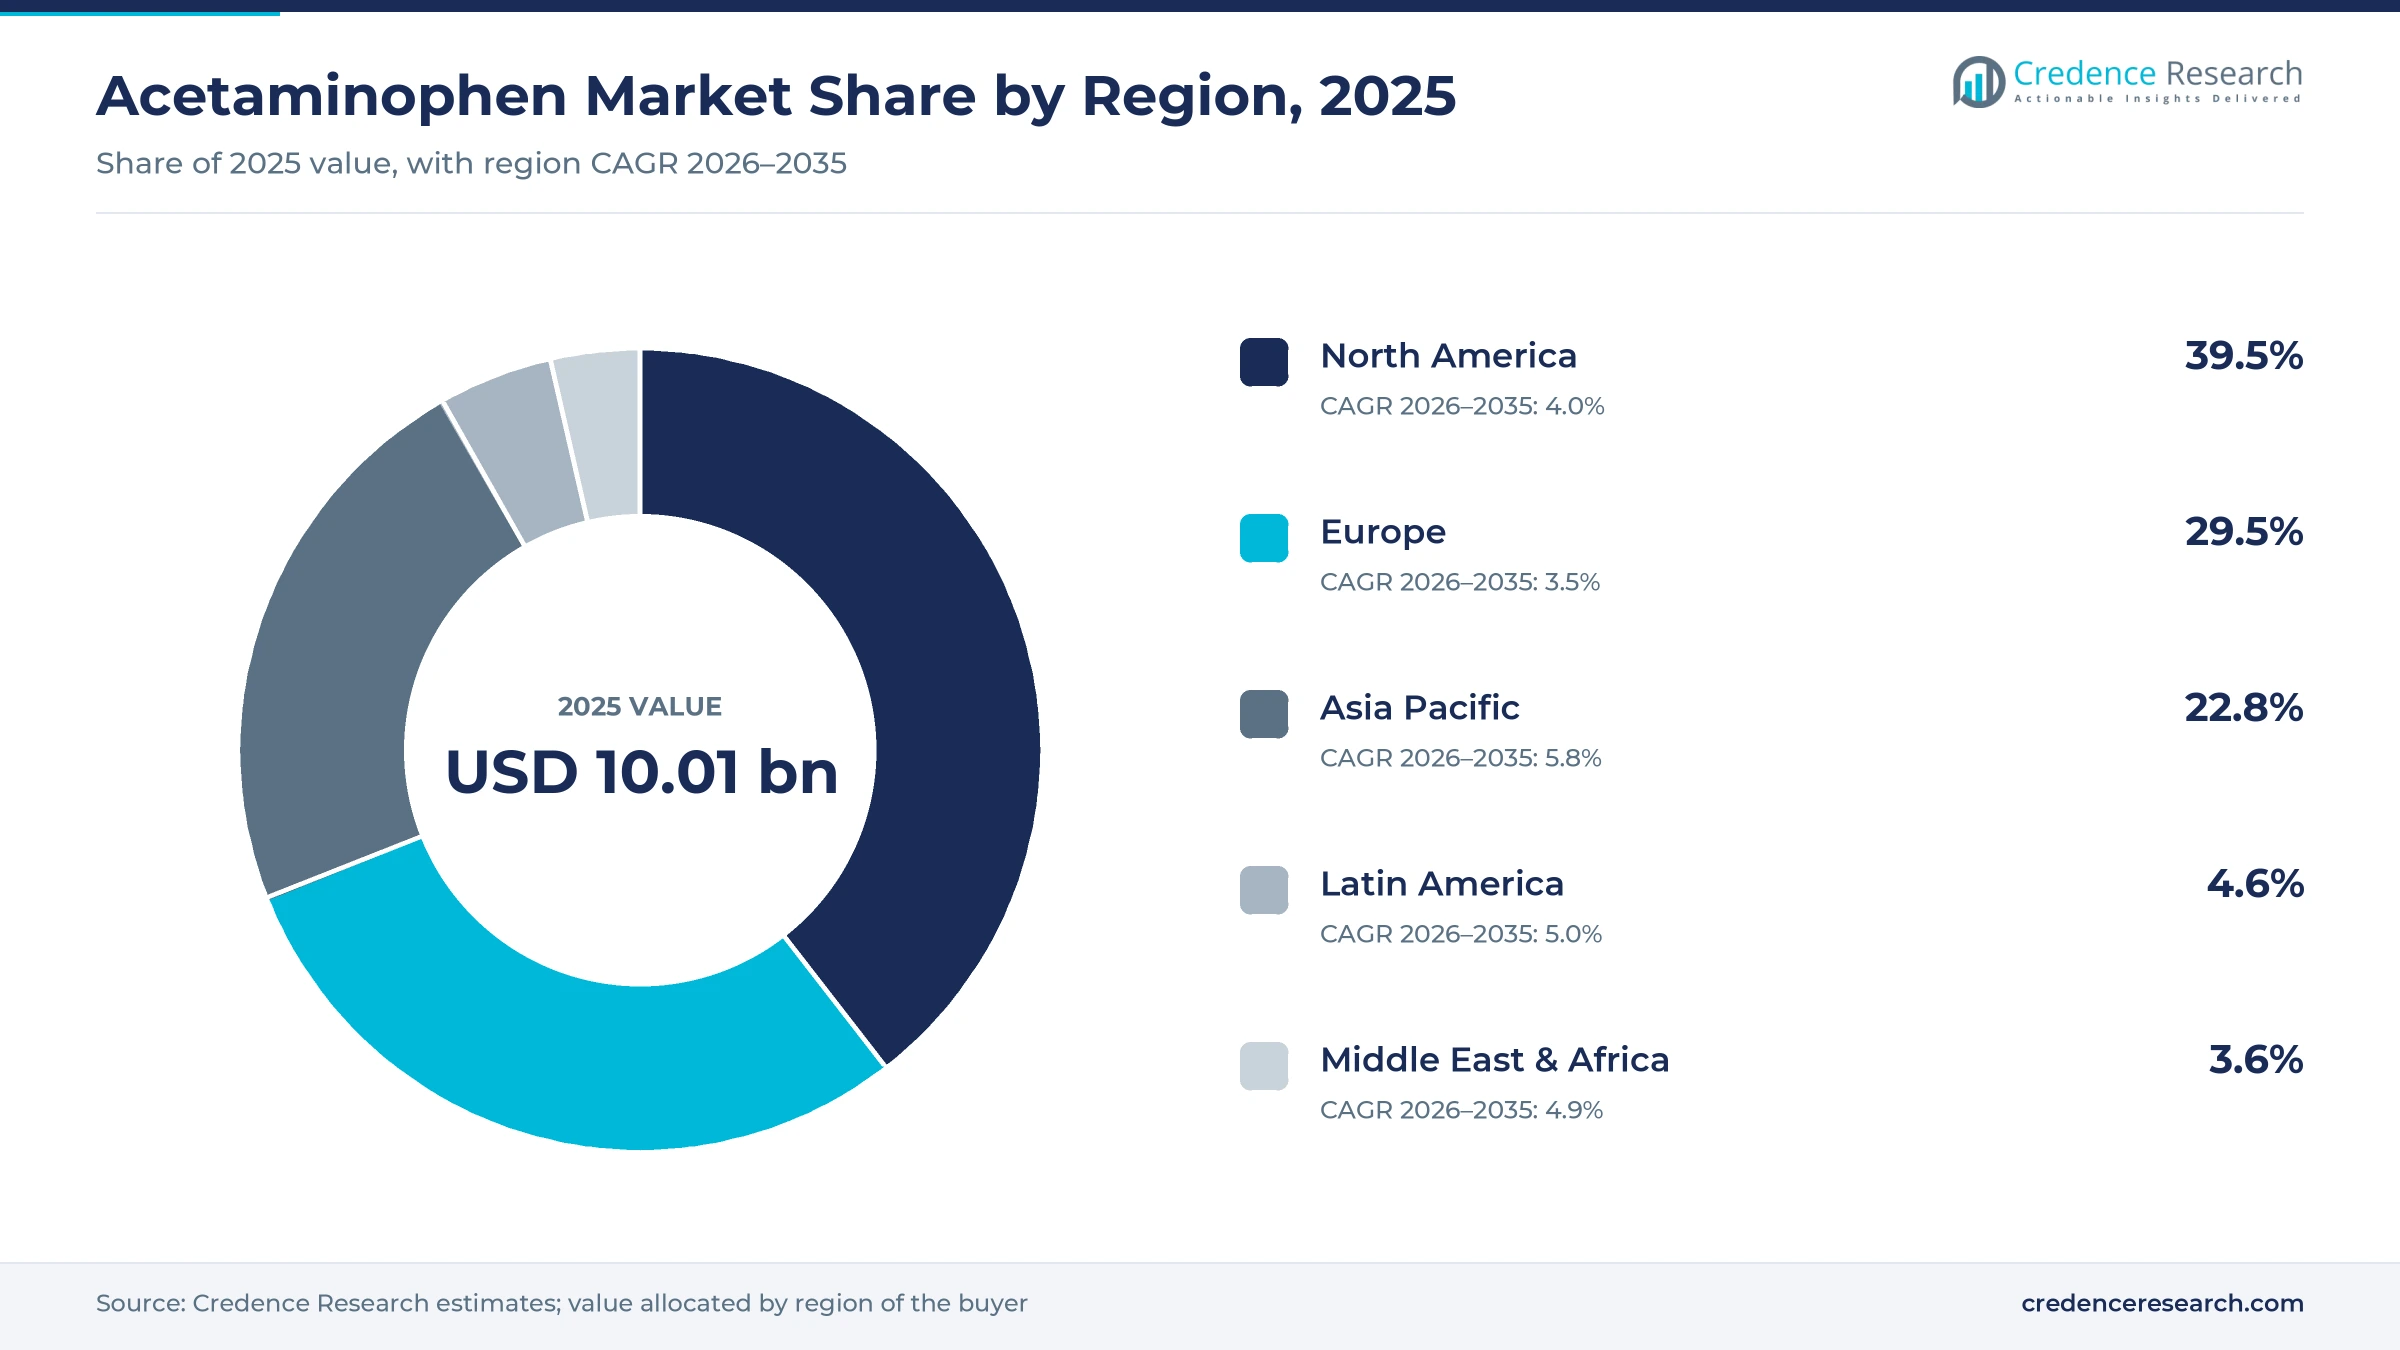
The global acetaminophen market was valued at USD 10.01 billion in 2025 and is projected to increase from USD 10.44 billion in 2026 to USD 15.29 billion by 2035, registering a CAGR of 4.33% during 2026–2035. Demand comes from adults treating joint pain, headaches and fever, from parents dosing children, and from hospitals that use the drug to cut opioid use after surgery. North America held the largest regional share, 39.5% in 2025, on high branded prices and a large prescription combination business. Asia Pacific is the fastest-growing region at 5.8% a year, because low-cost generics and small packs are reaching more buyers in India and Southeast Asia. The main commercial change is ownership, as the largest brands now sit with Kimberly-Clark and a private equity-controlled Opella, while the main restraint is a U.S. pregnancy label change that has raised legal risk for brand owners.
Which products and prices make up the market value?
The market counts finished medicines that contain acetaminophen, also called paracetamol, as an active ingredient, including plain tablets and liquids, cold and flu blends, fixed-dose combinations with ibuprofen or caffeine, prescription combinations with opioids and intravenous bags. Values are taken at the price the brand owner or generic maker receives from pharmacies, hospitals and retailers.
Bulk active ingredient sold to other drug makers is excluded so that value is counted once, inside the finished dose, and veterinary uses are excluded too. The value chain runs from para-aminophenol makers to ingredient producers, then to dose makers and finally to pharmacies, hospitals and online sellers.
Acetaminophen Market Insights
- The market is projected to rise from USD 10.01 billion in 2025 to USD 15.29 billion by 2035 at 4.33% a year, with growth led by plain doses, IV formats and Asian volume.
- North America held 39.5% of 2025 value, while Asia Pacific grows fastest at 5.8% a year on low-cost generics.
- Single-ingredient Acetaminophen led product types with 58.0% of 2025 value, as plain tablets remain the first choice for pain and fever.
- U.S. opioid dispensing fell from 46.8 to 35.4 prescriptions per 100 persons between 2019 and 2024, according to the CDC, shrinking combination demand.
- Kimberly-Clark completed its acquisition of Kenvue, the owner of Tylenol, on Nov. 2, 2026, which places the largest U.S. brand inside a broader consumer group.
Plain oral tablets lead while IV bags and online grow
How large is the acetaminophen opioid combination segment?
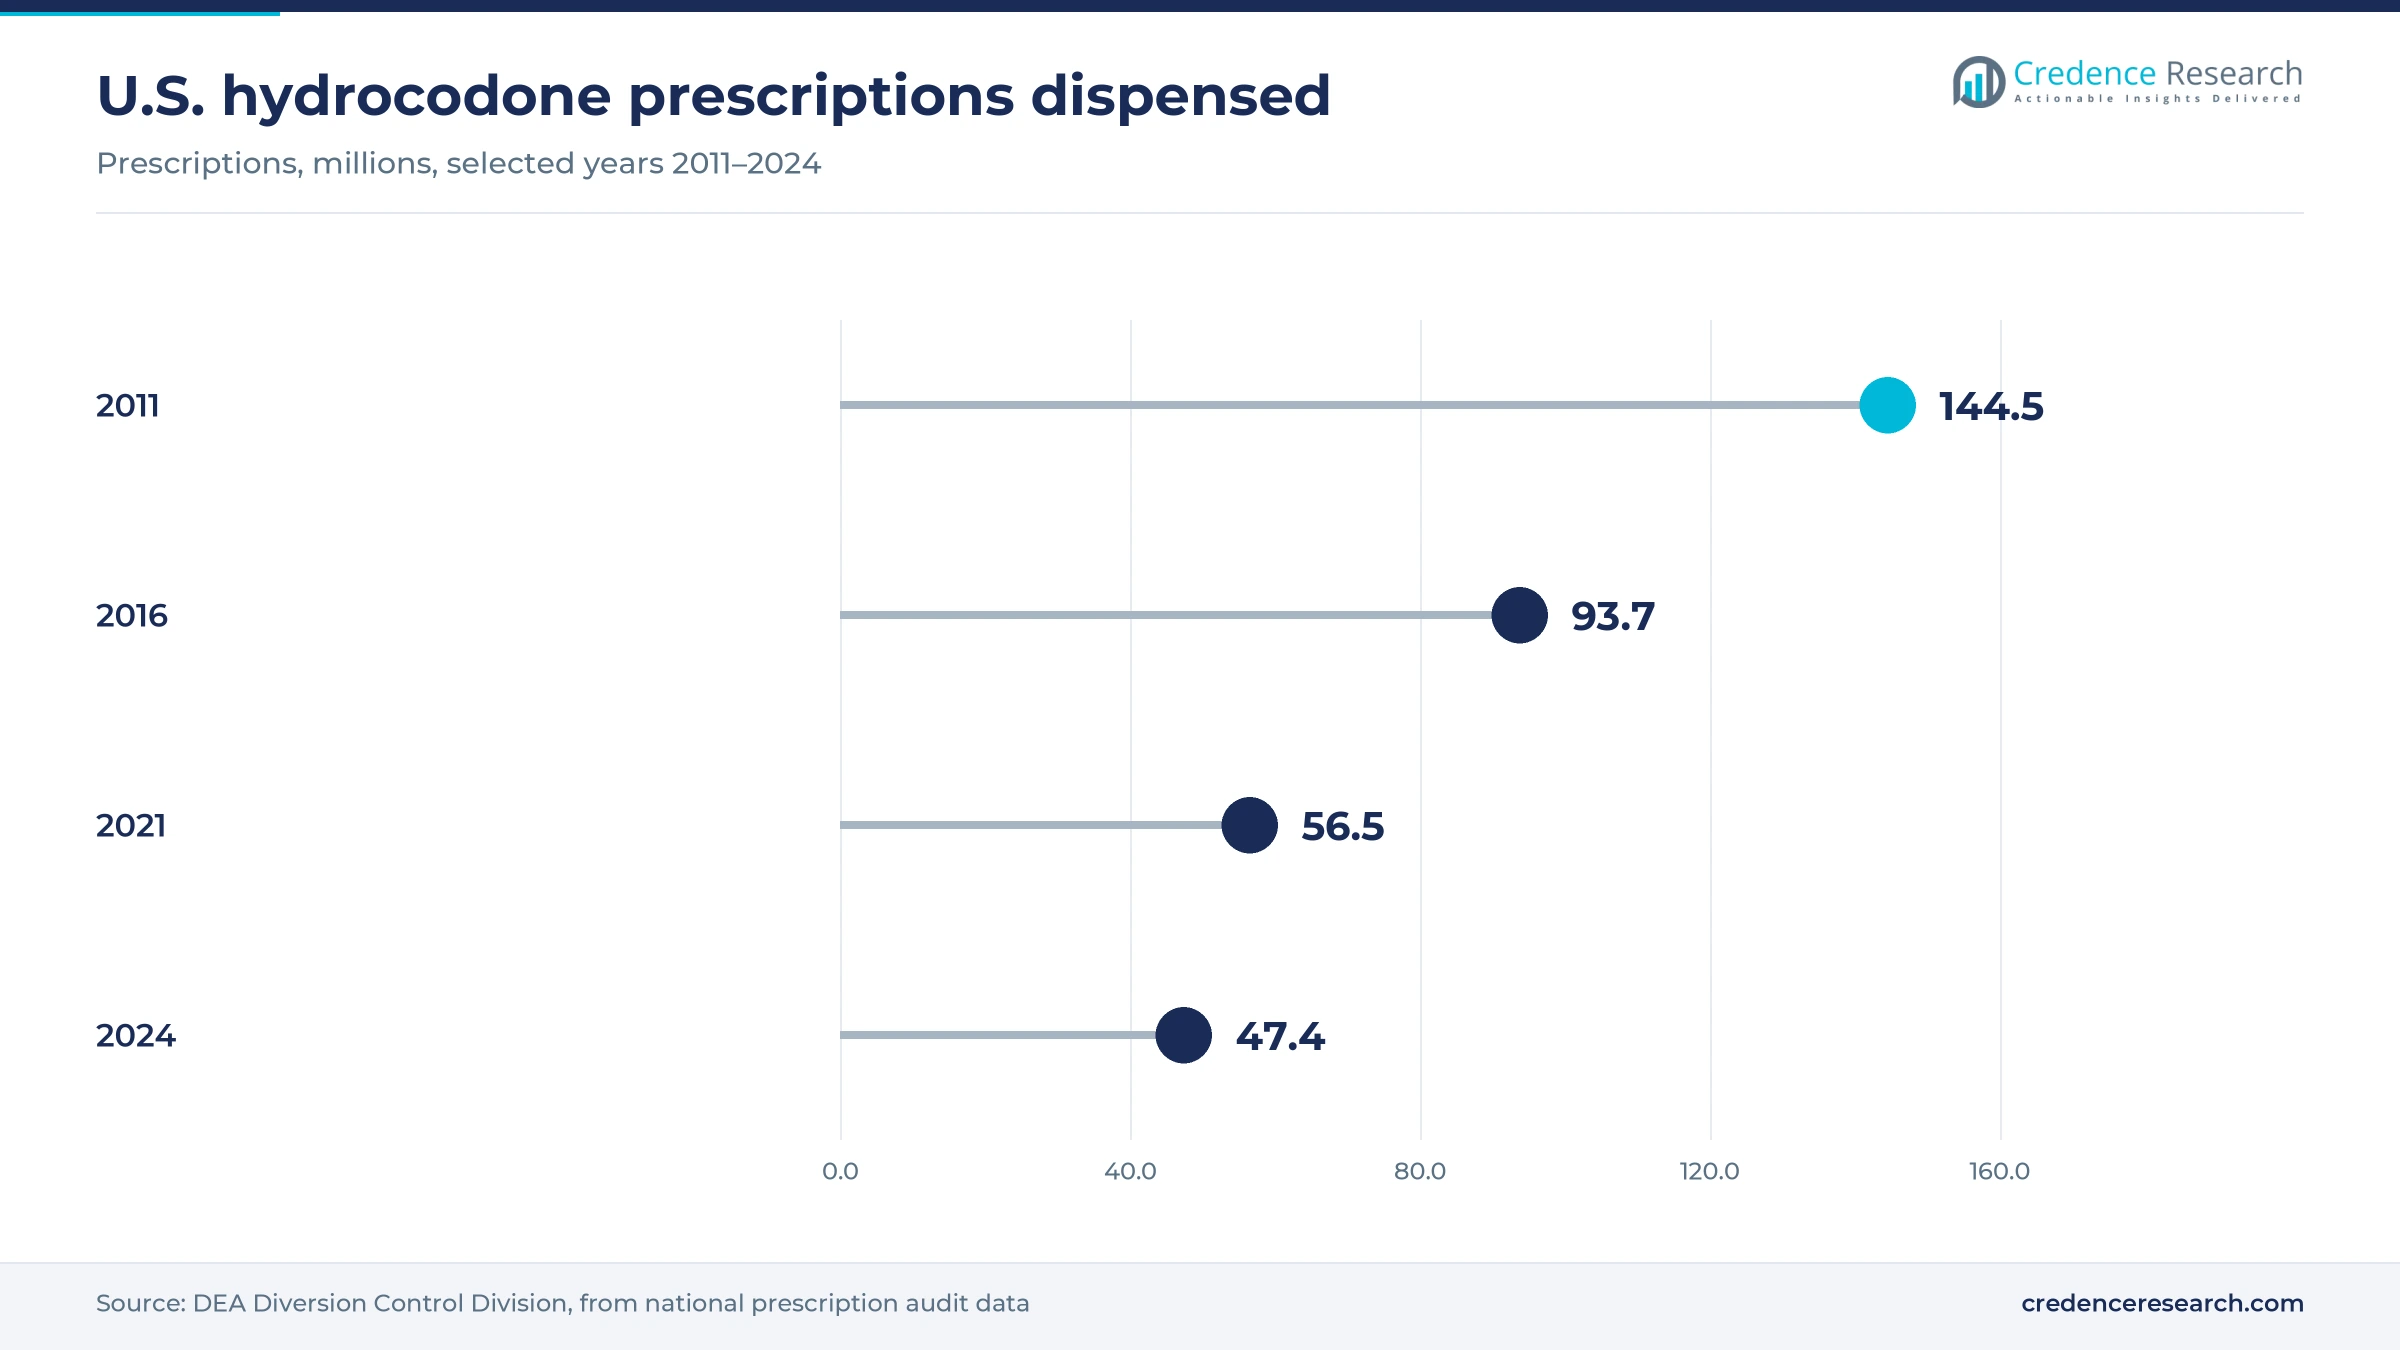
Based on product type, the market is categorized into single-ingredient acetaminophen, other combination products and acetaminophen-opioid combinations. Single-ingredient Acetaminophen led with 58.0% of 2025 value because plain tablets are the default fever and pain choice, and Kenvue said adult Tylenol had gained U.S. pain category share for 13 consecutive quarters by the third quarter of 2025. Other Combination Products grow fastest at 5.1% a year, as Hikma launched Combogesic IV, a fixed-dose infusion of acetaminophen with ibuprofen, in February 2024. Opioid combinations are shrinking, since the DEA counted 47.4 million hydrocodone prescriptions in 2024, against about 144.5 million at the 2011 peak.
Why does oral dosing hold most value?
Based on route of administration, the market is categorized into oral, injectable and others, which covers rectal and other routes. Oral dosing led with 91.0% of 2025 value because tablets, caplets and liquids serve every retail buyer, and the NHS Drug Tariff price of GBP 0.65 for 32 tablets shows how cheaply plain oral doses reach patients. Injectable products grow fastest at 6.2% a year, as CMS gave Combogesic IV the permanent billing code J0138 from Oct. 1, 2024, which eases hospital reimbursement. Hospitals using IV doses to reduce opioid use after surgery drive this gain.
Where do buyers purchase acetaminophen products?
Based on distribution channel, the market is categorized into retail pharmacies and drug stores, hospital pharmacies, e-commerce and others, which includes supermarkets and convenience stores. Retail Pharmacies and Drug Stores led with 50.0% of 2025 value because larger packs stay behind pharmacy rules, and Australia cut supermarket packs from 20 to 16 tablets from Feb. 1, 2025, which moves volume toward pharmacies. E-commerce grows fastest at 7.3% a year, from a small base, although Credence Research found no official global figure for online medicine purchases, which is an evidence gap.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Single-ingredient Acetaminophen | 58.0% | Other Combination Products | 5.1% |
| By Route of Administration | Oral | 91.0% | Injectable | 6.2% |
| By Distribution Channel | Retail Pharmacies and Drug Stores | 50.0% | E-commerce | 7.3% |
Branded caplets cost several times generic tablets
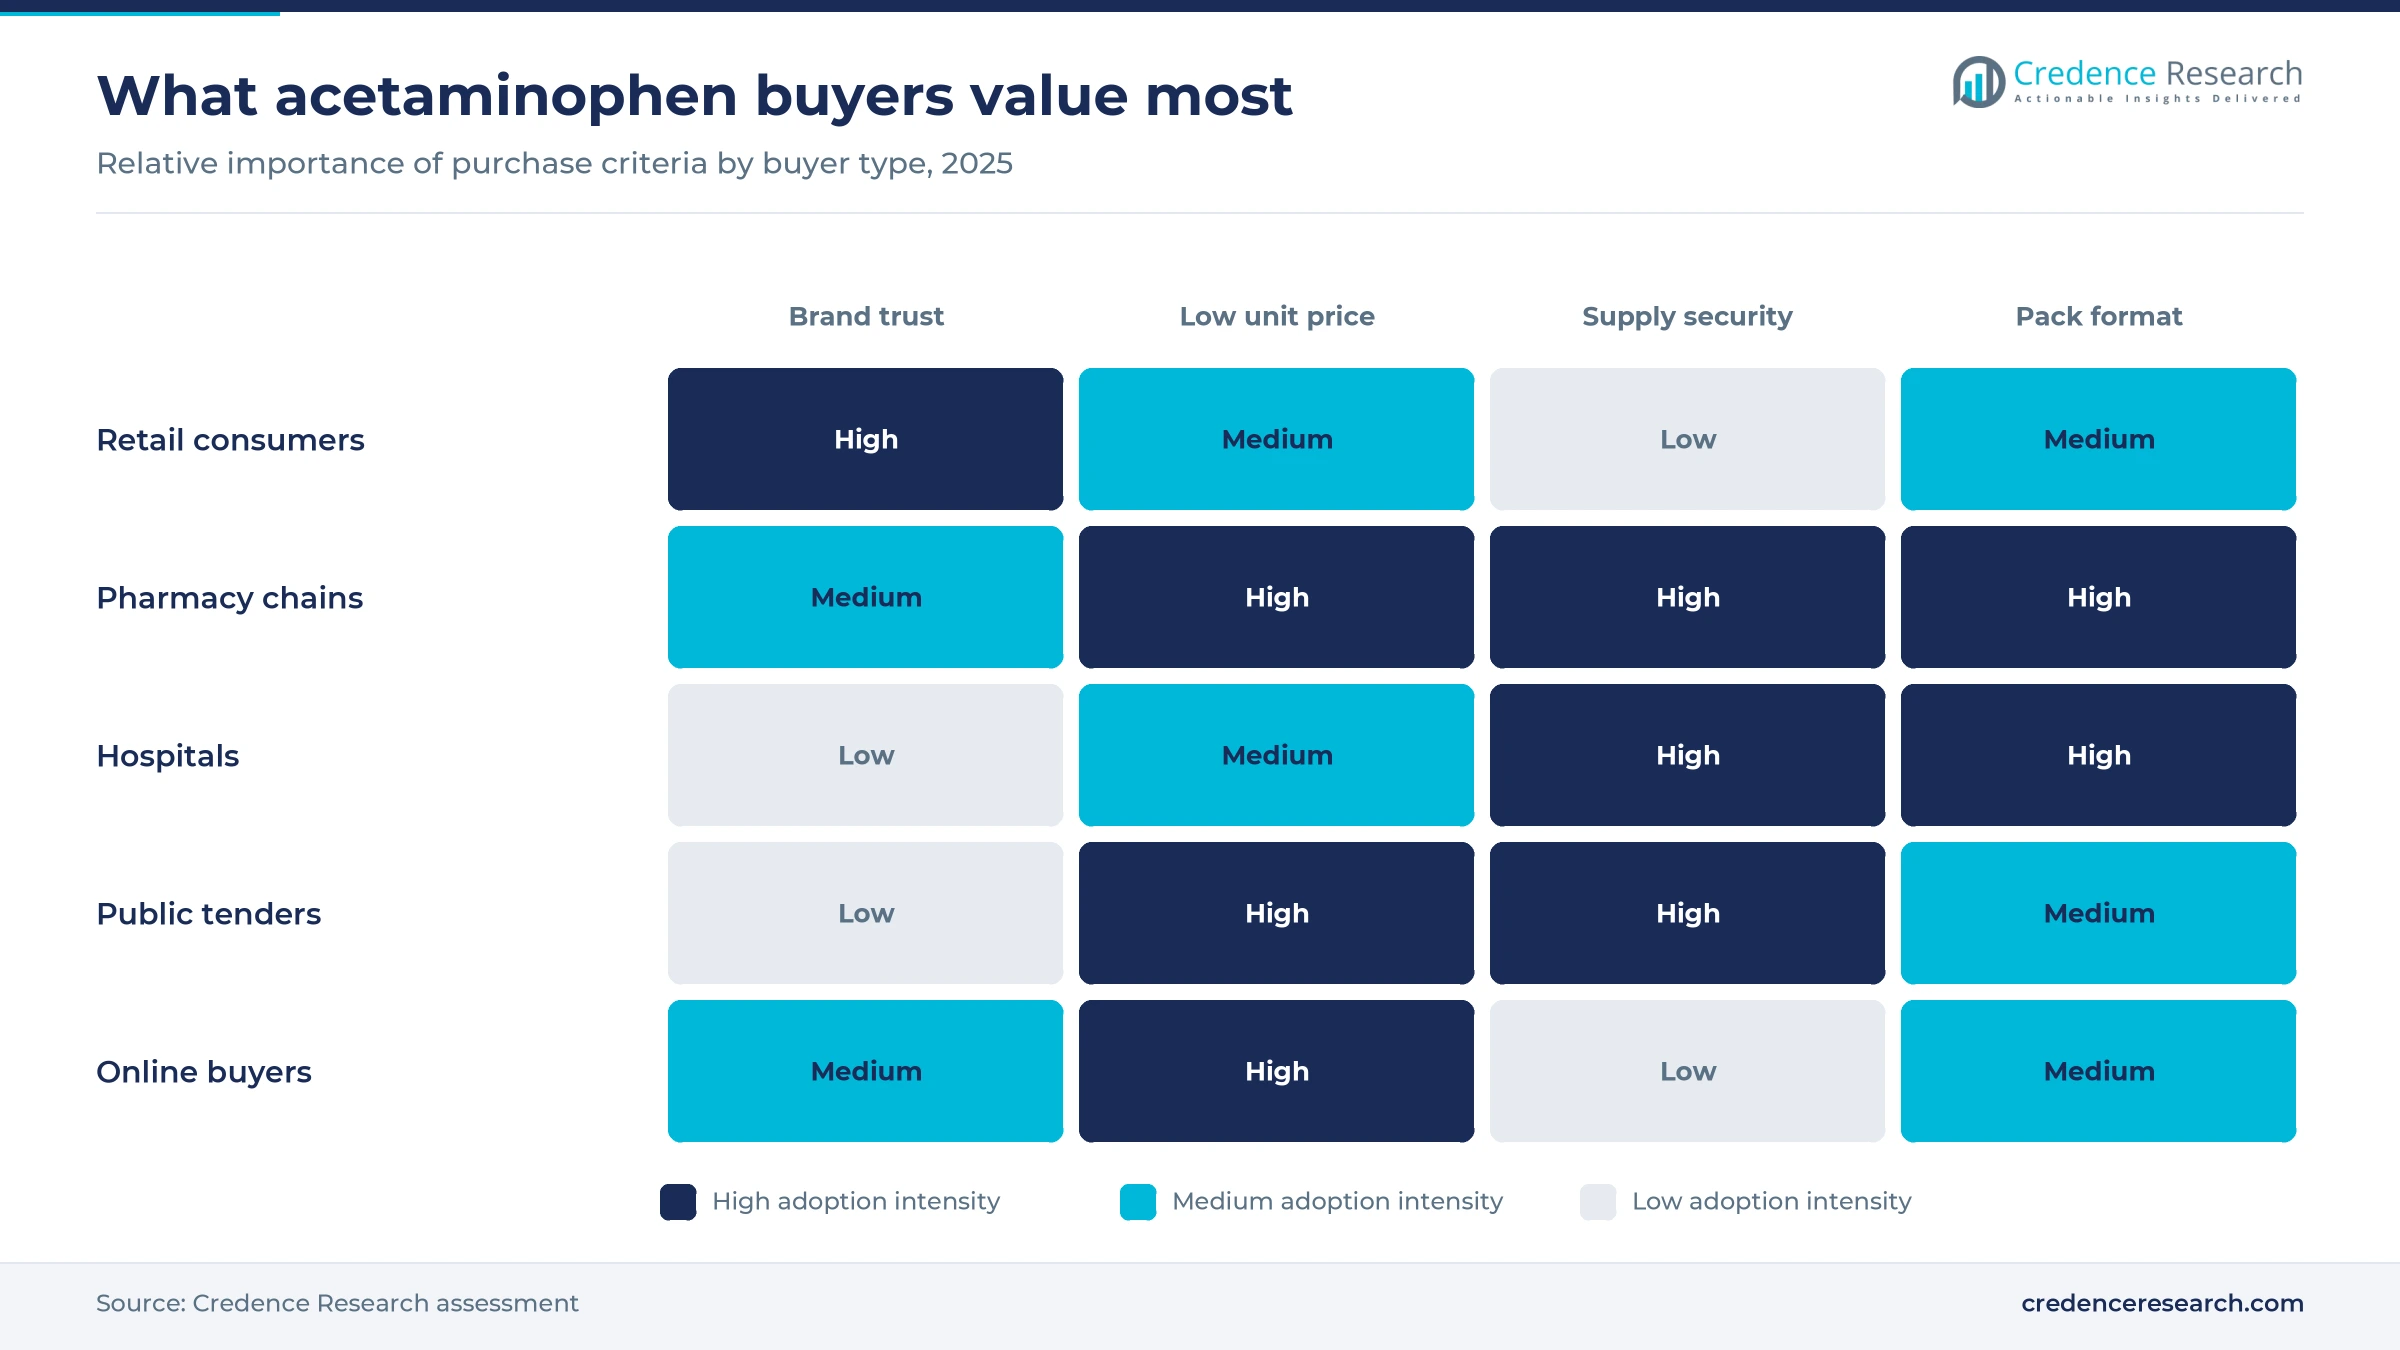
Prices are set per tablet or per dose, and the spread between branded and generic products is large in every major market. A branded U.S. tablet costs about USD 0.11 at retail, while the NHS pays about GBP 0.02 per generic tablet. Ingredient cost matters little to the shelf price, which follows brand trust, pack rules and retailer margins. Ingredient prices still move supplier margins, because dose makers buy on short contracts. Brand owners keep the widest margins, while generic dose makers and ingredient producers absorb price swings.
| Offer or segment | Typical price or fee | Basis |
|---|---|---|
| Tylenol Extra Strength 500 mg coated tablets, 100 count | USD 10.97 per pack | Walmart.com price, sold by Walmart, November 2026 |
| Generic paracetamol 500 mg tablets, 32 count | GBP 0.65 per pack | NHS Drug Tariff, effective July 1, 2025 |
| Paracetamol, phenylephrine and chlorpheniramine 500 mg tablet | Rs 5.15 per tablet | NPPA retail price notice, August 2025 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Joint pain, dengue fever and opioid-sparing surgery lift use
A rising osteoarthritis burden keeps daily pain demand high
Joint pain is the largest repeat use for acetaminophen, because older adults often cannot take NSAIDs for long periods due to stomach and heart risks. A Global Burden of Disease study in The Lancet Rheumatology counted about 595 million people with osteoarthritis in 2020, or 7.6% of the world population, in August 2023. The same study projected knee cases to rise 74.9% and hip cases 78.6% by 2050, which widens the base of daily users. The adult Tylenol share gains noted in the segment analysis show that brand owners capture much of this repeat demand. Makers of plain tablets and extended-release doses gain most, and the overlap with osteoarthritis treatment keeps prescribers recommending them first.
Dengue and seasonal fever outbreaks lift volumes
Fever drives sharp volume peaks, because health agencies tell patients with dengue to avoid NSAIDs that raise bleeding risk. The WHO recorded about 14.6 million dengue cases and more than 12,000 deaths in 2024, and the Americas reported more than 13 million of those cases. WHO names paracetamol as the recommended pain reliever for the disease, which has no specific cure, so it anchors standard dengue fever treatment. Haleon said in its 2025 full-year results that a weak cold and flu season cut its full-year organic growth by about 40 basis points, which shows how closely sales follow fever seasons. Generic makers in Latin America and South Asia gain most in outbreak years.
Hospitals use IV doses to cut opioid use after surgery
Hospitals are using acetaminophen as a base layer of pain control so that patients need fewer opioids after surgery. Vertex said in January 2025 that about 80 million Americans are prescribed medicine for moderate to severe acute pain each year, and about 40 million of those prescriptions are opioids. B. Braun received FDA approval in February 2021 for multiple-dose acetaminophen injection in PAB bags, while Fresenius Kabi sells ready-to-use freeflex bags. Hikma secured the permanent CMS code J0138 for Combogesic IV, effective Oct. 1, 2024, which simplifies billing. Makers of sterile injectables gain most, because each IV dose is worth many times an oral tablet.
Cheaper generic supply widens access in Asia
Low ingredient costs let generic makers sell acetaminophen at very low prices across Asia, which keeps volumes rising in price-sensitive markets. In India, the 650-milligram paracetamol tablet segment alone was worth Rs 624.2 crore in the 12 months to July 2025, according to industry data reported by Medical Dialogues. Micro Labs' Dolo-650 held about half of that segment, and it ranked as the most prescribed brand in India, with 0.66% of prescriptions from November 2024 to February 2025. With unit prices this low, volume tracks fever and pain episodes more closely than household income. Local brands with wide pharmacy reach gain the most from this cost base.
Brand owners consolidate as regulators cut pack sizes
Consumer health owners are consolidating the top brands
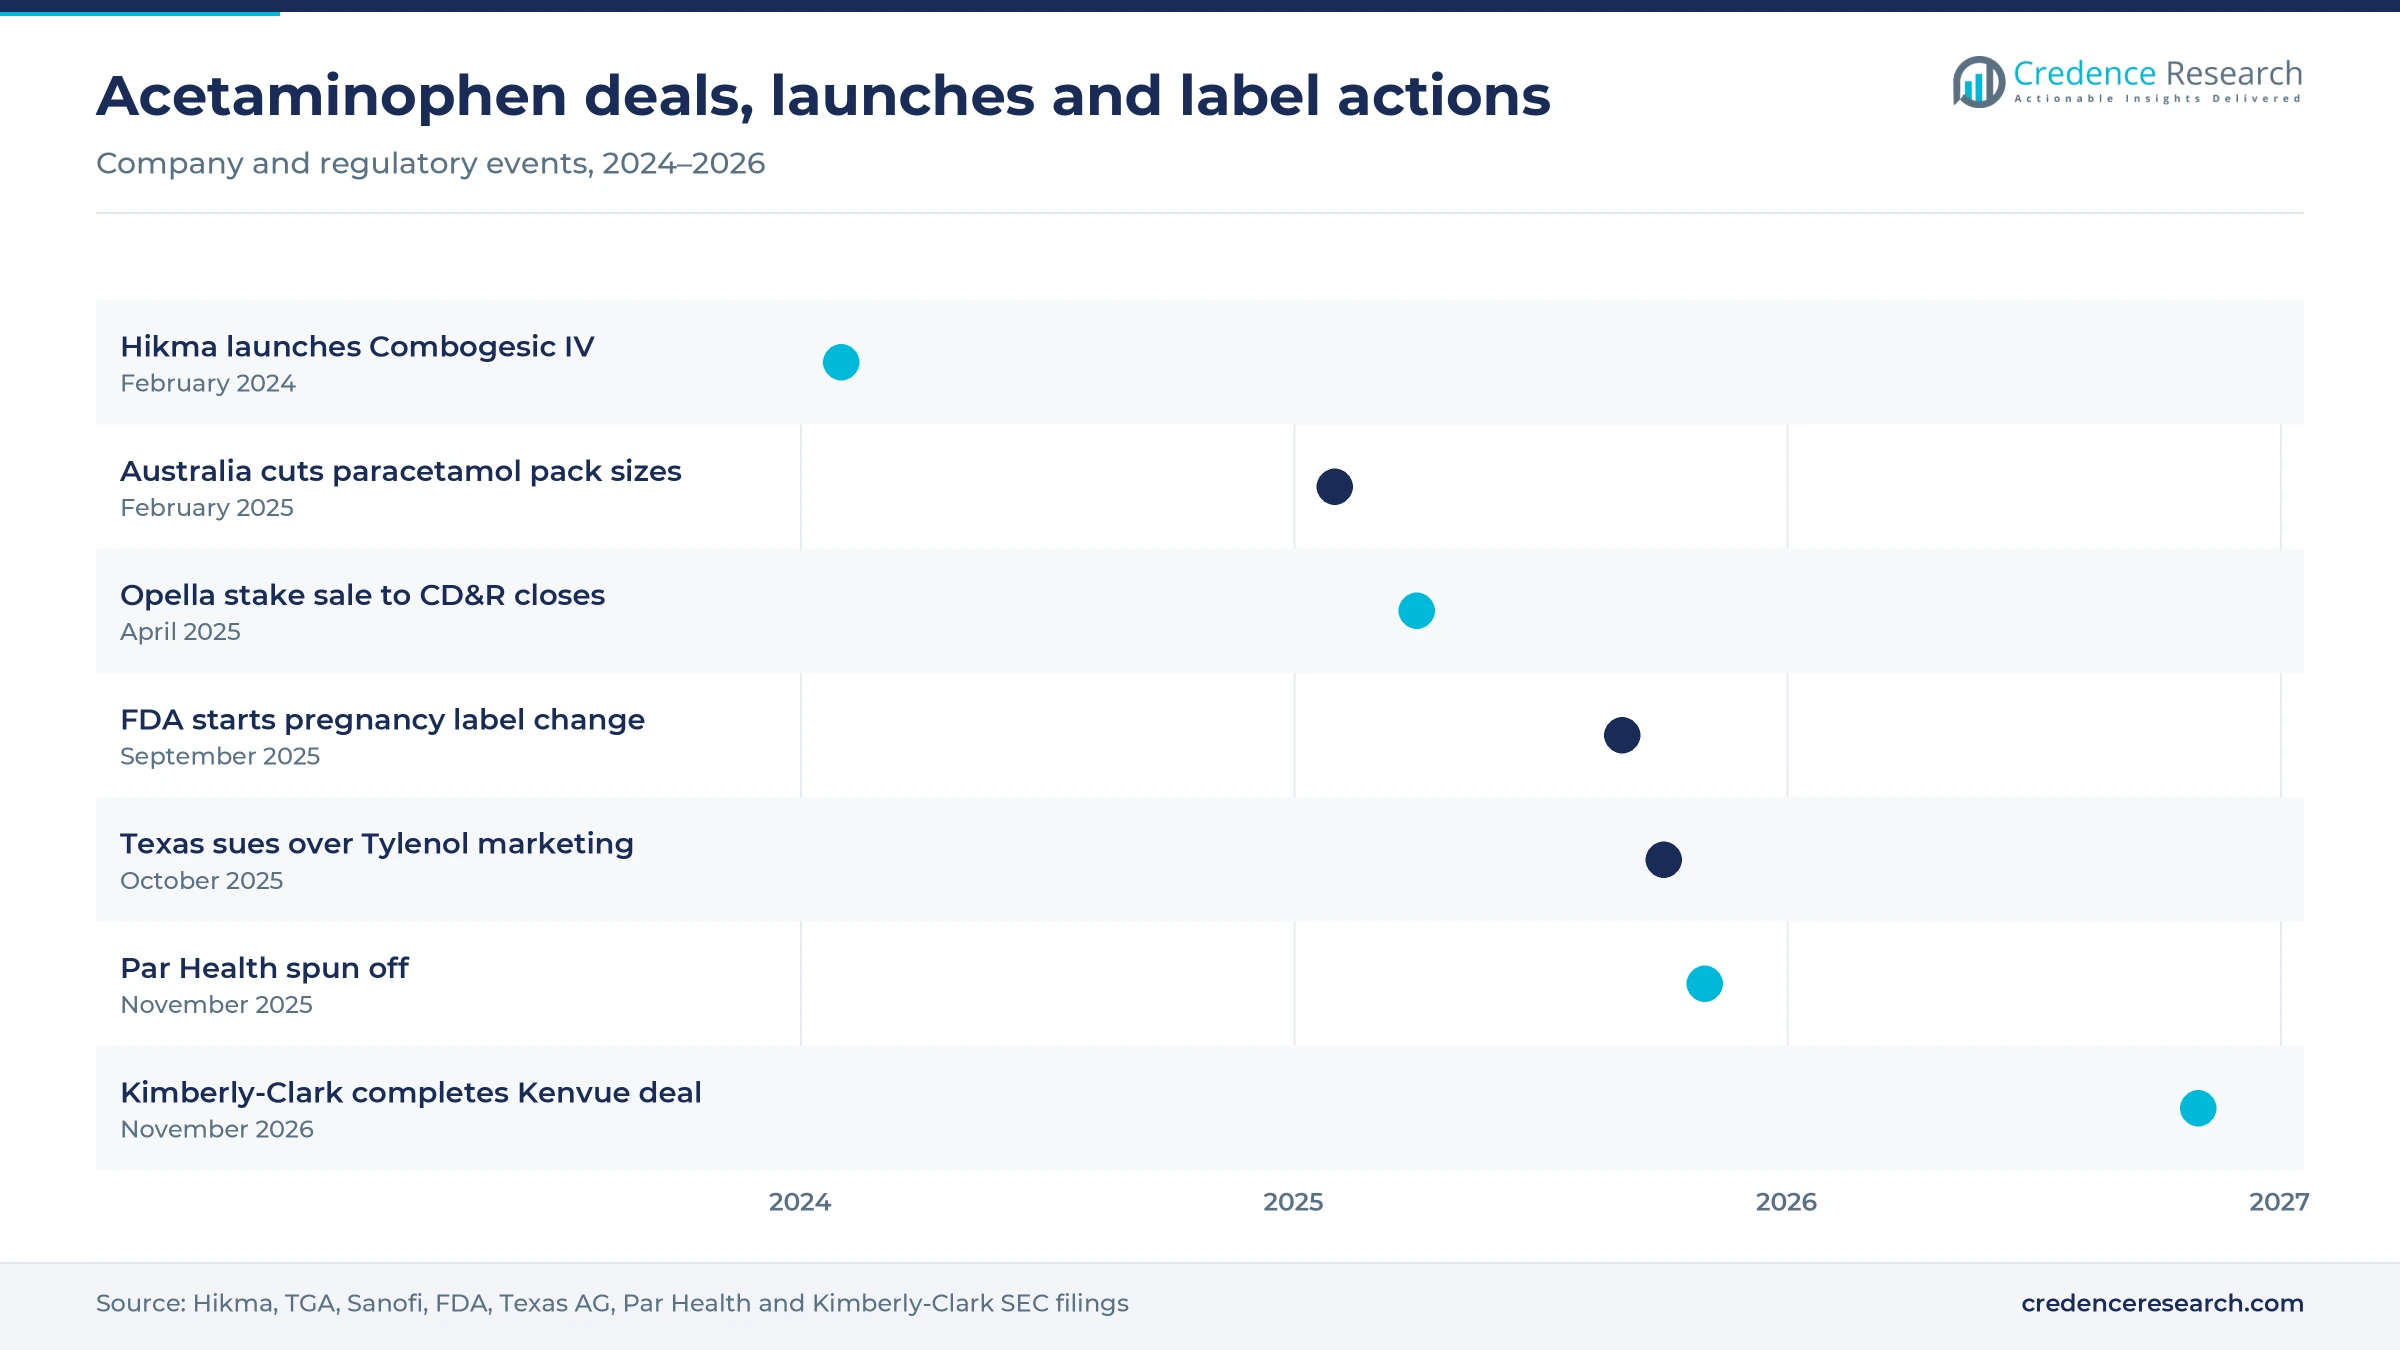
Large consumer and investment groups are shifting toward control of the main acetaminophen brands to gain scale in pharmacy and grocery distribution, creating openings for wider ranges across pain, cold and children's products. Sanofi and CD&R closed the Opella deal on April 30, 2025, leaving CD&R with 50.0%, Sanofi with 48.2% and Bpifrance with 1.8% of the owner of Doliprane. Kimberly-Clark completed its acquisition of Kenvue, the owner of Tylenol, on Nov. 2, 2026, according to its quarterly filing with the SEC. On the supply side, Par Health, which makes bulk acetaminophen in the U.S., was spun off from Mallinckrodt on Nov. 10, 2025. New owners are likely to push cost savings and portfolio pruning, so smaller brands face tougher shelf competition.
Regulators are shifting packs toward pharmacy control
Medicine regulators are shifting acetaminophen toward smaller packs and tighter dose limits to address overdose and liver injury, creating openings for pharmacy-only and blister-packed formats. Australia's TGA cut general sale packs from 20 to 16 tablets and pharmacy self-selection packs from 100 to 50 from Feb. 1, 2025, and made blister packs mandatory for some products. The TGA cited about 225 hospital admissions a year for paracetamol liver injury and about 50 deaths a year from intentional self-poisoning. In the U.S., the FDA capped prescription products at 325 milligrams per dose unit and added a boxed liver warning. Pharmacy chains gain, while grocery and convenience sellers lose some volume.
Fixed-dose IV combinations are an opening for opioid-free surgery
Surgical teams that want to avoid opioids are an underserved customer group for fixed-dose combinations that pair acetaminophen with an NSAID in one bag. Combogesic IV, approved by the FDA in October 2023 and launched by Hikma in February 2024, delivers 1,000 milligrams of acetaminophen and 300 milligrams of ibuprofen in a 15-minute infusion. AFT Pharmaceuticals licensed U.S. rights to Hikma in 2021, showing a route for originators without a U.S. hospital sales force. Vertex lists Journavx, a new non-opioid tablet, at USD 15.50 per pill, which leaves room for cheaper combinations beside intravenous ibuprofen. Hospitals can cut opioid doses per patient, while makers gain a higher-value product than generic bags.
Small packs are an opening in low-income Asian markets
Low-income households in Southeast Asia and South Asia are an underserved group, because they buy medicines a few tablets at a time rather than in large packs. Haleon said it launched a new four-tablet pack of Panadol in Indonesia in 2025 to bring in new consumers, and that this pack size accounts for about 65% of category volume there. Haleon also reported 5.2% organic growth in Asia Pacific in 2025, against a fall of 0.4% in North America. India's NPPA fixes retail prices for paracetamol cold blends, such as Rs 5.15 per 500-milligram tablet in August 2025. Brands that price by the strip and sell through small pharmacies can take share in over-the-counter drugs across these markets.
Pregnancy label, liver risk and opioid decline weigh
A U.S. pregnancy label change raises legal risk
The FDA began a label change process on Sept. 22, 2025, to note a possible link between acetaminophen use in pregnancy and autism, while stating that causation has not been established. Texas sued Johnson & Johnson and Kenvue over Tylenol marketing on Oct. 28, 2025. The European Medicines Agency said in September 2025 that its pregnancy advice remains unchanged. U.S. brand owners face the most exposure, because lawsuits and label wording can shift pregnant buyers and raise defense costs.
Liver injury keeps dose rules and warnings tight
Acetaminophen was the leading cause of acute liver failure in the U.S. between 1998 and 2003, and 48% of 275 such cases followed accidental overdose, according to the FDA. That record led to the prescription dose cap and boxed warnings noted above, and similar concerns drove Australia's pack cuts. Makers of high-strength and combination products are most exposed, because each new safety review can force reformulation, relabeling or smaller packs.
Falling opioid prescribing shrinks combination sales
U.S. opioid dispensing fell from 46.8 prescriptions per 100 persons in 2019 to 35.4 in 2024, according to the CDC dispensing rate data. Hydrocodone combinations moved to Schedule II on Oct. 6, 2014, which placed them under the strictest controls for approved medicines. Generic makers of hydrocodone and oxycodone combinations are most exposed, along with bulk suppliers whose volumes depend on them, while non-opioid options such as Journavx add pressure.
Volatile ingredient prices squeeze non-integrated makers
Many acetaminophen makers outside China buy para-aminophenol rather than make it, so swings in the starting material price pass straight into their costs. India's health minister inaugurated Sadhana Nitro Chem's para-aminophenol plant under the production linked incentive scheme only in March 2024, after the pandemic exposed dependence on imported bulk drugs. Producers in India, Europe and the U.S. without para-aminophenol plants are most exposed, and no official source publishes global capacity, which is an evidence gap for buyers.
North America leads on brands while Asia adds volume
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 3.95 | 39.5% | 4.0% |
| Europe | 2.95 | 29.5% | 3.5% |
| Asia Pacific | 2.28 | 22.8% | 5.8% |
| Latin America | 0.46 | 4.6% | 5.0% |
| Middle East & Africa | 0.36 | 3.6% | 4.9% |
North America leads on brand prices and hospital use
North America held 39.5% of 2025 acetaminophen value and grows at 4.0% a year. The region leads because branded caplets sell at high per-tablet prices, prescription opioid combinations remain a sizable business and hospitals buy IV bags in volume. Perrigo supplies store-brand tablets, which hold the low end of the shelf. Growth is slower than the market because opioid dispensing keeps falling and the pregnancy label case adds legal cost. Par Health's U.S. bulk supply gives buyers a domestic ingredient source.
Europe has high volume at low generic prices
Europe held 29.5% of 2025 acetaminophen value and grows at 3.5% a year, the slowest regional rate. Volumes are large, and France is home to Opella's Doliprane brand, but generic prices are very low, as the NHS Drug Tariff price of GBP 0.65 for 32 tablets shows. The EMA kept its pregnancy advice unchanged in September 2025, which spares European brands the U.S. label risk. Opella and Haleon are the main brand owners, while low reimbursed prices for generics cap the value per purchase.
Asia Pacific grows fastest on low-cost generic volume
Asia Pacific held 22.8% of 2025 acetaminophen value and grows fastest at 5.8% a year. Growth comes from India, China and Southeast Asia, where low-cost tablets reach more buyers through small pharmacies. India makes both the starting material and the finished dose, with Granules India and Micro Labs among the leading producers. Chinese producers remain a major ingredient source for dose makers across the region. Australia's smaller packs from February 2025 cut value per sale, which partly offsets the regional gain.
Latin America volumes follow dengue seasons
Latin America held 4.6% of 2025 acetaminophen value and grows at 5.0% a year. Demand swings with dengue, because the Americas reported more than 13 million cases in 2024 and doctors avoid NSAIDs for the disease. Brazil and Mexico are the largest markets, served by global brands and local generic makers. Credence Research found no regional sales statistics for acetaminophen, so this estimate rests on prices and fever burden, which is an evidence gap for buyers sizing the region.
Middle East and Africa remains a low-price generic market
Middle East & Africa held 3.6% of 2025 acetaminophen value and grows at 4.9% a year. Gulf pharmacies sell imported branded and generic tablets, while much of Africa relies on low-priced generic tablets from Indian makers. Credence Research found no public sales data for the region, so the estimate rests on import prices and population, which is a clear evidence gap. Makers with local registration and distributor networks are best placed to win public tenders.
Deals, launches and label actions from 2024 to 2026
| Development | Status and market relevance |
|---|---|
| In February 2024, Hikma launched Combogesic IV in the U.S., a fixed-dose infusion of acetaminophen and ibuprofen licensed from AFT Pharmaceuticals. | Commercial launch; a permanent CMS billing code followed from Oct. 1, 2024. |
| In April 2025, Sanofi and CD&R closed the sale of a 50.0% controlling stake in Opella, the owner of Doliprane. | Completed transaction; Sanofi keeps 48.2% and Bpifrance 1.8%. |
| In September 2025, the FDA began a label change process for acetaminophen products about use in pregnancy. | Regulatory process under way; the agency stated that causation has not been established. |
| In November 2025, Par Health, a U.S. maker of bulk acetaminophen and generic medicines, was spun off from Mallinckrodt. | Completed separation; the business combines Mallinckrodt and Endo generics and ingredient units. |
| In November 2026, Kimberly-Clark completed its acquisition of Kenvue, the owner of Tylenol. | Completed acquisition after shareholder approval in January 2026 and antitrust clearance in February 2026. |
Dose caps, IV bags and blister packs shape products
- The 325-milligram cap limits each prescription dose unit in the U.S., so opioid combinations use more tablets of lower strength.
- Ready-to-use IV bags such as B. Braun PAB and Fresenius Kabi freeflex containers remove mixing steps and suit operating rooms.
- Fixed-dose IV combinations deliver acetaminophen and ibuprofen in one infusion, which reduces the number of drugs a nurse must prepare.
- Blister packaging rules in Australia make tablets harder to stockpile, which changes pack design and line costs for suppliers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Brand trust, low-cost API and hospital contracts compete
Competition splits into brand owners, generic dose makers, sterile injectable suppliers and ingredient producers. Kimberly-Clark, through Kenvue, owns Tylenol, while Haleon sells Panadol and Opella sells Doliprane, and Reckitt sells paracetamol cold and flu remedies. Perrigo competes with store-brand tablets sold under retailer names in North American pharmacies. In India, Micro Labs leads the 650-milligram segment with Dolo-650, and Granules India supplies the ingredient and finished doses. B. Braun, Fresenius Kabi and Hikma compete for hospital IV contracts, with AFT Pharmaceuticals licensing its combination. Par Health makes bulk acetaminophen in the U.S. Brand owners win through trust and shelf space, generic makers through cost and registrations, and IV suppliers through supply reliability. Buyers should weigh supply security as heavily as unit price, given ingredient concentration in Asia, which also affects opioid drug combination makers.
Brand owners hold the margin over a commodity ingredient
Supply has three layers, with para-aminophenol and ingredient makers concentrated in China and India, many generic dose makers worldwide and a few brand owners, led by Kenvue, Haleon and Opella, that hold the main consumer names. Entry barriers are low for generic tablets but high for sterile IV production and for brands that need decades of trust. Margins sit mostly with brand owners and sterile injectable makers, while ingredient producers compete on cost and scale.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Kimberly-Clark Corporation (Kenvue) | Brand owner | Tylenol adult and children's acetaminophen tablets, caplets and liquids |
| Haleon plc | Brand owner | Panadol acetaminophen tablets and combination pain products worldwide |
| Opella | Brand owner | Doliprane acetaminophen tablets, sachets and syrups, led by France |
| Perrigo Company plc | Store-brand supplier | Retailer own-label acetaminophen tablets and caplets in North America |
| Reckitt Benckiser Group plc | Brand owner | Paracetamol-based cold and flu remedies in Europe and other markets |
| Micro Labs Limited | Generic brand owner | Dolo-650 paracetamol tablets, the leading 650 mg brand in India |
| Granules India Limited | Ingredient and dose maker | Paracetamol ingredient and finished doses from Indian plants |
| Par Health, Inc. | Ingredient supplier | Bulk acetaminophen ingredient and generic medicines made in the U.S. |
| B. Braun SE | Sterile injectables maker | Acetaminophen injection in multiple doses in PAB IV bags |
| Fresenius Kabi AG | Sterile injectables maker | Acetaminophen injection in ready-to-use freeflex bags for hospitals |
| Hikma Pharmaceuticals PLC | Hospital supplier | Combogesic IV acetaminophen and ibuprofen infusion in the U.S. |
| AFT Pharmaceuticals Limited | Originator and licensor | Maxigesic and Combogesic acetaminophen and ibuprofen combinations |
Volume holds firm while the value mix moves
Credence Research's view is that acetaminophen volumes will stay firm because no cheaper option exists for fever and everyday pain, but the value mix is moving. Single-ingredient Acetaminophen keeps 58.0% of 2025 value, while opioid combinations shrink and IV formats and fixed-dose blends add value. The new owners of Tylenol and Doliprane will push scale, which raises the bar for smaller brands. Generic makers with their own starting material are best placed to hold margins when ingredient prices swing.
Estimates rest on regulator data, filings and prices
The report uses 2025 as the base year and forecasts to 2035. The earlier Credence Research estimate was brought forward to 2025 with its own growth rate and checked against a top-down build from list prices, prescription counts and regional fever and pain burden, which supported it. All segment and regional splits shown here are Credence Research estimates. Sources include regulator documents, health statistics, company filings and releases, official price lists and peer-reviewed studies; no interviews or surveys are claimed.
Asia Pacific and IV formats carry growth to 2035
Injectable products should grow at 6.2% a year to 2035, the fastest route, while plain oral tablets remain the core of value. The market should reach USD 15.29 billion by 2035, with North America the largest region and Asia Pacific adding the most new volume. Results through 2027 depend on the U.S. pregnancy label case, the pace of opioid decline and the plans of the new owners of Tylenol and Doliprane. These projections are modeled estimates and would shift with regulatory and legal outcomes.
Opioid decline and label outcomes set the range
The range depends mainly on how fast opioid combinations fall, how U.S. pregnancy litigation develops and how quickly Asian volume grows. Faster decline in opioid combinations and court losses for brand owners would push buyers toward cheaper generics, while hospital uptake of IV combinations and strong fever seasons would lift value. Ingredient price swings mainly move margins rather than the market total.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 3.0% | USD 13.66 billion | U.S. litigation hits brand sales and opioid combinations fall faster than expected |
| Base | 4.33% | USD 15.29 billion | Steady fever and joint pain demand with gradual decline in opioid combinations |
| Upside | 5.3% | USD 16.66 billion | Fast IV combination uptake in hospitals and strong generic volume growth in Asia |
Frequently Asked Questions
How big is the acetaminophen market?
How is the acetaminophen opioid combination segment changing?
What is the Tylenol market share position in the U.S.?
Who are the leading acetaminophen manufacturers?
What is the acetaminophen price trend?
How does the FDA pregnancy label change affect the market?
Which product type leads the market?
Which region leads the acetaminophen market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Single-ingredient Acetaminophen
- 1.2.2 Other Combination Products
- 1.2.3 Acetaminophen-Opioid Combinations
- 1.3 By Route of Administration
- 1.3.1 Oral
- 1.3.2 Injectable
- 1.3.3 Others (Rectal and Other Routes)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 10.01 billion → 2035: USD 15.29 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Acetaminophen Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Acetaminophen Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Acetaminophen Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Acetaminophen Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Acetaminophen Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Acetaminophen Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Acetaminophen Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Acetaminophen Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 10.01 billion → 2035: USD 15.29 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Acetaminophen Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Single-ingredient Acetaminophen
- 12.3.7.2 Other Combination Products
- 12.3.7.3 Acetaminophen-Opioid Combinations
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Route of Administration - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Oral
- 12.4.7.2 Injectable
- 12.4.7.3 Others (Rectal and Other Routes)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Acetaminophen Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2035
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Acetaminophen Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Acetaminophen Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Kimberly-Clark Corporation (Kenvue)
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Haleon plc
- 17.4 Opella
- 17.5 Perrigo Company plc
- 17.6 Reckitt Benckiser Group plc
- 17.7 Micro Labs Limited
- 17.8 Granules India Limited
- 17.9 Par Health, Inc.
- 17.10 B. Braun SE
- 17.11 Fresenius Kabi AG
- 17.12 Hikma Pharmaceuticals PLC
- 17.13 AFT Pharmaceuticals Limited
- 17.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

