
Market Overview
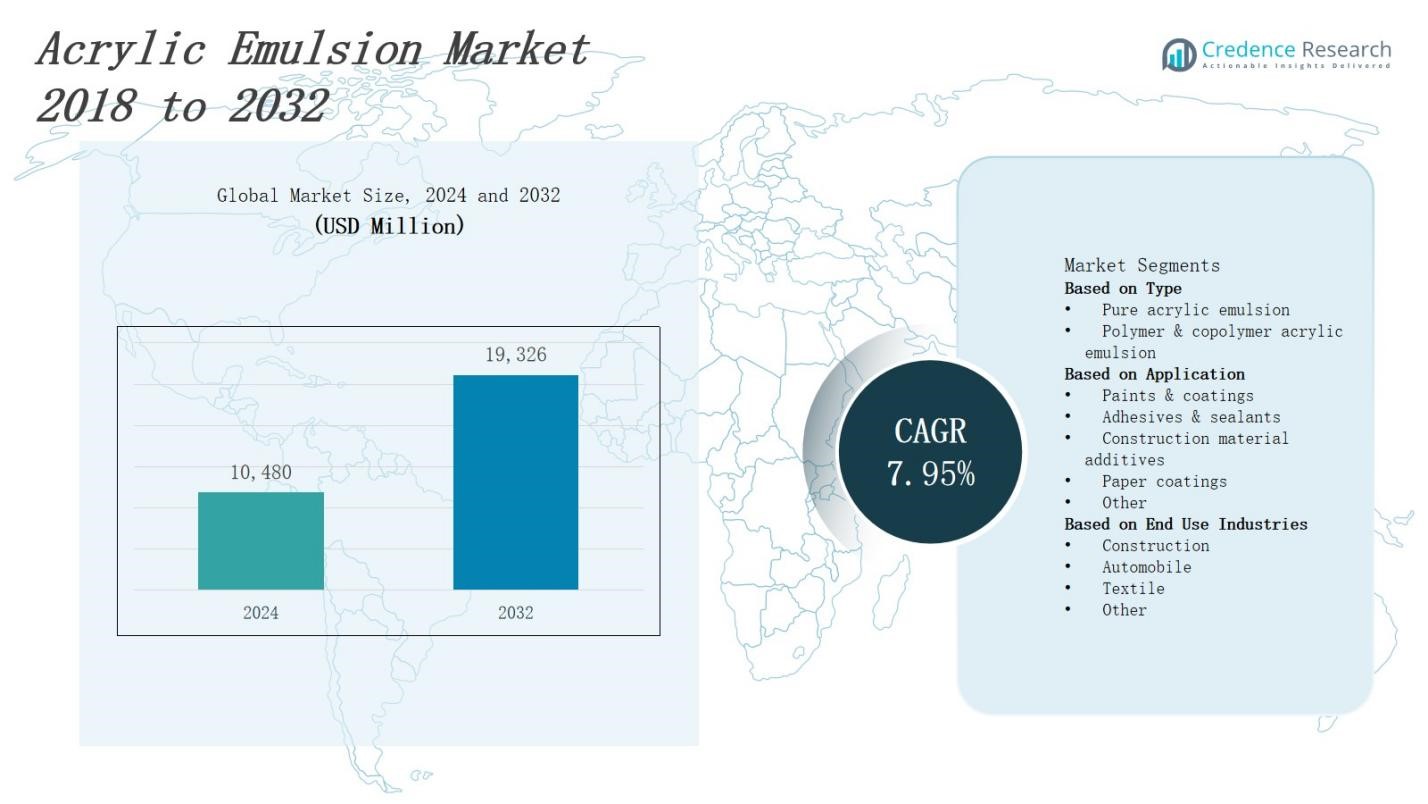
The acrylic emulsion market is projected to grow from USD 10,480 million in 2024 to USD 19,326 million by 2032, expanding at a CAGR of 7.95%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Acrylic Emulsion Market Size 2024 | USD 10,480 Million |
| Acrylic Emulsion Market, CAGR | 7.95% |
| Acrylic Emulsion Market Size 2032 | USD 19,326 Million |
The acrylic emulsion market grows driven by rising demand for high-performance coatings in construction, automotive, and packaging industries. Manufacturers leverage its excellent adhesion, weather resistance, and flexibility to meet stringent regulatory standards. Increasing urbanization and infrastructure development boost the need for durable, eco-friendly paints and adhesives. Technological advancements enhance product formulations, improving application efficiency and environmental safety. Growing consumer preference for sustainable and low-VOC solutions further accelerates adoption. These factors collectively stimulate innovation and expand the market, positioning acrylic emulsions as essential materials across diverse industrial applications throughout the forecast period.
The acrylic emulsion market spans key regions including North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Asia Pacific leads due to rapid urbanization and industrial growth, followed by North America and Europe, driven by stringent environmental regulations and advanced manufacturing. Latin America and the Middle East & Africa present moderate growth opportunities supported by expanding construction and industrial activities. Leading players such as Arkema Group, BASF, Dow Inc, Covestro, Henkel Additives, and Avery Dennison Performance Polymers dominate the market with strong regional presence and continuous innovation.
Market Insights
- The acrylic emulsion market is projected to grow from USD 10,480 million in 2024 to USD 19,326 million by 2032, expanding at a CAGR of 7.95%.
- Rising demand in construction, automotive, and packaging industries drives growth due to superior adhesion, weather resistance, and flexibility of acrylic emulsions.
- Strict environmental regulations encourage shift to low-VOC, eco-friendly formulations, increasing adoption of water-based acrylic emulsions globally.
- Technological advancements enhance durability, chemical resistance, and multifunctionality, supporting wider use in coatings, textiles, and paper applications.
- Asia Pacific leads with a 35% market share fueled by rapid urbanization and infrastructure growth, followed by North America (30%) and Europe (25%) with strong regulatory frameworks.
- Market challenges include volatile raw material prices, supply chain disruptions, and stringent regulatory compliance that demand continuous product reformulation and R&D investment.
- Latin America (6%) and Middle East & Africa (4%) offer moderate growth opportunities driven by expanding construction, automotive sectors, and infrastructure development.
Market Drivers
Rising Demand in Construction and Automotive Sectors
The acrylic emulsion market experiences strong growth driven by increasing demand from the construction and automotive industries. It offers superior adhesion, flexibility, and weather resistance, making it ideal for exterior and interior coatings. Growing urbanization and infrastructure projects boost the need for durable and protective coatings. Automotive manufacturers adopt acrylic emulsions to enhance vehicle aesthetics and corrosion resistance. These applications drive consistent consumption, reinforcing the market’s expansion globally. Manufacturers focus on tailoring products to meet industry-specific requirements.
- For instance, Lubrizol announced an expansion of its acrylic emulsion manufacturing capacity in Kentucky to meet the increasing demand in North America’s construction and industrial coatings markets.
Environmental Regulations and Sustainable Solutions
Stringent environmental regulations encourage the acrylic emulsion market to shift toward low-VOC and eco-friendly formulations. It provides an effective alternative to solvent-based coatings, reducing harmful emissions. Increasing awareness of environmental impact among end users accelerates the adoption of water-based acrylic emulsions. Manufacturers invest in research to improve biodegradability and compliance with regulatory standards. These efforts help meet the rising demand for sustainable products while maintaining high performance. The market benefits from growing emphasis on green building certifications worldwide.
- For instance, Benjamin Moore’s Natura line offers zero-VOC acrylic paints with excellent opacity and a variety of colors, ensuring environmental safety without compromising quality.
Technological Advancements Enhancing Product Performance
The acrylic emulsion market benefits from continuous innovation focused on improving product characteristics and application methods. Advances in polymerization techniques enhance durability, adhesion, and chemical resistance. It enables development of multifunctional coatings suited for diverse substrates and environmental conditions. Automation and smart manufacturing processes improve consistency and reduce production costs. Manufacturers integrate nanotechnology and additives to boost functionality. This technological progress supports broader adoption in sectors like packaging, textiles, and paper, strengthening market growth.
Expanding Applications Across Industries
The acrylic emulsion market finds increasing applications beyond traditional coatings, including adhesives, textiles, and packaging. It meets demand for flexible, durable, and water-resistant materials in various end uses. Growth in consumer goods and packaging sectors fuels demand for customizable and cost-effective solutions. The market responds by developing specialty emulsions tailored for specific performance requirements. Growing industrialization and rising disposable incomes in emerging economies further drive consumption. This diversification enhances market resilience and opens new revenue streams.
Market Trends
Increasing Adoption of Sustainable and Low-VOC Acrylic Emulsions
The acrylic emulsion market shows a clear trend toward sustainable and low-VOC formulations. It addresses growing environmental concerns and complies with stricter government regulations worldwide. Manufacturers develop water-based emulsions that reduce harmful emissions while maintaining performance standards. End users in construction, automotive, and packaging sectors prefer eco-friendly solutions to meet corporate sustainability goals. This trend drives investments in green technologies and product innovation, enhancing the market’s long-term viability and acceptance across industries.
- For instance, Maydos has developed low odor, APEO-free vinyl and styrene acrylic emulsions specifically designed for interior wall coatings, balancing eco-friendliness with durability.
Rising Use of Acrylic Emulsions in Advanced Coating Technologies
The acrylic emulsion market embraces advances in coating technologies, focusing on enhanced durability and multifunctionality. It supports the development of coatings with improved resistance to UV radiation, chemicals, and abrasion. Innovations include self-cleaning, anti-corrosion, and antimicrobial coatings tailored for specific applications. Manufacturers incorporate nanomaterials and crosslinking agents to boost performance. These developments expand the application scope of acrylic emulsions, attracting new customers and increasing demand in emerging sectors.
- For instance, Gantrade’s Acetoacetoxy Ethyl Methacrylate (AAEM) incorporates advanced crosslinking agents to create self-crosslinkable, ambient-temperature curing acrylic systems that enhance hardness, abrasion resistance, and gloss retention while remaining formaldehyde-free and environmentally friendly.
Expansion in Emerging Economies and Urbanization Impact
Emerging economies contribute significantly to the acrylic emulsion market growth due to rapid urbanization and industrialization. It fulfills the increasing need for durable construction materials, automotive coatings, and packaging solutions in countries such as China, India, and Brazil. Rising disposable incomes and infrastructure investments drive consumption across various sectors. Local manufacturers adapt formulations to regional climate and regulatory conditions, enhancing market penetration. This geographic expansion offers substantial growth opportunities for key market players.
Integration of Digital and Automated Manufacturing Processes
The acrylic emulsion market adopts digitalization and automation to improve production efficiency and product consistency. It leverages Industry 4.0 technologies such as IoT sensors, AI-driven quality control, and automated mixing systems. These innovations reduce waste, lower costs, and accelerate time-to-market for new formulations. Manufacturers gain competitive advantages by optimizing supply chains and enhancing responsiveness to customer demands. This trend supports scalable production and fosters continuous innovation, strengthening the market’s global position.
Market Challenges Analysis
Volatility in Raw Material Prices and Supply Chain Disruptions
The acrylic emulsion market faces challenges from fluctuating raw material costs, particularly petroleum-based feedstocks like acrylic acid and esters. Price volatility affects production expenses and profit margins, forcing manufacturers to adjust pricing strategies frequently. Supply chain disruptions, caused by geopolitical tensions and transportation constraints, further complicate procurement. It increases lead times and operational costs, impacting market stability. Manufacturers must adopt risk mitigation tactics, including supplier diversification and inventory management, to maintain steady production and meet demand efficiently.
Stringent Regulatory Compliance and Environmental Concerns
The acrylic emulsion market contends with strict environmental regulations that require continuous product reformulation. It must meet limits on volatile organic compounds (VOC) and hazardous substances in many regions. Compliance increases research and development expenses and prolongs product approval cycles. End users demand sustainable products without compromising performance, pressuring manufacturers to innovate rapidly. Failure to comply risks legal penalties and loss of market access. These regulatory complexities challenge market players to balance sustainability goals with cost-effectiveness and quality assurance.
Market Opportunities
Growth Potential in Emerging Markets and Infrastructure Development
The acrylic emulsion market finds significant opportunities in emerging economies driven by rapid urbanization and infrastructure expansion. It addresses the rising demand for durable coatings and adhesives in construction, automotive, and packaging sectors. Increasing government investments in smart cities and sustainable building projects create new applications for acrylic emulsions. Manufacturers can capitalize on these trends by tailoring products to regional requirements and climate conditions. Expanding middle-class populations and growing disposable incomes further boost consumption, offering sustained market growth in these regions.
Innovation in Specialty Applications and Sustainable Products
The acrylic emulsion market benefits from opportunities in developing specialty formulations for niche applications, including antimicrobial coatings, flexible packaging, and textiles. It supports increasing demand for multifunctional and high-performance products that meet specific industry needs. Rising emphasis on sustainability drives innovation in bio-based and low-VOC acrylic emulsions, attracting environmentally conscious consumers. Collaborations between chemical companies and end users accelerate product development and market adoption. This focus on advanced, eco-friendly solutions enhances competitive differentiation and opens new revenue streams.
Market Segmentation Analysis:
By Type
The acrylic emulsion market segments by type into pure acrylic emulsion and polymer & copolymer acrylic emulsion. Pure acrylic emulsions offer excellent weather resistance, adhesion, and clarity, making them suitable for high-performance coatings. Polymer and copolymer emulsions provide enhanced flexibility, durability, and chemical resistance, broadening application possibilities. Manufacturers optimize formulations to meet specific performance criteria, enabling versatile use across industries. Both types contribute significantly to market growth by addressing varied end-user requirements and regulatory standards.
- For instance, Dow Inc. has advanced manufacturing facilities producing acrylic emulsions targeted for architectural coatings and industrial uses, emphasizing products that enhance weather resistance and adhesion in exterior paints globally.
By Application
The acrylic emulsion market serves multiple applications, with paints and coatings dominating due to high demand for protective and decorative surfaces. Adhesives and sealants benefit from acrylic emulsions’ strong bonding and flexibility. Construction material additives enhance durability and water resistance in concrete and mortar products. Paper coatings improve printability and moisture resistance, supporting packaging and publishing sectors. Other applications include textiles and leather finishes, where acrylic emulsions enhance texture and durability.
- For instance, Ruico New Material highlights the use of acrylic emulsions in architectural paints that provide durable, weather-resistant films ideal for exterior building protection, maintaining color and gloss over time.
By End-Use Industries
The acrylic emulsion market finds extensive use in construction, driven by demand for sustainable and durable building materials. The automobile sector employs acrylic emulsions for corrosion-resistant and aesthetic coatings. Textile industries utilize emulsions for fabric finishes that improve flexibility and water repellency. Other industries, including packaging and consumer goods, also leverage acrylic emulsions to enhance product performance. These diverse end-use industries collectively drive the market’s steady growth and innovation.
Segments:
Based on Type
- Pure acrylic emulsion
- Polymer & copolymer acrylic emulsion
Based on Application
- Paints & coatings
- Adhesives & sealants
- Construction material additives
- Paper coatings
- Other
Based on End Use Industries
- Construction
- Automobile
- Textile
- Other
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North American acrylic emulsion market holds a 30% share driven by strong demand in construction, automotive, and packaging sectors. It benefits from established manufacturing infrastructure and strict environmental regulations that promote water-based, low-VOC coatings. The region’s focus on sustainability and green building standards increases adoption of eco-friendly acrylic emulsions. Leading companies invest in R&D to develop advanced formulations that meet regulatory and performance requirements. The presence of major end users and growing renovation activities further support market growth. North America continues to lead due to technological innovation and regulatory compliance.
Europe
Europe accounts for 25% of the acrylic emulsion market, propelled by growing demand for sustainable coatings in construction and automotive industries. It faces rigorous regulations on VOC emissions, encouraging manufacturers to innovate low-impact products. The market expands through investments in infrastructure modernization and renewable energy projects that require durable, environmentally friendly coatings. Europe’s well-developed industrial base and focus on circular economy principles drive increased use of recyclable and bio-based acrylic emulsions. It attracts key players focused on sustainability and product differentiation to meet diverse end-user needs.
Asia Pacific
Asia Pacific dominates with a 35% share of the acrylic emulsion market due to rapid urbanization, industrialization, and infrastructure growth in countries like China, India, and Japan. It experiences high demand for construction coatings, automotive finishes, and packaging materials driven by expanding middle-class populations and government investments. Manufacturers tailor acrylic emulsions to regional climate conditions and regulatory frameworks. The region attracts new entrants and increased production capacities to meet escalating consumption. Asia Pacific’s strong economic growth and infrastructure development create vast opportunities for market expansion.
Latin America
Latin America holds 6% of the acrylic emulsion market, supported by increasing construction activities and automotive production. It faces challenges from economic fluctuations but benefits from growing investments in residential and commercial projects. The demand for durable, cost-effective coatings and adhesives rises with urban population growth. Manufacturers focus on improving supply chains and localizing production to reduce costs. The region presents moderate growth potential, with companies exploring partnerships and collaborations to expand market presence.
Middle East & Africa
The Middle East & Africa captures 4% of the acrylic emulsion market, driven by infrastructure development and rising industrial activities. It experiences demand for coatings resistant to harsh environmental conditions such as heat and corrosion. Investment in oil and gas sectors and urbanization fuels growth in construction materials. The market remains fragmented, with opportunities for expansion through tailored product offerings and strategic alliances. Regulatory improvements and increasing awareness of sustainability gradually influence product adoption in this region.
Key Player Analysis
- Covestro
- Henkel Additives
- Mallard Creek Polymers
- BASF
- Jensen & Nicholson
- Arkema Group
- Max Paints
- Avery Dennison Performance Polymers
- Mitsui Chemicals
- Celanese
- B. Fuller
- Dow Inc
- DIC
Competitive Analysis
The acrylic emulsion market features intense competition among global and regional players focused on innovation, product quality, and regulatory compliance. Leading companies invest heavily in research and development to enhance performance and sustainability of their acrylic emulsions. It emphasizes eco-friendly formulations with low VOC content to meet stringent environmental standards. Key players maintain strong distribution networks and strategic partnerships to expand market reach. Companies differentiate through specialized products tailored for industries such as construction, automotive, and packaging. Price competitiveness and supply chain efficiency also influence market positioning. Continuous technological advancements and customer-driven customization intensify rivalry, driving overall market growth and innovation.
Recent Developments
- In April 2024, Lubrizol announced a significant investment to expand its acrylic emulsion manufacturing capacity at its Calvert City, Kentucky site.
- In November 2024, Shokubai Co., Ltd. announced the acquisition of 100% of Emulsion Technology Co., Ltd., a company specializing in the production and marketing of acrylic emulsions and fine products.
- In July 2023, Covestro introduced NeoCryl® A-2085, a waterborne acrylic copolymer developed for barrier coatings in food-contact-grade paper packaging, offering low odor and excellent water and grease barrier properties.
Market Concentration & Characteristics
The acrylic emulsion market exhibits a moderately concentrated competitive landscape dominated by several global chemical manufacturers and specialty polymer producers. It features key players that invest heavily in research and development to innovate high-performance, sustainable formulations meeting stringent environmental regulations. These companies maintain extensive distribution networks and strategic partnerships to enhance market reach and customer engagement. The market balances between established multinational corporations and regional manufacturers catering to localized demand and specific application needs. It demonstrates rapid technological advancement, with players focusing on low-VOC, bio-based emulsions and multifunctional coatings. Cost efficiency, product differentiation, and regulatory compliance shape competitive dynamics. Market characteristics include strong emphasis on product quality, environmental sustainability, and customization to meet diverse end-use industry requirements such as construction, automotive, and packaging. This structure fosters continuous innovation while ensuring steady growth and resilience amid raw material volatility and evolving regulatory frameworks.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-User Industries and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The acrylic emulsion market will expand due to rising demand from construction and automotive sectors.
- Manufacturers will focus on developing sustainable, low-VOC, and eco-friendly products.
- Technological innovation will enhance product performance and broaden application areas.
- Emerging economies will offer significant growth opportunities driven by urbanization.
- Increasing regulations will push manufacturers toward greener formulations.
- Expansion into specialty applications such as antimicrobial and flexible coatings will accelerate.
- Supply chain optimization and raw material diversification will gain importance.
- Digital and automated production processes will improve efficiency and quality.
- Collaboration between chemical companies and end users will drive tailored solutions.
- Market players will invest in R&D to maintain competitive advantage and meet evolving consumer demands.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand in Construction and Automotive Sectors
Acrylic emulsions are increasingly used in construction and automotive industries due to their superior adhesion, flexibility, and weather resistance, supporting durable coatings for infrastructure and vehicles. Urbanization and infrastructure projects globally are boosting the need for high-performance, protective coatings.
Stringent Environmental Regulations and Shift to Low-VOC Solutions
Tighter regulations on volatile organic compounds (VOCs) are accelerating the adoption of water-based, eco-friendly acrylic emulsions as alternatives to solvent-based coatings. This shift is driven by both regulatory compliance and growing consumer preference for sustainable products.
Technological Advancements in Product Formulation
Continuous innovation in polymerization and additive technologies is enhancing the durability, chemical resistance, and multifunctionality of acrylic emulsions. These advancements enable broader application in coatings, textiles, and packaging, meeting diverse industry requirements.
Expansion in Emerging Economies and Urbanization
Rapid industrialization and urban growth in Asia Pacific and other emerging regions are driving demand for acrylic emulsions in construction, automotive, and packaging applications. Rising disposable incomes and infrastructure investments in these markets create significant growth opportunities.
Diversification into Specialty and High-Performance Applications
Manufacturers are developing specialty acrylic emulsions for applications such as antimicrobial coatings, flexible packaging, and advanced textiles. This diversification addresses evolving end-user needs and opens new revenue streams, supporting market resilience and expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the acrylic emulsion market?
What factors are driving the growth of the acrylic emulsion market?
What are the key segments within the acrylic emulsion market?
What are some challenges faced by the acrylic emulsion market?
Who are the major players in the acrylic emulsion market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Pure acrylic emulsion
- 1.2.2 Polymer & copolymer acrylic emulsion
- 1.3 By Application
- 1.3.1 Paints & coatings
- 1.3.2 Adhesives & sealants
- 1.3.3 Construction material additives
- 1.3.4 Paper coatings
- 1.3.5 Other
- 1.4 By End Use Industries
- 1.4.1 Construction
- 1.4.2 Automobile
- 1.4.3 Textile
- 1.4.4 Other
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 10,480 million → 2032: USD 19,326 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Acrylic Emulsion Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Acrylic Emulsion Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Acrylic Emulsion Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Acrylic Emulsion Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Acrylic Emulsion Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Acrylic Emulsion Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Acrylic Emulsion Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Acrylic Emulsion Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 10,480 million → 2032: USD 19,326 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Acrylic Emulsion Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pure acrylic emulsion
- 12.3.7.2 Polymer & copolymer acrylic emulsion
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Paints & coatings
- 12.4.7.2 Adhesives & sealants
- 12.4.7.3 Construction material additives
- 12.4.7.4 Paper coatings
- 12.4.7.5 Other
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End Use Industries - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Construction
- 12.5.7.2 Automobile
- 12.5.7.3 Textile
- 12.5.7.4 Other
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Acrylic Emulsion End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Acrylic Emulsion Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Acrylic Emulsion Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Acrylic Emulsion Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Arkema Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 BASF
- 18.4 Dow Inc
- 18.5 Covestro
- 18.6 Henkel Additives
- 18.7 Avery Dennison Performance Polymers
- 18.8 Mallard Creek Polymers
- 18.9 Celanese
- 18.10 Mitsui Chemicals
- 18.11 DIC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

