
Market Overview:
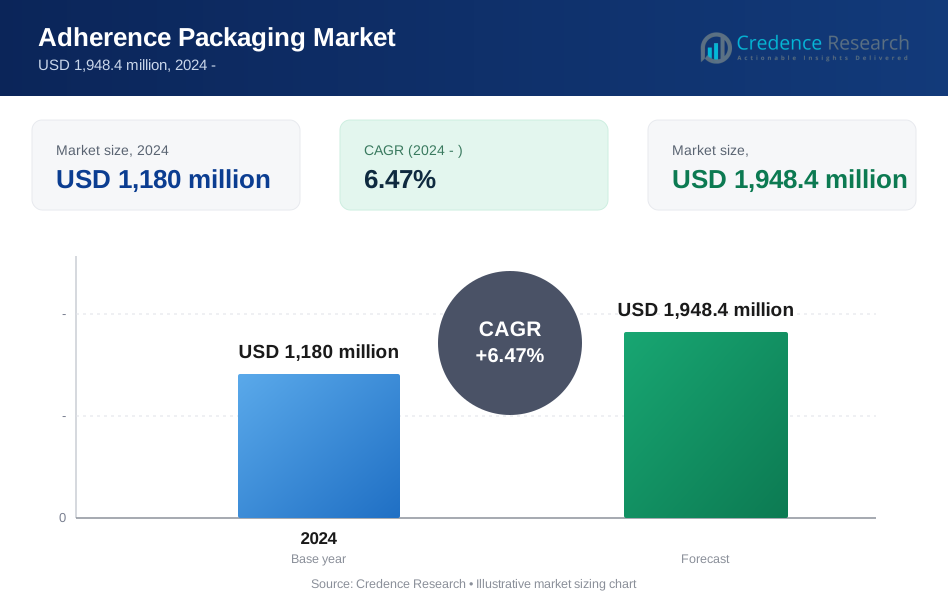
The Adherence Packaging Market is expected to expand from USD 1,180 million in 2024 to approximately USD 1,948.4 million by 2032, registering a compound annual growth rate (CAGR) of 6.47% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Adherence Packaging Market Size 2024 | USD 1,180 Million |
| Adherence Packaging Market, CAGR | 6.47% |
| Adherence Packaging Market Size 2032 | USD 1,948.4 Million |
This growth is primarily driven by the rising need for improved patient compliance, particularly among aging populations and individuals with chronic health conditions. As the burden of long-term therapies increases, healthcare providers and pharmacies are increasingly adopting adherence packaging to enhance medication accuracy, reduce hospital readmissions, and improve clinical outcomes. Key innovations such as multi-dose blister packs, smart labels, and unit-dose pouches are enhancing patient adherence by simplifying medication schedules and enabling real-time tracking. These packaging formats are particularly useful in long-term care settings and for patients managing multiple prescriptions.
Regionally, North America dominates the market, supported by robust healthcare infrastructure, rising chronic disease prevalence, and growing focus on patient-centric solutions. Europe follows with steady adoption, aided by favorable reimbursement policies and well-developed pharmacy networks. Meanwhile, Asia-Pacific is witnessing rapid growth due to expanding pharmaceutical production and improving healthcare access in countries like China, India, and South Korea. As medication adherence gains global importance, the market is poised for continued innovation and investment.
Market Insights:
- The Adherence Packaging Market is projected to reach USD 1,948.4 million by 2032, up from USD 1,180 million in 2024.
- Smart packaging trends, including NFC, sensors, and app integration, are key adoption enablers.
- North America holds the dominant regional share; Asia Pacific is the fastest-growing segment.
- Hospitals and pharmacies are the primary adopters due to increasing need for patient compliance.
- Plastics remain the preferred material, while eco-friendly alternatives are gaining traction.
- Regulatory pressures and operational costs pose constraints for small-scale pharmacies.
- Competitive dynamics are driven by automation, digital health integration, and service bundling.

Market Drivers:
Growing Chronic Disease Burden:
The Adherence Packaging Market benefits significantly from the rising prevalence of chronic conditions such as diabetes, hypertension, and cardiovascular diseases. Chronic illnesses require long-term and consistent medication regimens, making adherence packaging vital to ensure accurate and timely dosage. Healthcare systems increasingly promote the use of these packaging solutions to improve clinical outcomes. Pharmaceutical firms integrate adherence packaging to increase patient compliance and medication effectiveness. The aging population, more prone to chronic illnesses, further intensifies demand.
- For instance, Terumo Pharmaceutical Solutions, among other firms, has launched pre-fillable polymer syringes specifically for low-dose applications, ensuring that medications like insulin for diabetes patients are administered precisely.
Support from Regulatory Bodies:
Regulatory agencies around the world are enforcing stricter guidelines to improve patient safety and reduce medical errors. The Adherence Packaging Market aligns well with these priorities by offering compliance-supportive solutions. Packaging formats such as multi-dose blister packs reduce risks associated with improper medication usage. Guidelines in North America and Europe require improved pharmaceutical dispensing practices. The presence of barcode-enabled and serialized packaging enhances traceability and supply chain control.
- For instance, Gerresheimer AG offers packaging solutions such as serialized blister packs, addressing rigorous requirements for cleanroom packaging and validation to satisfy both European and North American pharmaceutical markets.
Technological Advancements in Packaging:
Technology plays a pivotal role in driving the evolution of the Adherence Packaging Market. Innovations like smart blister packs, RFID-enabled packs, and mobile app integration offer real-time tracking and reminders. These technologies increase user interaction and medication compliance rates. Pharmaceutical companies utilize these solutions to gain data-driven insights into patient behavior. Smart packaging helps reduce hospitalization by enabling early intervention when doses are missed. Integration with telehealth platforms expands utility.
Retail Pharmacies Driving Adoption:
Retail and mail-order pharmacies are contributing significantly to the growth of the Adherence Packaging Market. They offer pre-sorted medication packs to help patients manage complex prescriptions more effectively. These pharmacies integrate automated filling and sealing machinery to meet growing demand. Patients prefer these services for convenience. Retail chains promote these solutions to improve their value-added services. Pharmacies use custom-printed adherence packs to build brand identity and customer loyalty.
Market Trends:
Integration of Smart Packaging:
Smart technologies are increasingly being integrated into adherence packaging formats. The Adherence Packaging Market is seeing strong growth in the adoption of RFID tags, QR codes, and NFC chips. These allow real-time communication between the packaging and healthcare providers. Patients receive reminders through mobile apps linked to the packaging system. This trend aligns with the rising emphasis on digital health and remote patient monitoring. Smart packaging provides data analytics.
- For instance, Berry Global has introduced a digital, child-resistant medication closure (Berry Digi-Cap) that records each instance of the package being opened, stores patient usage history, continuously tracks temperature, and transfers data via NFC to smartphones or healthcare systems.
Shift Toward Personalized Medicine:
The rise of personalized healthcare is influencing packaging formats in the Adherence Packaging Market. Medication regimens are increasingly tailored to individual patient needs. Custom blister packs and pouches are being developed to align with these unique therapies. Personalization enhances medication effectiveness and reduces side effects. Packaging manufacturers are developing flexible, modular designs to accommodate diverse patient profiles. Retail pharmacies offer individualized adherence.
- For instance, Pharmacies can adopt Dispill quickly with minimal start-up costs, and the system integrates with most pharmacy management software for customization and operational efficiency
Growth of Eco-Friendly Solutions:
Sustainability is becoming a top priority in the Adherence Packaging Market. Manufacturers are transitioning toward recyclable, compostable, and biodegradable materials. Paper-based blister packs and plastic alternatives are gaining ground. Eco-conscious consumers and healthcare providers support these options to reduce environmental impact. Green packaging certifications influence purchasing decisions. Regulatory bodies encourage the use of sustainable materials. Supply chains are adapting.
Automation in Pharmacy Operations:
Pharmacy automation technologies are accelerating the adoption of adherence packaging formats. The Adherence Packaging Market is seeing increased implementation of robotic systems in pharmacies. These systems assemble multi-dose medication packs with high speed and accuracy. Automated packaging ensures consistent fill quality and reduces labor costs. Pharmacy chains and hospitals invest in these systems to scale services. Workflow efficiencies allow pharmacies to serve larger patient volumes.
Market Challenges Analysis:
High Implementation and Operational Costs:
The Adherence Packaging Market faces barriers from the high initial costs associated with implementing advanced packaging technologies. Smart packaging systems and automation equipment require substantial capital investment. Small and mid-sized pharmacies often struggle to justify these expenses. Ongoing maintenance, staff training, and integration with IT systems increase costs. For manufacturers, sourcing sustainable materials and customizing designs can be costly.
Limited Standardization and Regulatory Variability:
Regulatory inconsistency across countries poses a challenge for the Adherence Packaging Market. Each market may follow different protocols related to medication labeling, serialization, and packaging material use. Lack of global standardization complicates product design and increases compliance costs for manufacturers. Frequent changes in regulations can disrupt production and delay market entry. In emerging markets, absence of strong packaging mandates affects adoption.
Market Opportunities:
Expansion in Emerging Markets:
Emerging economies present significant opportunities for the Adherence Packaging Market. Rising healthcare expenditures and growing awareness of patient safety are creating new demand. Governments are investing in healthcare infrastructure and medication access. Local pharmaceutical manufacturing is expanding in Asia-Pacific, Latin America, and Africa. These regions seek cost-effective, compliance-friendly packaging solutions. Multinational players can penetrate these markets through strategic partnership.
Integration with Digital Health Platforms:
The integration of adherence packaging with digital health ecosystems creates new value propositions. Connected packaging systems can sync with patient portals, mobile apps, and telemedicine platforms. This integration supports remote monitoring and data sharing with care providers. Healthcare systems gain actionable insights to personalize interventions. Pharma firms can analyze usage trends to improve outcomes and reduce churn. Startups and tech companies are entering the space to offer smart solutions.
Market Segmentation Analysis:
By Material
The Adherence Packaging Market is segmented by material, with plastics holding the largest share due to their versatility, cost-efficiency, and durability. Paper and aluminum segments are gaining interest due to growing demand for sustainable alternatives.
- For instance, SCHOTT began producing high-quality FIOLAX® borosilicate glass tubing at its new facility in China, with an annual capacity of 20,000 tons. This glass is used for vials, syringes, and cartridges, with pharmaceutical vials produced by SCHOTT being deployed in 75% of COVID-19 vaccine projects globally.
By Packaging Type
Blister packs dominate the packaging type segment in the Adherence Packaging Market due to their unit-dose control and tamper-evident properties. Pouches and strip packs are gaining momentum for their portability and cost-effectiveness.
- For instance, Amcor has developed a multi-chamber blister pack system that allows for the transport and storage of both liquid and solid drug ingredients in separated, airtight compartments. This innovation permits medications to be mixed immediately before use, reducing the need for a cold chain in remote areas and winning multiple awards for its technical innovation.
By Dose Format
Multi-dose and unit-dose formats are commonly used in adherence packaging. Unit-dose formats are especially valued in clinical settings for ensuring accurate administration, while multi-dose options help manage complex regimens.
By End-User
Hospitals, retail pharmacies, and long-term care facilities are the main end users of adherence packaging solutions. Each of these settings demands high standards for medication safety, accuracy, and patient compliance.
Segmentation:
By Material
- Plastics
- Paper & Paperboard
- Aluminum
By Packaging Type
- Blister Packs
- Pouches
- Strip Packs
By Dose Format
- Unit-Dose
- Multi-Dose
By End-User
- Hospitals
- Retail Pharmacies
- Long-Term Care Facilities
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East & Africa
Regional Analysis:
North America Leads with Robust Infrastructure
North America holds the largest share in the Adherence Packaging Market, accounting for 37% of global revenue in 2024. Strong healthcare infrastructure, regulatory mandates on medication safety, and widespread adoption of unit-dose formats drive market growth. The United States dominates regional demand, supported by high chronic disease prevalence and pharmacy automation trends. Pharmacies and hospitals increasingly deploy adherence solutions to reduce medication errors and improve outcomes. Growing elderly population and reimbursement incentives further support expansion. The market continues to benefit from advanced technologies such as smart blister packs and barcode-integrated solutions.
Europe Benefits from Regulatory Push
Europe ranks second in the Adherence Packaging Market, contributing 27% of the global market. Regulatory frameworks encouraging safe dispensing and medication tracking enhance packaging adoption across the region. Germany, France, and the United Kingdom represent the largest national markets, supported by established pharmacy chains and government health initiatives. The shift toward sustainable packaging and increased investment in pharmaceutical services promote demand. Multi-dose pouches and paper-based packaging gain momentum amid environmental concerns. The region also experiences rising demand in long-term care facilities and geriatric care centers.
Asia-Pacific Emerges as High-Growth Region
Asia-Pacific holds 21% share of the Adherence Packaging Market and shows the highest growth potential through 2032. Rapid urbanization, expanding healthcare access, and increasing chronic illness incidence contribute to market expansion. China and India lead in both pharmaceutical production and consumption, attracting investments in adherence packaging solutions. The retail pharmacy sector continues to grow in urban centers, driving demand for single-use blister packs and low-cost pouches. Government focus on medication safety and regulatory modernization strengthens adoption rates. Rising awareness about compliance packaging in emerging economies supports long-term market penetration.
Key Player Analysis:
- Omnicell Inc.
- WestRock Company
- Cardinal Health
- McKesson Corporation
- Medicine-On-Time
- Jones Healthcare Group
- Manrex Limited
- Parata Systems LLC
- BD (Becton, Dickinson and Company)
- AARDEX Group
Competitive Analysis:
The Adherence Packaging Market is moderately fragmented, with key players leveraging technology, strategic partnerships, and service expansion to strengthen their positions. Companies differentiate through automation, smart packaging features, and eco-friendly designs to meet evolving customer needs. Competition intensifies in emerging regions where both local and global firms compete aggressively for market share. Players invest in digital health integration, such as connected pill packs and cloud-based monitoring systems, to enhance medication adherence. Regulatory compliance and customization capabilities also serve as critical differentiators in institutional and retail pharmacy settings. Mergers and acquisitions continue to shape the competitive landscape, enabling portfolio expansion and geographic reach. Increasing demand for multi-dose packaging and aging populations further fuel rivalry across segments.
Recent Developments:
· In May 2025, Omnicell Inc. launched its MedTrack RFID product line, a new generation of RFID-enabled dispensing and intelligent inventory management software. These solutions are aimed at increasing medication accuracy, reducing errors, and improving inventory visibility in perioperative and clinic settings by integrating automated workflows within the company’s connected pharmacy platform.
- In July 2024, WestRock Company completed its merger with Smurfit Kappa, forming Smurfit WestRock. This combination positions the new entity as a global leader in sustainable paper-based packaging, significantly expanding their geographic reach and product diversity, including advanced solutions for pharmaceutical adherence packaging.
Market Concentration & Characteristics:
The Adherence Packaging Market features moderate concentration, with leading companies driving innovation through automation, smart labels, and sustainable materials. The market faces moderate entry barriers due to high capital requirements, regulatory compliance, and the need for specialized manufacturing capabilities. Differentiation hinges on scalability, adherence to safety standards, and seamless integration with digital health platforms. Players focus on improving medication management outcomes, reducing hospital readmissions, and supporting pharmacy workflow efficiency. Technological advancements such as NFC-enabled packs and real-time monitoring tools are gaining traction. Partnerships with healthcare providers and payers are becoming vital to scale deployment. The shift toward personalized medicine and home-based care further increases demand for customized adherence solutions.
Report Coverage:
The research report offers an in-depth analysis based on Material, Packaging Type, Dose Format and End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. The report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Smart packaging and medication reminders will become core elements of chronic disease management programs.
- Pharmacies will expand automation for scalable, error-free packaging services tailored to patient schedules.
- Regulatory mandates on unit-dose packaging will drive format standardization and uptake across healthcare.
- AI-driven personalization tools will transform multi-pill blister pack customization in retail channels.
- Material innovation will shift packaging norms toward compostable and recyclable structures.
- Growth in telehealth will increase demand for connected packaging enabling remote patient adherence tracking.
- Private payers and healthcare systems will incentivize compliance-linked packaging through outcome-based models.
- Pharmacy chains will invest in end-to-end adherence solutions, bundling software, automation, and packaging.
- Localized production strategies will support packaging accessibility in developing markets.
- Consumer-centric packaging designs will improve patient interaction and medication behavior outcomes.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Adherence Packaging Market Market?
What factors are driving the growth of the Adherence Packaging Market Market?
What are the key segments within the Adherence Packaging Market Market?
What are some challenges faced by the Adherence Packaging Market Market?
Who are the major players in the Adherence Packaging Market Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Adherence Packaging Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Adherence Packaging Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 1,180 million → forecast year: USD 1,948.4 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Adherence Packaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Adherence Packaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Adherence Packaging Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Adherence Packaging Market Drivers
- 3.3 Adherence Packaging Market Restraints & Challenges
- 3.4 Adherence Packaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Adherence Packaging Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Adherence Packaging Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Adherence Packaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Adherence Packaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Adherence Packaging Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Adherence Packaging market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Adherence Packaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Adherence Packaging Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Adherence Packaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Adherence Packaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Adherence Packaging Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Adherence Packaging Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Adherence Packaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Adherence Packaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Adherence Packaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Adherence Packaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Adherence Packaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Adherence Packaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Adherence Packaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
