
Market Overview
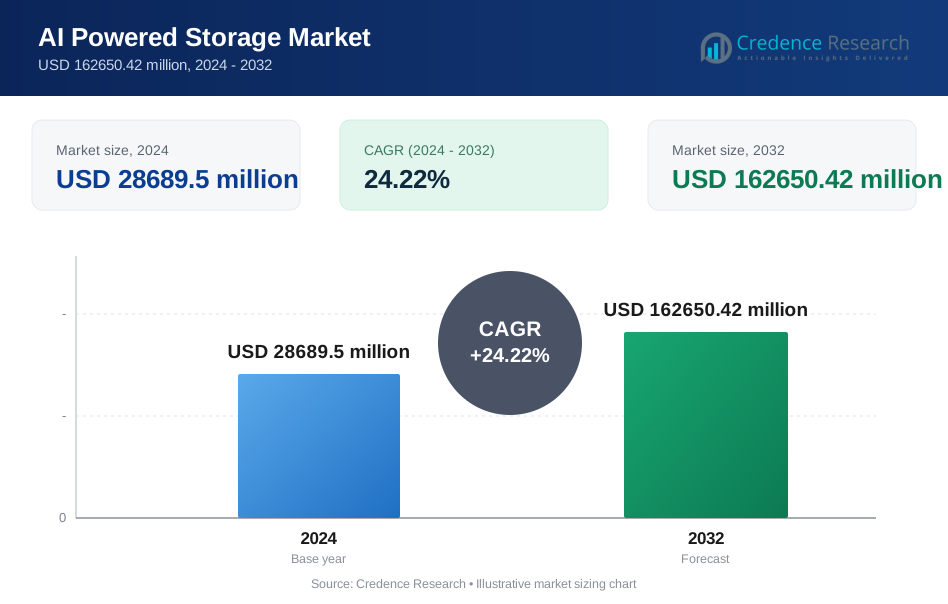
Ai Powered Storage Market size was valued USD 28689.5 million in 2024 and is anticipated to reach USD 162650.42 million by 2032, at a CAGR of 24.22% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| AI Powered Storage Market Size 2024 | USD 28689.5 million |
| AI Powered Storage Market, CAGR | 24.22% |
| AI Powered Storage Market Size 2032 | USD 162650.42 million |
The Ai Powered Storage Market includes major players such as Google Cloud, Hitachi Vantara, Microsoft Azure, Dell Technologies, Amazon Web Services (AWS), HPE, NetApp, IBM Corporation, Pure Storage, and NVIDIA. These companies expand their presence through high-performance flash systems, GPU-optimized architectures, and AI-driven data management tools that support large training and inference workloads. Providers focus on scalable storage platforms for hybrid and multi-cloud environments, strengthening adoption across enterprises and hyperscale data centers. North America led the market in 2024 with a 38% share, driven by strong cloud investment, rapid AI deployment, and continued modernization of data infrastructure.

Market Insights
- Ai Powered Storage Market reached USD 28689.5 million in 2024 and will hit USD 162650.42 million by 2032 at a CAGR of 24.22%.
- Demand grows as enterprises adopt high-speed storage to support AI workloads, real-time analytics, and automation across cloud and edge environments.
- Trends highlight rising use of NVMe flash, software-defined storage, and AI-optimized architectures that enhance throughput and reduce latency.
- Competition intensifies as leading vendors focus on scalable platforms, predictive analytics, and hybrid cloud integration while addressing performance and cost pressures.
- North America held 38% share, Europe 27%, Asia Pacific 25%, Latin America 6%, and Middle East and Africa 4%, while SSDs led storage medium adoption with a 72% share.
Market Segmentation Analysis:
By Offering
Hardware led the Ai Powered Storage Market in 2024 with about 68% share. Strong demand came from AI-optimized processors, accelerators, and high-bandwidth storage arrays used in data centers. Hardware adoption grew as enterprises required faster throughput for model training, real-time inference, and edge analytics. Rising deployments of GPU-enabled systems and NVMe-based architectures pushed this segment ahead of software. Software grew at a steady pace due to expansion in AI-driven data management and predictive storage tools but remained smaller because buyers prioritized physical infrastructure upgrades.
- For instance, NVIDIA states that one DGX H100 system combines 8 H100 Tensor Core GPUs with 640 gigabytes of GPU memory and delivers 32 petaFLOPS of FP8 AI compute for intensive training workloads.
By Storage System
Network Attached Storage held the dominant share in 2024 with nearly 47%. Businesses preferred NAS because shared environments handled heavy AI workloads with simple scaling and unified data access. NAS growth increased as cloud service providers and enterprises supported large unstructured datasets required for machine learning and deep learning tasks. Direct Attached Storage and Storage Area Network systems also expanded, yet adoption stayed lower due to higher integration needs and limited flexibility in distributed AI environments compared with NAS.
- For instance, NetApp reports that its AFF A900 all-flash array can deliver up to 2,400,000 IOPS per system with application latencies around 100 microseconds when supporting business-critical databases and virtualized workloads.
By Storage Medium
Solid State Drives dominated this segment in 2024 with about 72% share. SSD demand rose sharply because AI workloads needed high read/write speeds, lower latency, and better endurance than HDD units. Enterprises used SSD-based arrays to support training pipelines, edge inference, and real-time analytics. HDDs remained relevant for large-capacity archival needs but held a smaller share due to slower performance and reduced suitability for AI-intensive operations. Increasing server upgrades and reduced SSD costs helped maintain the segment leadership.
Key Growth Drivers
Rising demand for high-speed data processing
The Ai Powered Storage Market grows as enterprises handle larger datasets and require faster model training. High-speed systems support real-time analytics used in healthcare, finance, and manufacturing. Strong adoption of NVMe, GPU-accelerated storage, and flash arrays drives this demand. Organizations invest in low-latency infrastructure to boost AI accuracy and decision cycles.
- For instance, Intel documents that its Optane SSD P5800X can reach sequential read throughput up to 7.2 gigabytes per second, sequential write throughput up to 6.2 gigabytes per second, and mixed 4K random workloads up to 1,800,000 IOPS with read latency under 6 microseconds in vendor benchmarks.
Expansion of cloud and edge AI deployments
Wider use of cloud platforms and edge devices increases the need for intelligent storage that manages distributed workloads. Providers deploy scalable systems that automate data placement and improve inference performance. Growing use of autonomous systems, smart cities, and IoT sensors strengthens this shift. AI-driven orchestration improves storage efficiency across hybrid environments.
- For instance, Amazon Web Services specifies that each Inferentia2 chip provides 380 INT8 TOPS and 190 FP16 tensor TFLOPS, and that Inf2 instances with 12 Inferentia2 chips offer up to 2.3 petaFLOPS of compute and 9.8 terabytes per second of total memory bandwidth for large language model inference.
Growing investments in automation for data management
Companies automate storage workflows to reduce operational effort and improve reliability. AI tools optimize capacity, predict failures, and enhance security. Rising complexity in unstructured data pushes organizations to adopt self-managing systems. This investment trend supports seamless scaling in large data centers.
Key Trends & Opportunities
Adoption of AI-optimized storage architectures
Vendors design systems tailored for deep learning and large-language-model workloads. These platforms support parallel processing, faster retrieval, and efficient indexing. Enterprises gain improved throughput as demand for advanced analytics rises. Architectural innovation opens opportunities in autonomous vehicles, biotech, and financial AI applications.
- For instance, a 16-node Dell PowerScale F710 cluster running OneFS 9.9 has been measured delivering around 300 gigabytes per second of sequential read throughput, which equates to roughly 18 gigabytes per second per node when feeding large AI training datasets.
Growth of software-defined and composable storage
Software-defined platforms gain traction due to flexible scaling and reduced hardware dependence. Composable infrastructure lets users allocate storage resources dynamically based on workload type. This trend enables better utilization of high-performance drives and accelerators. Rising hybrid cloud activity expands opportunities for adaptive storage layers.
- For instance, Hewlett Packard Enterprise highlights that its Synergy composable infrastructure can bring a new server online in about 15 seconds, and Synergy compute modules can be ready to boot in less than 30 seconds, enabling rapid reprovisioning of compute and storage pools for changing workloads.
Rising focus on data governance and secure AI storage
Organizations seek systems that protect sensitive datasets while enabling AI access. Encryption, zero-trust controls, and automated compliance tools shape new opportunities. Growth in regulated industries increases demand for secure, auditable storage. Vendors respond with AI-powered threat detection and risk monitoring.
Key Challenges
High cost of advanced storage infrastructure
AI-ready systems require premium hardware, including flash arrays, accelerators, and high-bandwidth fabrics. Many mid-sized enterprises face budget limits when shifting from legacy units. High upfront investment slows adoption, especially in emerging markets. Cost remains a barrier despite long-term performance gains.
Integration complexity in hybrid and multi-cloud environments
AI workloads span edge, cloud, and on-premise sites, creating data movement and compatibility challenges. Organizations struggle with latency issues, diverse protocols, and inconsistent governance. Integrating intelligent storage into existing systems requires skilled teams. These hurdles slow deployment and impact scalability.
Regional Analysis
North America
North America held the largest share of the Ai Powered Storage Market in 2024 with about 38%. Strong adoption came from hyperscale data centers, cloud providers, and enterprises deploying AI-driven analytics across finance, healthcare, and retail. High investment in advanced flash systems, GPU-accelerated storage, and edge AI supported continued growth. Leading vendors expanded platforms that improved data throughput and automated storage operations. Rising deployment of large language models and real-time AI applications kept North America the most mature market.
Europe
Europe accounted for nearly 27% of the market in 2024. Demand increased as enterprises modernized infrastructure to support AI governance, compliance, and automation requirements. Industries such as automotive, telecom, and manufacturing invested in high-performance storage to advance autonomous systems and predictive analytics. The region saw rising adoption of software-defined storage and secure data platforms aligned with regulatory frameworks. Ongoing digital transformation programs encouraged investments in scalable architectures, strengthening Europe’s position in global AI storage adoption.
Asia Pacific
Asia Pacific captured around 25% market share in 2024 and grew rapidly due to expanding cloud ecosystems and rising AI adoption in China, India, Japan, and South Korea. Enterprises deployed intelligent storage to manage increasing volumes of unstructured data generated by e-commerce, fintech, and industrial automation. Government-backed digitalization and edge computing initiatives boosted demand for fast, scalable solutions. Vendors invested in high-density SSD systems and AI-optimized infrastructure to support regional growth, making Asia Pacific a high-potential market.
Latin America
Latin America held close to 6% share in 2024. Growth remained steady as countries expanded digital infrastructure and enterprises adopted AI for customer analytics, cybersecurity, and automation. Cloud migration accelerated demand for flexible, intelligent storage platforms. Despite budget limits in some markets, increasing adoption of managed services encouraged investments in high-performance systems. Telecom and banking sectors led deployment, supporting stronger uptake across emerging economies. Continued expansion of AI applications improved storage modernization trends in the region.
Middle East and Africa
Middle East and Africa accounted for nearly 4% of the market in 2024. Demand rose as governments and enterprises advanced smart city programs, digital banking, and AI-powered public services. Data centers expanded capacity to support regional cloud growth, increasing use of flash-based and software-defined storage. Adoption grew gradually due to cost challenges but gained momentum in the UAE, Saudi Arabia, and South Africa. Investments in cybersecurity and AI readiness strengthened the region’s position as an emerging market for intelligent storage solutions.
Market Segmentations:
By Offerings
- Hardware
- Software
By Storage System
- Network Attached Storage (NAS)
- Direct Attached Storage (DAS)
- Storage Area Network (SAN)
By Storage Medium
- Solid State Drive (SSD)
- Hard Disk Drive (HDD)
By End-User
- Enterprise
- Government Bodies
- Cloud Service Providers
- Telecom Companies
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Ai Powered Storage Market is shaped by leading players such as Google Cloud, Hitachi Vantara, Microsoft Azure, Dell Technologies, Amazon Web Services (AWS), HPE, NetApp, IBM Corporation, Pure Storage, and NVIDIA. Vendors focus on advanced architectures that support high-speed model training, scalable inference workloads, and intelligent data management. Companies invest in flash-based systems, GPU-accelerated platforms, and software-defined storage to enhance performance across hybrid and multi-cloud environments. Many providers integrate automation, predictive analytics, and real-time optimization to reduce latency and improve reliability. Strategic partnerships with cloud platforms, data center operators, and enterprise AI teams drive further innovation. Vendors also enhance security, governance, and energy efficiency as enterprises scale AI adoption across industries.
Key Player Analysis
- Google Cloud
- Hitachi Vantara
- Microsoft Azure
- Dell Technologies
- Amazon Web Services (AWS)
- HPE (Hewlett Packard Enterprise)
- NetApp
- IBM Corporation
- Pure Storage
- NVIDIA
Recent Developments
- In 2025, NetApp introduced a new enterprise-grade AI data platform featuring NetApp AFX disaggregated all-flash storage and the NetApp AI Data Engine (AIDE), which is built on the NVIDIA AI Data Platform reference design to provide consistent data access across hybrid cloud environments.
- In 2025, Dell Technologies announced a partnership with NVIDIA to develop AI data platforms for Dell PowerScale and future "Project Lightning" systems.
- In 2025, Pure Storage introduced the high-performance FlashBlade//EXA storage platform for AI and HPC workloads and integrated its FlashBlade products with the NVIDIA AI Data Platform reference desig
Report Coverage
The research report offers an in-depth analysis based on Offerings, Storage System, Storage Medium, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Ai powered storage systems will see wider use across cloud, edge, and on-premise setups.
- Demand for high-speed flash and NVMe architectures will grow with advanced AI workloads.
- Enterprises will adopt automated data management to improve efficiency and reduce downtime.
- Hybrid and multi-cloud environments will drive adoption of intelligent, self-optimizing storage.
- Growth in large language models will raise the need for high-capacity, low-latency storage.
- Software-defined storage will gain traction due to scalability and reduced hardware dependence.
- Security-driven storage designs will expand as AI governance and compliance needs rise.
- Edge AI growth will increase demand for compact, energy-efficient storage solutions.
- Vendors will integrate more predictive analytics to enhance performance and reliability.
- AI-optimized storage will become a core requirement for digital transformation across industries.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the AI Powered Storage market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the AI Powered Storage market projected to grow between 2025 and 2032?
Which AI Powered Storage market segment held the largest share in 2024?
What are the primary factors fueling the growth of the AI Powered Storage market?
Who are the leading companies in the AI Powered Storage market?
Which region commanded the largest share of the AI Powered Storage market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 AI Powered Storage Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global AI Powered Storage Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 28689.5 million → 2032: USD 162650.42 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 AI Powered Storage Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. AI Powered Storage Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 AI Powered Storage Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 AI Powered Storage Market Drivers
- 3.3 AI Powered Storage Market Restraints & Challenges
- 3.4 AI Powered Storage Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 AI Powered Storage Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 AI Powered Storage Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, AI Powered Storage category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 AI Powered Storage Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. AI Powered Storage Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the AI Powered Storage market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 AI Powered Storage Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 AI Powered Storage Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 AI Powered Storage Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in AI Powered Storage (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New AI Powered Storage Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global AI Powered Storage Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America AI Powered Storage Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe AI Powered Storage Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific AI Powered Storage Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America AI Powered Storage Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East AI Powered Storage Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa AI Powered Storage Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. AI Powered Storage Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
