
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Air Traffic Management Market Size 2024 | USD 9,365 million |
| Air Traffic Management Market, CAGR | 8.4% |
| Air Traffic Management Market Size 2032 | USD 17,854.2 million |
Market Overview
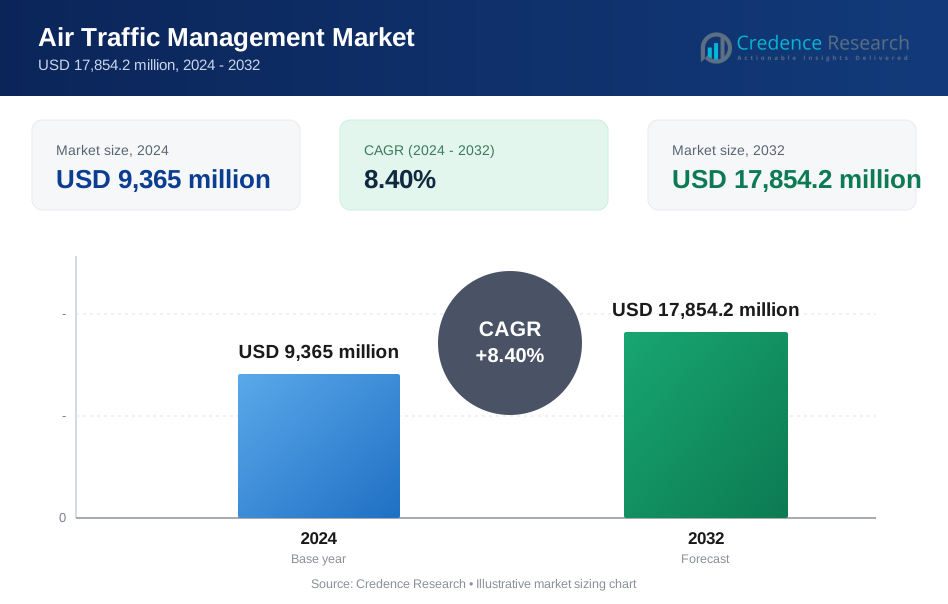
The air traffic management market is projected to grow from USD 9,365 million in 2024 to USD 17,854.2 million by 2032, registering a compound annual growth rate (CAGR) of 8.4% during the forecast period.
The air traffic management (ATM) market is driven by the rising demand for air travel, increasing fleet size, and the need to enhance operational efficiency and safety across global airspace. Governments and aviation authorities are investing heavily in modernizing ATM infrastructure with next-generation technologies such as satellite-based navigation, performance-based navigation (PBN), and automation systems to handle growing air traffic volumes. The integration of artificial intelligence (AI), machine learning, and big data analytics is improving real-time decision-making, traffic flow optimization, and predictive maintenance. Additionally, the growing emphasis on reducing carbon emissions and enhancing fuel efficiency is accelerating the adoption of advanced ATM solutions, including trajectory-based operations and digital towers. Unmanned aircraft system traffic management (UTM) is also emerging as a critical segment, driven by the increasing use of drones for commercial and logistics applications. These trends, combined with cross-border collaborations and regulatory support, are transforming the ATM landscape and creating opportunities for innovation and global market expansion.
The air traffic management market spans key regions including North America, Europe, Asia Pacific, and others such as Latin America and the Middle East & Africa. North America leads with strong federal investments and advanced aviation infrastructure, while Europe follows with regulatory initiatives like the Single European Sky. Asia Pacific is rapidly expanding due to surging air traffic in China and India. Latin America and the Middle East & Africa show gradual growth through airport modernization projects and regional cooperation. Across these regions, leading players such as Thales S.A., RTX Corporation, Indra Sistemas, Saab AB, Airbus SE, Honeywell International Inc., L3Harris Technologies, Leidos Holdings, Leonardo S.p.A., and Frequentis AG play a central role in delivering integrated, next-generation air traffic solutions tailored to both mature and emerging aviation markets. These companies actively compete through technological innovation, partnerships, and customized regional deployments.
Market Insights
- The air traffic management market is projected to grow from USD 9,365 million in 2024 to USD 17,854.2 million by 2032, at a CAGR of 8.4%.
- Rising global air travel, increased fleet sizes, and the need for efficient airspace use are driving strong demand for ATM systems.
- Governments are investing in advanced technologies like satellite-based navigation, PBN, AI, and automation to modernize infrastructure.
- Integration of unmanned aircraft systems and drone traffic management presents new growth avenues in both commercial and logistics sectors.
- North America leads the market with a 34% share, followed by Europe at 28% and Asia Pacific at 24%, driven by modernization and regulatory initiatives.
- High infrastructure costs and complex legacy system upgrades pose challenges, especially in developing regions and multi-stakeholder environments.
- Leading players including Thales, RTX, Indra, Saab, Airbus, Honeywell, L3Harris, Leidos, Leonardo, and Frequentis are advancing innovation, regional strategies, and partnerships.
Market Drivers
Surge in Global Air Travel and Passenger Volumes
The air traffic management market is expanding due to the consistent rise in global air travel and passenger traffic. More people are flying for business, tourism, and migration, increasing the pressure on aviation infrastructure. Airlines are adding new routes and increasing flight frequencies, which requires efficient traffic coordination. Governments and airport authorities are upgrading systems to prevent congestion. It supports demand for advanced air traffic control systems. Investment in airport expansions further supports market growth.
- For instance, Aireon and the Airport Authority of India (AAI) partnered in 2023 to pilot real-time Unmanned Traffic Management (UTM) using satellite-based surveillance, enhancing safety and coordination for both manned and unmanned aircraft in Indian airspace.
Modernization of Legacy Infrastructure and Systems
Aging air traffic control infrastructure has become inefficient in managing today’s complex airspace requirements. The air traffic management market is responding through large-scale modernization programs across major airports and regions. Advanced radar, surveillance, and automation systems are replacing outdated technologies. It enables faster response times and improved situational awareness. System upgrades are also focused on integrating commercial drones and new aircraft types. These enhancements boost operational efficiency and flight safety significantly.
- For instance, the Federal Aviation Administration (FAA) is replacing 618 legacy radars and installing new fiber, wireless, and satellite technologies at over 4,600 sites as part of its multi-billion-dollar National Airspace System overhaul, with a target completion date of 2028.
Emphasis on Safety, Efficiency, and Airspace Optimization
Ensuring passenger safety while optimizing airspace usage has become a priority for aviation stakeholders. The air traffic management market is benefiting from global efforts to enhance safety margins and reduce delays. Authorities are adopting performance-based navigation and communication systems to streamline routes. It enables more direct paths and minimizes fuel consumption. These upgrades reduce both environmental impact and operational costs. Strategic airspace design is becoming central to national aviation policies.
Technological Integration and Digital Transformation
Cutting-edge technologies like AI, IoT, and cloud computing are transforming the air traffic management market. Integration of data analytics allows real-time traffic monitoring and predictive maintenance. It improves decision-making accuracy and enhances capacity management. Digital towers and remote ATC systems are reshaping air traffic control operations. These technologies also support unmanned aerial vehicle (UAV) integration. Countries are prioritizing innovation to meet future aviation demands and achieve sustainable traffic management.
Market Trends
Rising Adoption of Satellite-Based Navigation and Communication Systems
The air traffic management market is witnessing a major shift toward satellite-based navigation and communication systems. These technologies offer higher accuracy, wider coverage, and reduced dependency on ground infrastructure. Countries are implementing performance-based navigation (PBN) to improve routing and flight efficiency. It supports smoother takeoffs, landings, and en-route operations. These upgrades contribute to reduced fuel usage and emissions. Adoption of GNSS and ADS-B continues to replace conventional radar-based systems.
- For instance, Delta Air Lines has equipped its fleet with ADS-B transponders, allowing real-time satellite-based aircraft tracking for improved air traffic management.
Growth of Remote and Digital Air Traffic Control Towers
Remote and digital towers are gaining traction as cost-effective and flexible solutions for airport operations. The air traffic management market is evolving with the deployment of high-definition cameras, sensors, and data transmission systems. It enables air traffic control services to operate from centralized or off-site locations. This trend improves scalability for smaller or regional airports. Enhanced situational awareness and operational continuity are key benefits. Governments are investing in these systems for long-term efficiency.
- For instance, Sweden’s Scandinavian Mountains Airport is fully operated from a remote tower in Sundsvall.
Increased Emphasis on System Interoperability and Global Harmonization
Aviation authorities are focusing on system interoperability to ensure seamless air traffic operations across regions. The air traffic management market is aligning with international standards to support cross-border coordination. Harmonization of procedures, communication protocols, and data sharing is essential for global airspace integration. It reduces complexity in managing international flights. Collaborative frameworks between nations and regulatory bodies are enabling this trend. This approach enhances safety and reduces delays across busy flight corridors.
Integration of Unmanned Aircraft Systems into Controlled Airspace
Unmanned aircraft system (UAS) integration is becoming a critical focus area for the air traffic management market. Governments and agencies are developing frameworks to accommodate drones in civilian airspace. It requires real-time tracking, traffic segregation, and communication protocols. Urban air mobility and drone delivery services are accelerating the need for UTM solutions. Traditional ATM systems are being upgraded to manage this complexity. The shift is reshaping airspace management strategies worldwide.
Market Challenges Analysis
High Costs and Complexity of Infrastructure Modernization
Modernizing air traffic control infrastructure involves significant capital investment and technical complexity. The air traffic management market faces challenges in upgrading outdated systems while maintaining uninterrupted operations. Budget constraints in developing regions often delay adoption of next-generation solutions. It requires long planning cycles, regulatory approvals, and skilled personnel to implement advanced technologies. Coordinating between multiple stakeholders, including airports, airlines, and governments, adds to the difficulty. Integration with legacy systems further complicates the modernization process.
Cybersecurity Threats and Data Privacy Concerns
Increasing reliance on digital platforms exposes the air traffic management market to cybersecurity risks. Air traffic systems process vast volumes of real-time data, making them targets for cyberattacks. It demands robust security protocols and constant monitoring to safeguard sensitive information. Breaches could disrupt operations, compromise safety, and damage public trust. The challenge lies in balancing system openness for interoperability with strong data protection. Addressing these risks requires ongoing investment in cybersecurity infrastructure and talent.
Market Opportunities
Expansion of Urban Air Mobility and Drone Traffic Management
Urban air mobility (UAM) is creating new pathways for growth in the air traffic management market. The rise of electric vertical takeoff and landing (eVTOL) aircraft and drone delivery systems demands new traffic coordination frameworks. It opens opportunities for developing unmanned traffic management (UTM) solutions tailored to low-altitude operations. Governments and private companies are collaborating to define airspace usage rules and build digital infrastructure. This emerging segment requires flexible, scalable, and automated traffic control systems.
Deployment of Artificial Intelligence and Predictive Analytics
Artificial intelligence offers strong potential to optimize decision-making and reduce operational inefficiencies in the air traffic management market. It enables real-time data analysis for flight path optimization, congestion prediction, and incident response. Integration of AI-driven systems can lower controller workload and improve safety margins. It also supports dynamic airspace management through scenario simulation and adaptive rerouting. The opportunity lies in applying machine learning tools to enhance situational awareness. This transformation can redefine traditional air traffic control models.
Market Segmentation Analysis:
By Airspace
The air traffic management market is segmented by airspace into Air Traffic Services (ATS), Air Traffic Flow Management (ATFM), Airspace Management (ASM), and Aeronautical Information Management (AIM). ATS holds a major share due to its central role in ensuring flight safety and efficient routing. ASM and AIM are gaining importance with increasing demand for structured airspace usage and real-time data sharing. It reflects a growing focus on integrating digital solutions into traditional control environments. ATFM is expanding to reduce congestion and improve airspace efficiency.
- For instance, SITA’s blockchain-based solutions are deployed to secure and streamline data sharing in aeronautical information management, ensuring the integrity of sensitive records and enabling seamless airport operations.
By Investment Type
By investment type, the market is divided into new installation and modernization & upgradation. Modernization & upgradation dominates due to aging infrastructure and the need for compliance with new aviation standards. The air traffic management market is seeing large-scale retrofitting of legacy systems with advanced technologies. New installations are rising in developing regions, supported by expanding airport networks. It indicates a dual trend of technological advancement and infrastructure expansion worldwide.
- For instance, Metron Aviation partnered with Celestial to upgrade three core air traffic management applications to the latest Ext JS framework, enabling new features and automation that improve operational efficiency and system reliability.
By Application
By application, the market includes communication, navigation, surveillance, and automation. Communication systems lead the segment, driven by the demand for real-time pilot-controller interaction and data exchange. Automation is gaining traction through AI and machine learning integration in control systems. The air traffic management market is adopting automation to reduce controller workload and improve operational accuracy. Navigation and surveillance technologies are also evolving to enhance situational awareness and aircraft tracking in dense and complex airspace.
Segments:
Based on Airspace
- Air Traffic Services (ATS)
- Air Traffic Flow Management (ATFM)
- Airspace Management (ASM)
- Aeronautical Information Management (AIM)
Based on Investment Type
- New Installation
- Modernization & Upgradation
Based on Application
- Communication
- Navigation
- Surveillance
- Automation
Based on End Use
- Commercial
- Military
Based on Offering
- Hardware
- Software & Solutions
Based on Service
- ATM as a service
- Maintenance Service
- Support Service
Based on Airport Size
- Large
- Medium
- Small
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest share of the air traffic management market, accounting for 34% in 2024. The region benefits from a well-established aviation infrastructure, high air traffic volume, and significant government investments in modernization. The Federal Aviation Administration (FAA) is leading major initiatives to upgrade air traffic systems through programs like NextGen. It supports the integration of satellite-based navigation and digital communication platforms. The presence of leading technology providers further strengthens innovation and deployment. The U.S. and Canada are focusing on system automation and unmanned aircraft integration.
Europe
Europe captures 28% of the air traffic management market, driven by cross-border cooperation and strict regulatory frameworks. The Single European Sky (SES) initiative promotes harmonized ATM systems across member states. It aims to optimize airspace usage, reduce delays, and enhance flight safety. Countries are investing in sustainable ATM solutions to meet climate goals and improve fuel efficiency. Technological advancements in digital towers and AI-powered decision support tools are gaining traction. Key players in the region are also expanding their capabilities to manage rising drone activity.
Asia Pacific
Asia Pacific represents 24% of the air traffic management market, fueled by rapid growth in commercial aviation and expanding airport infrastructure. China and India are investing heavily in modernizing their air navigation systems to support rising passenger volumes. It creates strong demand for advanced surveillance, communication, and automation solutions. Regional governments are prioritizing safety, efficiency, and capacity enhancement. Collaborative efforts are underway to standardize ATM operations across borders. Increasing drone usage and smart city development are adding new dimensions to regional airspace management.
Key Player Analysis
- Indra Sistemas, S.A.
- Saab AB
- RTX Corporation
- Airbus SE
- Frequentis AG
- Honeywell International Inc.
- L3Harris Technologies, Inc.
- Leidos Holdings, Inc.
- Leonardo S.p.A.
- Thales S.A.
Competitive Analysis
The air traffic management market features a competitive landscape dominated by global technology and defense firms that deliver advanced solutions for communication, navigation, surveillance, and automation. Key players include Indra Sistemas, Saab AB, RTX Corporation, Airbus SE, Frequentis AG, Honeywell International Inc., L3Harris Technologies, Leidos Holdings, Leonardo S.p.A., and Thales S.A. These companies focus on innovation, system integration, and government partnerships to maintain leadership. The market is seeing increased investment in AI, cloud-based platforms, and remote tower technologies. It is encouraging strategic collaborations, acquisitions, and joint ventures to enhance service capabilities and global reach. Competitive differentiation depends on technological expertise, regulatory compliance, and the ability to support scalable, interoperable ATM systems across regions. Firms that can deliver secure, flexible, and future-ready solutions are better positioned to capitalize on growing modernization demands from both developed and emerging aviation markets.
Recent Developments
- In May 2025, Aireon partnered with Thales to integrate AireonFLOW into Thales’ TopSky Flow Manager, aiming to enhance air traffic efficiency, reduce congestion, and support sustainable flight operations.
- In January 2024, EasyJet became the first airline partner of the Iris program-an initiative by the European Space Agency (ESA) and Viasat-which leverages next-generation satellite technologies to modernize air traffic management systems.
- In October 2023, Biju Patnaik International Airport in Bhubaneswar, Odisha, implemented a new air traffic management automation system at its upgraded control center, boosting operational efficiency and flight management capabilities.
- In July 2023, Skykraft Pvt Ltd completed its first successful trial of space-based VHF voice communications, a major step in its satellite program focused on providing aviation-specific space-based communication and surveillance solutions.
Market Concentration & Characteristics
The air traffic management market is moderately concentrated, with a few global players dominating through technological leadership, large-scale contracts, and long-standing relationships with government agencies and aviation authorities. It features high entry barriers due to regulatory complexity, infrastructure demands, and the need for certified, safety-critical systems. The market is characterized by long development cycles, integration with legacy infrastructure, and a strong emphasis on reliability and interoperability. Leading firms compete on innovation, offering advanced solutions in automation, AI integration, satellite navigation, and unmanned traffic management. Governments and defense agencies heavily influence procurement decisions, shaping market dynamics through policy and investment priorities. It also reflects a high level of customization, with vendors tailoring solutions to specific regional needs and traffic environments. Vendor consolidation, strategic partnerships, and joint ventures are common, enabling broader geographic reach and technology synergies. The competitive landscape favors companies with proven track records, strong R&D capabilities, and a focus on long-term operational support.
Report Coverage
The research report offers an in-depth analysis based on Airspace, Investment Type, Application, End-Use, Offering, Service, Airport Size and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Governments will continue prioritizing modernization of air traffic systems to improve safety and efficiency.
- Integration of AI and machine learning will enhance decision-making and traffic flow optimization.
- Unmanned aircraft system traffic management will become a core focus due to rising drone usage.
- Remote and digital towers will gain adoption, especially at regional and low-traffic airports.
- Cross-border harmonization efforts will strengthen interoperability of air traffic control systems.
- Investment in automation will reduce controller workload and increase real-time response capabilities.
- Urban air mobility will drive the development of new low-altitude traffic management frameworks.
- Cloud-based infrastructure and data analytics will play a growing role in system operations.
- Cybersecurity will remain a critical area of investment to protect airspace management systems.
- Regional expansion in Asia Pacific and the Middle East will open new growth opportunities for vendors.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Surge in Global Air Travel and Passenger Volumes
Increasing numbers of passengers and flights worldwide are straining existing airspace and airport infrastructure, necessitating advanced air traffic management systems to ensure safety, efficiency, and reduced congestion.
Modernization of Legacy Infrastructure and Systems
Aging air traffic control systems are being replaced or upgraded with next-generation technologies such as automation, satellite-based navigation, and digital communication to meet current and future airspace demands.
Emphasis on Safety, Efficiency, and Airspace Optimization
Aviation authorities are prioritizing performance-based navigation, real-time data sharing, and optimized airspace design to enhance safety margins, minimize delays, and reduce operational costs.
Technological Integration and Digital Transformation
The adoption of AI, machine learning, cloud computing, and big data analytics is enabling real-time decision-making, predictive maintenance, and improved traffic flow management, transforming traditional ATM operations.
Integration of Unmanned Aircraft Systems (UAS) and Urban Air Mobility
The rapid growth of drones and urban air mobility solutions is driving the need for new traffic management frameworks and unmanned traffic management (UTM) systems, expanding the scope and complexity of air traffic management.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Air Traffic Management market?
What are the key segments within the Air Traffic Management market?
What are some challenges faced by the Air Traffic Management market?
Who are the major players in the Air Traffic Management market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Commercial
- 1.2.2 Military
- 1.3 By Airspace
- 1.3.1 Air Traffic Services (ATS)
- 1.3.2 Air Traffic Flow Management (ATFM)
- 1.3.3 Airspace Management (ASM)
- 1.3.4 Aeronautical Information Management (AIM)
- 1.4 By Application
- 1.4.1 Communication
- 1.4.2 Navigation
- 1.4.3 Surveillance
- 1.4.4 Automation
- 1.5 By Investment Type
- 1.5.1 New Installation
- 1.5.2 Modernization & Upgradation
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 9,365 million → 2032: USD 17,854.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Air Traffic Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Air Traffic Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Air Traffic Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Air Traffic Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Air Traffic Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Air Traffic Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Air Traffic Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Air Traffic Management Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 9,365 million → 2032: USD 17,854.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Air Traffic Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Commercial
- 12.3.7.2 Military
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Airspace - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Air Traffic Services (ATS)
- 12.4.7.2 Air Traffic Flow Management (ATFM)
- 12.4.7.3 Airspace Management (ASM)
- 12.4.7.4 Aeronautical Information Management (AIM)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Communication
- 12.5.7.2 Navigation
- 12.5.7.3 Surveillance
- 12.5.7.4 Automation
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Investment Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 New Installation
- 12.6.7.2 Modernization & Upgradation
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Air Traffic Management End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Air Traffic Management Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Air Traffic Management Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Air Traffic Management Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Thales S.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 RTX Corporation
- 18.4 Indra Sistemas, S.A.
- 18.5 Saab AB
- 18.6 Airbus SE
- 18.7 Honeywell International Inc.
- 18.8 L3Harris Technologies, Inc.
- 18.9 Leidos Holdings, Inc.
- 18.10 Leonardo S.p.A.
- 18.11 Frequentis AG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

