
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Aircraft Cameras Market Size 2024 | USD 90.9 million |
| Aircraft Cameras Market, CAGR | 4.62% |
| Aircraft Cameras Market Size 2032 | USD 130.46 million |
Market Overview:
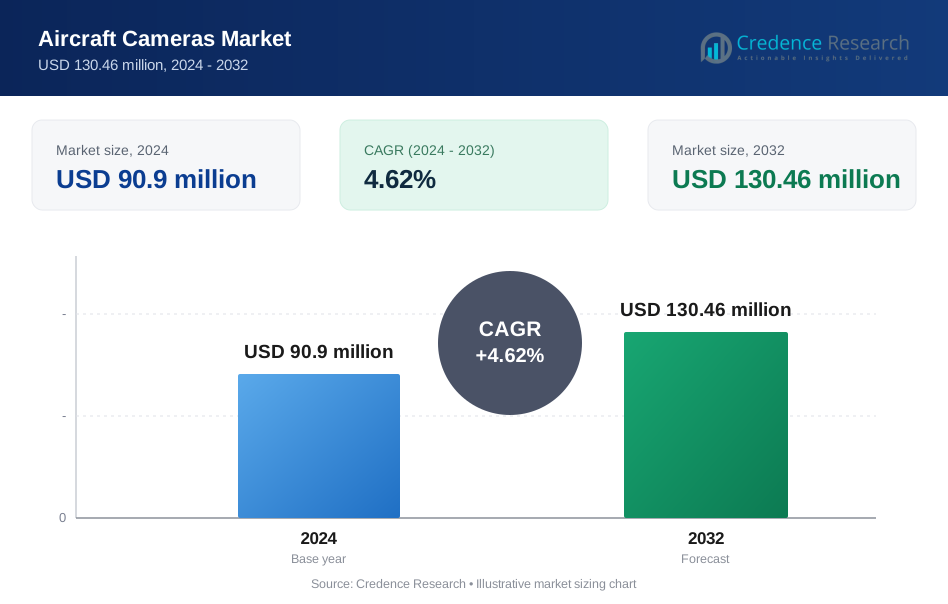
The Aircraft Cameras Market is projected to grow from USD 90.9 million in 2024 to an estimated USD 130.46 million by 2032, with a compound annual growth rate (CAGR) of 4.62% from 2024 to 2032.
The increasing demand for safety, surveillance, and real-time monitoring in the aviation industry is a key driver behind this growth. As airlines and aircraft manufacturers focus on enhancing flight safety, cameras are becoming critical for providing live footage for both operational monitoring and post-flight analysis. One of the primary factors contributing to the expansion of the aircraft cameras market is the rise in air traffic and the need for advanced safety solutions to prevent accidents and ensure passenger security. Additionally, the adoption of new technologies, including enhanced camera systems that integrate with aircraft systems, is driving market growth. These systems are used for a variety of purposes, including monitoring the interior and exterior of aircraft, capturing real-time video of flight conditions, and providing support during maintenance and troubleshooting. The growing emphasis on passenger experience and customer safety is also pushing airlines to equip their aircraft with more advanced camera systems. These systems not only help with in-flight monitoring but also assist in improving overall operational efficiency by providing critical data for predictive maintenance and troubleshooting.
Regionally, North America is expected to hold a significant share of the aircraft cameras market due to the presence of major airlines, aircraft manufacturers, and stringent safety regulations in the region. The European market is also expected to grow steadily, driven by increasing demand for advanced aircraft surveillance and the adoption of next-generation aircraft technologies. Asia Pacific is expected to witness rapid growth, particularly in countries like China and India, where the expansion of the aviation industry is driving the demand for high-tech aviation solutions.
cr_cta type="download_free_sample"]
Market insights:
- The Aircraft Cameras Market is projected to grow from USD 90.9 million in 2024 to USD 130.46 million by 2032, with a CAGR of 4.62%.
- Increasing air traffic and growing concerns about flight safety are driving the demand for advanced camera systems in aircraft for real-time monitoring and surveillance.
- Technological advancements in camera systems, such as AI and integration with aircraft systems, are enhancing operational efficiency and maintenance procedures.
- The market faces challenges from the high initial cost of advanced camera systems and potential regulatory hurdles in certain regions.
- Airlines are increasingly prioritizing passenger safety and operational efficiency, prompting them to invest in high-quality camera solutions for both interior and exterior monitoring.
- North America holds a significant share of the market due to its strong aviation industry, stringent safety regulations, and the presence of major aircraft manufacturers.
- Asia Pacific is expected to witness the fastest growth in the aircraft cameras market, driven by the expanding aviation sector in countries like China and India.
Market Drivers:
Increasing Focus on Aviation Safety:
The growing emphasis on aviation safety is a major driver for the aircraft cameras market. As air traffic volumes rise globally, governments and regulatory bodies are tightening safety protocols to ensure the well-being of passengers and crew. The International Civil Aviation Organization (ICAO) has set global standards for flight safety, urging airlines to incorporate advanced monitoring systems into their fleets. The increasing number of incidents and near-misses in aviation also drives the demand for real-time surveillance and monitoring technologies. According to the U.S. Federal Aviation Administration (FAA), there was a 15% increase in aviation safety-related investigations between 2020 and 2022.
Technological Advancements in Camera Systems:
The rapid advancement in camera technology, including high-resolution imaging, infrared cameras, and AI-based analytics, has revolutionized the aviation industry. Governments and private organizations are collaborating to integrate these technologies into aircraft for enhanced surveillance, predictive maintenance, and better in-flight monitoring. For example, according to the European Space Agency (ESA), satellite-based surveillance and monitoring systems, which incorporate advanced camera technologies, are becoming increasingly essential for air traffic management. The European Union Aviation Safety Agency (EASA) has collaborated with major airlines to improve in-flight data collection and real-time surveillance, enabling proactive maintenance and reducing downtime.
Regulatory Push and Safety Compliance:
Governments around the world are pushing for stricter safety regulations, compelling airlines to adopt advanced camera systems. The International Air Transport Association (IATA) and the FAA have set stringent guidelines for surveillance and monitoring systems in aircraft. The FAA has issued several directives mandating the installation of enhanced camera systems for aircraft monitoring, especially in commercial aviation. For example, in 2022, the U.S. Department of Transportation emphasized the integration of camera systems in flight data monitoring for commercial airlines to meet enhanced safety protocols. As the aviation industry faces increasing pressure from regulatory bodies to comply with international safety standards, airlines are increasingly adopting technologies that can improve operational safety and regulatory compliance.
Rising Demand for Predictive Maintenance:
The growing focus on predictive maintenance in the aviation sector is another major driver for the aircraft cameras market. With airlines operating under tight schedules and facing pressure to minimize operational costs, predictive maintenance powered by camera systems has become an essential tool. For instance, the U.S. Department of Transportation's Bureau of Transportation Statistics reported that in 2022, over 30% of all unscheduled aircraft maintenance events were due to mechanical failures that could have been prevented with advanced surveillance systems. As a result, many airlines, such as Delta Air Lines and Lufthansa, have partnered with technology firms to install advanced cameras that can detect early signs of equipment failure, reducing unplanned maintenance and improving flight scheduling.
Market Trends:
Integration of AI and Machine Learning for Enhanced Surveillance:
The integration of artificial intelligence (AI) and machine learning (ML) into aircraft cameras is transforming the industry by enabling smarter surveillance and maintenance systems. These technologies allow for real-time data processing and anomaly detection, enhancing flight safety and reducing the need for manual monitoring. AI and ML are particularly effective in identifying potential risks, such as mechanical issues, before they become critical. For instance, The U.S. Department of Transportation (DOT) allocated a $5 million budget in 2023 for research and development of AI-driven systems that integrate with aircraft cameras. This funding aims to improve real-time hazard detection, surveillance, and predictive maintenance capabilities within the aviation industry, showcasing how AI can automate safety monitoring and help prevent incidents.
Adoption of 360-Degree Cameras for Comprehensive Coverage:
360-degree cameras are increasingly being integrated into aircraft for complete monitoring of both the interior and exterior of the aircraft. These advanced camera systems offer more comprehensive coverage and enable airlines to monitor all aspects of an aircraft's condition during flight. These systems can enhance security, monitor the health of the aircraft, and provide critical data for maintenance. For instance, in 2021, the European Union Aviation Safety Agency (EASA) invested €10 million to support the development and adoption of advanced 360-degree camera systems for commercial aircraft. This technology provides enhanced situational awareness by allowing real-time monitoring from all angles, contributing to a reduction in maintenance costs and improving flight safety by identifying potential issues before they escalate.
Increasing Demand for In-Flight Monitoring Solutions:
The growing demand for in-flight monitoring systems is another key trend in the aircraft cameras market. These systems allow airlines to continuously monitor the aircraft's exterior and interior, helping them improve safety standards and streamline maintenance operations. With enhanced in-flight data capture, airlines can take proactive measures to address mechanical issues before they cause delays or safety concerns. For instance, the U.S. Federal Aviation Administration (FAA) issued a directive in 2022 that required all newly manufactured commercial aircraft to be equipped with advanced in-flight surveillance cameras. Additionally, the FAA allocated $8 million in grants to support the installation of these systems across U.S. airlines, highlighting the increasing importance of in-flight monitoring for both safety and operational efficiency.
Government Investment in Aircraft Surveillance Technologies:
Governments across the world are making substantial investments in aircraft surveillance technologies, reflecting the growing concern about aviation safety and the need to comply with international aviation regulations. These investments are fueling the adoption of advanced camera systems and data analytics tools that support real-time decision-making. The U.K. Civil Aviation Authority (CAA) allocated £4.5 million in 2023 to enhance camera surveillance systems in both airports and on aircraft. This funding is aimed at supporting the development and deployment of more sophisticated camera technologies that will improve aviation safety, increase regulatory compliance, and reduce operational risks.
Market Challenge Analysis:
High Initial Cost and Installation Complexity:
One of the significant challenges facing the aircraft cameras market is the high initial cost of advanced camera systems and their installation. Modern camera technologies, such as 360-degree and AI-driven systems, require significant investment in both equipment and infrastructure. The cost of acquiring and integrating these systems into existing aircraft fleets can be a barrier, especially for smaller airlines with limited budgets. Additionally, the installation process is complex, often requiring modifications to the aircraft's design, which further increases operational costs and downtime. For instance, the U.S. Federal Aviation Administration (FAA) has noted that retrofitting older aircraft with advanced camera systems can incur costs in the range of several million dollars per fleet, creating a financial burden for airlines that are already managing tight budgets.
Regulatory and Compliance Challenges:
The regulatory landscape for aviation safety and surveillance is continuously evolving, presenting challenges for manufacturers and airlines in terms of compliance. Governments and aviation authorities, such as the International Civil Aviation Organization (ICAO) and the Federal Aviation Administration (FAA), periodically update safety standards and surveillance requirements, which necessitate constant adaptation of camera systems. This can result in additional costs for airlines to meet new compliance standards or to upgrade existing systems. The European Union Aviation Safety Agency (EASA) introduced new regulations in 2021 requiring enhanced monitoring capabilities in commercial aircraft, compelling airlines to invest in upgraded camera systems and retrofit their fleets. This regulatory burden, along with the associated costs of compliance, can be a barrier to the widespread adoption of advanced camera technologies across the aviation sector.
Market Opportunities:
The aircraft cameras market presents significant opportunities for growth driven by increasing demand for advanced safety and monitoring systems in aviation. As air traffic continues to rise globally, airlines and aircraft operators are under greater pressure to enhance safety measures and operational efficiency. The integration of innovative camera technologies, such as AI-based surveillance systems and 360-degree cameras, offers a promising avenue for airlines to meet regulatory requirements while improving flight safety. Governments and regulatory bodies worldwide, such as the U.S. Federal Aviation Administration (FAA) and European Union Aviation Safety Agency (EASA), are pushing for enhanced safety standards, creating a favorable environment for the adoption of these technologies. This shift presents a strong market opportunity for manufacturers to develop and offer advanced camera solutions that provide real-time data for improved monitoring, predictive maintenance, and flight security.
Moreover, the increasing emphasis on predictive maintenance within the aviation sector opens up new avenues for growth. Airlines are seeking ways to reduce unscheduled maintenance and improve operational efficiency, and the integration of camera systems capable of identifying mechanical issues before they escalate is a critical solution. For example, AI-powered cameras that detect potential equipment failures offer airlines the opportunity to reduce costly downtime and enhance flight scheduling. The growing focus on sustainability and cost-cutting within the industry further strengthens the demand for such technologies, positioning the market for steady expansion. As airlines increasingly invest in digital solutions, manufacturers have an opportunity to develop innovative products that can support this transformation and improve overall operational safety and efficiency.
Market Segmentation Analysis:
By Type:
External cameras are primarily used for surveillance, monitoring, and navigation purposes, offering real-time imaging of the aircraft’s surroundings. These systems are crucial for ensuring safety, especially in challenging weather conditions or during landings and take-offs. They are gaining traction in both commercial and military sectors, driven by the increasing demand for enhanced situational awareness and real-time decision-making capabilities. Internal cameras, on the other hand, focus on providing in-cabin security, monitoring passengers, and facilitating cockpit visibility. These cameras are integral to commercial aircraft for both safety compliance and passenger management.
By Application:
The commercial aircraft segment is experiencing substantial growth, particularly in narrow-body and wide-body aircraft, which require efficient monitoring and enhanced safety. These aircraft benefit from both internal and external camera systems to improve navigation, security, and operational efficiency. Military aircraft, including fighter jets and transport planes, require specialized camera systems that offer superior surveillance, reconnaissance, and threat detection. Military helicopters and special mission aircraft also demand high-performance imaging systems capable of functioning under extreme conditions, driving innovation in camera technology.
Segmentation:
Based on Type:
- External Cameras
- Internal Cameras
Based on Application:
-
- Narrow-Body
- Wide-Body
- Regional Jets
- Turboprop/Helicopters
- Commercial Aircrafts
Based on Military Aircrafts
-
- Fighter Aircraft
- Transport Aircraft
- Special Mission Aircraft
- Military Helicopters
Regional:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the aircraft cameras market, accounting for approximately 35% of the global market. The growth in this region is driven by the increasing demand for advanced safety and surveillance systems, particularly in the commercial aviation sector. The presence of major aerospace and defense companies such as Honeywell, Collins Aerospace, and FLIR Systems has significantly contributed to market expansion. Additionally, North America's military sector remains a key driver, with ongoing investments in next-generation surveillance technologies for fighter jets, transport aircraft, and special mission aircraft. For instance, the U.S. Department of Defense continues to prioritize advanced imaging systems for situational awareness and threat detection in various military aircraft.
Europe
Europe represents a significant portion of the aircraft cameras market, holding around 25% of the global market share. The region is home to key aerospace players like Airbus, Leonardo, and Safran, which have contributed to the growth of the market. The demand for aircraft cameras in Europe is largely driven by the increasing need for enhanced security and operational efficiency in commercial aviation. European airlines are increasingly investing in high-definition external and internal camera systems to ensure passenger safety and improve navigation. For instance, the UK Ministry of Defence is implementing new surveillance technologies in its fleet of fighter jets and transport aircraft to enhance operational capabilities.
Asia Pacific
The Asia Pacific region is experiencing rapid growth in the aircraft cameras market, accounting for 30% of the global market share. The demand for aircraft cameras in this region is primarily driven by the booming aviation industry in countries like China, India, and Japan. As air travel in these nations continues to expand, both commercial and military sectors are increasingly adopting advanced camera systems to enhance safety, security, and operational efficiency. For instance, China’s growing defense capabilities and modernization of military aircraft are fueling the need for high-performance camera systems. The commercial aviation sector in India, with a rising number of domestic and international flights, is also investing in advanced surveillance technologies to meet global safety standards.
Key Player Analysis:
- AD Aerospace
- Cabin Avionics
- Collins Aerospace
- Eirtech Aviation Services
- Elbit Systems
- Kappa Optronics
- KID-Systeme
- Latecoere
- Meggitt
- Northrop Grumman
Competitive Analysis:
The aircraft cameras market is highly competitive, driven by increasing demand for advanced surveillance, safety, and navigation systems in aviation. Key players, including Flir Systems, Collins Aerospace, and Honeywell, dominate the market with a diverse portfolio of high-resolution, infrared, and multi-spectral cameras tailored for both commercial and military applications. Technological advancements such as AI-powered analytics, real-time imaging, and integration with unmanned aerial vehicles (UAVs) are further intensifying competition. Market growth is also fueled by rising concerns over aviation safety, security, and the growing need for enhanced situational awareness in flight operations. However, the high cost of advanced systems and the complexity of integration into existing aircraft infrastructure present challenges for new entrants. To maintain a competitive edge, companies are increasingly focusing on product innovation, strategic partnerships, and expanding their presence in emerging markets, particularly in Asia-Pacific, where aviation growth is robust.
Recent Developments:
- In January 2024, the Air Forces of Queensland added a new EC135 helicopter to their fleet, enhancing their police air operations. The aircraft, now stationed in Townsville, comes equipped with advanced features, including infrared cameras, powerful searchlights, moving mapping systems, and aircraft-mounted vehicle tracking systems. These upgrades will significantly improve operational capabilities and support a wide range of critical missions.
- In 2023, Safran revealed its plans to acquire Collins Aerospace's actuation and flight control business for USD 1.8 billion, with the goal of becoming a global leader in these sectors. That same year, L3Harris Technologies successfully completed its acquisition of Aerojet Rocketdyne, integrating it as a fourth business segment. Post-acquisition, L3Harris boosted capital spending on Aerojet Rocketdyne by 84%, significantly enhancing its production capabilities.
- In 2024, the U.S. Securities and Exchange Commission (SEC) reported that RTX Corporation, formerly known as Raytheon Technologies Corp., agreed to pay over USD 124 million to settle charges related to violations of the Foreign Corrupt Practices Act (FCPA).
- Additionally, in 2024, Elbit Systems secured contracts worth approximately USD 335 million to supply defense systems to a European nation. These contracts include the delivery of PULS (Precise and Universal Launching Systems) rocket launchers, rockets, and Hermes 900 Unmanned Aircraft Systems (UAS) equipped with advanced payloads.
Market Concentration & Characteristics:
The aircraft cameras market exhibits moderate concentration, with a few major players commanding a significant share of the industry. Companies such as Flir Systems, Collins Aerospace, Honeywell, and L3 Technologies lead the market, leveraging their extensive technological expertise and established customer bases. However, the market is also characterized by the presence of several smaller, specialized players that focus on niche applications, such as infrared and multispectral imaging for military and surveillance purposes. The market is driven by advancements in high-definition imaging, real-time data processing, and the growing integration of artificial intelligence and machine learning in flight safety systems. Key characteristics include rapid technological evolution, high R&D investments, and increasing demand for customization and integration capabilities. Furthermore, the market is seeing a trend toward partnerships and collaborations, particularly between aircraft manufacturers and camera technology providers, to offer innovative, cutting-edge solutions that enhance safety and operational efficiency.
Report Coverage:
The research report offers an in-depth analysis based on By type, By Military Aircrafts, By Application, By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for advanced aircraft cameras will continue to rise due to growing safety and security concerns in aviation.
- Integration of AI and machine learning technologies will enable real-time data analysis, enhancing situational awareness during flight operations.
- Military applications will drive the development of high-performance, infrared, and multispectral imaging systems.
- Increased adoption of unmanned aerial vehicles (UAVs) will expand the market, requiring specialized camera solutions for drone applications.
- Enhanced camera systems will become standard in commercial and private aviation, improving navigation and cockpit visibility.
- Collaboration between aviation companies and camera technology providers will lead to innovative solutions tailored to specific aircraft requirements.
- Regulatory pressure for improved safety standards will push airlines to invest in advanced surveillance systems.
- The growth of smart airports will drive demand for aircraft cameras for surveillance and security monitoring on the ground.
- The Asia-Pacific region will see significant market expansion as the aviation industry experiences rapid growth.
- As technology progresses, the cost of advanced camera systems will decrease, making them more accessible to a broader range of aircraft operators.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Focus on Aviation Safety
As global air traffic rises, regulatory bodies and airlines are prioritizing advanced camera systems to enhance flight safety, real-time monitoring, and post-flight analysis, driving adoption across both commercial and military fleets.
Technological Advancements in Camera Systems
Rapid innovation in high-resolution imaging, infrared, 360-degree cameras, and AI-based analytics is enabling more effective surveillance, predictive maintenance, and operational efficiency, making advanced camera systems more attractive to aircraft operators.
Regulatory Push and Safety Compliance
Stricter international and regional safety regulations are compelling airlines to invest in upgraded camera systems to meet evolving compliance standards, particularly in North America and Europe where oversight is stringent.
Rising Demand for Predictive Maintenance
Airlines are increasingly leveraging camera systems for predictive maintenance to minimize unscheduled downtime and reduce operational costs, as these systems can detect early signs of equipment failure and support proactive interventions.
Expansion of Aviation in Emerging Markets
Rapid growth in air travel and fleet expansion in Asia Pacific and other emerging regions is fueling demand for advanced aircraft cameras, as operators seek to meet global safety standards and improve passenger security.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the aircraft cameras market?
What factors are driving the aircraft cameras market?
What are the key segments within the aircraft cameras market?
Who are the major players in the aircraft cameras market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 External Cameras
- 1.2.2 Internal Cameras
- 1.3 By Application
- 1.3.1 Narrow-Body Aircraft
- 1.3.2 Wide-Body Aircraft
- 1.3.3 Regional Jets
- 1.3.4 Turboprop/Helicopters
- 1.3.5 Commercial Aircraft
- 1.4 By Military Aircraft
- 1.4.1 Fighter Aircraft
- 1.4.2 Transport Aircraft
- 1.4.3 Special Mission Aircraft
- 1.4.4 Military Helicopters
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 90.9 million → 2032: USD 130.46 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Aircraft Cameras Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Aircraft Cameras Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Aircraft Cameras Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Aircraft Cameras Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Aircraft Cameras Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Aircraft Cameras Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Aircraft Cameras Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Aircraft Cameras Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 90.9 million → 2032: USD 130.46 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Aircraft Cameras Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 External Cameras
- 12.3.7.2 Internal Cameras
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Narrow-Body Aircraft
- 12.4.7.2 Wide-Body Aircraft
- 12.4.7.3 Regional Jets
- 12.4.7.4 Turboprop/Helicopters
- 12.4.7.5 Commercial Aircraft
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Military Aircraft - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Fighter Aircraft
- 12.5.7.2 Transport Aircraft
- 12.5.7.3 Special Mission Aircraft
- 12.5.7.4 Military Helicopters
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Aircraft Cameras End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Aircraft Cameras Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Aircraft Cameras Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Aircraft Cameras Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Collins Aerospace
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Honeywell
- 18.4 FLIR Systems
- 18.5 Elbit Systems
- 18.6 Kappa Optronics
- 18.7 Meggitt
- 18.8 Northrop Grumman
- 18.9 AD Aerospace
- 18.10 Safran
- 18.11 L3Harris Technologies
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

