
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Aircraft Carbon Brake Disc Market Size 2024 | USD 1194.5 Million |
| Aircraft Carbon Brake Disc Market, CAGR | 7.9% |
| Aircraft Carbon Brake Disc Market Size 2032 | USD 2194.61 Million |
Market Overview:
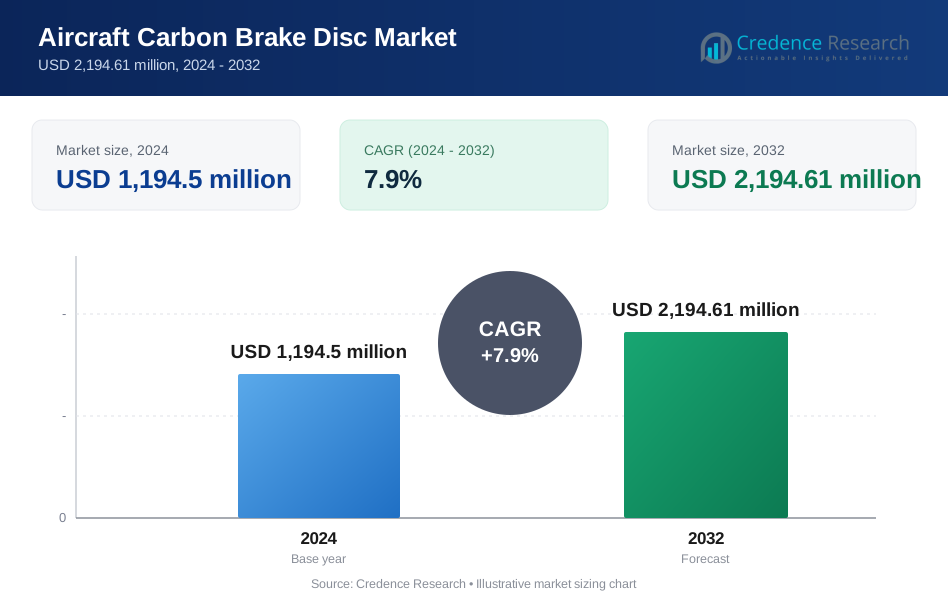
The Aircraft Carbon Brake Disc Market is projected to grow from USD 1194.5 million in 2024 to USD 2194.61 million by 2032, at a CAGR of 7.9% from 2024 to 2032.
Several factors contribute to the growth of the aircraft carbon brake disc market. Carbon brake discs offer numerous advantages over traditional metal counterparts, including higher durability, reduced weight, and improved performance, particularly in high-temperature environments. These benefits make them an attractive choice for modern commercial and military aircraft, where performance, safety, and efficiency are paramount. Furthermore, the adoption of carbon brake discs is gaining momentum due to their ability to significantly reduce maintenance costs over the lifespan of the aircraft. Additionally, the growth of the aviation industry, coupled with advancements in manufacturing technology, has enabled the production of more cost-effective carbon brake disc solutions. Moreover, the increasing focus on reducing carbon emissions and enhancing fuel efficiency in the aviation sector further fuels the adoption of carbon composite materials, contributing to market expansion.
Geographically, North America holds a prominent share of the aircraft carbon brake disc market, primarily driven by the strong presence of leading aircraft manufacturers, such as Boeing and Lockheed Martin, and a high demand for advanced aerospace technologies. The continuous investments in aerospace R&D by both government and private entities further bolster this growth. Europe also holds a significant market share, with countries like France, Germany, and the UK leading in aircraft production and defense contracts. Additionally, stringent regulatory standards related to safety and performance in Europe are fostering the adoption of innovative braking technologies. Meanwhile, the Asia-Pacific region is expected to witness the highest growth due to increasing investments in aviation infrastructure, particularly in emerging economies like China and India. As air traffic rises in these regions, the demand for efficient and reliable braking systems is expected to accelerate.
Market Insights:
- The Aircraft Carbon Brake Disc Market is projected to grow significantly from USD 1,194.5 million in 2024 to USD 2,194.61 million by 2032.
- Carbon brake discs offer superior advantages like higher durability, reduced weight, and improved performance in high-temperature environments, making them ideal for modern aircraft.
- The increasing focus on fuel efficiency and reducing carbon emissions is driving the adoption of carbon composite materials, further fueling market growth.
- North America holds the largest share, driven by leading aerospace companies like Boeing and Lockheed Martin, along with continuous R&D investments in the aerospace sector.
- Europe’s significant share is bolstered by stringent regulatory standards and demand from countries like France, Germany, and the UK in both commercial and military aircraft.
- The Asia-Pacific region is expected to witness the highest growth due to increasing investments in aviation infrastructure and rising air traffic in emerging economies like China and India.
- The high initial cost of carbon brake discs remains a challenge, but long-term maintenance savings and enhanced performance provide strong justification for the investment.
Market Drivers:
Technological Advancements in Aircraft Braking Systems:
One of the key drivers for the growth of the aircraft carbon brake disc market is the continuous advancement in braking technology. For instance, modern carbon brake discs from Safran Landing Systems and Honeywell Aerospace offer improved performance compared to traditional metal brake systems, particularly in high-temperature environments. These innovations provide airlines with enhanced safety and operational efficiency, ensuring a smoother, more reliable braking performance. As a result, the aviation industry increasingly favors carbon brake discs for both commercial and military aircraft.
Weight Reduction and Fuel Efficiency:
Carbon brake discs play a crucial role in reducing the overall weight of an aircraft. For example, Airbus and Boeing have incorporated lighter components that contribute to improved fuel efficiency, which is essential for airlines aiming to reduce operational costs and lower carbon emissions. As the aviation industry focuses on fuel economy and sustainable operations, carbon composite materials are increasingly adopted in aircraft braking systems. The reduced weight of carbon brake discs also leads to better performance, making them an attractive choice for modern aircraft designs.
Durability and Reduced Maintenance Costs:
The durability of carbon brake discs is another important factor driving their adoption. For instance, airlines such as Lufthansa and Emirates benefit from these discs offering lifespans and requiring less frequent maintenance compared to traditional metal brake systems. These discs offer longer lifespans and require less frequent maintenance compared to traditional metal brake systems. This results in lower maintenance costs and improved uptime for aircraft operators. With airlines and military organizations seeking to maximize the return on investment in their fleets, carbon brake discs provide a cost-effective solution by reducing the need for frequent replacements and maintenance.
Rising Demand for Commercial Aircraft:
The increasing global demand for commercial aircraft, driven by rising air travel, is another significant factor contributing to the market growth. For instance, airlines such as IndiGo and AirAsia expand their fleets to accommodate growing passenger traffic, and the demand for advanced braking technologies, including carbon brake discs, has surged. This trend is particularly pronounced in regions such as Asia-Pacific, where rapid economic development and rising disposable income are propelling air travel growth.
Market Trends:
Adoption of Lightweight Materials:
A prominent trend in the aircraft carbon brake disc market is the increased adoption of lightweight materials to enhance aircraft performance. For instance, carbon brake discs from Safran Landing Systems and Honeywell Aerospace are significantly lighter than traditional metal alternatives, which directly contributes to improved fuel efficiency and overall aircraft performance. As airlines and manufacturers prioritize fuel savings and sustainability, the use of lightweight materials such as carbon composites in braking systems has become increasingly common, especially in next-generation aircraft designs.
Integration of Advanced Manufacturing Techniques:
Another key trend is the integration of advanced manufacturing technologies to produce more cost-effective and reliable carbon brake discs. For instance, innovations such as additive manufacturing at Collins Aerospace and precision casting at Meggitt PLC enable manufacturers to create brake discs that meet the rigorous demands of modern aviation. These advanced techniques not only improve product quality but also reduce production costs, making carbon brake discs a more accessible option for both commercial and military applications.
Focus on Sustainability and Reduced Emissions:
Sustainability is a growing priority within the aviation industry, and carbon brake discs are seen as a solution to help reduce the environmental impact of air travel. For instance, carbon composite materials from Safran Landing Systems and Honeywell Aerospace are known for their high durability and low maintenance needs, which contribute to lowering the overall carbon footprint of an aircraft throughout its lifecycle. With global regulations pushing for reduced emissions and increased efficiency, the demand for carbon brake discs is aligned with the broader trend of sustainable aviation.
Customization and Integration with Aircraft Systems:
There is a growing trend towards the customization of carbon brake discs to meet the specific needs of various aircraft models. For instance, manufacturers like Collins Aerospace and Meggitt PLC are increasingly working with airlines such as American Airlines and aircraft producers like Airbus to tailor brake disc designs based on performance requirements, size, and other unique factors. This trend reflects the industry’s emphasis on integrating components that maximize the overall efficiency and safety of the aircraft, ensuring optimal braking performance in different operational environments.
Market Challenges Analysis:
High Initial Cost and Investment:
One of the primary challenges in the aircraft carbon brake disc market is the high initial cost associated with these advanced braking systems. Carbon brake discs are significantly more expensive than traditional metal alternatives due to the complex manufacturing processes and materials involved. This cost barrier can be a deterrent for smaller airlines or operators with budget constraints, especially in regions where price sensitivity is high. While the long-term cost benefits, such as reduced maintenance and longer lifespan, often justify the investment, the upfront financial commitment remains a challenge.
Limited Availability of Raw Materials:
The availability of high-quality raw materials required for manufacturing carbon brake discs can be another challenge. Carbon composites are produced using specialized fibers and resins, which may be subject to supply chain disruptions or price fluctuations. Limited access to these critical materials could impact production timelines and costs, potentially slowing down market growth. Additionally, any constraints in the raw material supply chain can hinder the ability of manufacturers to meet increasing demand for carbon brake discs in a timely and cost-effective manner.
Maintenance and Repair Complexity:
While carbon brake discs offer superior durability, their maintenance and repair processes are more complex compared to traditional metallic systems. Carbon brake discs require specialized knowledge and equipment for maintenance, which can lead to increased operational downtime and higher repair costs for airlines. This can be particularly challenging for operators in regions where skilled labor and advanced maintenance facilities are less accessible. Consequently, the need for specialized training and infrastructure to support carbon brake disc maintenance is a significant challenge.
Regulatory and Certification Challenges:
Another hurdle is the rigorous regulatory and certification processes that carbon brake discs must undergo to meet safety and performance standards in the aerospace industry. These extensive testing procedures and approvals can delay product entry into the market and increase development costs. Manufacturers must navigate complex regulatory environments, ensuring that their products meet both international and regional standards for safety and performance.
Market Opportunities:
The growing demand for fuel-efficient and environmentally friendly technologies presents significant opportunities in the aircraft carbon brake disc market. As airlines and military operators focus on reducing fuel consumption and minimizing their carbon footprint, the adoption of lightweight materials like carbon composites is increasingly prioritized. Carbon brake discs, which contribute to fuel savings and lower emissions, align with the industry's broader shift toward sustainability. This trend is expected to expand the adoption of carbon brake discs, especially in new-generation aircraft that are being developed with enhanced fuel efficiency and lower environmental impact as key design priorities. Moreover, the rising stringent environmental regulations are encouraging the transition to more sustainable materials, further boosting demand.
Another key opportunity lies in the expansion of the aviation sector in emerging markets, particularly in Asia-Pacific. Rapid economic growth and increasing air travel in countries like China, India, and other developing regions are driving demand for new aircraft and advanced aerospace technologies. As regional air traffic continues to rise, there will be an increasing need for advanced braking systems that offer enhanced performance, safety, and durability. This growth presents manufacturers with the opportunity to tap into a high-growth market, supplying carbon brake discs to both commercial and military aircraft producers in these regions. Additionally, as aerospace infrastructure develops in these regions, the demand for upgraded maintenance and repair services for carbon brake discs is also expected to grow, providing another avenue for market expansion. The shift toward domestic aircraft production in these regions could further drive demand for locally produced carbon brake discs.
Market Segmentation Analysis:
By Material Type
The aircraft carbon brake disc market can be segmented based on material type into carbon-carbon and carbon-ceramic brake discs. Carbon-carbon brake discs dominate the market due to their superior performance in high-temperature environments, making them ideal for commercial and military aircraft. These discs offer excellent durability, reduced weight, and enhanced braking efficiency. Carbon-ceramic brake discs, while less common, are gaining traction for their ability to deliver enhanced braking performance in certain high-performance aircraft, offering excellent wear resistance and thermal stability.
By Aircraft Type
The market is further segmented by aircraft type into commercial, military, and general aviation. Commercial aircraft hold the largest share, driven by the widespread adoption of carbon brake discs in large-scale passenger jets. Military aircraft also account for a significant portion of the market, as these aircraft require high-performance braking systems to withstand extreme operational conditions. General aviation is experiencing moderate growth as smaller aircraft are increasingly equipped with advanced braking solutions to enhance safety and performance.
By Fit Type
The aircraft carbon brake disc market is segmented into OEM (Original Equipment Manufacturer) and aftermarket fit types. The OEM segment holds the largest market share, driven by the ongoing production of new aircraft that require advanced braking systems. However, the aftermarket segment is experiencing significant growth, as airlines and military operators seek to replace or upgrade their existing braking systems with more durable and efficient carbon brake discs, enhancing the lifespan and performance of older fleets.
Segmentations:
By Material Type:
- Carbon-Composite
- Carbon-Carbon
By Aircraft Type:
- Military Aircrafts
- General Aviation
-
- Regional Jets
- Commercial Aircraft
- Wide Body Aircraft
- Narrow Body Aircraft
By Fit Type:
- Retro Fit
- First Fit
By Regions:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share in the aircraft carbon brake disc market, accounting for over 40% of the global market. This is primarily due to the strong presence of leading aircraft manufacturers such as Boeing and Lockheed Martin, along with a significant demand for advanced aerospace technologies. The region benefits from a well-established aerospace industry, supported by robust defense and commercial aviation sectors. Furthermore, the ongoing investments in research and development in the U.S. and Canada continue to drive innovation in braking systems, enhancing the adoption of carbon brake discs. The presence of large aircraft fleets operated by both commercial airlines and military forces further boosts the demand for these advanced braking solutions.
Europe
Europe holds a substantial share of the global aircraft carbon brake disc market, with a market share of more than 25%. Key players in the European aerospace industry, such as Airbus and Rolls-Royce, contribute to the region’s dominance. The demand for carbon brake discs in Europe is also supported by stringent regulatory standards for safety and performance in aviation, prompting the adoption of advanced materials like carbon composites. The region's focus on sustainability and reducing carbon emissions aligns with the growing preference for lightweight, fuel-efficient materials. Additionally, European military aircraft fleets, including those of NATO members, further enhance demand for high-performance braking systems.
Asia-Pacific
The Asia-Pacific region is experiencing rapid growth in the aircraft carbon brake disc market, with a market share of over 20%. Countries like China, India, and Japan are witnessing increasing investments in their aviation infrastructure, driving the demand for advanced aircraft components. The rise in air travel and the expansion of commercial aircraft fleets in this region are key factors fueling the growth of carbon brake disc adoption. Furthermore, the shift toward modern aircraft production in countries like China is creating significant opportunities for manufacturers to supply carbon brake discs. The expansion of defense budgets and increasing procurement of military aircraft in the region also contribute to market growth.
Rest of the World
The Rest of the World, including regions like the Middle East, Latin America, and Africa, holds the smallest market share, accounting for less than 15%. However, these regions are expected to show steady growth due to increasing air traffic, military modernization, and investments in aviation infrastructure. The demand for aircraft carbon brake discs in these regions is driven by expanding commercial fleets, particularly in the Middle East, and rising defense spending in countries like Brazil and South Africa.
Key Player Analysis:
- Safran S.A.
- Honeywell International Inc.
- Collins Aerospace
- UTC Aerospace Systems
- Meggitt PLC
- SGL Carbon
- Brembo S.p.A.
- ZF Friedrichshafen AG
- Parker Hannifin Corporation
- AAR Corp.
Competitive Analysis:
The aircraft carbon brake disc market is highly competitive, with key players focusing on technological innovation, cost-efficiency, and strategic partnerships. Leading companies such as Safran S.A., Honeywell International, and Collins Aerospace dominate the market by offering high-performance, durable carbon brake discs for both commercial and military aircraft. These players invest significantly in research and development to enhance product efficiency, durability, and sustainability, ensuring compliance with increasingly stringent safety and environmental regulations. For instance, Safran S.A. has developed the SepCarb®IV carbon brake, which offers a 30% reduction in brake usage and improved resistance to thermal and catalytic oxidation. Additionally, collaborations and mergers are becoming more prevalent as companies seek to strengthen their market position and expand their product offerings. New entrants are focusing on developing cost-effective solutions, while established players leverage their industry experience and manufacturing capabilities to maintain competitive advantages. With rising demand for advanced braking systems, companies are also exploring opportunities in emerging markets, particularly in the Asia-Pacific region, where aviation growth is accelerating.
Recent Developments:
- In April 2024, Safran Landing Systems launched a new generation of lightweight carbon brake discs, improving aircraft fuel efficiency and reducing CO2 emissions.
- In January 2024, Safran Landing Systems completed the acquisition of a leading carbon brake disc manufacturer, expanding its product portfolio and strengthening its market position in Europe.
- In February 2024, Honeywell Aerospace acquired a majority stake in a leading carbon brake disc manufacturer to enhance its product portfolio and technological capabilities.
- In January 2024, Collins Aerospace entered into a strategic partnership with a European aerospace firm to co-develop next-generation carbon brake technology.
- In August 2024, Collins Aerospace celebrated the groundbreaking of its expansion at the Spokane, Washington, carbon/carbon (C/C) brake production facility, adding 70,000 square feet to its manufacturing space.
Market Concentration & Characteristics:
The aircraft carbon brake disc market exhibits moderate concentration, with a few large players dominating the landscape. Companies such as Safran S.A., Honeywell International, and Collins Aerospace hold significant market shares due to their established brand presence, technological expertise, and extensive distribution networks. These key players focus on innovation, product differentiation, and strategic partnerships to maintain their competitive edge. While the market is predominantly driven by these major manufacturers, there is also room for smaller players and new entrants, especially those offering cost-effective or specialized solutions. The market characteristics include a high emphasis on research and development to meet evolving performance standards, safety regulations, and environmental requirements. Additionally, market participants are increasingly expanding their presence in emerging regions like Asia-Pacific, where demand for advanced aircraft components is growing rapidly, contributing to a dynamic and competitive market environment.
Report Coverage:
The research report offers an in-depth analysis based on Material Type, Aircraft Type, Fit Type and Regions. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for lightweight, fuel-efficient materials in the aviation industry will continue to drive the adoption of carbon brake discs.
- Technological advancements in manufacturing processes will make carbon brake discs more cost-effective, increasing their accessibility to a wider range of customers.
- Carbon brake discs will increasingly be integrated into next-generation aircraft models, focusing on performance, safety, and sustainability.
- Growing air traffic in emerging markets, particularly in Asia-Pacific, will create significant opportunities for the carbon brake disc market.
- As environmental regulations become more stringent, the aviation industry’s shift toward reducing carbon emissions will boost demand for carbon brake discs.
- Airlines and military operators will prioritize the adoption of durable, low-maintenance components, enhancing the market for carbon brake discs.
- Increased defense spending globally will contribute to the growing demand for advanced braking systems in military aircraft.
- The aftermarket segment will see growth as airlines seek to replace existing braking systems with carbon brake discs to extend the lifespan of older fleets.
- Regional players in emerging markets will increasingly enter the market, driven by rising local demand and improved aerospace infrastructure.
- The market will experience continued product innovations, with manufacturers focusing on enhancing braking performance, durability, and environmental sustainability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Aircraft Carbon Brake Disc Market?
What are the key factors driving the growth of the aircraft carbon brake disc market?
Which regions are expected to lead the aircraft carbon brake disc market?
How do carbon brake discs benefit modern aircraft?
Why is Asia-Pacific expected to see the highest growth in this market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Aircraft Carbon Brake Disc Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Aircraft Carbon Brake Disc Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,194.5 million → 2032: USD 2,194.61 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Aircraft Carbon Brake Disc Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Aircraft Carbon Brake Disc Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Aircraft Carbon Brake Disc Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Aircraft Carbon Brake Disc Market Drivers
- 3.3 Aircraft Carbon Brake Disc Market Restraints & Challenges
- 3.4 Aircraft Carbon Brake Disc Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Aircraft Carbon Brake Disc Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Aircraft Carbon Brake Disc Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Aircraft Carbon Brake Disc category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Aircraft Carbon Brake Disc Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Aircraft Carbon Brake Disc Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Aircraft Carbon Brake Disc market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Aircraft Carbon Brake Disc Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Aircraft Carbon Brake Disc Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Aircraft Carbon Brake Disc Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Aircraft Carbon Brake Disc (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Aircraft Carbon Brake Disc Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Aircraft Carbon Brake Disc Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Aircraft Carbon Brake Disc Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Aircraft Carbon Brake Disc Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Aircraft Carbon Brake Disc Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Aircraft Carbon Brake Disc Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Aircraft Carbon Brake Disc Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Aircraft Carbon Brake Disc Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Aircraft Carbon Brake Disc Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
